
 Superyacht Market | 2026-2036
Superyacht Market Size, Share, and Industry Trends Forecast 2026-2036
Superyacht Market Outlook
Market Context
IMO Tier III compliance is broadening the cost-of-entry calculus for new superyacht construction, forcing builders to integrate selective catalytic reduction or exhaust gas cleaning systems. Feadship leverages its Dutch heritage and custom-build expertise to command premium positioning in the 80-meter-plus segment. Lürssen anchors its competitive stance through in-house naval architecture and German engineering precision. Oceanco differentiates via silent-running hybrid platforms and advanced noise-vibration-harshness engineering.
Technical Definition and Segments
A superyacht denotes a privately crewed luxury vessel exceeding 24 meters in length, typically constructed from steel or aluminum hulls with composite superstructures, and designed for extended ocean cruising with onboard hospitality, propulsion, and safety systems managed to IMO SOLAS standards. Motor yachts dominate order books due to their superior volume-to-length ratios and helipad compatibility, while expedition yachts represent the fastest-growing product type as owners prioritize polar-class hull ratings and extended-range autonomy. Hybrid propulsion technology concentrates margin pools among early movers, though smart navigation systems are penetrating across all size tiers from 40 feet to over 100 feet.
Regulatory Frame and Outlook
The EU Green Deal and IMO MARPOL Annex VI together impose escalating carbon intensity indicators on superyacht operations, while the EU AI Act begins touching autonomous navigation certification pathways. Flag states including the Marshall Islands and Cayman Islands adapt their registries to these evolving standards, reshaping where vessels register and refit. Stakeholders must monitor whether emerging battery-electric harbor craft regulations will cascade upstream to superyacht shore-power and hotel-load architectures.
Market Dynamics
The superyacht market pivots on the collision between IMO Tier III emissions mandates and owner demand for extended-range autonomy, forcing builders to absorb selective catalytic reduction costs while preserving hull efficiency and interior volume ratios.
Growth Catalysts
- EU Green Deal marine extensions:The EU's escalating carbon intensity indicators for vessels over 500 gross tons are accelerating refit cycles in Mediterranean charter fleets, creating replacement demand for compliant propulsion architectures.
- Polar-class hull certification:Expedition yacht buyers are prioritizing ice-strengthened construction for Antarctic and Arctic cruising, expanding addressable geography for owners seeking differentiated itineraries.
- Silent-running hybrid platforms:Advanced noise-vibration-harshness engineering is enabling overnight anchorage in marine protected areas where conventional diesel operation faces restrictions.
Market Restraints
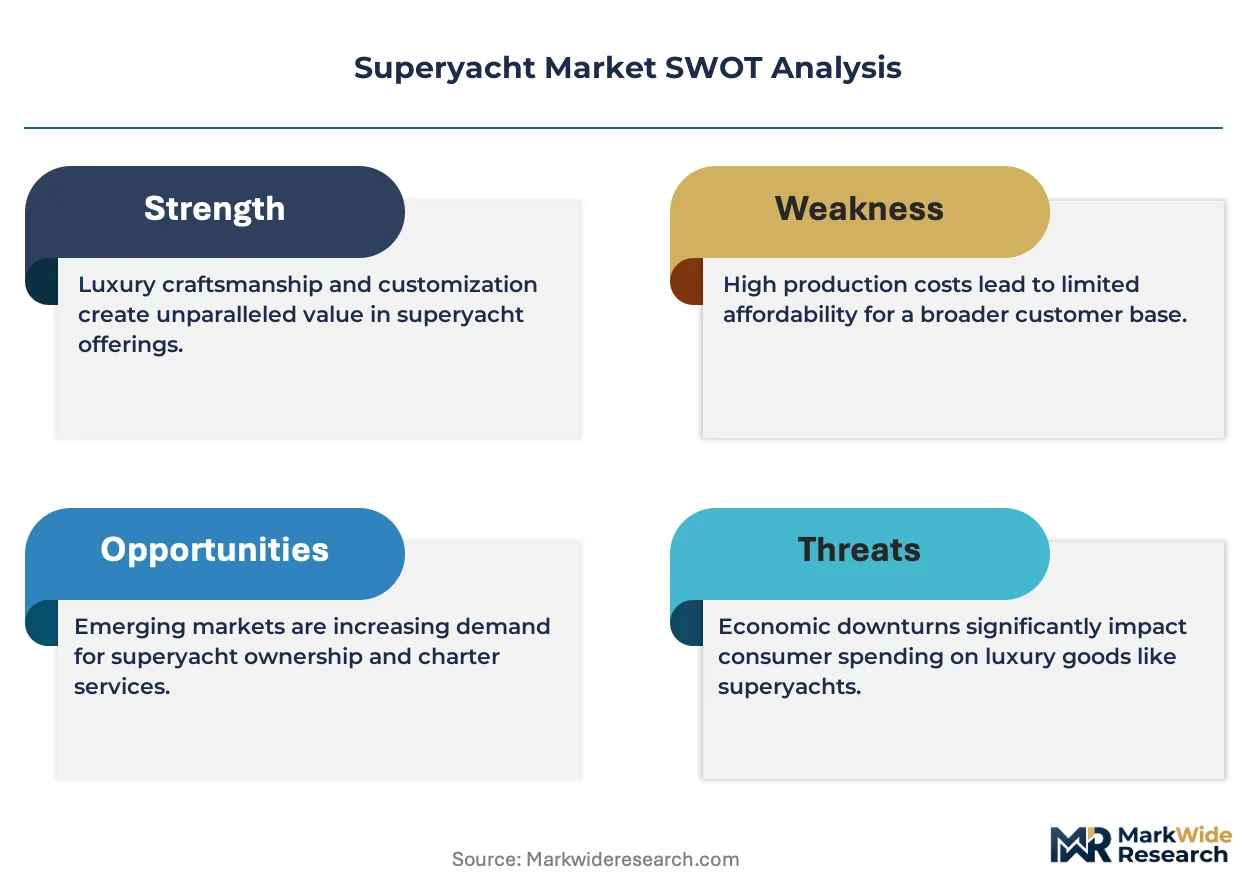
- Steel and aluminum price volatility:Hull material costs fluctuate with energy-intensive smelting economics, compressing builder margins on fixed-price contracts for custom 80-meter-plus projects.
- Netherlands-Germany supply concentration:Premium custom construction clusters in Northern Europe, creating geographic vulnerability to regional labor disputes and currency swings.
- IMO SOLAS compliance timelines:Safety equipment certification delays for novel propulsion systems extend delivery schedules and tie up capital in work-in-progress inventory.
Strategic Opportunities
- Saudi Arabia's Red Sea development:The kingdom's coastal tourism investments are creating new homeport infrastructure for superyacht owners seeking alternatives to saturated Mediterranean marinas.
- Shore-power hotel load architectures:Battery-electric harbor craft regulations in EU ports are cascading upstream, rewarding early adopters of high-capacity shore connection systems.
- AI-assisted route optimization:Convergence of autonomous navigation sensors and predictive weather routing is reducing fuel burn on transoceanic passages, appealing to cost-conscious charter operators.
Industry Challenges
- Marine electrical engineering talent scarcity:Hybrid propulsion complexity outpaces training pipeline output for specialists capable of integrating diesel-electric architectures with hotel load management.
- Flag state re-registration friction:Marshall Islands and Cayman Islands registry adaptations to evolving EU and IMO standards create documentation delays during ownership transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superyacht Market |
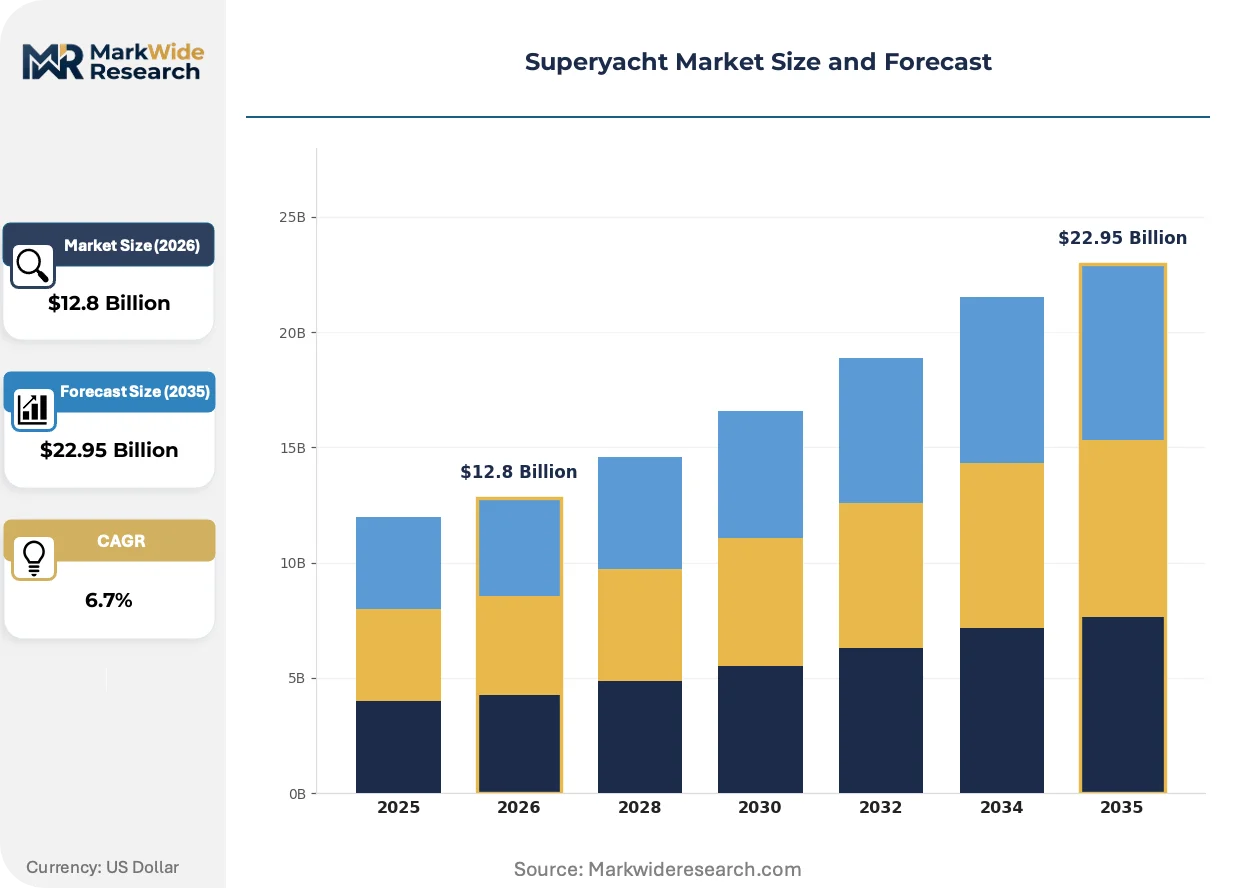
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Yachts, Sailing Yachts, Expedition Yachts, Catamarans End User: Private Owners, Charter Companies, Fleet Management, Corporate Clients Technology: Hybrid Propulsion, Solar Power, Smart Navigation Systems, Autonomous Vessels Size: 40-60 Feet, 61-80 Feet, 81-100 Feet, Over 100 Feet |
| Companies Covered | Feadship, Amels, Fincantieri Yachts, Royal Huisman, Heesen Yachts, Lürssen, Oceanco, Damen Yachting, Benetti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superyacht Market Strategic Shifts
Superyacht construction is fragmenting along propulsion technology lines, with diesel-electric hybrids, hydrogen fuel cells, and methanol-ready engines competing for capital allocation while owners demand proof of operational reliability before committing to novel architectures.
Containerized battery systems are modularizing energy storage on board, allowing owners to upgrade capacity without hull modifications. Charter operators in the Mediterranean corridor are specifying swappable battery configurations to meet variable itinerary demands. This approach is compressing refit timelines and shifting capital expenditure from new construction toward mid-life propulsion overhauls.
REACH chemical restrictions and EU MRV monitoring requirements are tightening material specifications for interior finishes and hull coatings. Builders sourcing composite superstructures must now document full substance inventories through the supply chain. Northern European yards are responding by consolidating supplier relationships to reduce compliance verification overhead.
Charter brokers are unbundling crewed yacht access from traditional fixed-week packages, responding to ultra-high-net-worth individuals seeking shorter, impulse-driven bookings. Digital platforms connecting owners directly with guests are displacing conventional brokerage commissions in Monaco and Antibes. This pattern is most pronounced among younger owners in Middle Eastern fleets who prioritize asset utilization rates over privacy exclusivity.
Superyacht Market Segmentation
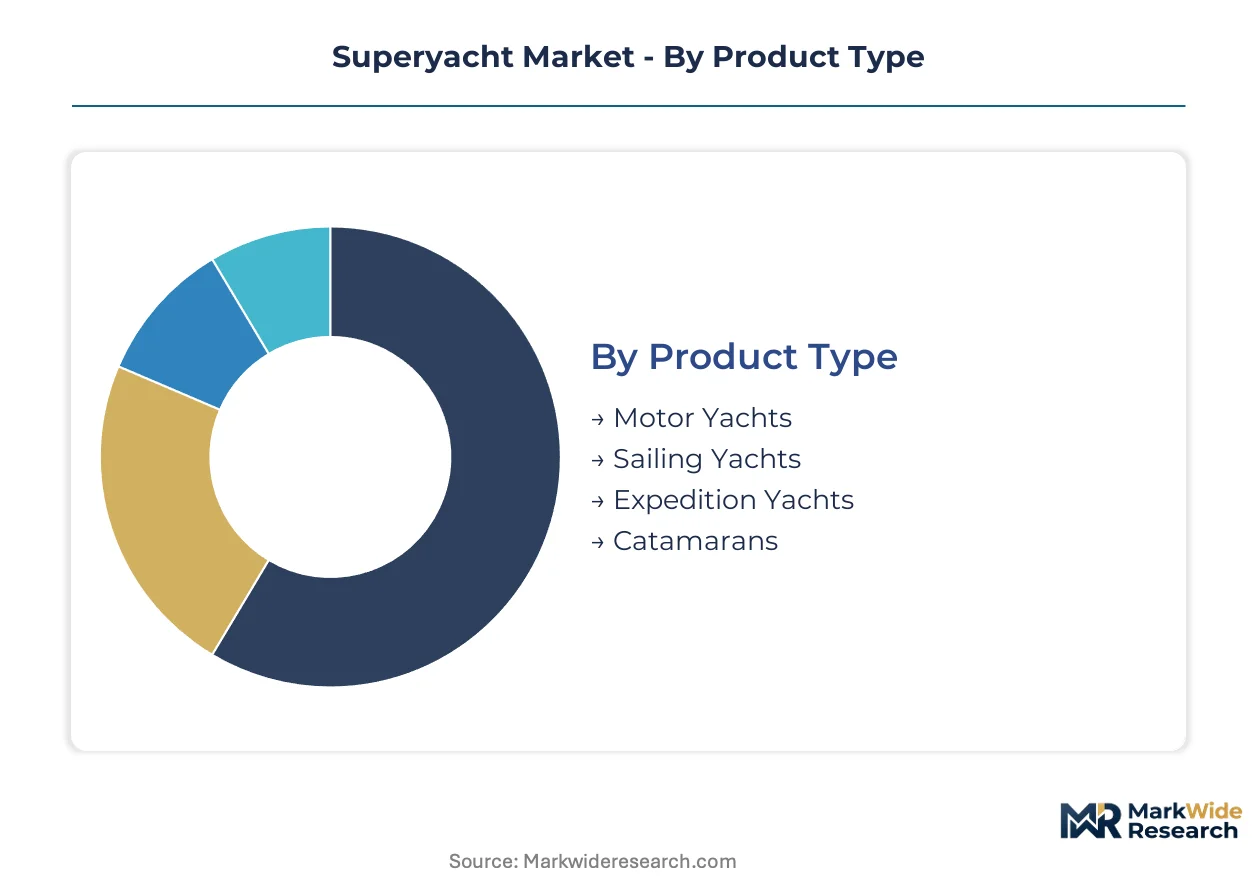
Superyacht segmentation reveals how propulsion technology, ownership structure, and vessel scale interact to determine margin profiles and regulatory exposure. Builders and operators calibrate portfolio strategy across these dimensions to capture value from IMO compliance timelines and charter demand patterns.
Product Type:
Motor yachts and sailing yachts function as standalone platforms with complete hospitality systems, while expedition yachts and catamarans embed specialized capabilities into hull architectures designed for specific cruising domains.
- Motor Yachts:Steel or aluminum hulls with composite superstructures deliver superior volume-to-length ratios and helipad compatibility. Demand concentrates among private owners in Monaco and Antibes seeking maximum interior space for extended Mediterranean cruising, though EU Green Deal emissions standards are extending refit cycles for pre-Tier III vessels.
- Expedition Yachts:Ice-strengthened hulls with polar-class certification enable Antarctic and Arctic itineraries. Charter companies in emerging Red Sea corridors are prioritizing these platforms for differentiated route offerings, with Saudi Arabia's coastal tourism investments creating new homeport infrastructure outside saturated Mediterranean marinas.
- Sailing Yachts:Wind-diesel hybrid rigs appeal to owners prioritizing fuel autonomy and silent propulsion in marine protected areas.
- Catamarans:Twin-hull configurations maximize deck space and stability for shallow-water exploration in Caribbean and Southeast Asian archipelagos.
Motor yachts lead volumes today; expedition yachts are gaining share fastest.
End User:
Cost tier differentiation separates capital-intensive private ownership from operational expenditure models where asset utilization rates drive procurement decisions.
- Private Owners:Ultra-high-net-worth individuals in the Middle East are expanding fleet acquisitions with emphasis on custom 80-meter-plus builds from Northern European yards. Feadship and Lürssen command premium positioning through Dutch heritage and German engineering precision respectively.
- Charter Companies:Mediterranean operators are unbundling fixed-week packages into shorter impulse-driven bookings via digital platforms. This pattern is most pronounced among younger Middle Eastern owners who prioritize utilization rates over privacy exclusivity.
- Fleet Management:Professional operators handle technical compliance and crewing for multiple-vessel portfolios, absorbing IMO SOLAS certification complexity.
- Corporate Clients:Hospitality and entertainment firms deploy vessels for client entertainment and executive retreat programming.
Private owners dominate capital deployment; charter companies are expanding most quickly.
Technology:
Maturity gradients separate proven diesel-electric architectures from emerging platforms where operational reliability remains unproven at superyacht scale.
- Hybrid Propulsion:Silent-running diesel-electric systems enable overnight anchorage in noise-restricted marine protected areas. Oceanco differentiates via advanced noise-vibration-harshness engineering, though marine electrical engineering talent scarcity constrains integration capacity across Northern European yards.
- Smart Navigation Systems:AI-assisted route optimization converges autonomous sensors with predictive weather routing, reducing fuel burn on transoceanic passages for cost-conscious charter operators in the Monaco-Antibes-Porto Cervo corridor.
- Solar Power:Deck-integrated photovoltaic arrays supplement hotel loads during daylight anchorage periods.
- Autonomous Vessels:Remote-operated and limited-crew concepts face EU AI Act certification pathway uncertainties for autonomous navigation.
Hybrid propulsion leads installed base expansion; smart navigation systems are climbing the fastest.
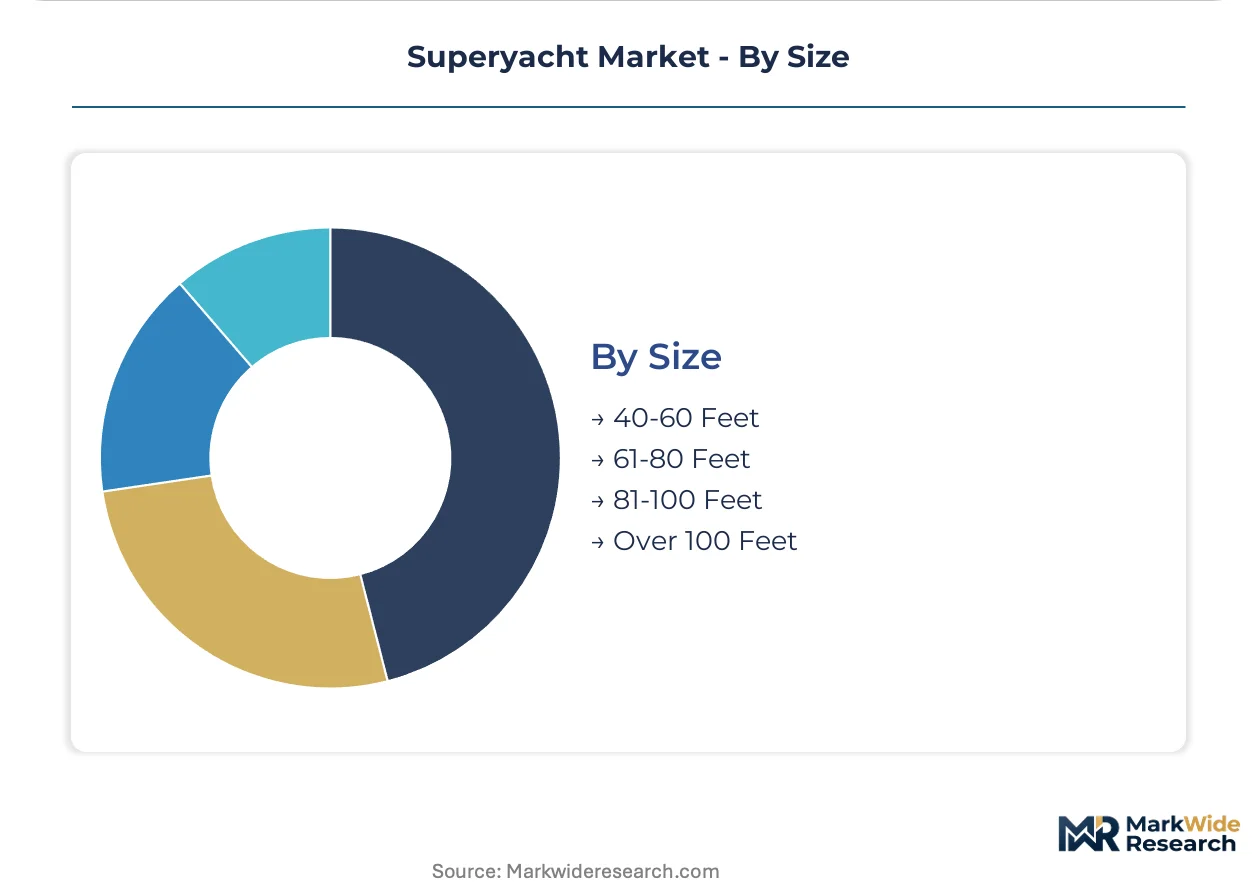
Size:
Volume thresholds determine regulatory jurisdiction, crewing requirements, and builder specialization concentration.
- Over 100 Feet:Custom construction from Netherlands and Germany supply clusters dominates this segment, with Feadship and Lürssen anchoring competitive positioning through in-house naval architecture. Steel and aluminum price volatility compresses margins on fixed-price contracts.
- 81-100 Feet:Semi-custom platforms balance personalization with production efficiencies, attracting private owners seeking IMO SOLAS compliance without full custom build timelines.
- 61-80 Feet:Production yacht builders compete on delivery speed and option packages for entry-level superyacht buyers.
- 40-60 Feet:High-volume manufacturing from Southern European and Turkish yards serves price-sensitive ownership transitions from recreational boating.
Over 100 feet commands revenue concentration; 81-100 feet shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval architects and marine engineers concentrate in Dutch and German shipbuilding clusters, anchoring superyacht construction expertise in Northern Europe while Mediterranean charter demand and Middle Eastern fleet expansion reshape ownership patterns worldwide.
Netherlands
Custom 80-meter-plus construction dominates Dutch output, with Feadship leveraging centuries of shipbuilding heritage for premium positioning. The country's national environmental regulator enforces EU Green Deal marine emissions standards that accelerate refit demand for pre-Tier III vessels. Amsterdam and Rotterdam harbor zones concentrate naval architecture firms supplying Northern European yards with propulsion integration expertise.
Germany
German yards capture orders from ultra-high-net-worth individuals prioritizing engineering precision and extended-range autonomy. Lürssen anchors competitive positioning through in-house naval architecture capabilities developed over decades. Hamburg and Bremen industrial zones host specialized suppliers of selective catalytic reduction systems for IMO Tier III compliance.
Italy
Production yacht builders in Italy serve entry-level superyacht buyers transitioning from recreational boating, with Benetti representing established Mediterranean construction heritage. The country's national maritime regulator adapts flag state documentation to evolving EU emissions monitoring requirements. Viareggio and Livorno clusters concentrate semi-custom platforms balancing personalization with delivery speed.
United Arab Emirates
Dubai and Abu Dhabi marinas attract Middle Eastern fleet owners expanding acquisitions beyond saturated Mediterranean corridors. The UAE's federal maritime authority coordinates with IMO standards while developing regional certification pathways for hybrid propulsion systems. Jebel Ali industrial zones support refit capacity for vessels transitioning between European and Asian cruising routes.
United States
American owners prioritize expedition yachts with polar-class hull ratings for Antarctic and Arctic itineraries, extending addressable geography beyond traditional cruising grounds. The US Coast Guard enforces SOLAS compliance timelines that extend delivery schedules for novel propulsion architectures. Florida's southeast coast clusters charter operators unbundling fixed-week packages into shorter impulse-driven bookings.
Superyacht Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the superyacht construction landscape, creating a tiered structure where custom builders command premium positioning and production yards compete on delivery speed. Northern European yards concentrate 80-meter-plus construction through consolidated supplier relationships. Three strategic archetypes dominate: heritage custom builders, semi-custom platform specialists, and production volume manufacturers. Competitive moves center on M&A for naval architecture capabilities and strategic partnerships for hybrid propulsion integration.
Among Dutch heritage builders, Feadship and Royal Huisman occupy positions exemplifying custom construction expertise, while German engineering precision finds representation in Lürssen's market presence. Italian production specialists including Benetti and Benetti anchor the Mediterranean semi-custom tier, with Oceanco representing silent-running hybrid platform differentiation. These named entities serve as archetype anchors rather than exhaustive market coverage, illustrating how geographic origin and organizational structure correlate with strategic positioning across the length-based segmentation.
| Leading Market Players |
|---|
| Feadship |
| Amels |
| Fincantieri Yachts |
| Royal Huisman |
| Heesen Yachts |
| Lürssen |
| Oceanco |
| Damen Yachting |
| Benetti |
| Others |
Value Chain & Pricing Dynamics
Captive in-house naval architecture at Dutch and German yards anchors both supply security and premium pricing power, insulating custom 80-meter-plus builders from commodity volatility while forcing production yards to compete on delivery speed rather than material cost arbitrage.
Pricing Analysis
Charter brokers are unbundling fixed-week packages into shorter impulse-driven bookings. Three-tier pricing structure across custom, semi-custom, and production tiers separates Feadship-level heritage positioning from Turkish volume manufacturers. Pricing pressure stems from steel and aluminum smelting cost volatility compressing margins on fixed-price contracts. Charter operators in Monaco and Antibes show highest price sensitivity; Middle Eastern private owners demonstrate lowest.
Supply Chain Analysis
Marine electrical engineering talent scarcity in Netherlands and Germany constrains hybrid propulsion integration capacity across Northern European yards. Supply concentrates in Dutch custom clusters, German precision-engineering corridors, and Italian semi-custom production zones. Builders draw from Norwegian steel mills, German SCR system suppliers, and Italian composite superstructure fabricators. Single-source vulnerability runs through selective catalytic reduction component vendors. Distribution runs through direct owner-yard contracts with charter operators as secondary demand channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The superyacht market functions as a stable compounder, with IMO Tier III compliance mandates creating predictable replacement cycles that sustain builder order books regardless of macroeconomic volatility.
For Market Incumbents: Deploy backward integration into naval architecture capabilities to defend against emerging Turkish production yards capturing entry-level buyers. Consolidate supplier relationships to reduce REACH chemical compliance verification overhead. Absorb marine electrical engineering talent scarcity through apprenticeship pipeline investments in Amsterdam and Rotterdam harbor zones. For New Entrants and Emerging Players: Begin with expedition yacht platforms for Saudi Arabia's Red Sea development corridor, where polar-class hull certification differentiates against saturated Mediterranean charter inventory. Target shore-power hotel load architecture retrofits as regulatory cascade from EU battery-electric harbor craft rules creates upgrade demand. Pursue direct digital platform relationships with younger Middle Eastern owners prioritizing utilization rates. For Investors and Strategic Acquirers: Roll-up economics work for semi-custom platform specialists because IMO SOLAS certification complexity creates barriers to organic scale-up. Five-to-ten-year viability hinges on hybrid propulsion reliability demonstration at superyacht scale. Target yards with in-house naval architecture and established Marshall Islands flag state relationships. Monitor EU AI Act autonomous navigation certification pathway clarity as inflection signal for smart navigation system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Integration | Oceanco's silent-running platforms demonstrate NVH engineering as margin driver in marine protected areas. |
| Polar-Class Hull Certification | Ice-strengthened construction expands addressable geography for Antarctic and Arctic itineraries. |
| Digital Charter Platform Launch | Direct owner-guest matching displaces conventional brokerage commissions in Monaco and Antibes. |
| Shore-Power Architecture Retrofit | High-capacity connection systems capture regulatory cascade from EU harbor craft electrification rules. |
| Naval Architecture Capability Acquisition | In-house design control insulates custom builders from production yard price competition. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with superyacht builders, charter operators, naval architects, marine electrical engineers, and flag state registry officials with secondary validation against IMO regulatory filings, EU MRV emissions databases, Lloyd's Register classification records, and customs trade data for steel and aluminum hull materials. Bottom-up vessel order book analysis and top-down macroeconomic demand modeling provided cross-check triangulation.
Segment-weighting across the projection horizon applied product type, propulsion technology, ownership structure, and vessel size dimensions to distribute volume and value estimates. CAGRs derived from historical delivery pattern analysis and forward-looking regulatory compliance timeline modeling. Forecast inputs incorporated EU Green Deal marine extension implementation schedules and Saudi coastal tourism infrastructure deployment.
Several conditions sit outside the modeled scope, including unannounced IMO MARPOL Annex VI amendments and unforeseen battery-electric propulsion breakthroughs at superyacht scale. Forecasts reflect assumptions about continued Northern European supply cluster dominance and stable Middle Eastern fleet expansion appetite. Practitioners should monitor Marshall Islands and Cayman Islands registry adaptation timelines for early signals of flag state re-registration friction impacts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Kayak Seats Market