
 Europe Personal Watercraft Market | 2026-2036
Europe Personal Watercraft Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Personal Watercraft Market Foresight
CE marking under the Recreational Craft Directive 2013/53/EU is redrawing competitive boundaries for personal watercraft sold in Europe. BRP Inc. leverages its Rotax engine manufacturing footprint to dominate high-performance sit-down models across Alpine lake markets. Yamaha Motor Co., Ltd. anchors its position through proprietary jet pump technology and dense dealer networks in France and Italy. Kawasaki Heavy Industries, Ltd. specializes in supercharged sport variants that command premium positioning among racing enthusiasts.
Personal watercraft are motorized vessels typically under four meters in length, powered by inboard jet pumps that draw water through an intake grate and expel it through a steerable nozzle for propulsion and directional control. Their primary commercial purpose centers on recreational surface navigation, patrol applications, and adventure tourism where maneuverability in shallow coastal zones exceeds conventional propeller-driven boats. Sit-down configurations capture the majority of volume, while electric technology represents the fastest-expanding segment as harbors in Barcelona and Nice impose emissions restrictions on two-stroke engines. Jet pump systems retain structural importance across all powertrain categories, forming the core differentiator in handling performance and shallow-water operational safety.
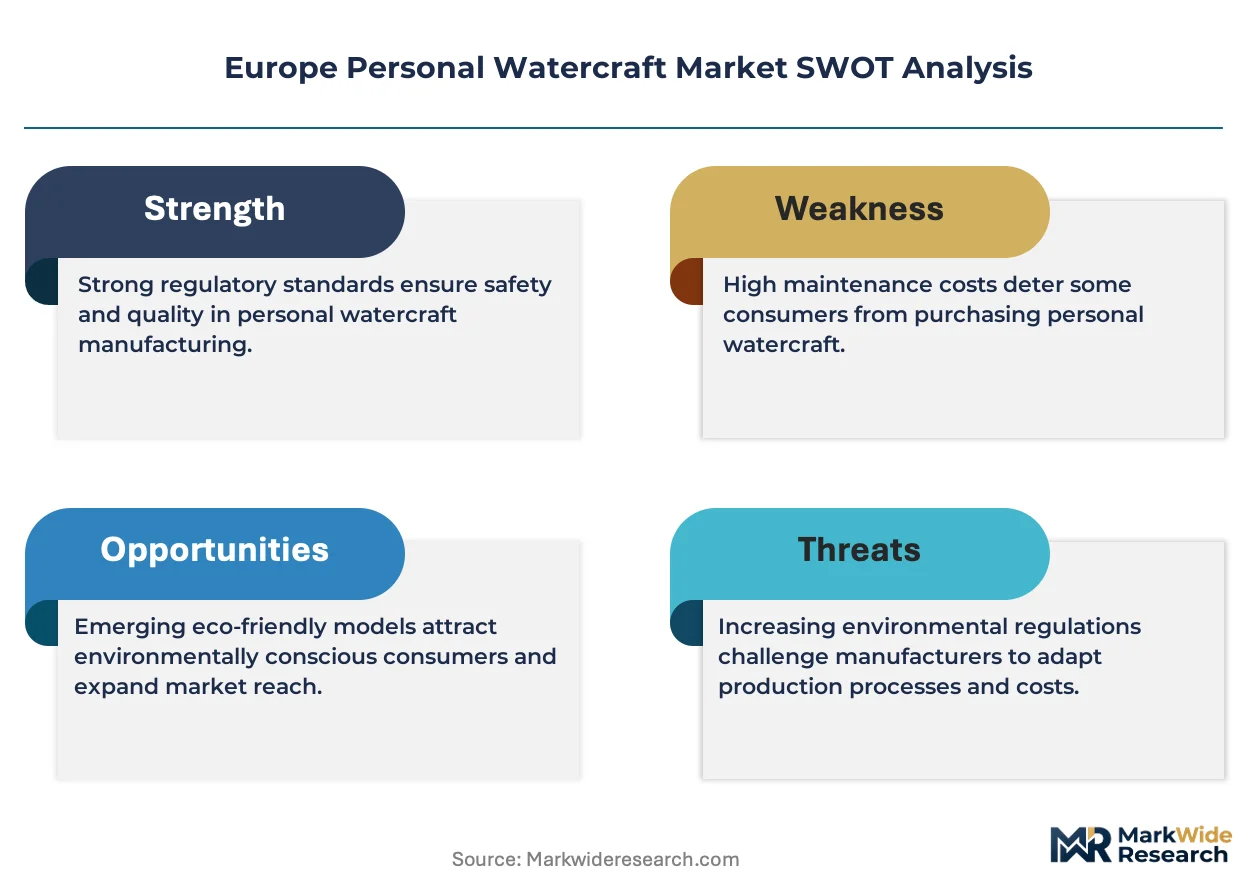
The European Maritime Safety Agency coordinates with national flag administrations to enforce noise and emission standards that determine product homologation timelines. REACH compliance for composite hull materials and the F-Gas Regulation on refrigerants in manufacturing processes add layers of technical obligation for importers and assemblers. ECHA substance restrictions on anti-fouling coatings are forcing reformulation of hull treatments used in saltwater environments. Stakeholders must track how the EU AI Act's emerging classification framework could affect autonomous navigation features entering rental and rescue segments.
Market Dynamics
Electric propulsion architecture is decomposing the established two-stroke dominance across European harbors as municipalities from Barcelona to Nice impose emissions-based access restrictions. This technology pivot demands simultaneous redesign of hull manufacturing processes and charging infrastructure placement.
Growth Catalysts
- EU Green Deal marine decarbonization mandates:National flag administrations accelerate R&D tax incentives for zero-emission propulsion development. Battery-electric variants gain preferential berth allocation in Mediterranean coastal zones.
- Adventure tourism fleet renewal:Rental operators in French and Italian lake districts replace aging two-stroke inventories with four-stroke and electric alternatives. Seasonal booking volumes support accelerated depreciation schedules.
- REACH-compliant composite formulations:Hull manufacturers reformulate resin systems to eliminate restricted substances. ECHA substance restrictions on anti-fouling coatings drive innovation in saltwater-compatible surface treatments.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack assembly depends on East Asian cell manufacturing. European pack integrators face extended lead times and currency exposure.
- CE marking homologation costs:Recreational Craft Directive 2013/53/EU compliance requires third-party notified body involvement. Small assemblers absorb disproportionate fixed certification expenses relative to production volumes.
- Seasonal demand compression:Alpine and Mediterranean usage patterns concentrate revenue into 16-20 week windows. Fleet operators struggle to amortize capital across full calendar years.
Strategic Opportunities
- Autonomous navigation integration:The EU AI Act's emerging classification framework creates regulatory clarity for rental and rescue applications. Sensor fusion and collision-avoidance algorithms enable unmanned patrol configurations.
- Spanish Atlantic coast underpenetration:Galician and Basque coastal zones lack dense rental infrastructure present in Mediterranean counterparts. Harbor development programs in Santander and A Coruña invite early-mover positioning.
- Subscription-based fleet access:Digital platforms displace traditional seasonal leases. Younger demographics in French urban centers prefer app-mediated hourly access over ownership.
Industry Challenges
- Marine electrician skill scarcity:High-voltage propulsion maintenance requires certifications absent from traditional marine mechanic training. Technical institutes in Italy and France lag curriculum updates.
- Jet pump corrosion in saltwater environments:Accelerated wear on impeller housings and wear rings demands more frequent service intervals. Coastal rental operators face elevated parts logistics complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Personal Watercraft Market |
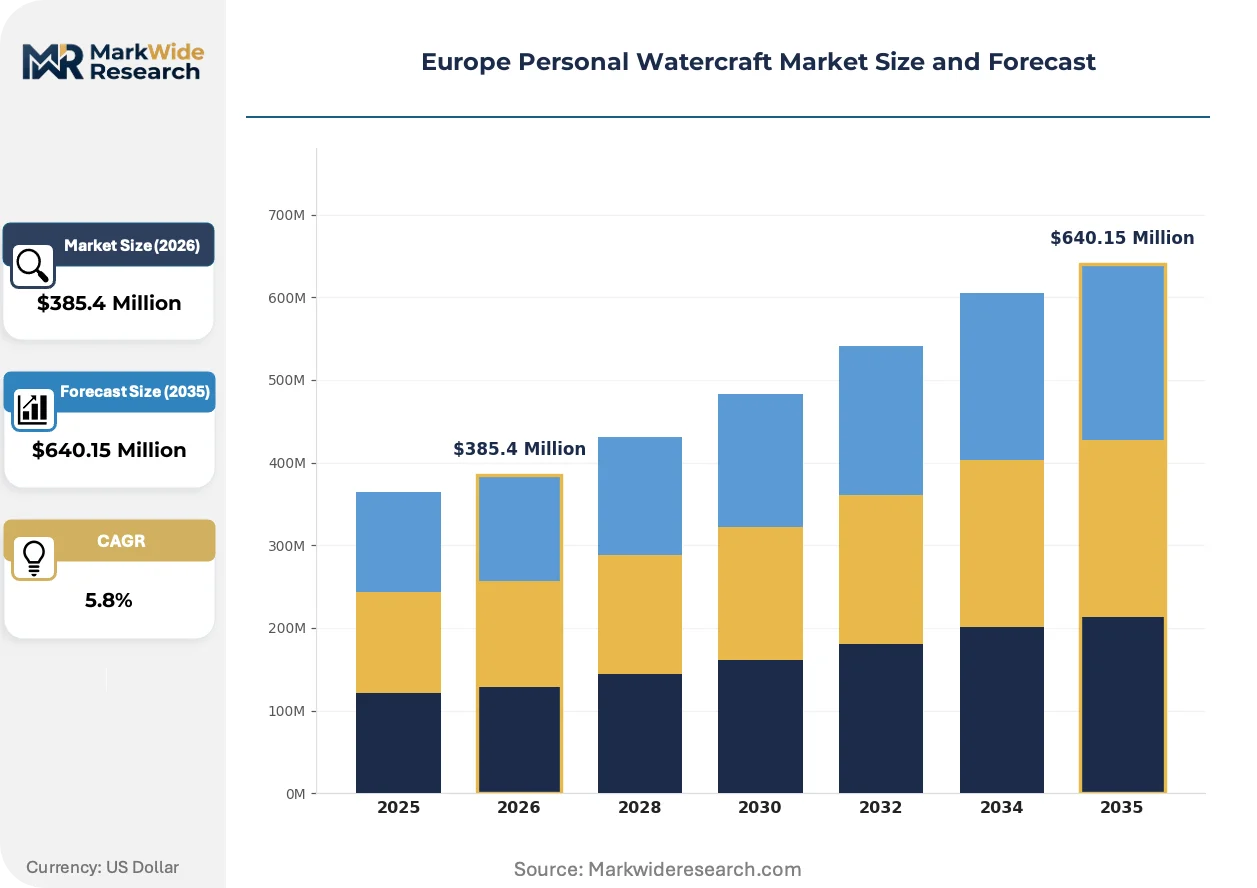
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up, Sit-down, Recreational, Sport, Luxury, Utility Technology: Two-Stroke Engine, Four-Stroke Engine, Electric, Hybrid, Jet Pump Application: Leisure, Racing, Rescue Operations, Rentals, Training, Adventure Tours End User: Marine Parks, Rental Services, Sports Enthusiasts, Rescue Teams, Tour Operators |
| Companies Covered | BRP Inc., Yamaha Motor Co., Ltd, Kawasaki Heavy Industries, Ltd., Belassi GmbH, Taiga Motors, Polaris Inc, Narke, Krash Industries, Brunswick Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Personal Watercraft Market Shifts & Advancements
Propulsion electrification is compressing established supply relationships while creating entry points for automotive battery suppliers and power electronics specialists. This convergence demands new competencies in thermal management and waterproofing that incumbent marine engine manufacturers must acquire or partner for.
Modular battery architectures are decomposing the traditional monolithic powertrain purchase model. Rental fleet operators in Lake Como and Lake Annecy adopt swappable pack systems to eliminate charging downtime during peak season. This operational model compresses capital requirements per usable hour and enables smaller operators to compete with vertically integrated chains.
CE marking enforcement under the Recreational Craft Directive is tightening noise and emission homologation timelines. The European Maritime Safety Agency coordinates with notified bodies to harmonize testing protocols across member states. Manufacturers targeting multiple national markets face consolidated compliance costs but reduced duplication.
Digital-first booking platforms are fragmenting traditional dealer-rental relationships. Mediterranean coastal resorts see direct-to-consumer reservation systems capture share from marina-based brokers. Spanish and Italian millennials demonstrate strongest preference for transparent pricing and real-time availability verification.
Europe Personal Watercraft Market Segmentation
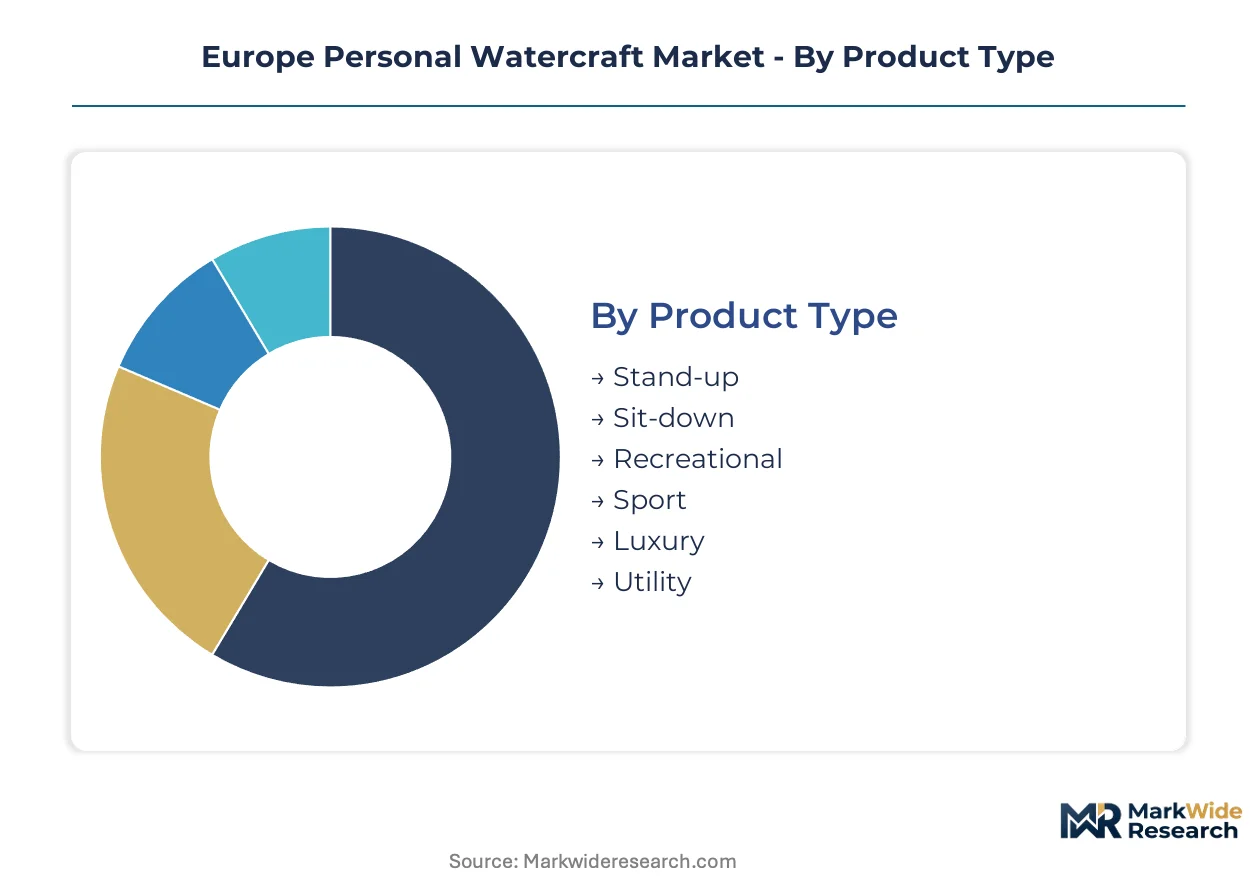
Segmentation in the European personal watercraft market reveals how regulatory pressure and usage patterns split demand across distinct technical and commercial configurations. Each category exposes different vulnerability to emissions restrictions, seasonal revenue compression, and fleet electrification timelines.
Product Type:
Domestic lake markets in France and Italy favor sit-down comfort and stability, while Mediterranean rental operators mix configurations to match tourist skill levels and harbor access rules.
- Sit-down:Enclosed hull designs with saddle seating dominate Alpine lake recreation and family-oriented coastal rentals. French operators in Lake Annecy and Lake Bourget prioritize these models for their lower training burden and reduced liability exposure.
- Stand-up:Compact, rider-active platforms with handlebar steering demand greater physical engagement and skill acquisition. Italian racing clubs and specialized training centers in Sardinia concentrate orders for competitive and instructional use.
- Recreational:Entry-level configurations balance affordability with essential safety features for casual weekend users.
- Sport:Performance-tuned hulls with enhanced acceleration profiles attract enthusiast buyers in Spain's Balearic Islands.
- Luxury:Premium finishes, integrated audio systems, and extended-range fuel capacity target high-net-worth individual ownership in Monaco and Cannes.
- Utility:Modified platforms with cargo racks and towing points serve harbor patrol and light commercial duties in Portuguese marina operations.
Sit-down configurations command the established base. The steepest expansion runs through electric-adapted utility variants for municipal harbor services.
Technology:
Cost tiers separate established internal combustion from emerging electric architectures, with hybrid systems occupying a transitional price band for operators hedging against charging infrastructure gaps.
- Electric:Battery-electric propulsion with submerged motor pods and regenerative coasting capability. Barcelona and Nice harbor authorities now mandate zero-emission access for new rental licenses, compressing adoption timelines for Mediterranean fleet operators.
- Four-Stroke Engine:Fuel-injected, multi-cylinder powerplants meeting EU Stage V emission standards. Alpine lake districts in Switzerland and Austria require these or cleaner alternatives, phasing out legacy two-stroke inventories through permit renewal conditions.
- Two-Stroke Engine:Lightweight, carbureted designs with higher specific power output but elevated hydrocarbon emissions.
- Hybrid:Parallel electric-combustion systems allowing silent harbor maneuvering with extended range capability.
- Jet Pump:The universal propulsion mechanism across all powertrain categories, with impeller and nozzle designs adapted to each energy source.
Four-stroke architectures retain the installed fleet majority. Electric systems gain share fastest where municipal access restrictions bite deepest.
Application:
Volume concentrates in seasonal leisure and rental segments, while rescue and training applications demand specialized certification and equipment durability.
- Leisure:Private ownership for weekend recreation on inland waterways and protected coastal zones. German buyers in Bavaria and Baden-Württemberg favor this segment for lake access adjacent to urban centers.
- Rentals:High-utilization fleet operations with standardized maintenance protocols and insurance frameworks. Croatian coastal resorts from Split to Dubrovnik anchor Mediterranean rental density, with operators replacing two-stroke units ahead of EU Green Deal enforcement.
- Racing:Closed-course competition with modified hulls and unrestricted power output.
- Rescue Operations:Configured for rapid deployment, patient retrieval, and all-weather reliability.
- Training:Dual-control platforms with instructor override capability for certification schools.
- Adventure Tours:Guided group experiences requiring reliability and passenger capacity for extended coastal routes.
Rental applications anchor current volume. Adventure tours climb fastest as experience-based tourism expands along Atlantic and Mediterranean coastlines.
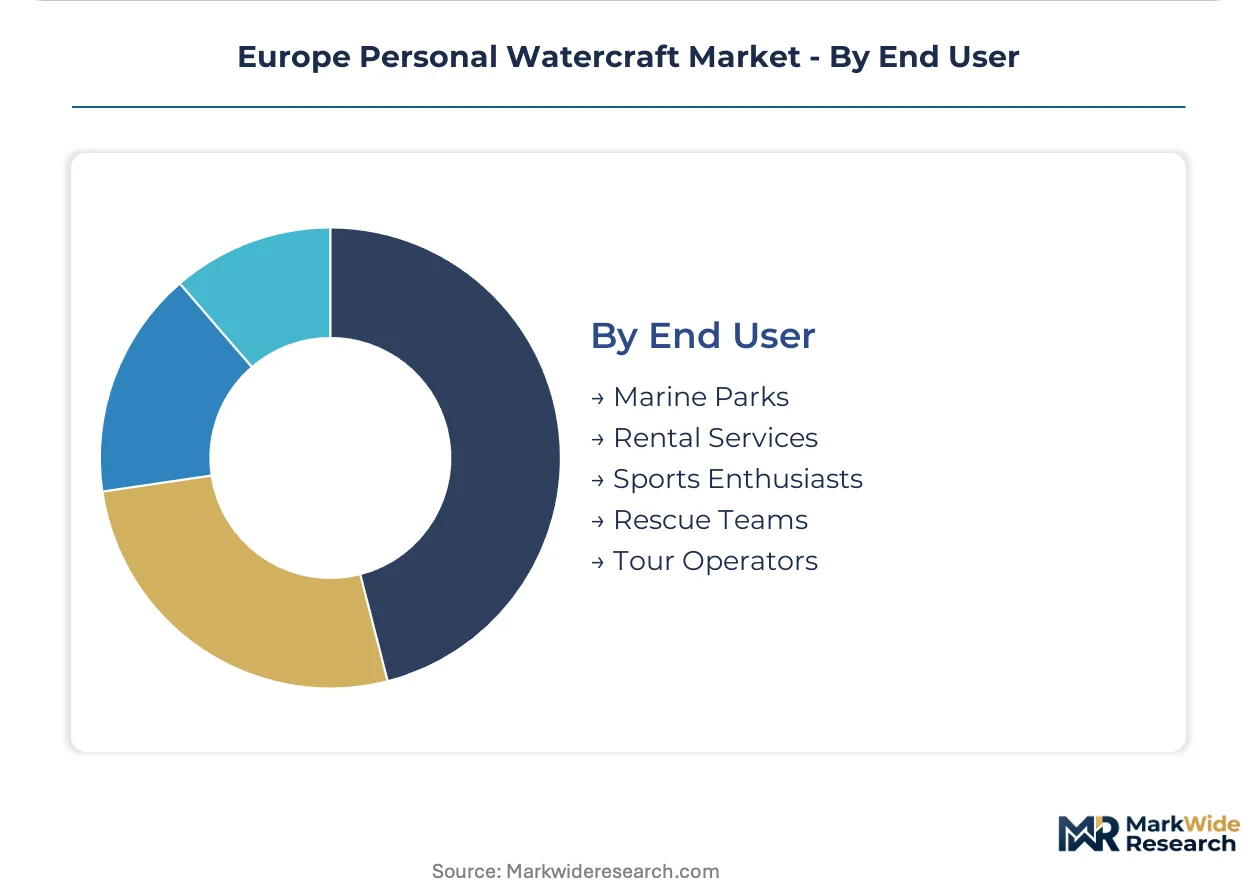
End User:
Customer type determines procurement rhythm, with rental services and marine parks running predictable replacement cycles while sports enthusiasts and rescue teams trigger episodic demand spikes.
- Rental Services:Fleet operators with centralized procurement, standardized training programs, and direct manufacturer relationships. Italian lake district cooperatives and Spanish coastal chains dominate order flow through volume purchasing agreements.
- Sports Enthusiasts:Individual buyers with high specification sensitivity and brand loyalty. French and British performance-oriented consumers drive premium sport and luxury segment orders through specialized dealers.
- Marine Parks:Regulated entertainment venues with safety certification requirements and capacity constraints.
- Rescue Teams:Government and volunteer organizations with mission-specific equipment standards.
- Tour Operators:Small businesses bundling watercraft access with guided experiences and hospitality services.
Rental services command the established base. Sports enthusiasts deliver the steepest expansion as electrified performance models penetrate enthusiast communities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rental services and private enthusiasts dominate procurement across European waterways. Fleet operators concentrate in Mediterranean coastal zones and Alpine lake districts. National regulators impose divergent emissions timelines that reshape regional demand patterns.
France
Lake Annecy and Lake Bourget operators drive sit-down configuration demand for family recreation. The EU Green Deal accelerates harbor access restrictions in Nice and Cannes, pushing rental fleets toward electric alternatives. Provence-Alpes-Côte d'Azur harbors now mandate zero-emission permits for new commercial licenses.
Italy
Adventure tourism operators along Lake Como and Sardinia's coastlines expand guided tour capacities. REACH compliance requirements force hull manufacturers in Lombardy to reformulate resin systems. Venetian lagoon patrol services test electric utility platforms for municipal harbor maintenance.
Spain
Barcelona harbor authorities enforce emissions-based access tiers that exclude two-stroke engines from peak season operations. Galician and Basque coastal zones remain underpenetrated by rental infrastructure relative to Mediterranean counterparts. Santander harbor development programs invite early-mover fleet positioning.
Germany
Bavarian lake districts near Munich sustain private ownership demand for weekend recreation. The F-Gas Regulation imposes refrigerant constraints on manufacturing processes at assembly facilities. Baden-Württemberg technical institutes lag in marine electrician curriculum updates for high-voltage propulsion maintenance.
Croatia
Split to Dubrovnik coastal resorts anchor Mediterranean rental density with standardized fleet operations. CE marking homologation under the Recreational Craft Directive compresses product entry timelines for importers. Adriatic harbor operators replace aging two-stroke inventories ahead of EU Green Deal enforcement deadlines.
Europe Personal Watercraft Market Competitive Landscape
Player mix skews toward diversified powersports conglomerates with engine manufacturing footprints. Market structure concentrates around three to five integrated manufacturers controlling distribution networks and proprietary propulsion technology. Strategic archetypes span vertically integrated engine specialists, automotive-electronics entrants, and boutique performance fabricators. Competitive moves center on electric powertrain partnerships and modular battery architecture licensing.
Within the diversified powersports tier, BRP Inc. and Yamaha Motor Co., Ltd. occupy positions reflecting established marine engine competencies and dense dealer networks. Kawasaki Heavy Industries, Ltd. sits within the performance-specialist archetype, commanding premium positioning among enthusiast segments. Taiga Motors represents the automotive-electronics entrant pattern, leveraging power electronics expertise from adjacent mobility sectors. Belassi GmbH exemplifies the European boutique fabricator model with focused production scale.
| Leading Market Players |
|---|
| BRP Inc. |
| Yamaha Motor Co., Ltd |
| Kawasaki Heavy Industries, Ltd. |
| Belassi GmbH |
| Taiga Motors |
| Polaris Inc |
| Narke |
| Krash Industries |
| Brunswick Corporation |
| Others |
Supply & Pricing Matrix
Rotax engine manufacturing scale in Austria and Yamaha's jet pump production in Japan establish volume thresholds that compress unit economics for smaller assemblers. These scale advantages propagate through CE marking homologation cost absorption and bulk procurement of REACH-compliant composite resins, setting price floors that marginal players struggle to breach.
Pricing Analysis
Cost-plus contracts with lithium-ion cell suppliers index battery pack pricing to nickel and cobalt commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates supercharged sport variants from rental-grade four-stroke models and entry-level electric platforms. Cost compression in economy tiers intensifies because Chinese cell manufacturers dominate cathode supply. Rental services exhibit highest price sensitivity due to seasonal utilization constraints, while luxury buyers in Monaco and Cannes demonstrate lowest elasticity.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell manufacturing, while Japan and Austria concentrate precision engine and jet pump production. European pack integrators draw from East Asian cell supply, with hull lamination resting on Italian and French composite formulators. Single-source vulnerability concentrates in high-nickel cathode chemistry. Distribution runs through manufacturer-owned dealer networks in France and Italy, supplemented by direct fleet procurement agreements with Mediterranean rental operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal watercraft markets increasingly reward service-attach revenue streams, with subscription-based fleet access platforms and modular battery swap networks expanding faster than hardware unit sales. Recurring maintenance contracts for high-voltage propulsion systems represent the fastest-growing profit layer.
For Market Incumbents: Fortify dealer network density in French and Italian lake districts against digital platform disintermediation. Deepen backward integration into electric powertrain assembly to capture margin from automotive-electronics entrants. Prioritize CE marking pre-certification for autonomous navigation features ahead of EU AI Act enforcement timelines. For New Entrants and Emerging Players: Differentiate on swappable battery architecture for rental operators in Croatian and Spanish coastal zones. Galician and Basque harbors offer the most penetrable geography given underdeveloped rental infrastructure. Pursue direct fleet procurement relationships with municipal harbor authorities seeking electric utility platforms for patrol applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rental fleet operators with subscription platform integration and maintenance contract backlogs. Long-term viability favors targets with established CE marking pathways and charging infrastructure partnerships. Monitor EU Green Deal enforcement acceleration in Mediterranean harbors as the primary inflection signal for electric adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Partnership | BRP and Yamaha battery supply agreements with automotive cell manufacturers compress development timelines for zero-emission models. |
| Modular Battery Licensing | Taiga Motors' swappable pack architecture enables smaller rental operators to compete with vertically integrated chains on capital efficiency. |
| Autonomous Navigation Certification | EU AI Act compliance investment creates first-mover positioning in unmanned harbor patrol and rescue segments. |
| Harbor Charging Infrastructure | Partnerships with Barcelona and Nice port authorities secure preferential berth allocation for electric fleet operators. |
| REACH-Compliant Composite Reformulation | Italian hull manufacturers' resin system innovation eliminates restricted substances ahead of ECHA enforcement deadlines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU customs trade data, Recreational Craft Directive homologation records, and ECHA substance restriction filings. Primary interviews engaged fleet procurement managers at Mediterranean rental operators, marine service technicians in French lake districts, and powertrain engineers at Austrian engine manufacturing facilities. Secondary validation incorporated European Maritime Safety Agency noise standard protocols, F-Gas Regulation compliance disclosures, and harbor authority emissions access tier documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segmentation dimensions modeled span product configuration, propulsion architecture, application type, and end-user procurement pattern across the projection horizon. CAGRs derive from fitted growth curves applied to electric adoption S-cycles and replacement demand schedules for aging two-stroke inventories. Industry-specific forecast inputs include EU Green Deal enforcement timelines for harbor access restrictions and seasonal utilization rates for Alpine and Mediterranean operators.
Material uncertainties — lithium-ion supply chain disruptions, CE marking homologation delays, and EU AI Act classification revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding battery cost decline trajectories and charging infrastructure deployment rates. Recalibration cycles align with material shifts in EU marine decarbonization mandates and ECHA substance restriction updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Kayak Seats Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Electric Baby Car Market