
 Recreational Vehicle Parks and Campgrounds Market | 2026-2036
Recreational Vehicle Parks and Campgrounds Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Vehicle Parks and Campgrounds Market Insights
Membership-based reservation platforms is realigning how inventory gets monetized across the campground sector. Kampgrounds of America leverages its franchise network to sustain national coverage density. Equity LifeStyle Properties anchors its portfolio in destination-adjacent locations with extended-stay revenue models. Sun Communities competes through integrated RV sales and site rental bundling.
Recreational vehicle parks and campgrounds constitute land-based hospitality infrastructure designed for temporary vehicle-mounted or tent-based lodging, typically incorporating utility hookups for electrical (30-50 amp), water, and sewage connections alongside communal amenities. The primary commercial purpose centers on monetizing outdoor recreation access through nightly or seasonal site fees. Full-service campgrounds command the dominant revenue share due to utility infrastructure requirements and higher per-night pricing, while RV resorts capture concentrated margin pools from extended-stay snowbird demographics. Family travelers represent the largest customer type by volume, though retiree segments generate superior length-of-stay economics.
EPA Clean Water Act provisions govern wastewater discharge from centralized campground facilities, while ADA Title III mandates shape site accessibility design standards across public and private properties. State-level environmental review processes in California and Colorado add permitting layers for new capacity expansion. Stakeholders must monitor evolving accessibility compliance thresholds and utility infrastructure resilience requirements as climate variability intensifies operational risk profiles.
Market Dynamics
Membership-based reservation platforms are restructuring inventory monetization across the campground sector, compressing booking windows and shifting revenue recognition patterns for facility operators.
Growth Catalysts
- ADA Title III accessibility mandates:Federal accessibility standards are compelling facility upgrades that expand addressable customer bases and extend average guest lifecycles.
- Snowbird seasonal migration:Retiree demographics from northern states are establishing predictable winter occupancy patterns in Arizona and Florida.
- Smart utility metering:Electrical submetering technology is enabling consumption-based pricing models that improve margin capture on high-amp RV connections.
Market Restraints
- EPA wastewater discharge compliance:Clean Water Act provisions impose capital-intensive treatment infrastructure requirements on facilities near protected watersheds.
- Land scarcity in destination corridors:Competition for developable parcels along coastal California and mountain resort zones limits greenfield expansion.
- Seasonal revenue volatility:Weather-dependent occupancy patterns in northern-tier states compress annual yield per available site.
Strategic Opportunities
- Glamping infrastructure retrofit:Fixed-structure luxury tent platforms command premium nightly rates from experience-seeking millennials.
- Electric vehicle charging integration:Level 2 and DC fast charging installations attract EV-towing RV segments underserved by traditional fuel stations.
- Extended-stay workforce housing:Remote worker demographics are converting weekly site rentals into monthly corporate housing alternatives in Colorado and Utah.
Industry Challenges
- Skilled maintenance technician shortage:Electrical, plumbing, and wastewater system repair expertise is concentrating in urban labor markets distant from rural campground locations.
- Legacy reservation system integration:Proprietary property management platforms resist API connectivity with third-party distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Vehicle Parks and Campgrounds Market |
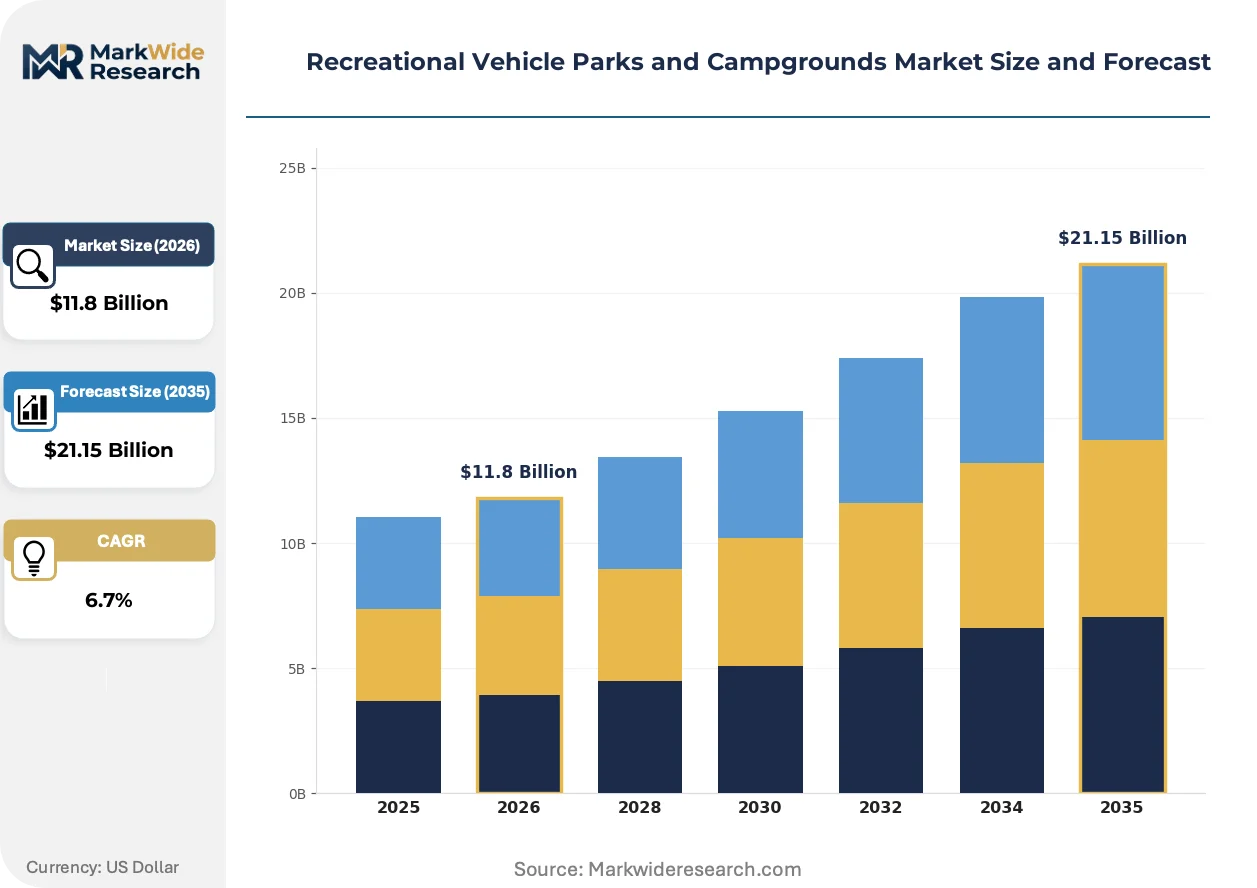
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Campgrounds, Primitive Campgrounds, RV Resorts, Tent-Only Sites Customer Type: Family Travelers, Adventurers, Retirees, Tourists Facility Type: Public Parks, Private Campgrounds, Luxury Campgrounds, State Parks Activity Type: Fishing, Hiking, Boating, Sightseeing |
| Companies Covered | Kampgrounds of America, Equity LifeStyle Properties, Sun Communities, Northgate Resorts, Thousand Trails, Blue Water Development, RVC Outdoor Destinations, Good Sam, Yogi Bear's Jellystone Park Camp-Resorts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Vehicle Parks and Campgrounds Market Trends and Innovations
Digital infrastructure and sustainability mandates are reconfiguring capital deployment priorities across the campground sector, altering how operators compete for guest segments.
Internet-of-Things sensor networks are converging with campground operations management, enabling predictive maintenance of septic systems and automated irrigation controls. Destination resort operators in California and Arizona are deploying these systems fastest, reducing utility waste and labor dispatch costs while compressing incident response windows.
EPA effluent limitation guidelines are tightening discharge standards for centralized wastewater facilities, forcing infrastructure upgrades or operational restructuring. Properties near sensitive water bodies face the steepest compliance timelines, with Colorado and Florida operators accelerating treatment plant investments ahead of enforcement phase-ins.
Subscription-based access models are displacing transactional nightly bookings among frequent travelers. Kampgrounds of America and regional cooperatives are capturing guest loyalty through annual membership fees, converting price-sensitive families into recurring revenue streams concentrated in the western United States.
Recreational Vehicle Parks and Campgrounds Market Segmentation
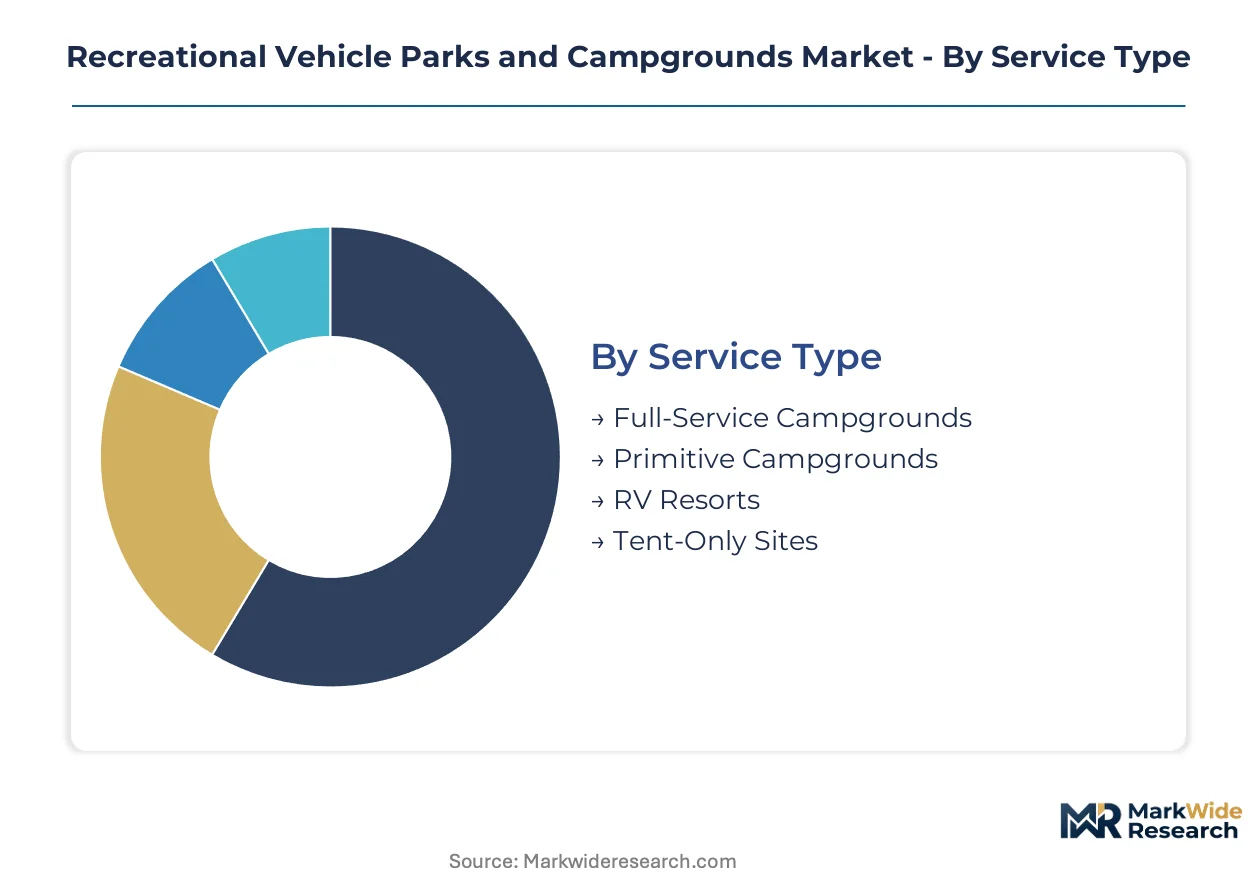
Segmentation in recreational vehicle parks and campgrounds reveals divergent capital intensity and margin profiles across service tiers. Facility operators calibrate infrastructure investment against guest duration and amenity expectations, creating distinct competitive arenas within the same geographic markets.
Service Type:
Full-service infrastructure commands premium positioning through utility density, while primitive offerings compete on access and price.
- Full-Service Campgrounds:Sites deliver 30-50 amp electrical, potable water, and sewage hookups alongside centralized bathhouses and Wi-Fi infrastructure. Demand concentrates in Arizona and Florida where snowbird demographics establish extended-stay patterns requiring reliable utility continuity. EPA wastewater discharge standards elevate capital barriers for new entrants near protected watersheds.
- Primitive Campgrounds:Undeveloped parcels provide vehicle access without utility connections, targeting self-contained RVs and tent campers. Western public land corridors in Colorado and Utah sustain occupancy through proximity to trailheads and dispersed recreation access. ADA Title III pathway mandates are forcing accessibility retrofits on legacy facilities.
- RV Resorts:Premium amenities include pools, clubhouses, and organized activities alongside full utility packages.
- Tent-Only Sites:Restricted-access parcels exclude vehicles entirely, preserving natural terrain for backpacking demographics.
Today's leader: Full-Service Campgrounds. Tomorrow's challenger: RV Resorts.
Customer Type:
Duration economics separate volume-driven family segments from retiree yield optimization.
- Family Travelers:Multi-generational groups drive peak-season occupancy with 2-4 night stays concentrated around school holiday windows. Western United States destinations in California and Colorado capture this flow through proximity to national parks and adventure infrastructure. Membership platform adoption is highest among this price-sensitive cohort.
- Retirees:Extended-stay snowbirds generate superior per-site annual revenue through 3-6 month winter migrations. Arizona and Florida facilities optimize for this demographic with social programming and healthcare access partnerships. Smart utility metering enables consumption-based pricing that improves margin capture on high-amp connections.
- Adventurers:Activity-focused travelers prioritize trail access over amenity density.
- Tourists:Transient guests en route to destination attractions fill shoulder-season capacity gaps.
Family Travelers anchor current volume. Retirees are climbing the fastest in revenue contribution per available site.
Facility Type:
Ownership structure determines regulatory exposure and pricing autonomy.
- Private Campgrounds:Commercial operators control rate setting and amenity investment, enabling rapid response to demand shifts. California and Colorado markets show highest private penetration where land scarcity justifies premium positioning. State environmental review processes add permitting friction for capacity expansion.
- Public Parks:Federal and municipal ownership limits pricing flexibility but secures location monopolies near iconic destinations.
- Luxury Campgrounds:Glamping infrastructure commands nightly rates through fixed-structure tent platforms and concierge services.
- State Parks:Recreation-focused public ownership balances access mandates with cost-recovery requirements.
Private Campgrounds dominate margin optimization. Luxury Campgrounds are gaining share fastest in experience-seeking millennial segments.
Activity Type:
Experience anchoring shapes facility design and seasonal demand curves.
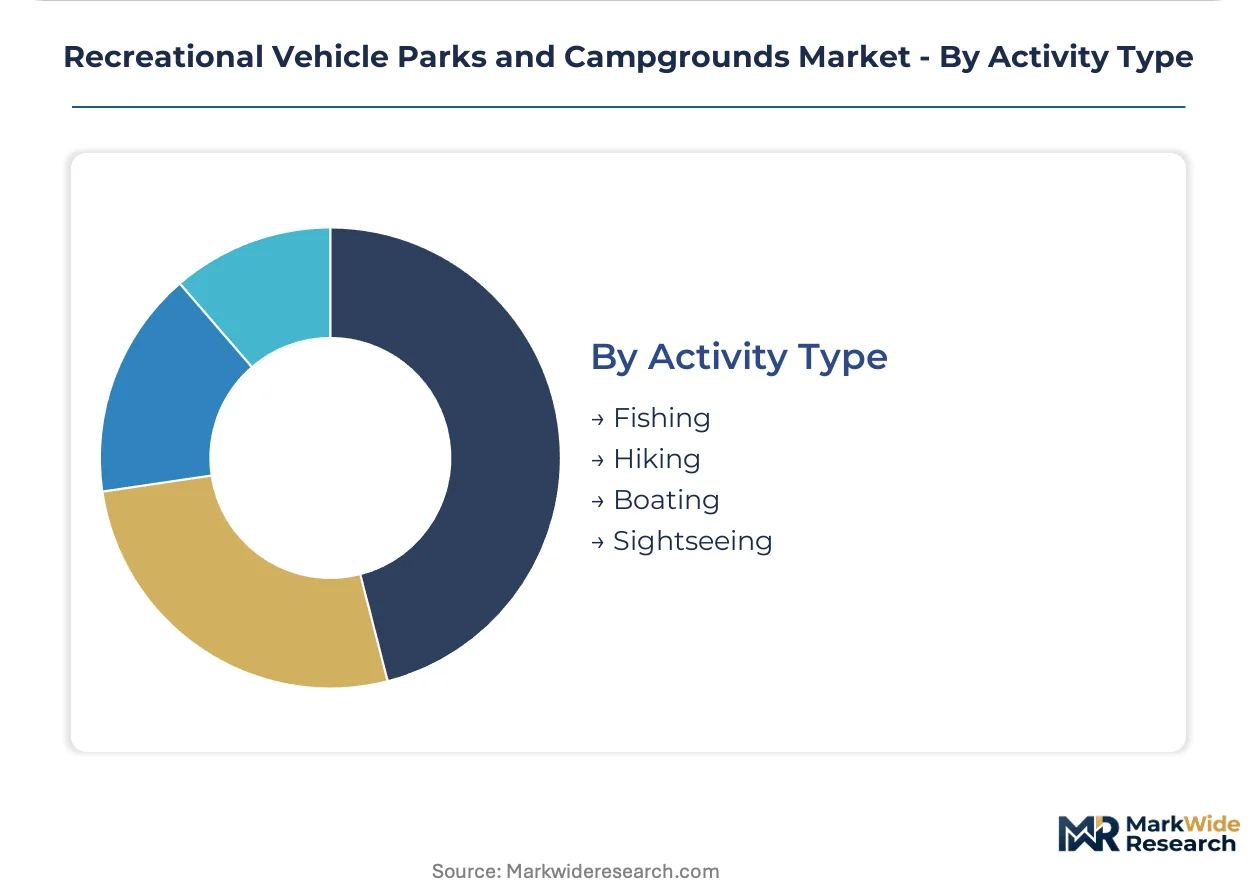
- Fishing:Water-access sites require dock infrastructure and boat launch maintenance, concentrating investment in Great Lakes and Rocky Mountain watersheds.
- Hiking:Trailhead proximity drives premium pricing in Colorado and Utah where public land access creates sustained occupancy pressure.
- Boating:Marina-adjacent facilities face elevated insurance and infrastructure costs.
- Sightseeing:Scenic corridor positioning supports transient booking patterns with lower amenity requirements.
Hiking anchors destination selection. Fishing is expanding most quickly in Great Lakes regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's campground infrastructure emphasizes seasonal tourism cycles, while the United States sustains year-round occupancy through diversified climate zones and snowbird migration corridors.
United States
Western states including California, Arizona, and Colorado concentrate demand through proximity to public lands and national parks. EPA Clean Water Act provisions govern wastewater discharge standards for facilities near protected watersheds. The Colorado River corridor anchors extended-stay patterns where retirees establish predictable winter occupancy.
Canada
Provincial parks in Ontario and British Columbia capture peak-season family travelers during July-August windows. Environment and Climate Change Canada administers environmental assessment protocols for new campground development. The Rocky Mountain parks cluster in Alberta sustains infrastructure investment through Parks Canada partnership frameworks.
Australia
Coastal Queensland and New South Wales drive caravan park demand through domestic tourism recovery and international visitor return. The country's national environmental regulator enforces water quality standards for coastal facility discharge. The Gold Coast hinterland anchors premium RV resort development with extended-stay amenities.
Germany
Bavaria and Baden-Württemberg concentrate camping demand through Alpine access and lake district recreation. ECHA REACH compliance obligations shape chemical handling protocols for facility maintenance operations. The Black Forest region sustains occupancy through certified sustainable tourism designations.
France
Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine capture Mediterranean and Atlantic coastal demand through seasonal tourism flows. ANSM oversees water quality monitoring for facilities with centralized treatment infrastructure. The Dordogne valley anchors glamping retrofit investment targeting experience-seeking demographics.
Recreational Vehicle Parks and Campgrounds Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with franchise networks dominating national coverage while independent operators retain regional density. The vendor base organizes around three archetypes: membership-platform aggregators, destination-adjacent real estate investment trusts, and integrated RV sales-rental bundlers. Consolidation concentrates in Sun Belt markets where snowbird demographics justify acquisition premiums. Geographic expansion and amenity retrofit constitute the dominant competitive moves as operators respond to accessibility mandates and experience-seeking demand shifts.
Within the membership-platform tier, Kampgrounds of America and Thousand Trails exemplify network-scale reservation systems that convert transactional bookings into recurring revenue streams. Equity LifeStyle Properties occupies a position among destination-adjacent real estate trusts optimizing extended-stay yield in high-occupancy corridors. Sun Communities anchors the integrated bundling archetype through combined site rental and vehicle sales operations.
| Leading Market Players |
|---|
| Kampgrounds of America |
| Equity LifeStyle Properties |
| Sun Communities |
| Northgate Resorts |
| Thousand Trails |
| Blue Water Development |
| RVC Outdoor Destinations |
| Good Sam |
| Yogi Bear's Jellystone Park Camp-Resorts |
| Others |
Pricing and Supply Chain Analysis
Utility infrastructure costs cascade from electrical transformer upgrades through site-level metering to nightly rate structures, with copper cabling and smart submetering hardware anchoring capital deployment decisions across Arizona and Florida destination corridors.
Pricing Analysis
Capacity additions in Texas and Colorado are reshaping price floors for full-service hookup tiers. Three-tier pricing structure across premium resort, standard full-service, and primitive economy levels segments snowbird retirees from price-sensitive family travelers. Cost compression in primitive campgrounds is intensifying because ADA pathway mandates force accessibility retrofits without corresponding rate lift. Family travelers exhibit highest price sensitivity, while extended-stay retirees accept premium positioning for utility continuity and social programming.
Supply Chain Analysis
Regional distribution centers for electrical hardware and wastewater treatment components follow hub-and-spoke patterns anchored in Phoenix, Denver, and Orlando. Supply concentrates in domestic manufacturing for 30-50 amp pedestals and septic system components, with PVC piping and electrical conduit drawing from petrochemical feedstocks vulnerable to commodity volatility. Single-source vulnerability concentrates in smart metering chipsets from Taiwan and South Korea. Distribution runs through campground operator cooperatives and franchise procurement networks rather than traditional hospitality supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as snowbird demographics shift toward destination-adjacent properties with healthcare access and extended-stay amenities.
For Market Incumbents: Cement loyalty lock-in through membership platform density in western migration corridors. Prioritize backward integration into smart utility metering to capture consumption-based margin expansion. Defend against glamping retrofit entrants by accelerating fixed-structure luxury tent deployments in Colorado and Utah before permitting windows tighten. For New Entrants and Emerging Players: Enter via workforce housing conversions in remote worker corridors of Utah and Idaho where monthly site rentals undercut corporate apartment rates. Target primitive campground acquisitions in California public land buffer zones where ADA grandfathering delays compliance costs. Lead with EV charging infrastructure as a differentiated amenity for electric tow vehicle segments. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented independent operators lack capital for EPA wastewater treatment upgrades in Colorado and Florida watershed zones. Long-term viability favors destination-adjacent real estate trusts with extended-stay revenue models over transient-focused operators. Watch snowbird demographic migration patterns as the inflection signal for Arizona and Florida acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Glamping Infrastructure Retrofit | Fixed-structure luxury tent platforms capture experience-seeking millennials at premium nightly rates in Dordogne-style deployments. |
| Smart Utility Metering Deployment | Electrical submetering enables consumption-based pricing that improves margin capture on high-amp RV connections. |
| EV Charging Integration | Level 2 and DC fast charging installations attract electric tow vehicle segments underserved by traditional fuel stations. |
| Membership Platform Expansion | Annual subscription models convert price-sensitive families into recurring revenue streams concentrated in western states. |
| Workforce Housing Repositioning | Monthly site rentals target remote worker demographics in Colorado and Utah as corporate housing alternatives. |
Research Methodology
Bottom-up occupancy modeling reconciled against top-down infrastructure investment tracking forms the analytical core. Primary interviews with campground operators, franchise development officers, utility infrastructure vendors, and municipal planning officials combined with secondary validation from EPA enforcement databases, state environmental review filings, and ADA compliance inspection records. Trade association membership data and reservation platform transaction disclosures anchored segmentation calibration.
Input-output matrices mapped site-level revenue per available site against capital expenditure flows across the projection horizon. Service tier, customer duration profile, facility ownership structure, and regional regulatory cluster dimensions shaped volume and value segmentation. CAGRs derived from cohort-based occupancy trend extrapolation tempered by infrastructure capacity constraints and permitting velocity in destination corridors. Snowbird migration pattern indices and remote worker demographic dispersion fed geographic demand allocation.
Inputs from reservation platform disclosures and municipal permitting databases were available through the study window; gaps in private operator financial reporting introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding EPA enforcement phase-in timing and ADA accessibility threshold evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Caravanning Market