
 Fifth Wheel Trailer Market | 2026-2036
Fifth Wheel Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Fifth Wheel Trailer Market Analytics
Lightweight composite chassis construction is fragmenting traditional steel-dominated manufacturing workflows across the fifth wheel trailer industry. Forest River leverages multi-plant capacity across the Midwest and Southeast to sustain cost advantages in high-volume production. Grand Design RV anchors its reputation on residential-grade fit-and-finish standards that command premium positioning. Keystone RV competes through breadth of floorplan variety spanning entry-level to mid-luxury price bands.
A fifth wheel trailer is a towable recreational vehicle that couples to a pickup truck via a kingpin hitch mounted above the rear axle, typically measuring 25 to 45 feet in length and constructed with aluminum or fiberglass sidewalls bonded to a steel or laminated floor frame. The design places a substantial portion of trailer weight directly over the truck axle, improving stability and enabling larger living quarters than conventional travel trailers. Luxury fifth wheel configurations now capture the deepest margin pools as retirees and full-time travelers prioritize residential amenities including washer-dryer prep, dual bathrooms, and insulated four-season packages. Toy hauler variants represent the fastest-expanding product type as adventurers demand integrated garage spaces for ATVs, motorcycles, and kayaks without sacrificing sleeping capacity.
NHTSA Federal Motor Vehicle Safety Standards govern trailer lighting, braking, and tire specifications, while EPA regulations on wood composite emissions affect interior cabinetry material selection. State-level RV registration fees and length restrictions in jurisdictions such as California and Texas further shape product dimension strategies and regional sales patterns. Stakeholders must monitor evolving electrification requirements as manufacturers evaluate compatibility with electric pickup tow vehicles and their reduced payload ratings.
Market Dynamics
Lightweight composite chassis construction is fragmenting traditional steel-dominated manufacturing workflows across the fifth wheel trailer industry, forcing retooling investments and supplier base reconfiguration.
Growth Catalysts
- Remote work normalization:Full-time travelers now represent a rapidly expanding buyer segment as distributed employment enables extended road-based living without fixed residence requirements.
- NHTSA safety standards:Federal Motor Vehicle Safety Standards for trailer braking and lighting systems continue tightening product compliance requirements, accelerating replacement cycles among fleet operators.
- RV park infrastructure:United States highway accessibility and dedicated campground networks support fifth wheel adoption through purpose-built pull-through sites and utility hookups.
Market Restraints
- Steel-aluminum price volatility:Raw material input costs for frame construction fluctuate with commodity markets, compressing margins on entry-level product lines.
- Electric pickup payload limitations:Reduced tow ratings on battery-electric trucks constrain compatibility with heavier luxury configurations.
- State registration fee structures:California and Texas impose length-based levies that disincentivize purchases of extended toy hauler variants.
Strategic Opportunities
- Four-season insulation packages:Cold-weather camping demand creates premium positioning for manufacturers offering thermal bridge elimination and enclosed underbelly designs.
- Dual-bathroom floorplans:Retiree buyers prioritize residential amenity density, opening margin expansion through washer-dryer prep and separated vanity configurations.
- Integrated garage spaces:Toy hauler variants capture adventurer segments seeking ATV and motorcycle transport without sacrificing sleeping capacity.
Industry Challenges
- Skilled lamination technician scarcity:Bonded aluminum-fiberglass sidewall production requires specialized craft labor that regional training pipelines fail to replenish.
- Multi-jurisdictional type approval:California Air Resources Board emissions rules on wood composite cabinetry add compliance layers distinct from federal EPA standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fifth Wheel Trailer Market |
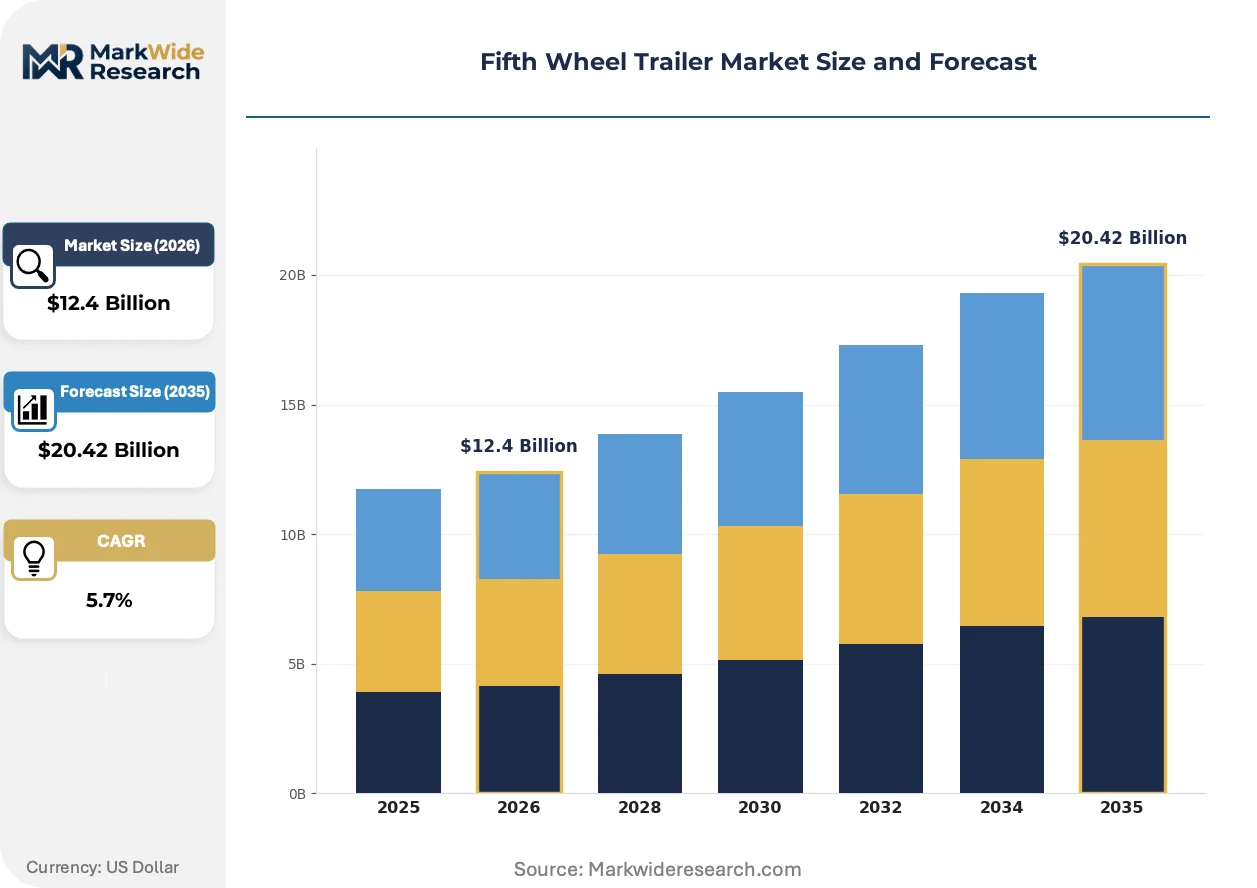
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fifth Wheel, Luxury Fifth Wheel, Toy Hauler, Eco-Friendly Fifth Wheel End User: Families, Retirees, Adventurers, Full-Time Travelers Material: Aluminum, Fiberglass, Steel, Composite Size: Small, Medium, Large, Extra Large |
| Companies Covered | Brinkley RV, Jayco RV, Forest River, Prime Time RV, Luxe Fifth Wheel, Keystone RV, Alliance RV, DRV Luxury Suites, Grand Design RV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fifth Wheel Trailer Market Evolving Landscape
Electrification compatibility, regulatory emissions control, and residential-grade amenity density are converging to redefine product development priorities and buyer expectations across the fifth wheel trailer segment.
Aluminum-composite floor frame construction is hybridizing traditional steel chassis architecture. Full-time travelers and snowbird retirees are adopting laminated subfloor systems at accelerating rates. This material transition is hybridizing supplier relationships and compressing lead times for domestic frame sourcing.
EPA regulations on wood composite formaldehyde emissions are reshaping interior cabinetry material selection. Manufacturers face reformulation costs for particleboard substrates and adhesive systems. Luxury configurations targeting four-season buyers are most affected, with several producers accelerating solid-wood and thermoplastic alternatives.
Direct-to-consumer digital configuration tools are displacing traditional dealer lot selection. Remote workers and younger first-time buyers increasingly design floorplans online before factory commissioning. This channel shift is most visible in the United States, where manufacturer websites now host immersive 3D visualization platforms.
Fifth Wheel Trailer Market Segmentation
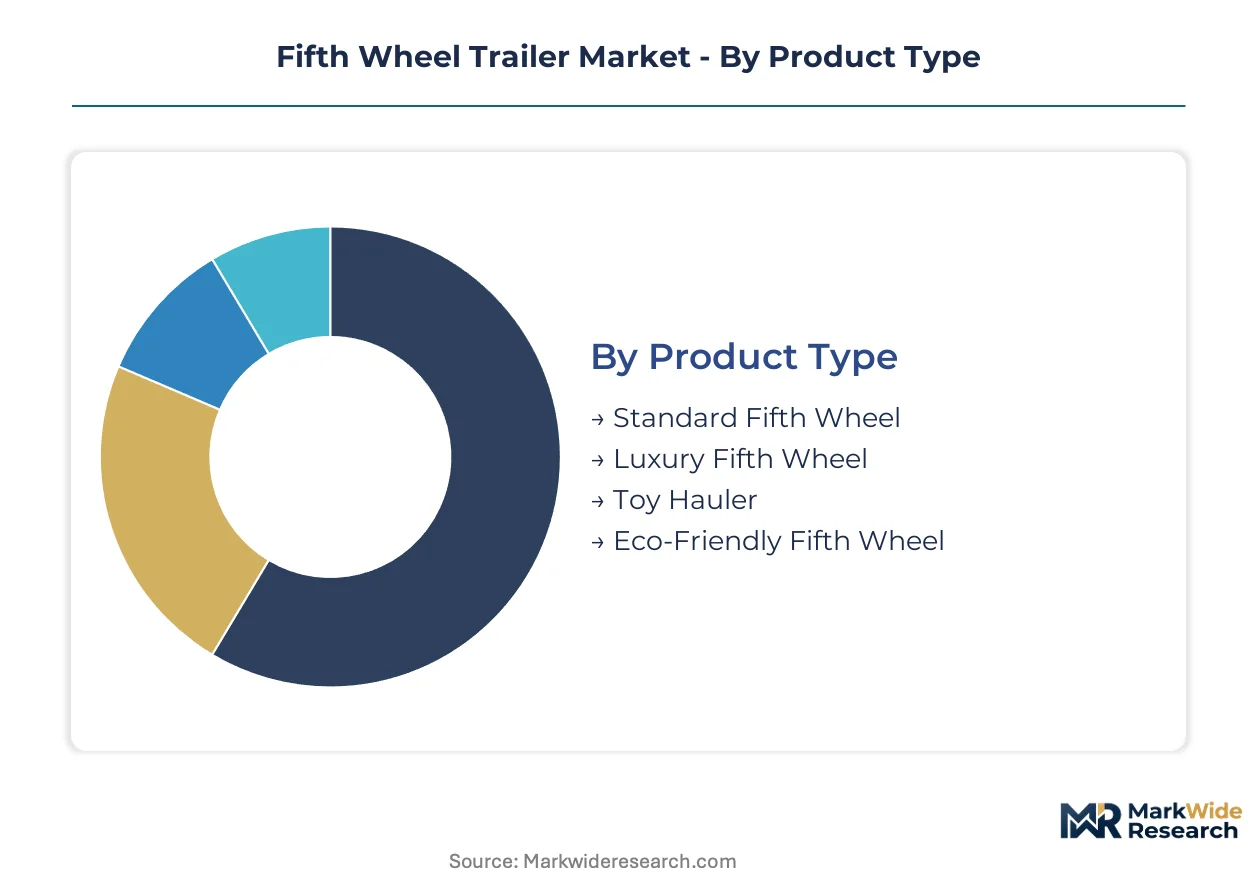
Fifth wheel trailer segmentation reveals distinct service ecosystems, warranty structures, and parts availability patterns that shape manufacturer profitability. Product type and end-user dimensions drive the most pronounced differences in post-purchase revenue streams.
Product Type:
After-sales service intensity varies dramatically across product categories, with toy hauler configurations demanding specialized garage-door mechanism support and luxury units requiring residential-grade appliance servicing networks.
- Standard Fifth Wheel:Entry-level construction with aluminum or fiberglass sidewalls bonded to steel chassis frames. Demand concentrates among first-time buyers in Texas and Florida, where state registration fees favor lighter configurations and seasonal camping patterns dominate usage cycles.
- Luxury Fifth Wheel:Residential-grade fit-and-finish with washer-dryer prep, dual bathrooms, and four-season insulation packages. Full-time travelers in Arizona and retiree snowbird corridors drive premium positioning, with extended warranty penetration reaching highest rates in this tier.
- Toy Hauler:Integrated garage spaces accommodate ATVs, motorcycles, and kayaks without sacrificing sleeping capacity. Adventurer segments in Utah and Colorado favor these variants for backcountry access.
- Eco-Friendly Fifth Wheel:Laminated composite construction and solar prep packages target sustainability-conscious buyers. California Air Resources Board emissions compliance adds certification layers for cabinetry materials.
By volume, Standard Fifth Wheel leads. By growth pace, Toy Hauler is ahead.
End User:
Cost tier stratification separates discretionary vacation spend from residential replacement budgets, with full-time travelers commanding highest per-unit configuration values and longest financing terms.
- Families:Weekend and school-break usage patterns favor bunkhouse floorplans with convertible sleeping arrangements. Entry-level to mid-range price bands dominate this segment.
- Retirees:Snowbird migration corridors between Minnesota and Texas anchor seasonal demand. Residential amenity density—including separated vanities and residential appliances—drives premium specification rates.
- Adventurers:Backcountry access requirements prioritize toy hauler compatibility and off-grid power systems. This segment shows highest attachment rates for generator and solar packages.
- Full-Time Travelers:Remote work normalization has expanded this category fastest. Distributed employment enables extended road-based living without fixed residence requirements, pushing demand toward largest floorplans with dedicated office spaces.
Retirees generate highest absolute unit volumes. Full-Time Travelers are expanding most quickly.
Material:
Supply concentration for laminated composites has shifted procurement patterns, with domestic frame sourcing lead times compressing as aluminum-composite hybridization displaces traditional steel workflows.
- Aluminum:Lightweight sidewall construction dominates mass-market production. Bonded aluminum-fiberglass lamination requires skilled technicians that regional training pipelines struggle to replenish.
- Fiberglass:Gelcoat exterior finishes command premium positioning for weather resistance. Luxury configurations specify full-body paint over fiberglass substrates.
- Steel:Traditional chassis frames persist in entry-level and heavy-duty toy hauler applications. Commodity price volatility compresses margins when steel markets spike.
- Composite:Laminated floor frame systems hybridize traditional architecture. Full-time travelers adopt these at accelerating rates for weight reduction and thermal performance.
Steel retains volume leadership in chassis applications. Composite is gaining share fastest in sidewall and floor systems.
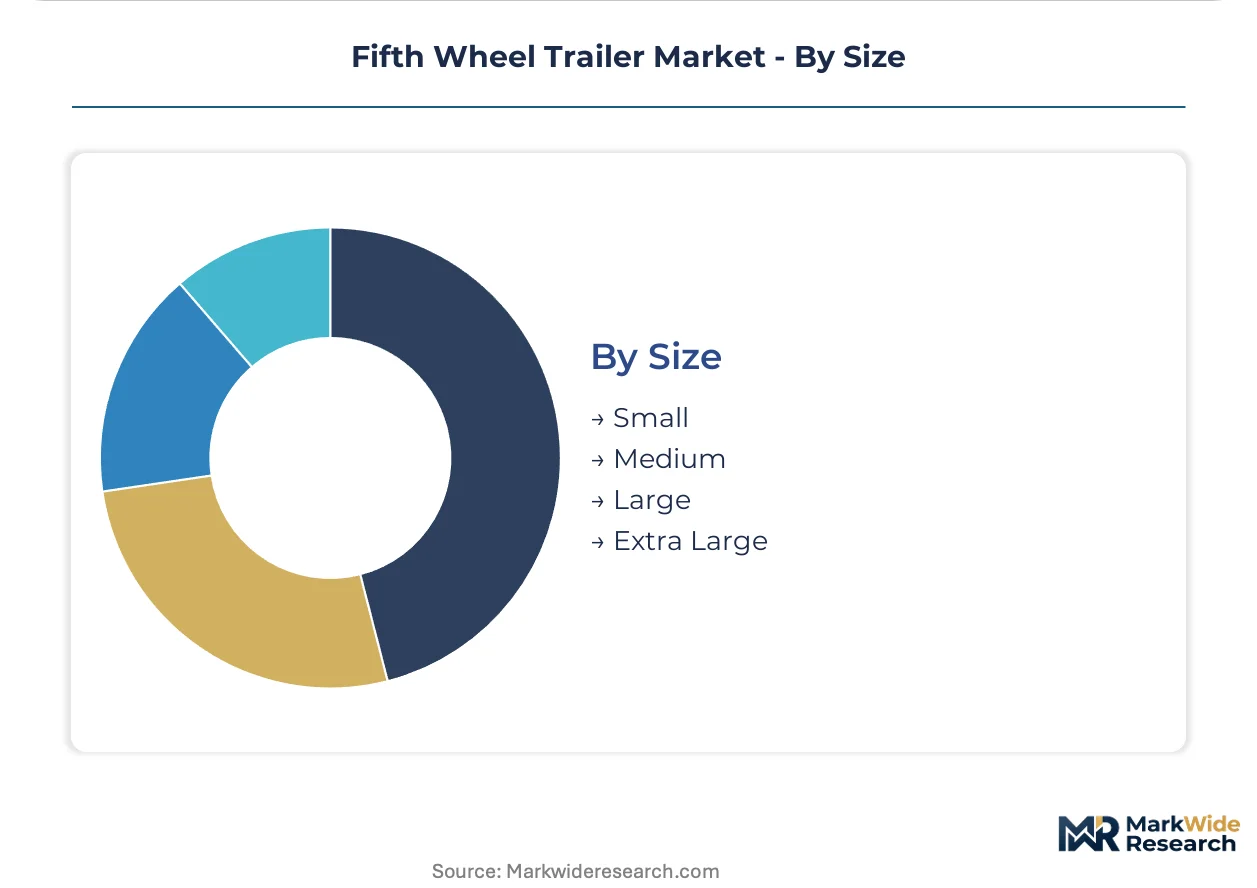
Size:
State-level registration fee structures create geographic demand fragmentation, with California and Texas imposing length-based levies that reshape regional sales patterns.
- Small:Compact configurations under 30 feet suit urban storage constraints and state length restrictions. Younger first-time buyers favor these for maneuverability.
- Medium:30-38 foot range balances living space with tow vehicle compatibility. This segment captures broadest demographic appeal.
- Large:38-45 foot configurations maximize residential amenity density. Full-time travelers and retirees prioritize these for extended occupancy comfort.
- Extra Large:Extended toy hauler variants exceed 45 feet with integrated garage volumes. State registration disincentives limit adoption in California despite strong adventurer demand.
Medium size leads in unit shipments. Large configurations show steepest expansion trajectory among full-time traveler demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Full-time travelers and retiree snowbirds concentrate demand in highway-accessible regions with established RV park infrastructure. The United States dominates unit volumes, while Canada and select European markets sustain niche adoption among adventure-oriented buyers.
United States
Remote workers and retirees drive fifth wheel demand across Arizona, Texas, and Florida seasonal corridors. NHTSA Federal Motor Vehicle Safety Standards govern trailer braking and lighting compliance. Elkhart, Indiana anchors manufacturing concentration, with laminated sidewall production expanding across Midwest supplier networks.
Canada
Snowbird migration patterns sustain winter demand in British Columbia and Alberta manufacturing bases. Transport Canada CMVSS regulations mirror NHTSA safety frameworks with provincial registration variations. The Quebec-Ontario corridor hosts specialized cold-weather insulation suppliers serving four-season configurations.
Germany
Adventure tourism and caravanning culture support premium fifth wheel interest among domestic buyers. KBA type-approval requirements and EU trailer directive harmonization shape product compliance. Bavarian industrial clusters near Munich concentrate chassis component fabrication for export markets.
Australia
Remote work normalization expands outback touring demand among domestic travelers. ADR trailer standards and state-based registration authorities regulate safety compliance. Queensland manufacturing hubs near Brisbane specialize in off-road suspension configurations for backcountry access.
United Kingdom
Retiree leisure touring sustains modest fifth wheel adoption despite narrower tow vehicle availability. DVSA trailer safety regulations and post-Brexit type-approval divergence add compliance complexity. Midlands-based fabricators concentrate on compact configurations suited to European road constraints.
Fifth Wheel Trailer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands, with consolidation pressure intensifying among mid-scale fabricators. The vendor base separates into three strategic archetypes: multi-brand conglomerates leveraging plant network scale, premium specialists commanding residential-grade positioning, and value-focused volume producers optimizing floorplan variety. Dominant competitive moves include backward integration into chassis fabrication and geographic expansion of lamination capacity.
Among North American manufacturers, Forest River, Grand Design RV, and Keystone RV exemplify distinct competitive positioning. Forest River represents the multi-plant conglomerate archetype with distributed Midwest and Southeast capacity. Grand Design RV occupies the premium residential-fit-and-finish tier. Keystone RV anchors the breadth-driven strategy spanning entry-level through mid-luxury configurations.
| Leading Market Players |
|---|
| Brinkley RV |
| Jayco RV |
| Forest River |
| Prime Time RV |
| Luxe Fifth Wheel |
| Keystone RV |
| Alliance RV |
| DRV Luxury Suites |
| Grand Design RV |
| Others |
Value Network & Pricing Analysis
Elkhart County, Indiana anchors laminated sidewall and chassis fabrication capacity, concentrating margin capture among multi-plant conglomerates while compressing pricing power for regional fabricators without captive lamination facilities.
Pricing Analysis
Steel and aluminum futures indexation in frame supply contracts forces quarterly price adjustments that ripple through manufacturer cost structures. Three-tier pricing structure across premium, standard, and economy levels segments buyers by amenity density and warranty depth. Pricing pressure stems from commodity volatility in steel markets, squeezing entry-level configurations where buyers exhibit highest price sensitivity. Full-time travelers in luxury tiers demonstrate lowest price elasticity, prioritizing residential-grade fit-and-finish over unit cost.
Supply Chain Analysis
Contract lamination capacity concentrates among Midwest-based sidewall specialists serving Forest River, Grand Design RV, and Keystone RV production networks. The supply chain draws from domestic steel mills, Canadian aluminum smelters, and Chinese fiberglass mat suppliers. Single-source vulnerability in bonded aluminum-fiberglass lamination technicians creates bottleneck risk as regional training pipelines fail to replenish skilled craft labor. Distribution runs through franchised dealer networks with manufacturer-direct digital configuration platforms gaining share among remote worker demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fifth wheel trailer market offers durable defensive positioning through regulatory entrenchment, as NHTSA safety standards and state-level emissions rules create compliance moats that disadvantage unscaled entrants lacking certification infrastructure.
For Market Incumbents: Entrench market position through backward integration into composite chassis fabrication and captive lamination capacity expansion across Indiana and Ohio manufacturing corridors. Electric pickup payload limitations threaten luxury configuration demand, requiring accelerated lightweight material R&D to preserve tow compatibility. Dealer network consolidation represents the priority lever for channel control against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: Eco-friendly fifth wheel configurations in California represent the most penetrable entry point, as CARB emissions compliance creates certification barriers that filter out mass-market competitors. Four-season insulation packages for snowbird retirees in Arizona-Texas corridors offer second white-space opportunity. Go-to-market execution should prioritize factory-direct digital configuration platforms with immersive visualization tools.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-scale fabricators with captive lamination capacity and established NHTSA compliance histories. Long-term viability hinges on electrification compatibility and lightweight material transitions over the coming decade. The signal to watch is electric pickup tow rating announcements from major OEMs as inflection indicator for luxury configuration demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chassis Fabrication | Captive composite frame production insulates margin from steel-aluminum volatility at Elkhart suppliers. |
| Four-Season Insulation Package Expansion | Cold-weather thermal bridge elimination commands premium positioning among Minnesota snowbird retirees. |
| Direct-to-Consumer Digital Configuration | Factory commissioning platforms displace dealer inventory carrying costs for remote worker buyers. |
| CARB-Compliant Cabinetry Certification | California Air Resources Board emissions compliance unlocks eco-friendly segment access in Sacramento regulatory environment. |
| Toy Hauler Garage Mechanism R&D | Integrated ATV lift systems differentiate adventurer configurations in Utah and Colorado backcountry markets. |
Research Methodology
Operator-level perspectives from RV dealership principals, lamination plant supervisors, NHTSA compliance officers, and full-time traveler user groups anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against NHTSA FMVSS filings, EPA wood composite emissions databases, state registration fee schedules, and manufacturer production disclosures. Bottom-up unit shipment modeling triangulated against top-down consumer expenditure estimates from recreation vehicle trade associations.
Scenario-bracketing around electric pickup adoption curves and remote work normalization rates bounded demand projections across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, material construction, and size tier alongside geographic regulatory cluster variations. CAGRs derived from historical shipment trajectories adjusted for replacement cycle acceleration under tightening safety standards and full-time traveler demographic expansion.
Practitioners should monitor electric vehicle tow rating announcements, steel futures volatility, and CARB emissions rulemaking for early signals of forecast revision. Quarterly review of lamination technician training pipeline output and dealer inventory days-supply is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Water Scooter Market