
 Australia Recreational Vehicle Market | 2026-2036
Australia Recreational Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Recreational Vehicle Market Outlook
Market Context
Asset-light leasing and subscription-based RV access models is rewriting competitive dynamics by lowering entry barriers for younger demographics and occasional users. Jayco leverages its vertically integrated manufacturing footprint across Victorian facilities to sustain cost leadership across the mid-market caravan segment. Winnebago Group anchors premium motorhome positioning through specialized diesel-powered chassis configurations and national dealership coverage. Crusader Caravans differentiates via aluminum frame construction technology and direct-to-consumer configuration tools that compress order-to-delivery cycles.
Technical Definition and Segment Structure
Australia recreational vehicles encompass self-propelled and towable mobile dwellings engineered for temporary habitation, typically incorporating sleeping quarters, cooking facilities, and onboard power systems ranging from 12V DC to 240V AC with solar augmentation. These units serve domestic tourism, seasonal migration, and remote workforce accommodation across Australia's vast road network and low-population hinterlands. Caravan and camper trailer categories dominate unit volume due to lower capital outlay and compatibility with existing passenger vehicle tow ratings, while motorhome and fifth-wheel configurations capture concentrated margin pools among retiree and long-haul adventurer end users. Electric and hybrid fuel type adoption remains nascent but structurally significant as tow vehicle electrification progresses and campground charging infrastructure expands along major highways.
Regulatory Environment and Outlook
The Australian Design Rules administered by the Department of Infrastructure, Transport, Regional Development, Communications and the Arts govern structural integrity, braking performance, and lighting compliance for all new RV registrations. State-level registration authorities including VicRoads, Transport for NSW, and Queensland Department of Transport and Main Roads impose varying mass limits, inspection regimes, and licensing prerequisites that fragment market access requirements. TGA-aligned electrical safety standards and gas certification protocols further constrain aftermarket modification and self-build activity. Stakeholders must monitor impending ADR revisions affecting trailer stability control mandates and the alignment of state registration frameworks with federal minimum standards to anticipate compliance cost shifts and product redesign cycles.
Market Dynamics
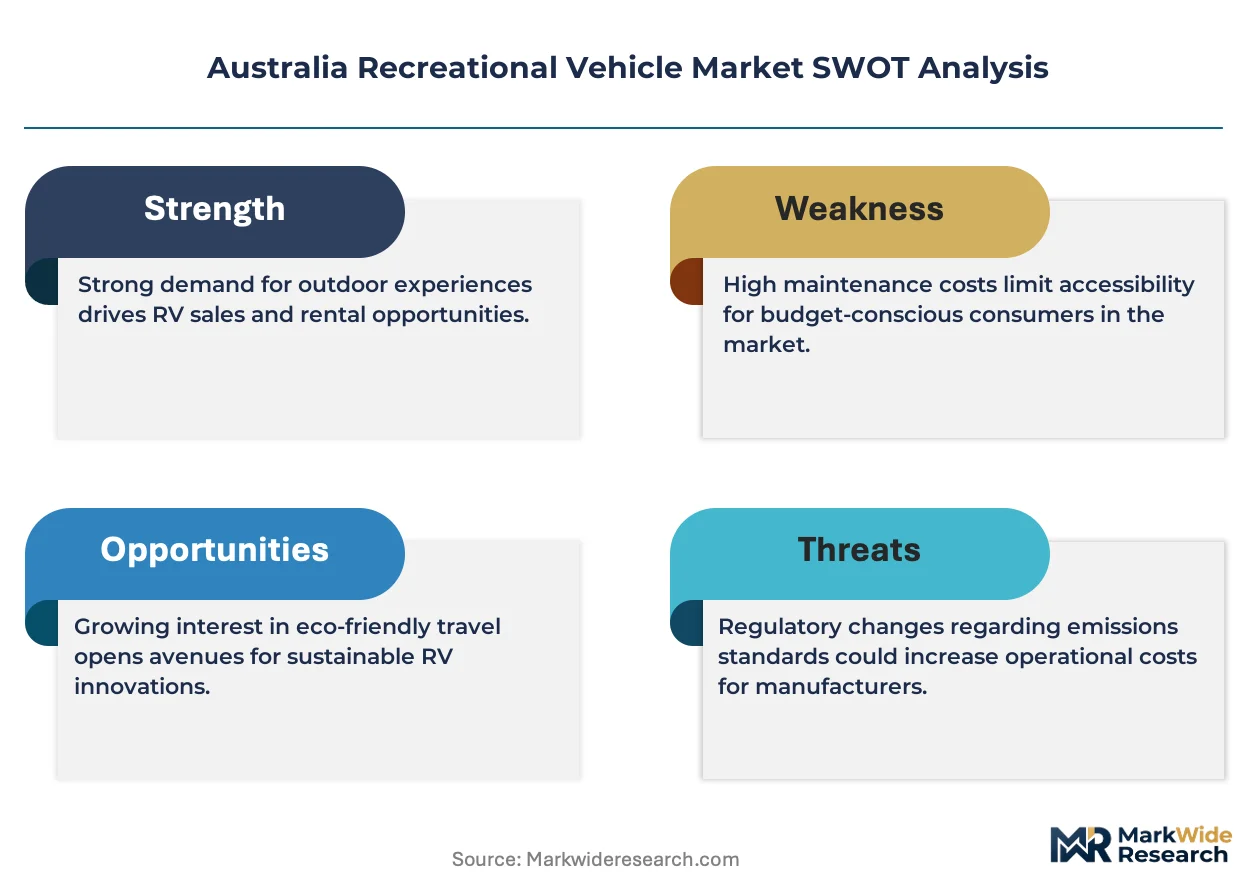
ADR compliance mandates and state registration fragmentation are forcing manufacturers to engineer modular platforms that satisfy divergent mass limits and inspection regimes across Australian jurisdictions.
Growth Catalysts
- Retiree demographic expansion:Australia's aging population is accelerating demand for mobile leisure accommodations, with coastal Queensland and New South Wales caravan parks expanding infrastructure to capture this cohort.
- Solar-augmented power systems:12V DC to 240V AC electrical architectures with photovoltaic integration are reducing campground dependency and extending remote-stay duration for long-haul adventurers.
- Tow vehicle electrification:Battery-electric passenger vehicles with enhanced tow ratings are opening new buyer segments previously excluded by payload limitations.
Market Restraints
- Aluminum and steel input volatility:Frame construction materials face commodity price swings that compress margin pools for mid-market caravan producers.
- State licensing fragmentation:VicRoads, Transport for NSW, and Queensland Department of Transport impose non-harmonized mass limits and inspection prerequisites that inflate compliance overhead.
- Substitution by glamping infrastructure:Permanent luxury tent accommodations at coastal destinations are capturing occasional users who previously rented entry-level camper trailers.
Strategic Opportunities
- Subscription-based access models:Asset-light leasing platforms targeting younger demographics and infrequent users are expanding addressable market beyond traditional ownership.
- Trailer stability control mandates:Impending ADR revisions will require integrated electronic braking systems, creating aftermarket upgrade demand and OEM premium positioning.
- Remote workforce accommodation:Mining and infrastructure projects in Western Australia and Northern Territory are sourcing self-contained RVs for fly-in-fly-out worker housing.
Industry Challenges
- Gas certification technician scarcity:TGA-aligned electrical safety and gas compliance protocols require specialized certifiers, creating bottlenecks in production throughput.
- Aftermarket modification liability:Self-build activity and owner modifications trigger warranty disputes and insurance coverage gaps that strain dealer networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Recreational Vehicle Market |
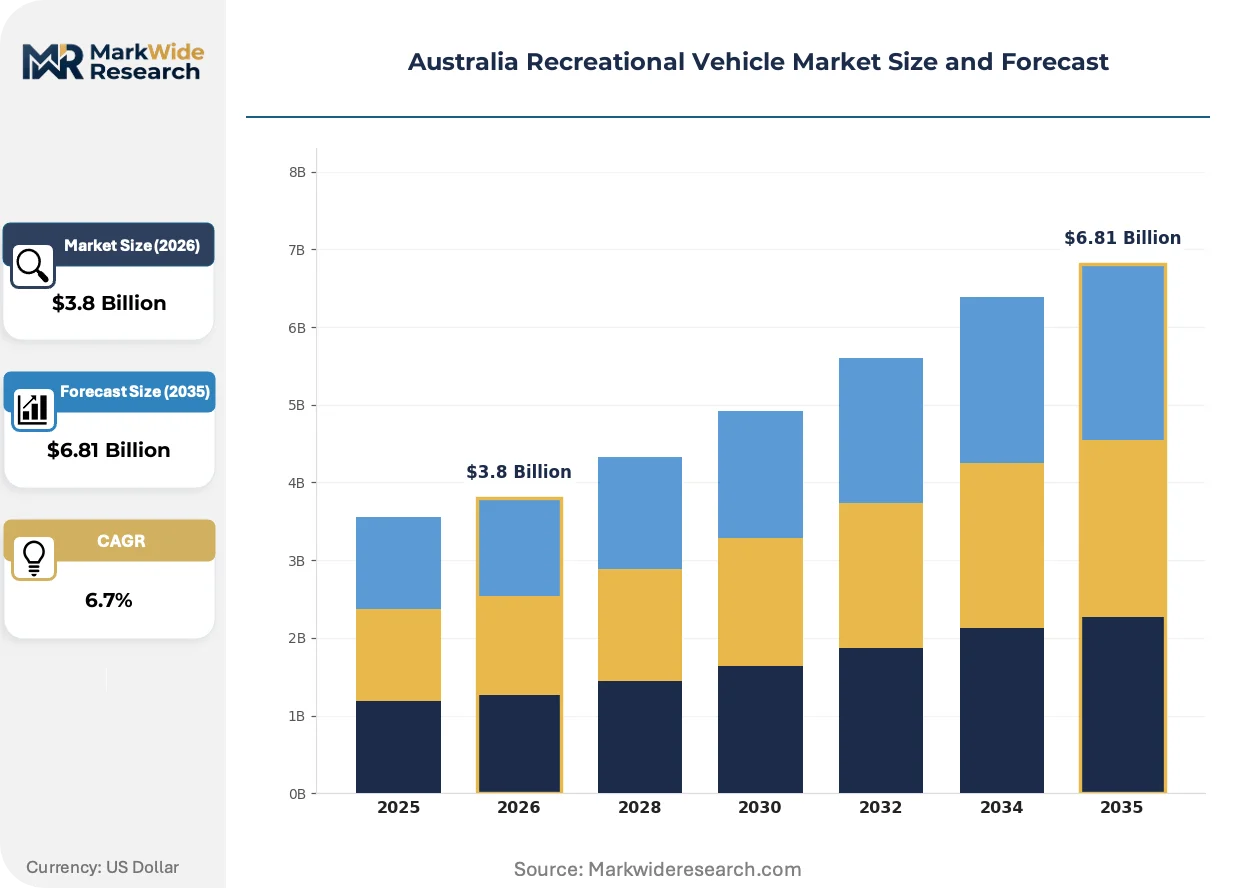
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorhome, Caravan, Camper Trailer, Fifth Wheel Distribution Channel: Direct Sales, Dealerships, Online Platforms, Rental Services End User: Families, Retirees, Adventurers, Tourists Fuel Type: Diesel, Petrol, Electric, Hybrid |
| Companies Covered | Winnebago Group, Swift Group Australia, Jayco, Crusader Caravans, Titanium Caravans, Snowy River Caravans, Sunliner Recreational Vehicles, Market Direct, Avida RV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Recreational Vehicle Market Strategic Shifts
Electrification of tow vehicles and charging infrastructure deployment are compressing the traditional diesel-autonomy advantage that long-haul motorhomes have held for decades.
Lightweight composite panel construction is collapsing the historical trade-off between structural durability and tow vehicle compatibility. Retiree buyers migrating from rigid-frame caravans to composite-bodied units are demanding single-vehicle garage storage solutions. Manufacturers are responding with sub-2,000 kg tare designs that expand compatible tow vehicle pools.
The Department of Infrastructure, Transport, Regional Development, Communications and the Arts is revising Australian Design Rules to mandate trailer stability control systems. This regulatory trajectory will phase out basic mechanical braking configurations by the mid-2030s. Premium motorhome segments are pre-emptively integrating proprietary electronic chassis control to differentiate safety positioning.
Direct-to-consumer configuration tools are displacing traditional dealership specification processes. Buyers in Queensland and coastal New South Wales are compressing order-to-delivery cycles through online customization portals. This channel shift reduces inventory carrying costs for manufacturers while fragmenting geographic concentration of sales activity.
Australia Recreational Vehicle Market Segmentation
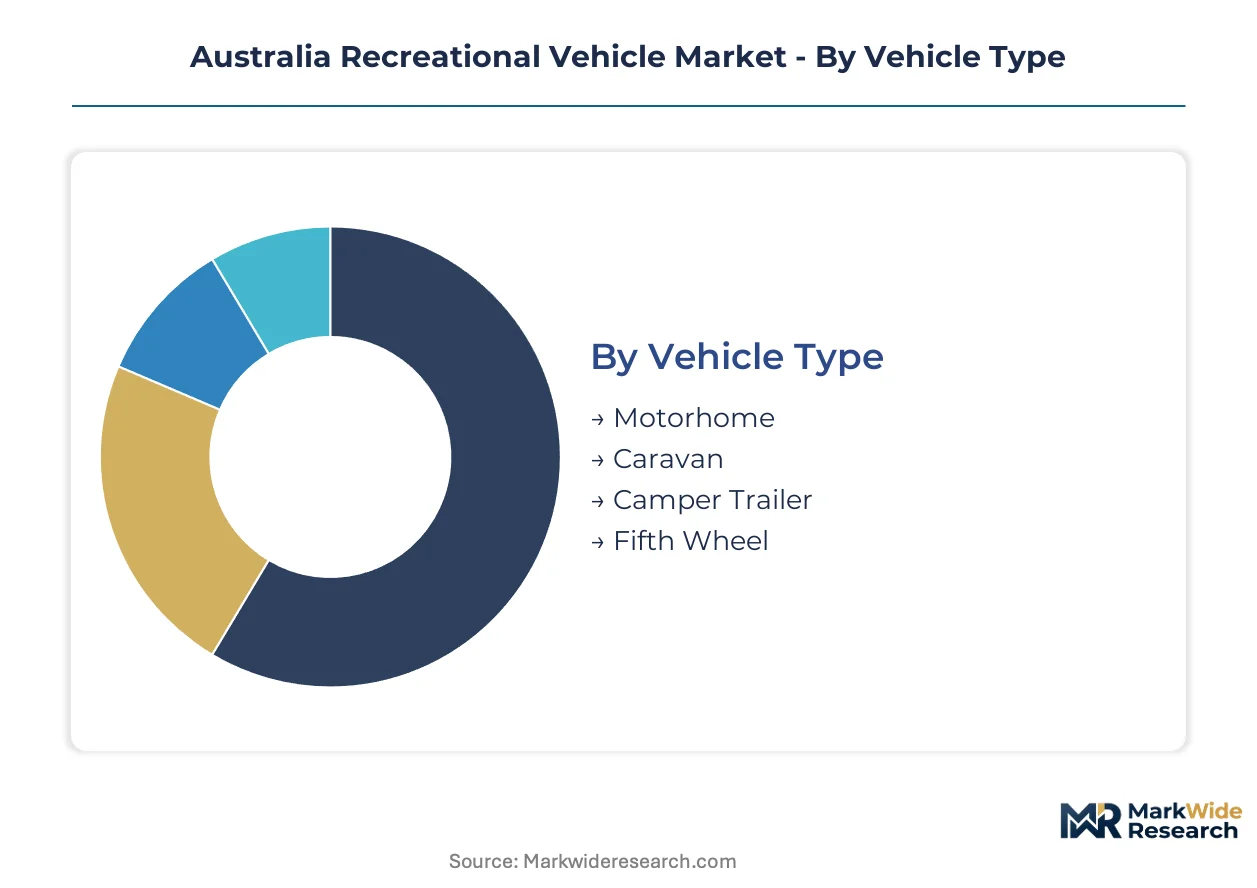
Segmentation in the Australian RV market reveals how capital intensity, usage patterns, and regulatory constraints fragment buyer behavior across distinct product configurations. Understanding these divisions illuminates where margin pools concentrate and where new entrants face structural barriers.
Vehicle Type:
Cost tier determines access thresholds and recurring expenditure profiles across the four vehicle configurations.
- Caravan:Towable units with rigid or composite body construction dominate unit volume through compatibility with standard passenger vehicle tow ratings. Demand concentrates in Queensland and coastal New South Wales where retirees seek seasonal migration flexibility without motorhome capital outlay.
- Motorhome:Self-propelled dwellings built on dedicated chassis configurations command premium positioning through integrated drivetrains and higher amenity density. Long-haul adventurers traversing Western Australia's remote road networks favor diesel-powered variants for extended autonomy between fuel stops.
- Camper Trailer:Collapsible soft-wall or hard-wall towables minimize storage footprint and entry price point. Younger families in suburban Melbourne and Sydney use these for intermittent weekend escapes without dedicated parking requirements.
- Fifth Wheel:Hitch-mounted over-bed configurations requiring heavy-duty tow vehicles occupy a narrow niche. Mining project contractors in the Northern Territory source these for semi-permanent workforce accommodation near remote extraction sites.
Caravan holds installed capacity. Motorhome is rotating up the share rankings.
Distribution Channel:
Customer acquisition economics vary sharply between asset-heavy dealership networks and emerging digital pathways.
- Dealerships:Physical showrooms with service bays and parts inventory anchor mid-market caravan transactions. Regional Queensland dealers leverage caravan park partnerships to bundle site bookings with unit sales.
- Direct Sales:Manufacturer-owned configuration portals compress order-to-delivery cycles and capture margin otherwise allocated to independent retailers. Jayco's Victorian facilities utilize this channel to penetrate price-sensitive buyer segments.
- Online Platforms:Aggregator marketplaces and manufacturer portals enable geographic arbitrage for buyers outside dealership catchments. These channels expand most quickly among metropolitan millennials researching specifications before limited physical inspection.
- Rental Services:Short-term access models lower trial barriers for uncertain first-time users. Operators near Sydney and Brisbane airports capture inbound international tourists seeking self-drive alternatives to conventional accommodation.
Dealerships hold installed capacity. Direct sales is rotating up the share rankings.
End User:
Life stage and mobility requirements segment buyers into four cohorts with divergent product specifications.
- Retirees:Extended-duration travelers prioritizing comfort and single-level living configurations. This cohort concentrates in Queensland's Gold Coast hinterland and northern New South Wales coastal corridors where caravan park infrastructure supports months-long stays.
- Families:School-holiday users seeking bunk configurations and outdoor kitchen amenities for intermittent use. Demand clusters around Melbourne's eastern suburbs and Sydney's northern beaches where storage constraints favor collapsible camper trailers.
- Adventurers:Remote-terrain specialists requiring high ground clearance, water capacity, and off-grid power autonomy. Western Australia's Pilbara region and South Australia's Flinders Ranges attract this segment seeking isolation from established campground networks.
- Tourists:Short-stay renters and international visitors utilizing rental fleets for curated touring routes. These users concentrate along the Great Ocean Road and Tasmania's east coast where pre-planned itineraries dominate.
Retirees hold installed capacity. Families is rotating up the share rankings.
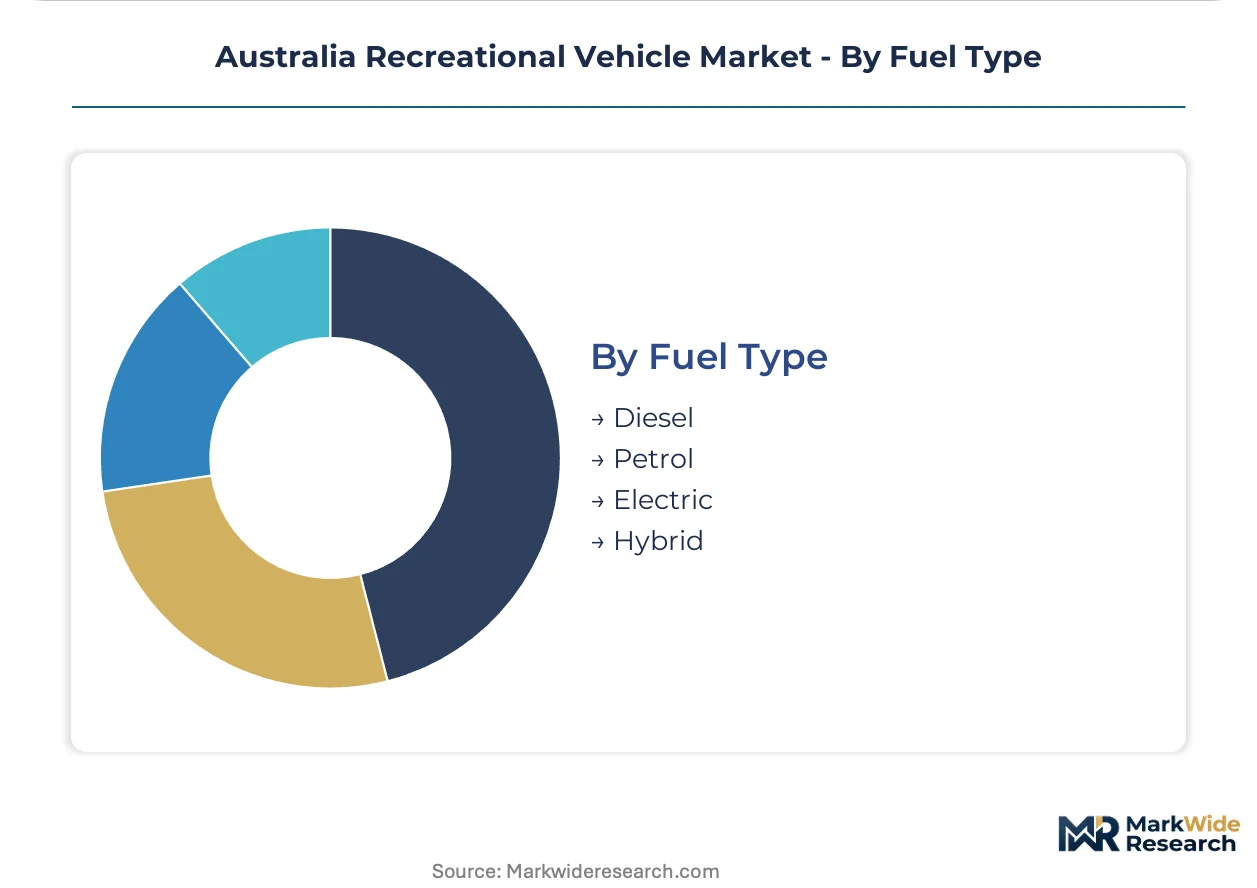
Fuel Type:
Propulsion technology maturity shapes operational range, infrastructure dependency, and resale trajectory across powertrain options.
- Diesel:Compression-ignition engines dominate motorhome segments through torque characteristics suited to heavy chassis and extended range. Long-haul adventurers crossing the Nullarbor Plain rely on diesel's established fuel station network.
- Petrol:Spark-ignition configurations persist in lightweight camper trailers and entry caravans towed by conventional passenger vehicles. Urban families around Perth and Adelaide favor petrol compatibility with existing fleet vehicles.
- Electric:Battery-electric tow vehicles with manufacturer-extended range ratings are emerging for short-haul caravan applications. Charging infrastructure deployment along the Hume and Pacific Highways is accelerating feasibility for coastal corridor touring.
- Hybrid:Parallel and series-hybrid powertrains bridge range anxiety and electrification preferences. These configurations are gaining share fastest among metropolitan buyers seeking reduced fuel expenditure without campground charging dependency.
Diesel holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-based registration incentives and caravan park infrastructure investments are redistributing demand across Australia's eastern seaboard and resource corridors. Queensland and New South Wales dominate retiree migration patterns, while Western Australia and South Australia attract remote workforce and adventure touring segments.
New South Wales
Coastal retirement communities from Byron Bay to Port Macquarie drive seasonal caravan park occupancy. Transport for NSW maintains mass limit variations that manufacturers must engineer around for registration compliance. Sydney's northern beaches and Central Coast manufacturing clusters supply camper trailer configurations optimized for suburban storage constraints.
Queensland
The Gold Coast hinterland and Sunshine Coast corridor concentrate Australia's highest density of long-stay caravan park infrastructure. The Queensland Department of Transport and Main Roads imposes inspection regimes that differ from southern states, fragmenting compliance requirements. Brisbane-based dealers leverage airport proximity to capture inbound tourist rental demand.
Victoria
Melbourne's eastern suburbs generate family-oriented demand for collapsible camper trailers with bunk configurations. VicRoads enforces distinct licensing prerequisites and mass thresholds that shape product specifications for the state market. Geelong and Melbourne manufacturing facilities anchor domestic production capacity for mid-market caravan segments.
Western Australia
Mining fly-in-fly-out operations in the Pilbara and Goldfields regions source self-contained RVs for remote workforce accommodation. The state's vast road networks and sparse fuel infrastructure sustain demand for diesel-powered motorhomes with extended range capability. Perth metropolitan buyers favor petrol-compatible camper trailers matched to existing passenger vehicle fleets.
South Australia
The Flinders Ranges and Eyre Peninsula attract adventure touring segments seeking isolation from established campground networks. South Australia's registration authority maintains alignment with federal ADR minimums rather than imposing additional state-specific requirements. Adelaide-based rental operators serve international tourists traversing the Great Ocean Road corridor.
Australia Recreational Vehicle Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated domestic manufacturers and specialized import distributors. Three strategic archetypes dominate: scale-driven mass-market producers with captive manufacturing footprints, premium motorhome specialists leveraging diesel chassis partnerships, and aluminum-frame innovators compressing delivery cycles through direct-to-consumer channels. Competitive moves concentrate on manufacturing capacity expansion in Victoria and Queensland, plus strategic partnerships with tow vehicle OEMs to align payload specifications.
Within the scale-driven tier, Jayco anchors mid-market positioning through Victorian manufacturing concentration. Winnebago Group occupies the premium motorhome vector with national dealership coverage and specialized chassis configurations. Crusader Caravans exemplifies the materials-innovation archetype, differentiating through aluminum frame construction and configuration tools that accelerate order fulfillment. These three fabricators collectively represent the structural segmentation between volume production, premium positioning, and manufacturing technology differentiation.
| Leading Market Players |
|---|
| Winnebago Group |
| Swift Group Australia |
| Jayco |
| Crusader Caravans |
| Titanium Caravans |
| Snowy River Caravans |
| Sunliner Recreational Vehicles |
| Market Direct |
| Avida RV |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Victorian manufacturing clusters is compressing margin pools for mid-market caravan producers while simultaneously pressuring suppliers to absorb commodity volatility through longer payment terms. This utilization imbalance rewards vertically integrated fabricators with captive chassis production and penalizes assemblers dependent on spot-market aluminum frame sourcing.
Pricing Analysis
Certification level under TGA-aligned electrical safety and gas compliance protocols creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ADR compliance tier and customization density driving differentiation. Cost compression in the standard tier is intensifying because aluminum input volatility transfers directly to frame fabricators without downstream pricing power. Retiree buyers demonstrate lowest price sensitivity, prioritizing single-level living configurations and extended warranties, while younger families exhibit highest elasticity, favoring rental and subscription access models over capital outlay.
Supply Chain Analysis
Export-control regimes on advanced composite panel technology from European suppliers limit domestic access to lightweight construction materials, forcing Australian manufacturers toward heavier fiberglass alternatives. Supply concentrates in China for electrical components, Germany for chassis braking systems, and domestic Victorian facilities for final assembly. Raw material dependencies center on aluminum extrusions, lithium-ion battery cells, and photovoltaic panels. Single-source vulnerability in specialized gas certification equipment creates production bottlenecks when TGA-aligned inspection capacity saturates. Distribution runs through independent dealership networks with service bay requirements, though direct-to-consumer configuration portals are fragmenting geographic sales concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state registration frameworks and divergent buyer life stages creates niche entry points for specialized players. The retiree demographic expansion simultaneously with younger family subscription appetite splits demand into ownership and access-based segments.
For Market Incumbents: Insulate margin pools by deepening backward integration into aluminum frame production and captive solar power system assembly, reducing exposure to commodity volatility. Secure exclusive caravan park partnership networks in Queensland and coastal New South Wales to lock in seasonal migration demand before emerging rental platforms capture trial users. For New Entrants and Emerging Players: Pursue white-space opportunities in remote workforce accommodation for Western Australian mining contractors, where fly-in-fly-out operations seek semi-permanent RV housing beyond traditional caravan park infrastructure. Target the fifth-wheel configuration segment, which remains underpenetrated relative to retiree motorhome and family caravan volumes. Deploy direct-to-consumer configuration tools with compressed order-to-delivery cycles as the primary go-to-market angle, mirroring successful channel shifts in Queensland metropolitan markets. For Investors and Strategic Acquirers: Long-term, this sits as a demographic tailwind play because Australia's aging population structure supports sustained retiree demand for mobile leisure accommodations regardless of cyclical tourism fluctuations. Acquisition target archetype: aluminum-frame innovators with direct-to-consumer channel infrastructure and TGA-aligned certification capabilities already embedded. Watch trailer stability control mandate implementation timing as the inflection signal—early compliance investments will separate premium-positioned OEMs from laggards facing forced redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Frame Production | Captive aluminum extrusion capacity insulates margin pools from commodity volatility affecting Victorian assemblers. |
| Direct-to-Consumer Configuration Portal Launch | Online customization tools compress order-to-delivery cycles and capture margin otherwise allocated to Queensland dealerships. |
| Caravan Park Partnership Network Expansion | Exclusive site booking bundling with unit sales locks in retiree seasonal migration patterns along coastal New South Wales corridors. |
| TGA-Aligned Certification Capacity Investment | In-house gas and electrical safety certifiers eliminate production bottlenecks constraining throughput for mid-market producers. |
| Subscription-Based Access Model Pilot | Asset-light leasing platforms penetrate younger demographics and occasional users excluded by traditional ownership economics. |
Study Parameters
Operator-level perspectives from caravan park operators, OEM production planners, TGA certification specialists, and dealership network managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against Australian Design Rule filings, state registration authority inspection protocols, customs import data for chassis components, and caravan park occupancy surveys. Bottom-up unit volume estimates triangulated with top-down expenditure flow analysis across the projection horizon.
Scenario-bracketing around tow vehicle electrification penetration and aluminum price volatility bands structured the analytical framework. Segmentation dimensions modeled encompass vehicle type, distribution channel, end-user life stage, and fuel type propulsion architecture. CAGRs were derived from fitted trend extrapolation moderated by regulatory compliance cost assumptions and infrastructure deployment trajectories. Industry-specific forecast inputs incorporated ADR revision timelines and state registration harmonization probability assessments.
Sensitivities concentrate around trailer stability control mandate timing, tow vehicle electrification acceleration, and state registration framework convergence. Forecasts reflect documented assumptions regarding retiree demographic trajectories and commodity input price paths. Material shifts in federal-state regulatory alignment or breakthrough composite panel technology commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Segway Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market