
 Norway Electric Vehicle Market | 2026-2036
Norway Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Electric Vehicle Market Insights
Fleet operators is unwinding the traditional private-owner dominance that defined Norway's early EV transition. Tesla sustains brand pull through its Supercharger network density along Norwegian coastal corridors. Volkswagen anchors volume sales with its ID.buzz van targeting postal and last-mile delivery contracts. Volvo Car specializes in premium electric SUVs that command pricing power in Oslo's affluent suburbs.
An electric vehicle converts stored electrical energy into mechanical propulsion through battery-electric or fuel-cell powertrains, with lithium-ion battery packs typically delivering 300-600 volts DC to permanent-magnet synchronous motors. Passenger cars occupy the dominant volume position yet face margin compression as subsidies phase down and competition intensifies. Fast charging infrastructure captures disproportionate investment attention because range anxiety persists among rural buyers and commercial fleets running extended duty cycles. Solid state battery technology promises energy density gains that would reshape vehicle packaging and thermal management requirements.
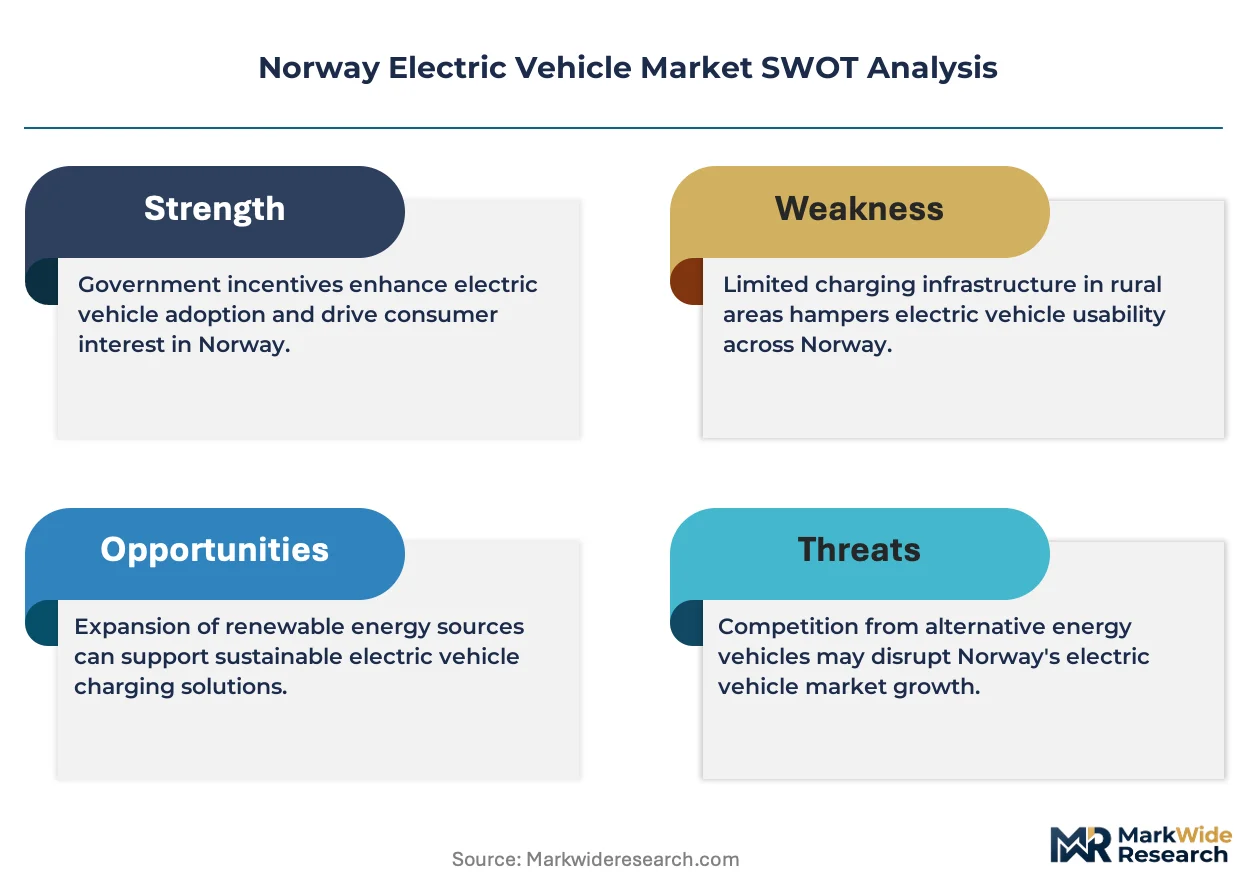
Norwegian regulators enforce zero-emission vehicle sales quotas through the Ministry of Climate and Environment while the Norwegian Public Roads Administration administers EV toll exemptions and bus lane access privileges. The country's national petroleum fund divestment from fossil fuel investments signals long-term policy commitment that underwrites charging infrastructure subsidies. Stakeholders must monitor how grid capacity constraints in northern counties reshape deployment priorities and whether fleet electrification timelines accelerate faster than utility upgrade schedules permit.
Market Dynamics
Fleet electrification timelines are compressing against utility infrastructure upgrade cycles, creating a structural tension between commercial buyer readiness and distribution grid capacity in Norway's northern counties.
Growth Catalysts
- Zero-emission vehicle mandate:Norway's Ministry of Climate and Environment enforces binding sales quotas that eliminate internal combustion engine options for commercial buyers, accelerating van and bus procurement decisions.
- CO2 taxation structure:Steep levies on fossil fuel vehicles compress total cost of ownership payback periods to under three years for electric vans in postal and last-mile delivery applications.
- Oslo charging density:Eastern Norway concentrates over half of all fast-charging points, enabling fleet operators to run extended duty cycles without range anxiety penalties.
Market Restraints
- Lithium supply concentration:Cathode active material processing clusters in China create single-source dependency for Norwegian battery pack assemblers, exposing margins to export control volatility.
- Grid reinforcement lag:Northern Norway's distribution networks lack transformer capacity for simultaneous fleet depot charging, forcing operators into costly demand charge management or staggered vehicle deployment.
- Residual value uncertainty:Rapid battery chemistry evolution erodes confidence in secondary market pricing for first-generation electric vans, elevating leasing costs for risk-averse fleet managers.
Strategic Opportunities
- V2G integration:Bi-directional charging infrastructure transforms parked commercial fleets into grid stabilization assets, opening revenue streams through frequency regulation contracts with Statnett.
- Solid-state battery convergence:Silicon-anode and ceramic electrolyte technologies promise thermal management simplification that would enable heavier payloads in electric vans without range sacrifice.
- Rural charging corridors:Underpenetrated western coastal routes between Bergen and Ålesund present first-mover advantage for operators willing to pre-position fast-charging hubs ahead of tourism and freight demand.
Industry Challenges
- High-voltage technician scarcity:Norwegian vocational programs graduate fewer than two hundred certified EV powertrain specialists annually, creating recruitment bottlenecks for fleet maintenance operations scaling beyond fifty vehicles.
- Interoperability certification delays:Nordic harmonization of CCS2 charging communication protocols lags German and Dutch standardization timelines, forcing operators to maintain redundant adapter inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Electric Vehicle Market |
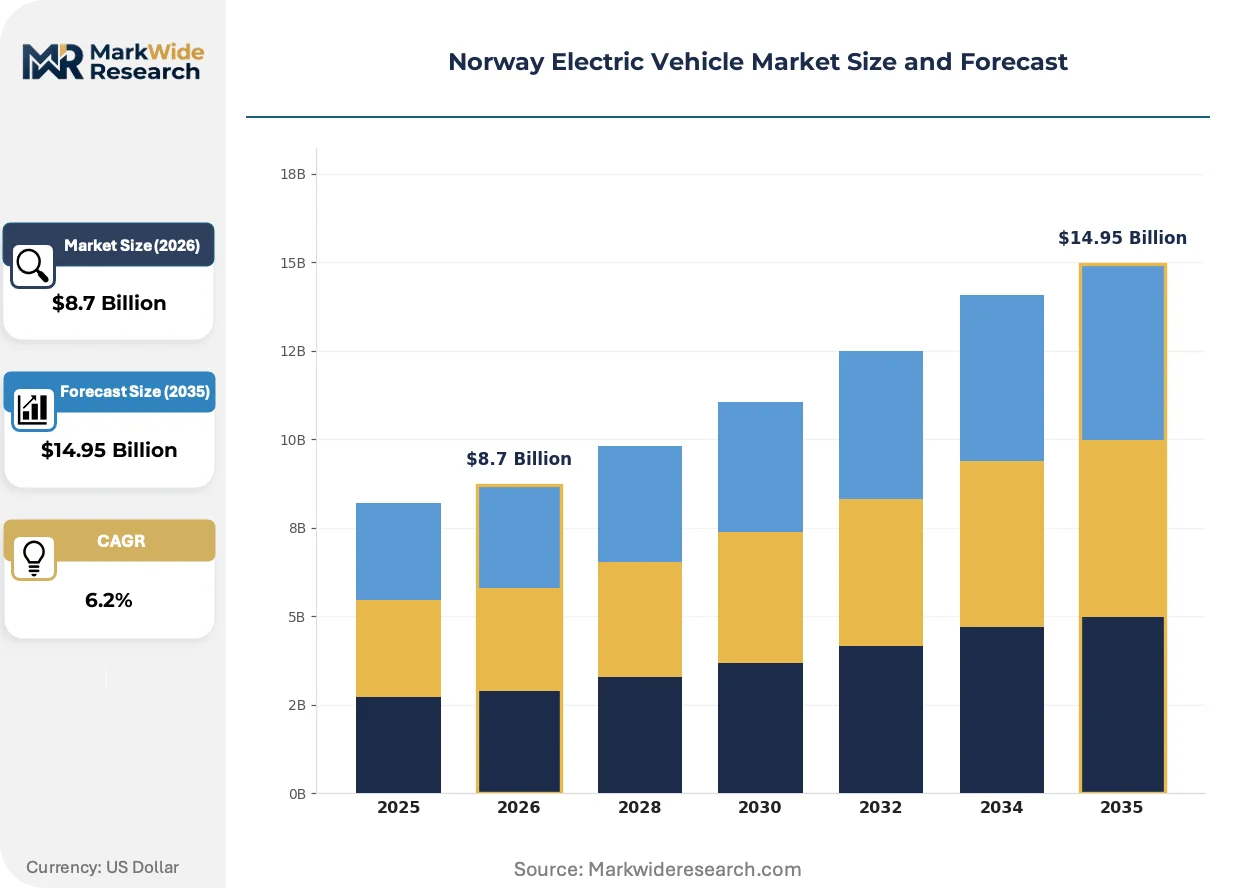
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vans, Buses, Trucks Battery Technology: Lithium-ion, Solid State, Lead Acid, Nickel Metal Hydride Charging Infrastructure: Fast Charging, Home Charging, Superchargers, Public Charging Stations Market Segment: Private Owners, Fleet Operators, Ride Sharing, Government Agencies |
| Companies Covered | Tesla, Volkswagen, Volvo Car, Toyota, Skoda, Nissan, Audi, Hyundai, BMW, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Electric Vehicle Market Trends and Innovations
Battery-electric powertrains are fragmenting into modular cell-to-pack architectures while charging infrastructure evolves toward megawatt-scale depot systems. These shifts are compressing vehicle development cycles and rewiring fleet operator procurement criteria.
Solid-state battery research is decomposing the traditional thermal management burden that constrains energy density in lithium-ion packs. Norwegian research institutes and automotive suppliers are co-developing sulfide-based electrolyte formulations that eliminate liquid cooling loops entirely. Fleet operators running temperature-sensitive pharmaceutical or fresh food logistics are piloting early prototypes to capture payload weight advantages. This technology is decomposing the packaging constraints that currently force van designers into compromised cargo volumes.
Norway's zero-emission vehicle mandate tightens annually through 2025, with the Norwegian Public Roads Administration administering toll exemptions and bus lane access that compound the regulatory stick with tangible operational carrots. Commercial buyers face progressive penalty structures for internal combustion engine retention, redirecting capital allocation toward electric van procurement committees. Postal and parcel delivery segments are responding fastest, with route density in Oslo and Drammen justifying dedicated depot charging investments ahead of regulatory deadlines.
Subscription-based fleet access is displacing traditional ownership models among mid-sized logistics operators unwilling to absorb battery degradation risk or residual value volatility. Leasing providers now bundle charging infrastructure, maintenance, and energy costs into per-kilometer contracts that transfer technical complexity to specialized asset managers. This model is gaining strongest traction in Stavanger and Trondheim, where oil sector layoffs have created entrepreneurial delivery service formations with limited balance sheet capacity for vehicle capitalization.
Norway Electric Vehicle Market Segmentation
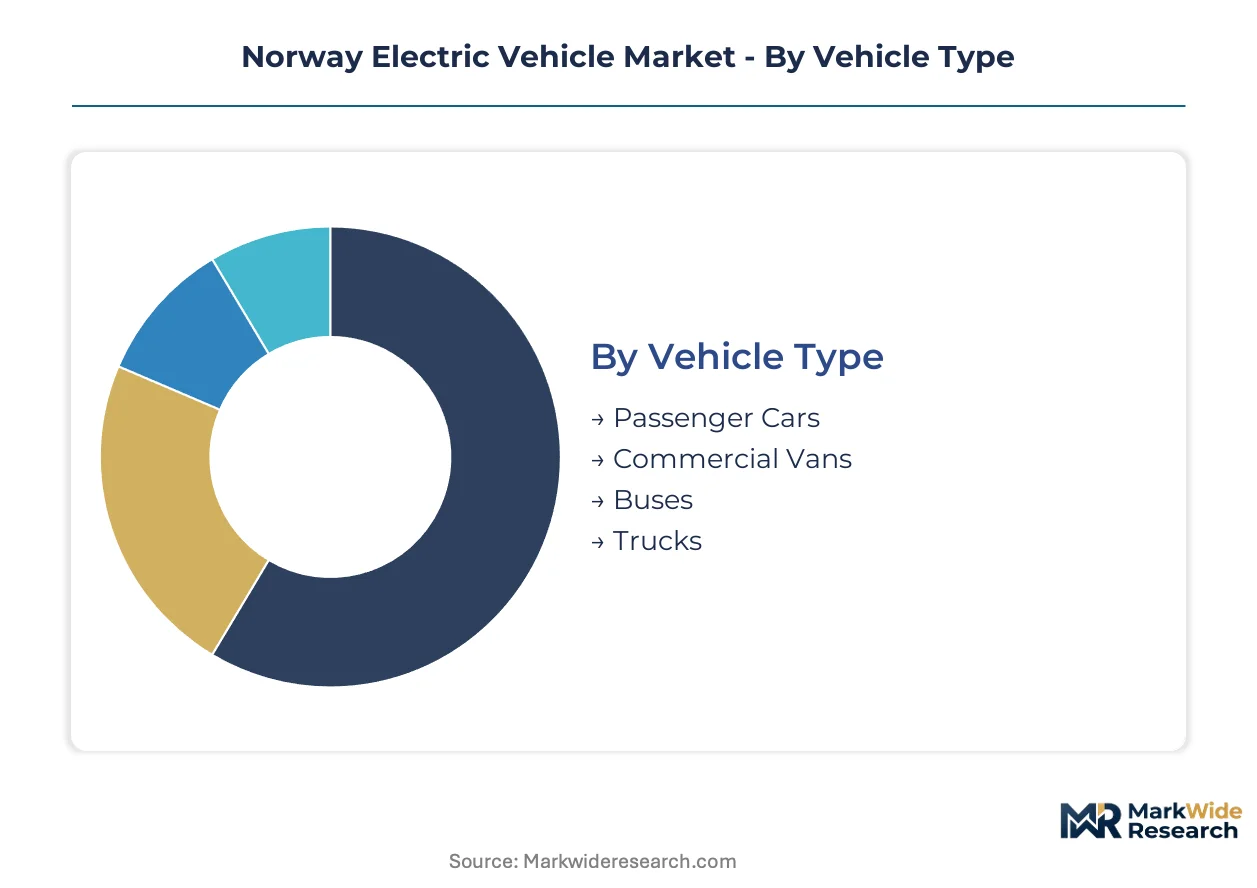
Norway's electric vehicle market fragments along four intersecting dimensions that shape procurement patterns across Oslo's affluent suburbs and northern rural corridors. Understanding these segment boundaries clarifies why fleet operators now outpace private buyers in volume growth and how charging infrastructure investments concentrate geographically.
Vehicle Type:
Domestic demand concentrates on passenger cars and light commercial vehicles, while export-oriented manufacturing from Swedish and German plants supplies heavier-duty segments.
- Passenger Cars:Battery-electric sedans and SUVs dominate registration volumes, with lithium-ion packs delivering 300-600 volts DC to permanent-magnet synchronous motors. Oslo and surrounding eastern counties absorb the densest concentration as zero-emission mandates eliminate internal combustion engine options for new buyers.
- Commercial Vans:Postal and last-mile delivery fleets drive procurement acceleration, with total cost of ownership payback periods compressing below three years under steep CO2 taxation. Northern counties face depot charging constraints that stagger deployment timelines despite regulatory deadlines.
- Buses:Urban transit authorities in Bergen and Trondheim electrify route networks ahead of national mandates, though rural intercity lines lag due to range limitations and sparse fast-charging corridors.
- Trucks:Heavy-duty electric powertrains remain nascent, with pilot programs limited to short-haul distribution from Oslo container terminals where return-to-base charging infrastructure exists.
Passenger cars hold the largest share; momentum sits with commercial vans as fleet electrification timelines compress.
Battery Technology:
Cost tier differentiation separates premium solid-state research programs from commoditized lithium-ion volume production serving mainstream vehicle categories.
- Lithium-ion:NMC and LFP cathode formulations power virtually all current Norwegian EV registrations, with cell-to-pack architectures reducing thermal management overhead. Chinese processing concentration for cathode active materials exposes assemblers to export control volatility.
- Solid State:Sulfide-based electrolyte research at Norwegian institutes promises energy density gains that would eliminate liquid cooling loops entirely. Pharmaceutical logistics operators pilot early prototypes to capture payload weight advantages in temperature-sensitive cargo applications.
- Lead Acid:Auxiliary power applications in legacy commercial vehicle retrofits represent residual demand, declining rapidly as lithium-ion costs fall.
- Nickel Metal Hydride:Hybrid-electric transitional technology retains minimal presence, largely displaced by full battery-electric powertrains across all vehicle categories.
Lithium-ion dominates installed base; solid-state chemistry gains share fastest among premium commercial applications.
Charging Infrastructure:
Application context determines infrastructure preference, with depot systems serving fleet duty cycles and public networks addressing range anxiety among dispersed private owners.
- Fast Charging:DC rapid chargers above 150kW concentrate along coastal corridors and Oslo-Akershus economic zones, enabling extended commercial duty cycles without range penalties. Grid reinforcement lag in northern counties limits simultaneous depot deployment.
- Home Charging:Residential AC wallboxes serve suburban private owners in Oslo's affluent districts, though apartment dwellers face installation barriers that push demand toward public alternatives.
- Superchargers:Proprietary high-power networks anchor coastal route coverage, with density heaviest on corridors linking Stavanger, Bergen, and Trondheim.
- Public Charging Stations:Municipal deployments in city centers and retail parking structures address apartment resident access gaps, with utilization rates highest in eastern Norway population clusters.
Fast charging commands capital allocation; home charging expands most quickly as suburban housing stock turns over.
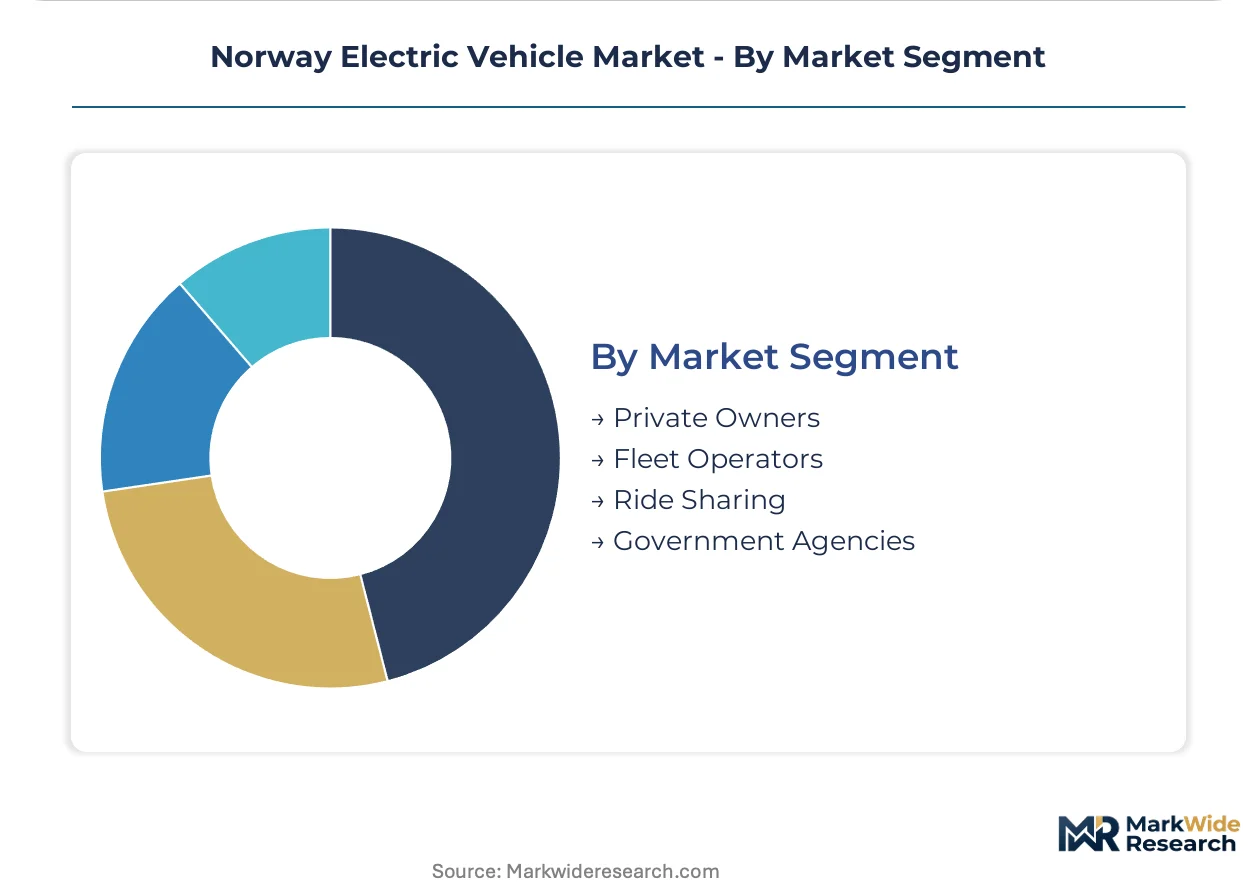
Market Segment:
Customer type stratification reveals fleet operators displacing private owners as the primary volume driver, with procurement patterns diverging sharply on financing and risk tolerance.
- Private Owners:Affluent households in Oslo suburbs purchase premium electric SUVs through conventional retail channels, absorbing residual value risk directly as battery chemistry evolution accelerates.
- Fleet Operators:Postal, parcel, and urban delivery services scale van procurement through subscription-based access models that transfer technical complexity to specialized asset managers. Stavanger and Trondheim entrepreneurial formations drive strongest traction.
- Ride Sharing:Platform drivers prioritize vehicles with fastest charging capability to maximize utilization, concentrating demand on models compatible with high-power urban charging networks.
- Government Agencies:Municipal and national procurement committees enforce zero-emission mandates through binding quotas administered by the Ministry of Climate and Environment, with bus lane access and toll exemptions compounding regulatory pressure.
Fleet operators capture volume leadership; ride sharing climbs fastest as platform economics favor electric operating cost structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea Link cable and Nordic grid interconnects underpin Norway's electricity surplus that powers continental Europe's largest per-capita EV fleet. This transmission infrastructure exports clean hydropower while stabilizing domestic charging demand curves.
Oslo and Akershus
Urban density and affluence concentrate Norway's highest EV registration rates, with postal fleets and ride-sharing platforms driving van procurement acceleration. The Norwegian Public Roads Administration administers toll exemptions and bus lane access that compound operational advantages for commercial operators. Drammen corridor logistics hubs deploy dedicated depot charging ahead of national zero-emission deadlines.
Bergen and Western Counties
Tourism freight and coastal shipping logistics create distinctive duty-cycle demands for electric commercial vehicles. County-level procurement committees enforce municipal zero-emission mandates that redirect transit authority capital toward electric bus networks. Underpenetrated charging corridors between Bergen and Ålesund present infrastructure investment gaps that fleet operators now target for first-mover positioning.
Trondheim and Central Norway
Oil sector restructuring has spawned entrepreneurial delivery formations with limited balance sheet capacity for vehicle capitalization. Subscription-based fleet access models gain strongest traction here as specialized asset managers absorb battery degradation risk. Statnett grid integration trials explore vehicle-to-grid revenue streams from parked commercial fleets.
Northern Norway
Sparse population distribution and extreme temperature ranges test battery thermal management systems in ways that southern markets do not. Distribution grid transformer capacity constraints force fleet operators into staggered vehicle deployment or costly demand charge management. Tromsø municipal authorities pilot solid-state battery prototypes for temperature-sensitive pharmaceutical logistics.
Stavanger and Southwestern Region
Energy sector transition employment shifts redirect skilled technician labor toward EV maintenance operations. Regional vocational programs graduate certified high-voltage specialists below fleet scaling requirements, creating recruitment bottlenecks. Coastal Supercharger density heaviest on corridors linking Stavanger to Bergen enables extended commercial duty cycles.
Norway Electric Vehicle Market Competitive Landscape
Listed automotive conglomerates compete with private specialists across battery supply chain control and charging infrastructure ownership. Market structure tilts toward consolidated volume manufacturers with captive finance arms, yet software-defined vehicle capabilities open entry points for technology-native challengers. Three archetypes dominate: integrated OEMs with proprietary charging networks, platform-agnostic fleet service aggregators, and cell chemistry specialists upstream. Competitive moves concentrate on strategic partnerships for solid-state battery development and geographic expansion of fast-charging corridor coverage.
Among volume-focused manufacturers, Tesla, Volkswagen, and Volvo Car occupy distinct positioning vectors. Tesla exemplifies the integrated infrastructure archetype through coastal corridor Supercharger density that anchors brand pull. Volkswagen represents fleet procurement specialization with van platforms targeting postal and last-mile delivery contract structures. Volvo Car sits within premium SUV positioning that commands pricing power in Oslo's affluent suburban markets.
| Leading Market Players |
|---|
| Tesla |
| Volkswagen |
| Volvo Car |
| Toyota |
| Skoda |
| Nissan |
| Audi |
| Hyundai |
| BMW |
| Others |
Pricing and Supply Chain Analysis
Cell-to-pack manufacturing scale at Asian battery plants compresses Norwegian EV assemblers' input costs while concentrating pricing power among cathode active material processors in China. This scale asymmetry forces domestic fleet operators into long-term offtake contracts that lock in volume-discount tiers but expose margins to export control volatility.
Pricing Analysis
Volume-discount tiering structures dominate Norwegian EV procurement, with fleet operators capturing 15-20% unit cost reductions above 500-vehicle annual commitments while private buyers absorb sticker prices without scale leverage. Price differentiation rests on charging speed capability and battery warranty length, with 800V architectures and 8-year coverage commanding premiums in Oslo's commercial van segment. Cost compression in mid-tier passenger cars is intensifying because Volkswagen and Skoda expand ID-platform production for postal contracts. Fleet managers exhibit highest price sensitivity due to total cost of ownership scrutiny, while affluent private buyers in Akershus suburbs show lowest sensitivity to premium SUV positioning.
Supply Chain Analysis
Inbound logistics costs through Rotterdam-Antwerp container corridors and Baltic Sea feeder routes add 8-12% to landed battery pack costs for Norwegian assemblers lacking direct Asian supplier relationships. Cathode active material processing concentrates in China, South Korea, and Japan, with NMC and LFP formulations drawing from cobalt and lithium hydroxide feedstocks anchored in Chile and Australia. Single-source vulnerability to Chinese export licensing for graphite anodes and electrolyte salts creates procurement contingency requirements. Distribution runs through Gothenburg and Hamburg hub-and-spoke networks before final-mile deployment to Oslo depot charging installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across Norwegian postal and parcel segments has shifted bargaining power toward volume buyers capable of dictating charging infrastructure co-investment terms. This buyer-power concentration rewards suppliers with modular platform architectures and subscription-ready financing structures.
For Market Incumbents: Fortify Supercharger corridor density along Bergen-Ålesund coastal routes to preempt emerging fleet deployment in underpenetrated western logistics corridors. Secure captive lithium hydroxide supply through offtake agreements with Australian spodumene processors to offset Chinese cathode concentration risk. Deepen software-defined vehicle capabilities to defend against technology-native entrants targeting subscription-based fleet access models.
For New Entrants and Emerging Players: Anchor in Trondheim and Stavanger entrepreneurial delivery formations where oil sector restructuring has created balance-sheet-constrained buyers receptive to per-kilometer fleet access contracts. Target pharmaceutical logistics operators in Northern Norway piloting solid-state battery prototypes for temperature-sensitive cargo applications. Pursue vehicle-to-grid integration partnerships with Statnett as differentiated entry angle against established charging network incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet service aggregators bundling charging infrastructure, maintenance, and energy costs into single-contract vehicle access. Long-term viability in this market hinges on grid integration capabilities and battery chemistry optionality across the next decade. Acquisition targets should display established Statnett frequency regulation contracts or sulfide-based solid-state electrolyte research partnerships with Norwegian institutes. Watch for inflection signals in northern county transformer upgrade schedules that would unlock simultaneous depot charging deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in cathode active material access from South Korean processors for ID-platform van production. |
| Charging Infrastructure Partnership | Extends coastal Supercharger density to Bergen-Ålesund corridors ahead of tourism freight demand. |
| Software-Defined Vehicle Investment | Enables over-the-air thermal management updates for solid-state battery prototypes in pharmaceutical logistics. |
| Vehicle-to-Grid Integration | Transforms parked commercial fleets into Statnett frequency regulation assets with contracted revenue streams. |
| Geographic Manufacturing Footprint | Positions cell-to-pack assembly near Gothenburg hub to reduce Rotterdam-Antwerp logistics exposure. |
Research Methodology
Operator-level perspectives from fleet procurement managers, charging infrastructure developers, high-voltage maintenance technicians, and Statnett grid integration specialists anchored the qualitative base for this analysis. Primary interview data triangulated against vehicle registration databases from the Norwegian Public Roads Administration, IHS Markit powertrain production records, and customs filings tracking lithium-ion cell imports through Gothenburg and Hamburg. Secondary validation drew from Ministry of Climate and Environment policy disclosures, Norwegian Public Roads Administration toll exemption utilization reports, and Statnett grid capacity planning documents. Bottom-up fleet deployment modeling converged with top-down market sizing across vehicle class, battery chemistry, charging infrastructure type, and customer segment dimensions.
Sensitivity analysis tested forecast robustness against variable assumptions including northern county transformer upgrade timelines, Chinese export control stringency on cathode materials, and solid-state battery commercialization pace. The analytical framework modeled volume and value outputs across passenger cars, commercial vans, buses, and trucks by lithium-ion and solid-state chemistry splits, with depot versus public charging infrastructure deployment patterns as cross-cutting segmentation. CAGRs derived from logistic growth curve fitting to historical registration trajectories, incorporating CO2 taxation elasticity parameters and zero-emission mandate compliance deadlines as structural break points. Forecast inputs included Statnett grid reinforcement capital expenditure plans and Norwegian vocational program graduation rates for high-voltage technician certification.
Material uncertainties — grid capacity constraints in northern counties, battery chemistry evolution trajectories, and geopolitical export control disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and infrastructure investment schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France E-Bike Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Saudi Arabia Electric Vehicle Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Automotive Battery Thermal Management System Market