
 Middle East and Africa Personal Watercraft Market | 2026-2036
Middle East and Africa Personal Watercraft Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Personal Watercraft Market Foresight
Marine tourism is recalibrating demand composition across the Middle East and Africa Personal Watercraft Market as coastal resort operators replace aging rental fleets. Yamaha Motors leverages its established dealership network across Gulf Cooperation Council states to sustain parts availability and service coverage. BRP Inc. competes through specialized sit-down models optimized for extended Red Sea touring routes. Kawasaki Motors Corporation anchors its regional position with high-thrust engines designed for warm-water salinity conditions.
Personal watercraft are motorized vessels typically under four meters in length, powered by inboard jet drives generating thrust through water impellers rather than propellers, with hull compositions ranging from fiberglass-reinforced polymer to lightweight composite materials engineered for planing efficiency in coastal and inland waterways. Sit-down models dominate commercial rental channels due to passenger stability and dual-rider capacity, while stand-up variants retain niche demand among racing enthusiasts in South African competitive circuits. Jet skis configured for rescue operations command premium positioning within government agency procurement frameworks across the region.
UAE's maritime regulator enforces stability and emissions standards that shape product certification requirements for commercial operators throughout Gulf markets. South Africa's national maritime safety authority mandates operator licensing and vessel registration that filter informal sellers from legitimate distribution channels. Egypt's Suez Canal Authority coordinates coastal zone management policies affecting marina development permissions along Red Sea governorates. Stakeholders must monitor evolving certification reciprocity agreements between Gulf and North African jurisdictions to optimize regional distribution strategies.
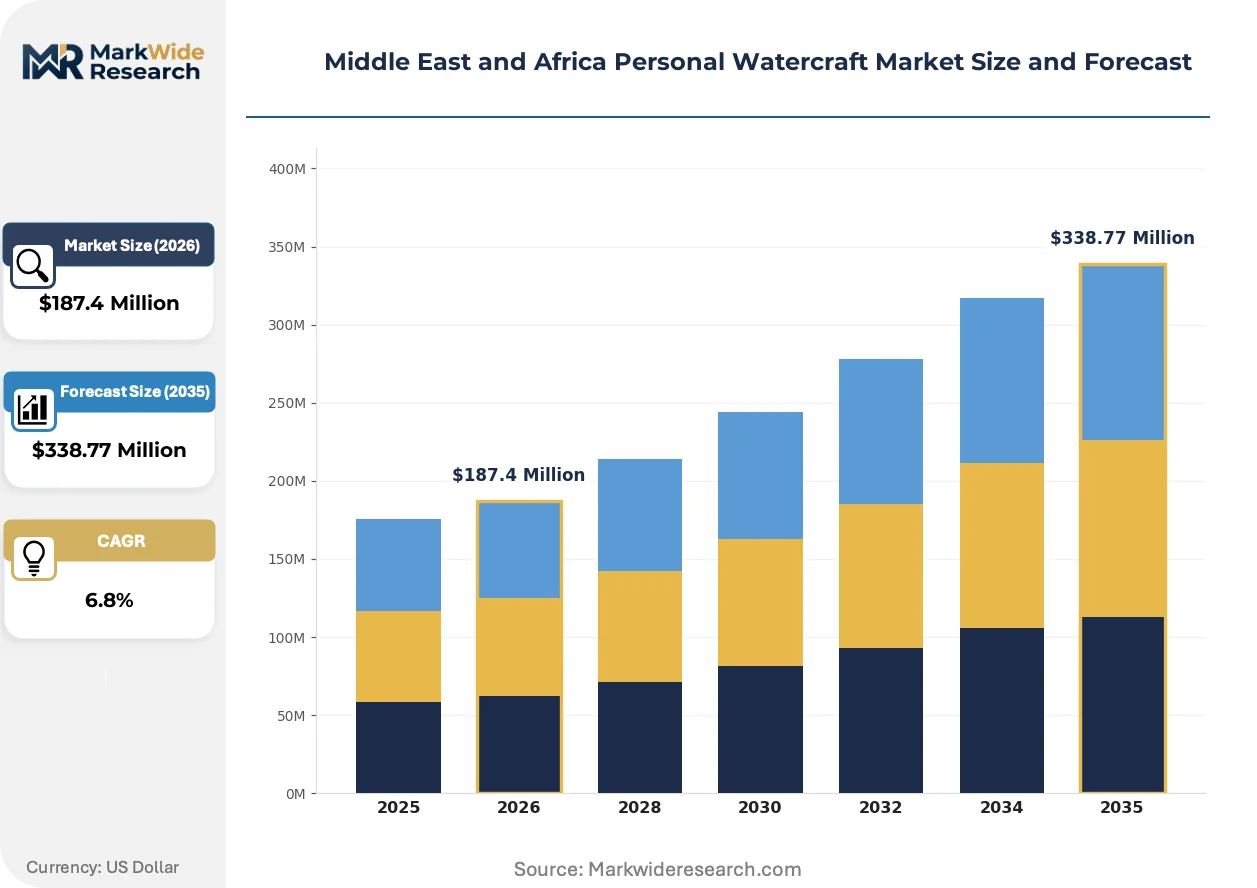
Market Dynamics
Marine tourism operators across the Red Sea corridor are accelerating fleet replacement cycles as UAE stability mandates force early retirement of non-compliant rental units, compressing procurement timelines and reshaping vendor qualification criteria.
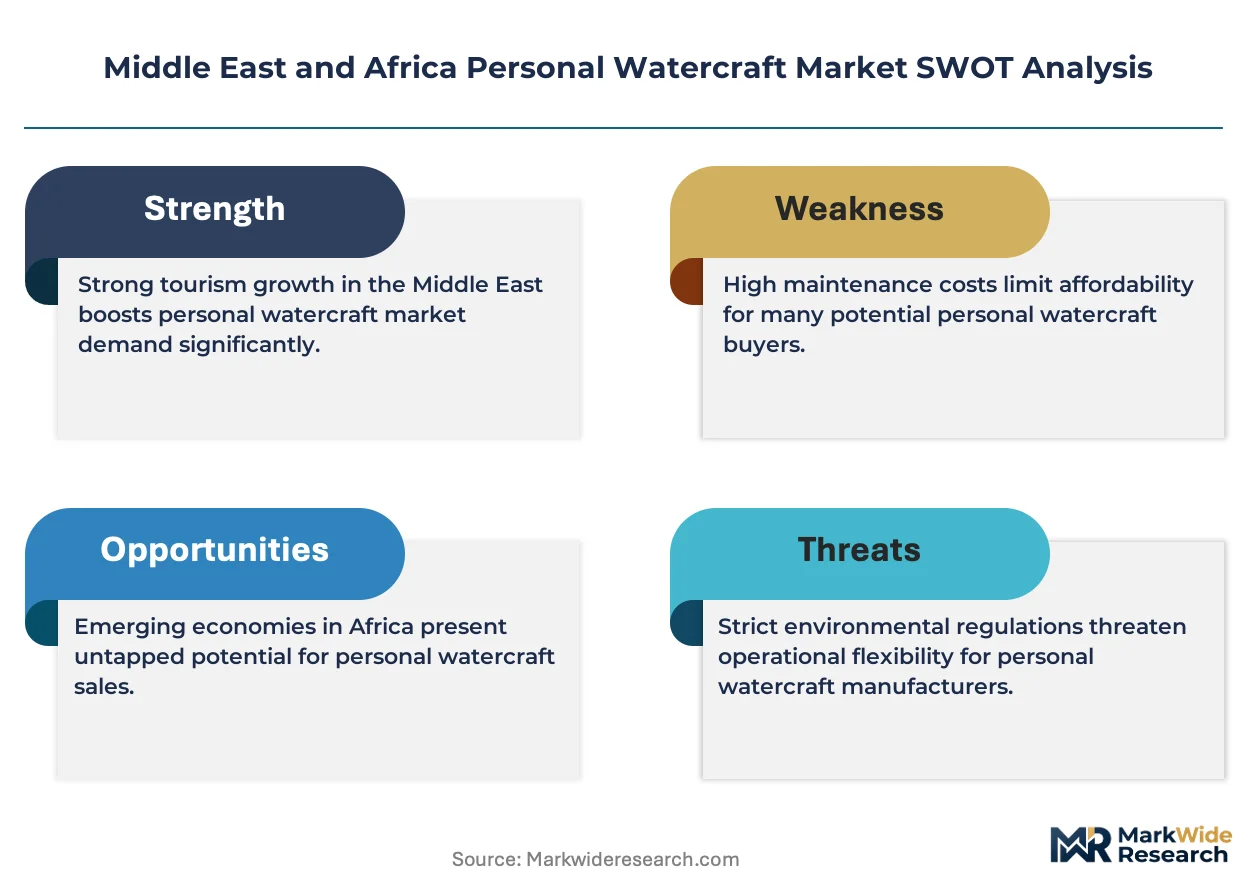
Growth Catalysts
- MOHAP Stability Certification:UAE's enhanced maritime safety framework mandates upgraded hull design standards for commercial operators, forcing fleet modernization across Gulf rental channels.
- Red Sea Resort Development:Coastal infrastructure expansion in Egyptian governorates generates sustained procurement demand from marine tourism operators seeking dual-rider capacity vessels.
- Sit-Down Configuration Dominance:Passenger stability requirements in commercial rental applications displace stand-up variants from mainstream fleet procurement.
Market Restraints
- Composite Material Cost Volatility:Fiberglass-reinforced polymer and lightweight hull composites face input price pressure from petrochemical feedstock fluctuations.
- Engine Supply Concentration:High-thrust powertrain sourcing concentrates among Japanese and North American suppliers, creating procurement bottlenecks for regional distributors.
- Warm-Water Salinity Degradation:Corrosion acceleration in Red Sea and Gulf operating environments compresses component lifecycles and elevates maintenance burdens.
Strategic Opportunities
- Western Cape Private Investment:South Africa's coastal recreation infrastructure attracts sustained capital deployment from high-net-worth buyers seeking personal ownership models.
- Rescue Configuration Premium Positioning:Government agency procurement frameworks across Gulf and North African jurisdictions create specialized demand for jet ski emergency response platforms.
- Marina Development Permissions:Egypt's Suez Canal Authority coordinates coastal zone management policies that unlock new berthing capacity along underdeveloped Red Sea governorates.
Industry Challenges
- Operator Licensing Compliance:South Africa's national maritime safety authority mandates vessel registration and certified training that filter informal sellers from legitimate distribution channels.
- Certification Reciprocity Fragmentation:Divergent stability and emissions standards between Gulf and North African jurisdictions complicate regional distribution strategies for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Personal Watercraft Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Skis, Stand-Up Models, Sit-Down Models, Touring Watercraft Application: Recreational Use, Racing, Rescue Operations, Rentals End User: Private Owners, Rental Operators, Marine Tourism, Government Agencies Distribution Channel: Online Sales, Dealerships, Boat Shows, Rental Outlets |
| Companies Covered | BRP Inc., Yamaha Motors, Kawasaki Motors Corporation, Polaris Industries, Honda Motors, Zodiac Nautic, Sea-Doo, Avon Marine, Gibbs Sports Amphibians, Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Personal Watercraft Market Shifts & Advancements
Propulsion efficiency and regulatory compliance are converging to redefine product architecture across Middle East and Africa personal watercraft procurement, with warm-water operating conditions dictating material and engineering priorities.
Closed-loop cooling systems engineered for elevated salinity environments are rewriting durability expectations for commercial rental fleets. Red Sea tour operators in Egyptian coastal governorates are specifying these configurations as standard procurement requirements. The technology is compressing maintenance intervals and extending hull service life in corrosive operating conditions.
MOHAP's enhanced stability certification framework is mandating hull redesigns that exceed baseline international standards. Commercial operators throughout UAE and Gulf Cooperation Council states must now demonstrate enhanced passenger protection through third-party testing protocols. The regulation is elevating entry barriers for uncertified suppliers while rewarding established manufacturers with pre-approved product portfolios.
Marine tourism buyers are consolidating procurement decisions under centralized fleet management structures. Large-scale resort operators across Red Sea and Gulf destinations are displacing fragmented local purchasing with direct manufacturer relationships. This concentration is most visible in UAE and Saudi Arabia where integrated hospitality groups control multi-property water sports concessions.
Middle East and Africa Personal Watercraft Market Segmentation
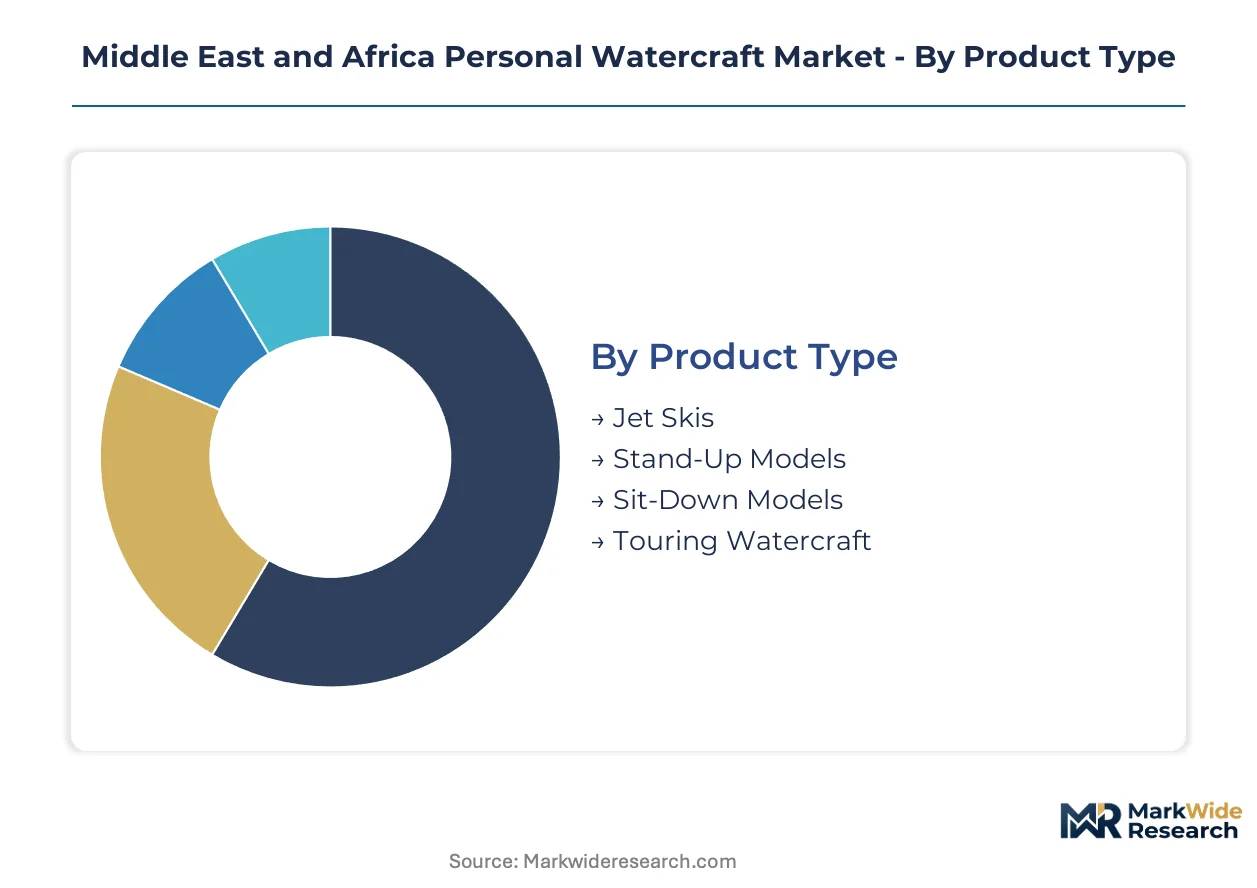
Fleet replacement cycles across Red Sea marine tourism corridors are fragmenting demand into distinct procurement tiers. Each segment category carries specific certification and operational requirements that reshape vendor qualification criteria across Gulf and North African markets.
Product Type:
Upgrade timelines compress as UAE stability mandates force early retirement of non-compliant hull designs, accelerating procurement across all configurations.
- Jet Skis:Compact recreational vessels with inboard jet drives generating thrust through water impellers rather than propellers. Red Sea rental operators in Egyptian governorates specify these for high-frequency daily deployment due to maneuverability in congested marina environments.
- Sit-Down Models:Dual-rider capacity vessels with enhanced passenger stability through wider hull geometry and lower center of gravity. UAE commercial operators under MOHAP certification requirements now mandate these configurations exclusively, displacing stand-up variants from fleet procurement.
- Stand-Up Models:Single-rider athletic configurations retaining niche demand in South African competitive racing circuits.
- Touring Watercraft:Extended-range vessels with larger fuel capacity and ergonomic seating for multi-hour Red Sea coastal routes.
Sit-Down Models sit at the top of the volume ranking, with Touring Watercraft climbing the fastest as extended-route tourism expands.
Application:
Cost tier differentiation separates premium-configured government procurement from standardized commercial rental specifications.
- Recreational Use:Private ownership applications concentrated in South Africa's Western Cape province where high-net-worth buyers prioritize performance specifications over rental durability requirements.
- Rentals:High-utilization commercial deployment demanding corrosion-resistant materials and simplified maintenance protocols for warm-water salinity conditions. Egyptian Red Sea resort operators specify closed-loop cooling systems as standard for this channel.
- Rescue Operations:Specialized configurations with emergency lighting, rescue sleds, and enhanced stability for government agency procurement across Gulf jurisdictions.
- Racing:Competition-tuned engines and lightweight composite hulls for organized circuit events.
Rentals command the highest procurement volume, while Rescue Operations gain share fastest as maritime safety agencies modernize emergency response fleets.
End User:
Customer type concentration shifts toward centralized fleet management structures among integrated hospitality groups.
- Rental Operators:Multi-unit procurement decisions consolidated under professional fleet managers replacing fragmented local purchasing. Saudi Arabian integrated resort groups now control water sports concessions across multiple properties.
- Marine Tourism:Red Sea corridor operators accelerating replacement cycles amid coastal resort development in Egyptian governorates.
- Private Owners:Individual buyers in South Africa's coastal recreation infrastructure seeking personal ownership models.
- Government Agencies:Emergency response and maritime patrol units across Gulf Cooperation Council states specifying rescue-configured platforms.
Rental Operators dominate procurement volume, with Marine Tourism expanding most quickly as Red Sea infrastructure investment accelerates.
Distribution Channel:
Supply concentration favors established dealership networks with parts availability and service coverage across dispersed coastal markets.
- Dealerships:Authorized service centers with certified technicians and genuine parts inventory. Gulf Cooperation Council states rely on these for MOHAP compliance documentation and warranty support.
- Boat Shows:Annual exhibitions in Dubai and Johannesburg concentrating multi-brand comparison for fleet buyers.
- Online Sales:Digital configuration tools with limited penetration due to inspection requirements for commercial certification.
- Rental Outlets:Direct manufacturer relationships for large-scale resort operators displacing intermediary distribution.
Dealerships maintain the highest transaction volume, with Boat Shows gaining traction fastest as fleet procurement consolidates under centralized decision-making.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red Sea coastal corridor anchors procurement concentration across the Middle East and Africa Personal Watercraft Market, with Egyptian resort development and UAE regulatory mandates driving fleet replacement cycles. Marine tourism infrastructure expansion in Saudi Arabia and South Africa's Western Cape province generates parallel demand vectors for commercial rental and private ownership segments.
United Arab Emirates
MOHAP's enhanced stability certification framework forces early retirement of non-compliant rental fleets across Dubai and Abu Dhabi coastal concessions. The maritime safety regulator mandates third-party hull testing that elevates entry barriers for uncertified suppliers. Integrated hospitality groups in the emirates now consolidate multi-property water sports procurement under centralized fleet management structures.
Saudi Arabia
Red Sea coastal development in the Western Region generates sustained demand for dual-rider capacity vessels from marine tourism operators. The General Authority for Maritime Affairs coordinates berthing permissions that unlock new marina capacity along underdeveloped governorates. NEOM project contractors specify closed-loop cooling systems for extended-range touring configurations in warm-water salinity conditions.
Egypt
Resort operators in South Sinai and Red Sea governorates accelerate fleet replacement amid coastal infrastructure expansion. The Suez Canal Authority coordinates coastal zone management policies affecting marina development permissions. Hurghada and Sharm el-Sheikh marine tourism clusters specify sit-down configurations exclusively for high-frequency daily deployment.
South Africa
Western Cape coastal recreation infrastructure attracts sustained private investment from high-net-worth buyers seeking personal ownership models. The national maritime safety authority mandates operator licensing and vessel registration that filter informal sellers from legitimate distribution channels. Cape Town and Garden Route municipalities anchor competitive racing circuit demand for stand-up configurations.
Middle East and Africa Personal Watercraft Market Competitive Landscape
Portfolio diversification dominates the current landscape as established manufacturers extend product ranges to capture rescue configuration premiums and extended-range touring demand. The vendor base concentrates around Japanese and North American powertrain suppliers with pre-certified hull designs for MOHAP compliance. Three archetypes define competitive positioning: integrated marine powertrain specialists, diversified recreational vehicle conglomerates, and regional distribution-focused assemblers. Strategic moves center on dealership network densification in Gulf Cooperation Council states and direct manufacturer relationships with consolidated hospitality groups.
Among diversified recreational vehicle manufacturers, BRP Inc., Yamaha Motors, and Kawasaki Motors Corporation occupy positions shaped by warm-water operating requirements and regulatory certification frameworks. BRP Inc. exemplifies the extended-range touring specialist archetype through Red Sea route optimization. Yamaha Motors anchors the established dealership network model across Gulf markets with genuine parts availability and service coverage. Kawasaki Motors Corporation represents the high-thrust powertrain engineering tier with configurations engineered for elevated salinity degradation resistance.
| Leading Market Players |
|---|
| BRP Inc. |
| Yamaha Motors |
| Kawasaki Motors Corporation |
| Polaris Industries |
| Honda Motors |
| Zodiac Nautic |
| Sea-Doo |
| Avon Marine |
| Gibbs Sports Amphibians, Inc. |
| Others |
Supply & Pricing Matrix
MOHAP's enhanced stability certification mandates for commercial rental fleets are compressing procurement timelines and forcing supply chains to prioritize pre-certified hull designs from established manufacturers, which elevates pricing power for compliant vendors while squeezing margins on uncertified inventory.
Pricing Analysis
Petrochemical feedstock volatility in fiberglass-reinforced polymer inputs passes through to hull manufacturing costs, with pricing stratifying across MOHAP-certified premium tiers, standard commercial rental specifications, and uncertified economy alternatives. Price differentiation hinges on certification grade and volume scale, with large-scale resort operators extracting favorable terms through consolidated fleet procurement. Cost compression in the economy tier is intensifying as informal sellers face exclusion from UAE and Saudi Arabian commercial channels. Marine tourism operators demonstrate lowest price sensitivity due to regulatory compliance imperatives, while individual private owners in South Africa's Western Cape exhibit highest elasticity.
Supply Chain Analysis
Maritime freight costs from Japanese and North American powertrain suppliers concentrate procurement risk for regional distributors serving Gulf Cooperation Council markets. Manufacturing draws from Japan, USA, and Canada for high-thrust engines, with hull fabrication tethered to fiberglass composite suppliers in China and Southeast Asia. Single-source vulnerability in warm-water salinity-resistant cooling system components elevates exposure to supply interruptions. Distribution runs through authorized dealership networks with certified technicians across dispersed Red Sea and Gulf coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where fleet replacement cycles and regulatory upgrading are concentrating procurement around premium-certified specifications, rewarding manufacturers with pre-approved MOHAP portfolios.
For Market Incumbents: Deepen backward integration into corrosion-resistant cooling system components to secure supply continuity against Japanese supplier concentration. Expand certified service capacity in Saudi Arabian Western Region governorates to capture NEOM project procurement. Anchor position through exclusive supply agreements with consolidated hospitality groups displacing fragmented rental channels.
For New Entrants and Emerging Players: Begin with rescue configuration platforms for government agency procurement across Gulf jurisdictions, where specialized specifications and limited certified competition create accessible entry points. Target Egyptian Red Sea governorates for marina development-linked fleet deployment. Establish direct manufacturer relationships with emerging resort operators bypassing established dealership networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional assemblers possessing MOHAP pre-certification and established Suez Canal Authority coordination relationships. Long-term viability favors entities with durable positioning in closed-loop cooling technology and warm-water salinity engineering capabilities. Monitor Egyptian coastal infrastructure investment commitments as the inflection signal for Red Sea corridor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Certification Investment | Pre-approved hull designs unlock UAE and Saudi commercial rental procurement channels. |
| Closed-Loop Cooling System Development | Salinity-resistant configurations command premium positioning in Red Sea tour operator specifications. |
| Direct Resort Operator Relationships | Bypassing dealership intermediaries captures margin from consolidated hospitality group procurement. |
| Rescue Platform Specialization | Government agency frameworks across Gulf jurisdictions create defensible niche demand. |
| Western Cape Service Network Expansion | South African private ownership concentration rewards localized aftermarket presence. |
Research Methodology
Multiple input streams — structured interviews with marine tourism fleet managers, primary discussions with UAE maritime safety regulators, and secondary validation through customs trade data and hospitality group procurement disclosures — were reconciled to construct demand estimates across the analysis window. Conversations encompassed resort operators in Egyptian Red Sea governorates, Saudi Arabian Western Region development contractors, South African coastal recreation infrastructure investors, and authorized dealership principals in Gulf Cooperation Council states. Bottom-up vessel deployment counts were triangulated against top-down hospitality sector capital expenditure tracking.
Historical fleet replacement patterns were cross-referenced against panel input from procurement directors at integrated resort groups to model adoption trajectories across the projection horizon. Segmentation dimensions encompassed product configuration, application use-case, end-user archetype, and distribution channel structure. CAGRs were derived from regression analysis of procurement volume against coastal infrastructure investment indicators and regulatory compliance deadline schedules. Warm-water salinity degradation rates and closed-loop cooling system penetration assumptions informed durability-adjusted fleet sizing estimates.
Caveats apply where Egyptian marina development permissions, Saudi Arabian berthing capacity approvals, or MOHAP certification reciprocity agreements with North African jurisdictions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Motorized Quadricycle Market