
 Recreational Boating Market | 2026-2036
Recreational Boating Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Boating Market Analysis
A capital-intensity divergence between integrated hull manufacturers and outsourced assemblers is bifurcating competitive returns in recreational boating. Brunswick Corporation leverages captive engine production through Mercury Marine to sustain margin control across the sterndrive and outboard segments. Groupe Beneteau anchors its position through vertical manufacturing of sailing yachts and powerboats across French and Polish production facilities. Yamaha Motor Co., Ltd. dominates personal watercraft through proprietary jet propulsion technology and dense dealer networks in coastal United States markets.
Recreational boating encompasses the design, manufacture, and sale of vessels intended for non-commercial leisure use, with hull construction ranging from hand-laid fiberglass to vacuum-infused carbon fiber composites engineered for hydrodynamic efficiency and weight reduction. The primary commercial purpose centers on enabling leisure cruising, fishing, waterskiing, and sailing activities for private owners and charter operators. Motorboats occupy the largest revenue pool due to higher unit values and broader family accessibility, while electric and hybrid fuel types represent the fastest-growing structural segment as marina infrastructure expands charging capabilities. Yachts command premium margin concentration through semi-custom production and extended build cycles.
The United States Coast Guard enforces construction and safety standards under federal boating regulations, while the EPA administers marine engine emissions limits that manufacturers must satisfy for market access. European builders navigate CE marking requirements and the EU Green Deal's decarbonization timeline for recreational craft. Stakeholders must monitor battery energy density improvements and shore power infrastructure buildouts to assess when electric propulsion crosses threshold viability for extended cruising applications.
Market Dynamics
Electric propulsion technology is forcing a fundamental recalibration of hull design priorities as battery weight distribution and thermal management reshape hydrodynamic engineering conventions across the recreational boating sector.
Growth Catalysts
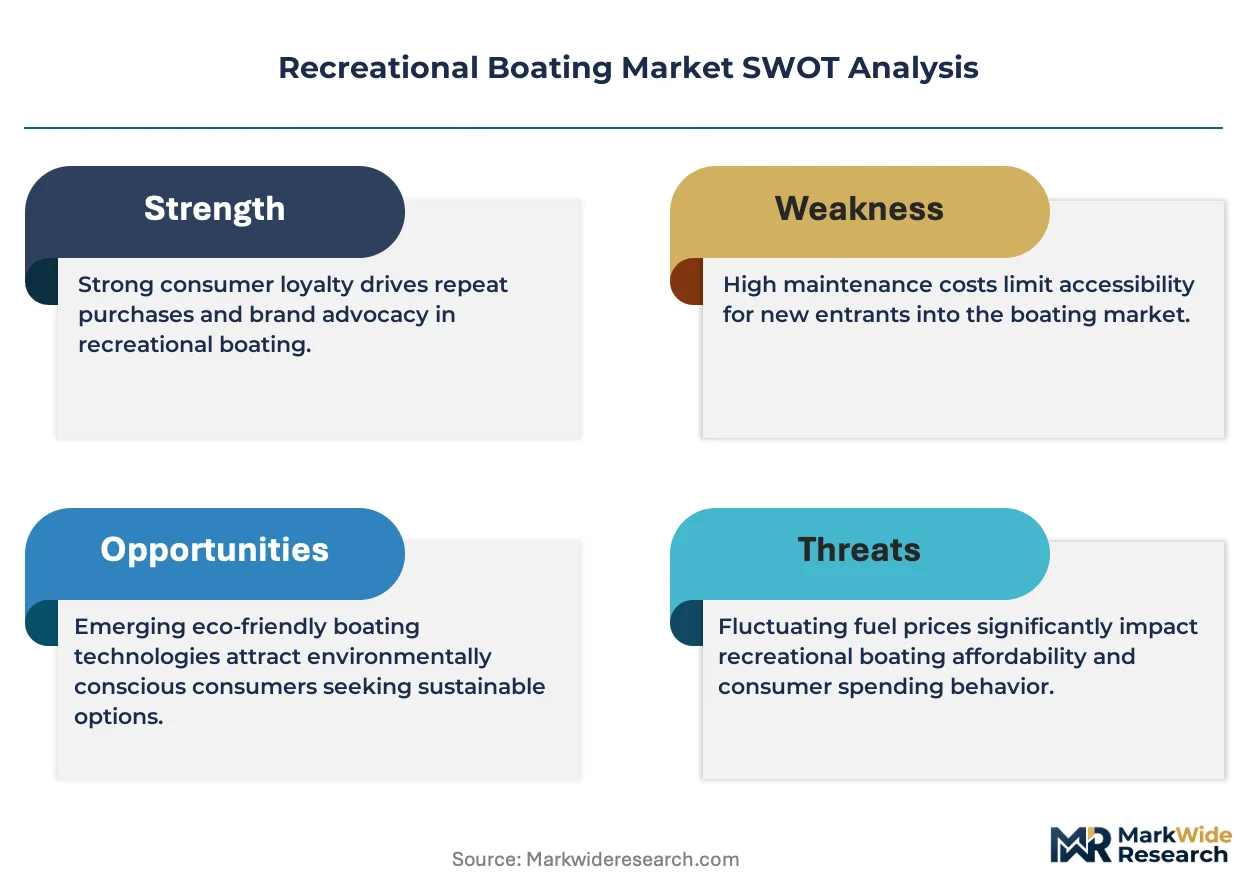
- EU Green Deal Decarbonization Timeline:The EU Green Deal mandates progressive emissions reductions for recreational craft, compelling manufacturers to accelerate electric and hybrid development programs to maintain market access across Mediterranean coastal states.
- Marina Charging Infrastructure Expansion:Shore power installations at ports in France, Italy, and Spain are multiplying, enabling extended cruising ranges that previously constrained electric vessel adoption among weekend boaters.
- Polymer Matrix Composites:Vacuum-infused carbon fiber manufacturing processes are reducing hull weights by substantial margins, improving power-to-weight ratios and extending battery range for electric propulsion systems.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Raw material price fluctuations for cathode minerals constrain electric vessel pricing flexibility, compressing margins for builders targeting mid-market family segments.
- Outboard Engine Supply Concentration:Mercury Marine and Yamaha Motor command dominant positions in North American sterndrive and outboard supply, creating procurement bottlenecks for independent hull assemblers.
- Energy Density Limitations:Current battery chemistry delivers insufficient kilowatt-hour capacity for multi-day offshore cruising, restricting electric propulsion to day-boat and harbor-cruise applications.
Strategic Opportunities
- Inland Waterway Electrification in Germany:The Rhine-Main-Danube corridor lacks comprehensive electric vessel penetration, presenting first-mover advantages for builders establishing charging partnerships with municipal port authorities.
- Peer-to-Peer Charter Platforms:Digital rental marketplaces are fragmenting traditional dealer-based distribution, enabling direct owner-to-consumer revenue streams that bypass conventional brokerage channels.
- Photovoltaic-Hybrid Convergence:Integrated solar panel arrays combined with battery storage systems are creating self-sustaining auxiliary power for sailing yachts, reducing generator dependency during extended anchorage.
Industry Challenges
- Composite Technician Scarcity:Vacuum infusion and resin transfer molding expertise remains concentrated among aging workforces in French and Italian shipyards, constraining production scaling for premium hull manufacturers.
- CE Marking Certification Timelines:European notified body backlogs extend recreational craft approval cycles by 8-14 months, delaying new model launches and compressing effective selling seasons.
- Legacy Hull-Engine Integration Complexity:Retrofitting conventional fiberglass hulls originally engineered for internal combustion with electric drivetrains requires structural reinforcement that compromises weight targets and stability calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Boating Market |
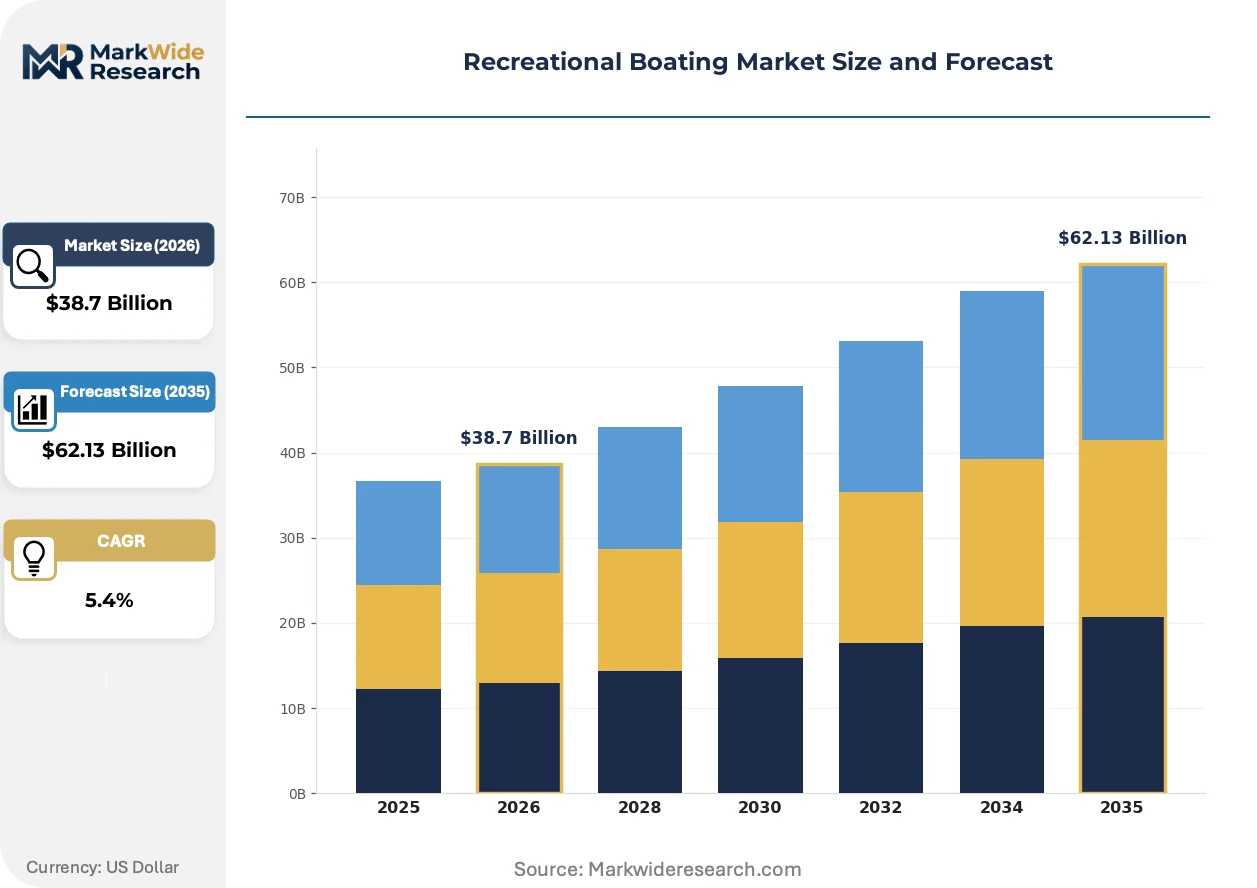
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yachts, Sailboats, Motorboats, Personal Watercraft End User: Families, Tourists, Fishing Enthusiasts, Water Sports Participants Application: Leisure Cruising, Fishing, Waterskiing, Sailing Fuel Type: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | Brunswick Corporation, Yamaha Motor Co., Ltd., Groupe Beneteau, Azimut Benetti Group, Ferretti Group, Malibu Boats, MasterCraft Boat Holdings, Bavaria Yachtbau, Bombardier Recreational Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Boating Market Emerging Trajectories
Propulsion electrification is rewriting vessel architecture fundamentals as powertrain placement shifts from stern-mounted engines to distributed battery banks, demanding new competencies in thermal engineering and electrical systems integration.
Solid-state battery chemistry is displacing conventional lithium-ion configurations in premium electric day-cruiser development. Scandinavian builders are adopting these energy-dense cells for 40-foot cabin cruisers intended for archipelago hopping. The technology is displacing range anxiety as the primary purchase barrier among affluent coastal owners in Norway and Sweden.
The EPA's updated marine engine emissions standards under the Clean Air Act are tightening hydrocarbon and nitrogen oxide limits for outboard motors above 115 horsepower. Manufacturers must certify new powertrains through expanded test cycles that simulate variable load conditions. Sterndrive and inboard segments face disproportionate compliance costs, accelerating exits from the mid-displacement family cruiser category.
Subscription-based vessel access models are fragmenting traditional ownership patterns among younger demographic cohorts. Fractional membership programs at Lake Tahoe and Chesapeake Bay marinas are replacing outright purchase for entry-level buyers seeking seasonal flexibility. Coastal United States markets exhibit the fastest penetration, with Florida and California operators consolidating fleet assets to serve dispersed member bases.
Recreational Boating Market Segmentation
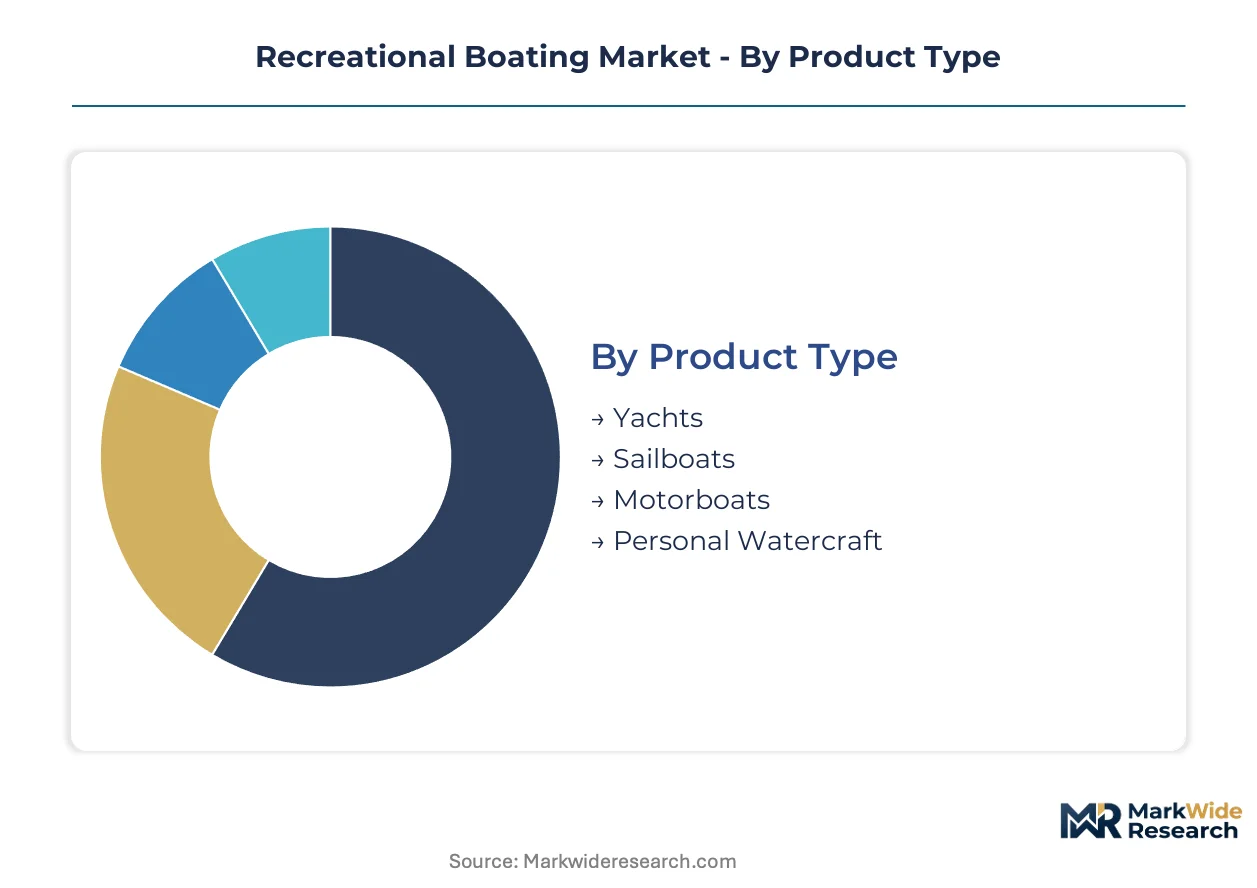
Segmentation in recreational boating reveals how margin pools shift between hull architecture complexity and propulsion technology maturity. Builders prioritize product mix across these dimensions to defend profitability against regulatory and materials cost pressures.
Product Type:
Motorboats command the largest absolute margin pool through higher unit values and volume accessibility, while yachts concentrate premium returns through extended production cycles and customization premiums.
- Motorboats:Fiberglass and aluminum hull configurations dominate family cruising and fishing applications across the Great Lakes and coastal United States. Demand clusters around sterndrive and outboard configurations that balance performance with marina storage constraints.
- Yachts:Semi-custom production with vacuum-infused composite construction yields extended build cycles and substantial pre-delivery revenue recognition. Mediterranean charter operators in France and Italy anchor demand for 40-60 foot cabin cruisers with crew accommodations.
- Sailboats:Keelboat and catamaran configurations serve coastal cruising and racing communities concentrated in French Atlantic shipyards and New England harbors.
- Personal Watercraft:Jet propulsion technology enables compact hull designs for individual operators seeking waterskiing tow capacity and shallow-water maneuverability in Florida and California coastal zones.
The dominant share belongs to Motorboats, while Yachts is closing the gap fastest through premium pricing power in Mediterranean markets.
End User:
Volume concentration follows seasonal recreation patterns, with family segments driving consistent replacement demand and fishing enthusiasts commanding specialized equipment premiums.
- Families:Multi-console bowriders and deck boats prioritize passenger capacity and swim platform accessibility for day-cruising in Chesapeake Bay and Lake Michigan. Marinas report peak seasonal utilization correlating with school vacation calendars.
- Fishing Enthusiasts:Center-console hulls with livewell systems and outrigger mounts target offshore trolling and bottom-fishing in the Gulf of Mexico and Pacific Northwest. Electronics integration for sonar and chart plotting represents substantial aftermarket attachment.
- Tourists:Charter fleet operators in the Greek Islands and Croatian Adriatic source sailing yachts and motor cruisers for weekly bareboat rentals with seasonal crew employment.
- Water Sports Participants:Wakeboard tower installations and ballast systems drive specialized inboard propulsion demand for slalom and wake surfing in inland reservoirs across Texas and Arizona.
Families retain the largest participation base, though Fishing Enthusiasts is expanding most quickly through tournament organization and specialized media programming.
Application:
Activity-based segmentation determines hull form optimization and equipment specification, with leisure cruising requiring maximum layout flexibility.
- Leisure Cruising:Cabin cruisers and express yachts emphasize overnight accommodations with galley and head facilities for coastal island-hopping in the Balearics and Florida Keys. Range and seakeeping comfort dominate specification priorities.
- Fishing:Tournament-grade center consoles integrate outboard quad-engine configurations for high-speed runs to offshore canyons. Rod storage, ice capacity, and fighting chair foundations define hull architecture.
- Waterskiing:Inboard direct-drive and V-drive propulsion systems generate tournament-caliber wake shapes through hull bottom design and engine placement aft of the transom.
- Sailing:Racing and cruising configurations diverge in keel depth, sail area displacement ratios, and interior volume allocation for offshore passages versus buoy-rounding performance.
Leisure Cruising maintains the broadest addressable base, while Fishing is gaining share fastest through specialized retail channel development.
Fuel Type:
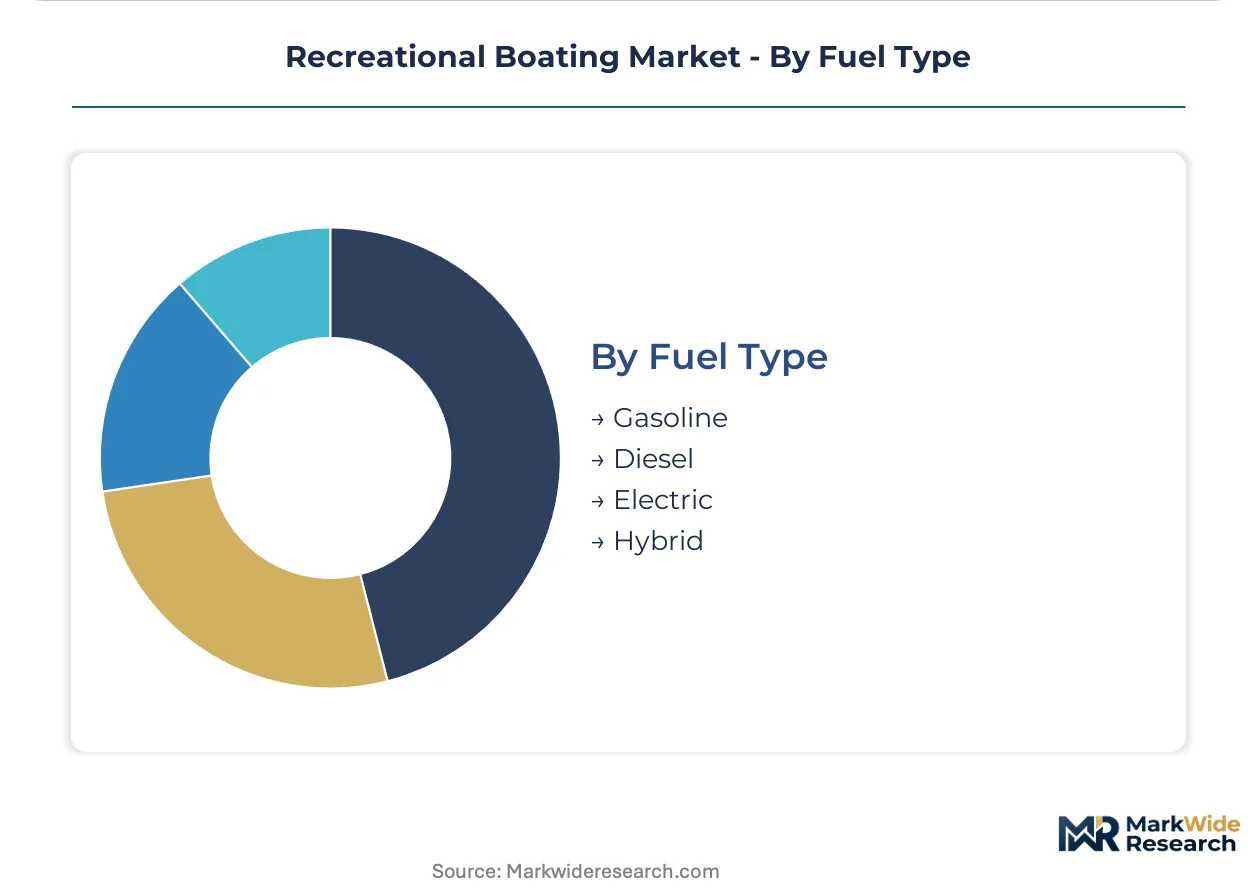
Regulatory pressure and infrastructure investment are restructuring propulsion economics, with electric systems capturing development resources despite current range constraints.
- Gasoline:Outboard and sterndrive engines from Mercury Marine and Yamaha Motor dominate the sub-300 horsepower segment through established dealer service networks and fuel dock availability. Carburetion and direct injection architectures face escalating EPA emissions compliance costs.
- Electric:Battery-electric propulsion systems with 50-150 kilowatt-hour capacity enable harbor cruising and day-boat operation in Scandinavian archipelagos where shore power infrastructure is dense. Solid-state chemistry adoption is extending range thresholds for premium builders.
- Diesel:Inboard shaft-drive configurations persist in displacement trawlers and sailing yacht auxiliaries where torque and fuel range outweigh emissions penalties.
- Hybrid:Serial and parallel architectures combining diesel generators with electric motors offer redundancy for offshore passages while enabling harbor electric-only operation under EU Green Deal incentives.
Gasoline retains installed base dominance, though Electric is climbing the fastest as marina charging networks expand across Mediterranean ports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium vessel pricing in Italy exceeds comparable French-built craft by substantial margins, while Great Lakes manufacturers in the United States command volume advantages through dense marina networks.
United States
Family cruising demand concentrates in Chesapeake Bay and Lake Michigan, where multi-console bowriders dominate seasonal replacement cycles. The EPA enforces marine engine emissions limits under the Clean Air Act, tightening hydrocarbon standards for outboard motors above 115 horsepower. Wisconsin and Tennessee host concentrated sterndrive and outboard engine production, supplying North American dealer networks.
Italy
Mediterranean charter operators anchor demand for 40-60 foot cabin cruisers with crew accommodations, generating extended build cycles and pre-delivery revenue recognition. CE marking requirements from European notified bodies extend recreational craft approval timelines by 8-14 months. The Adriatic shipyards of Lombardy and Tuscany specialize in vacuum-infused composite construction for semi-custom yacht production.
France
Sailing yacht and powerboat demand clusters in Atlantic and Mediterranean coastal markets, with vertical manufacturing across French and Polish production facilities. The EU Green Deal mandates progressive emissions reductions for recreational craft, compelling electric and hybrid development programs. Shipyards in the Vendée region concentrate vacuum infusion expertise for premium hull manufacturing.
Germany
Inland waterway cruising on the Rhine-Main-Danube corridor lacks comprehensive electric vessel penetration, presenting first-mover opportunities for charging partnerships. The KBA administers vessel registration and safety compliance for recreational craft operating on federal waterways. Bavarian and Baden-Württemberg marinas are expanding shore power installations to support harbor electric-only operation.
Sweden
Archipelago hopping generates demand for 40-foot electric cabin cruisers with solid-state battery configurations, displacing range anxiety among affluent coastal owners. Scandinavian builders are adopting energy-dense cells for premium day-cruiser development. Stockholm and Gothenburg marinas lead shore power infrastructure density, enabling extended cruising ranges for weekend boaters.
Recreational Boating Market Vendor Landscape
Concentration sits with integrated hull manufacturers and outsourced assemblers, creating a bifurcated structure where captive engine production sustains margin control against procurement-dependent competitors. Tier-one builders leverage vertical manufacturing across multiple production facilities, while mid-market assemblers face supply bottlenecks from concentrated outboard and sterndrive suppliers. Three archetypes dominate: integrated powertrain-hull manufacturers, premium semi-custom yacht builders, and volume-focused family cruiser assemblers. Competitive moves center on electric propulsion R&D partnerships and marina charging infrastructure alliances.
Among North American powerboat specialists, Brunswick Corporation and Malibu Boats exemplify divergent strategic positions, with the former representing integrated engine-hull manufacturing and the latter occupying the performance watersports segment. Yamaha Motor Co., Ltd. anchors the personal watercraft category through proprietary jet propulsion technology. Groupe Beneteau represents European vertical manufacturing breadth across sailing and powerboat categories.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Yamaha Motor Co., Ltd. |
| Groupe Beneteau |
| Azimut Benetti Group |
| Ferretti Group |
| Malibu Boats |
| MasterCraft Boat Holdings |
| Bavaria Yachtbau |
| Bombardier Recreational Products |
| Others |
Supply Flow & Price Mechanics
Fourteen-month CE marking approval cycles compress selling seasons and concentrate pricing power with vertically integrated hull manufacturers who absorb regulatory delays through captive production scheduling. This lead-time environment rewards builders with in-house composite manufacturing and penalizes outsourced assemblers facing procurement bottlenecks from concentrated engine suppliers.
Pricing Analysis
Configured-to-order pricing for semi-custom yachts commands spreads exceeding standard production motorboats through customization premiums and extended build-cycle revenue recognition. Three-tier pricing structure across premium, standard, and economy levels stratifies by hull construction method and propulsion certification tier. Cost compression in mid-market family segments intensifies because lithium-ion battery mineral volatility constrains electric vessel pricing flexibility. Charter operators and fractional membership buyers exhibit highest price sensitivity, while affluent coastal owners in Scandinavian archipelagos show least sensitivity to solid-state battery premiums.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for carbon fiber prepregs and marine-grade aluminum extrusions. Manufacturing gravity centers on Italy, France, and Poland for vacuum-infused composite hulls, with Wisconsin and Tennessee anchoring sterndrive and outboard engine production. Raw material dependencies rest on epoxy resin systems, cathode minerals for battery cells, and marine-grade 5083 aluminum sheet. Single-source vulnerability concentrates in Mercury Marine and Yamaha Motor outboard supply. Distribution runs through dealer networks for family cruisers and direct charter fleet sales for Mediterranean yacht builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through EPA emissions certification and CE marking approval timelines creates defensive moats for established hull manufacturers with existing regulatory relationships.
For Market Incumbents: Shield market position by deepening backward integration into battery energy management systems and expanding captive composite production capacity in Polish facilities. Mercury Marine and Yamaha Motor engine supply concentration poses substitution risk from emerging electric drivetrain specialists. Prioritize certification investment for solid-state battery configurations ahead of EU Green Deal phase-in timelines. For New Entrants and Emerging Players: CE marking fast-track partnerships with French and Italian notified bodies unlock 8-14 month approval timeline compression versus standard submission queues. White-space concentration sits in Rhine-Main-Danube inland waterway electrification and peer-to-peer charter platform infrastructure. Target German municipal port authority charging partnerships as the most penetrable geography. Pursue direct-to-consumer digital rental marketplace routes bypassing legacy dealer networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric propulsion R&D programs as battery chemistry development and thermal engineering competencies displace traditional mechanical engineering skill bases. Long-term viability favors builders with demonstrated marina charging infrastructure alliances and solid-state battery supply agreements. Acquisition target archetype: mid-market hull assemblers with established CE marking relationships and scalable vacuum infusion capacity. Monitor shore power installation density at Mediterranean ports as inflection indicator for electric vessel addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Marina Charging Infrastructure Partnership | Shore power density at French and Italian ports directly enables extended cruising range for electric day-boats. |
| Solid-State Battery Supply Agreement | Energy-dense cell procurement from Scandinavian suppliers displaces range anxiety among affluent coastal owners. |
| CE Marking Fast-Track Certification | European notified body relationship compression accelerates new model launch timing by 8-14 months. |
| Backward Integration into Composite Manufacturing | Captive vacuum infusion capacity in Polish facilities insulates margin control from resin price volatility. |
| Peer-to-Peer Charter Platform Launch | Digital rental marketplace routes fragment traditional dealer-based distribution for weekend boaters. |
Methodological Framework
A spread of perspectives from hull manufacturing executives, marina operations directors, marine engine procurement leads, and charter fleet managers converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from EPA emissions filings, EU notified body approval databases, customs trade records for carbon fiber imports, and SEC disclosures from publicly traded boat manufacturers. Bottom-up vessel production estimates triangulated against top-down marina utilization surveys.
Segmentation dimensions modeled include hull architecture type, propulsion technology maturity, end-user recreation pattern, and regional regulatory cluster across the projection horizon. CAGRs derived from historical production volume trajectories, replacement cycle analysis, and infrastructure investment correlation with electric vessel adoption rates. Forecast inputs incorporated battery energy density improvement curves and shore power installation timelines at Mediterranean ports.
Underlying assumptions cover stable lithium-ion mineral supply chains and progressive EU Green Deal enforcement, with deviation risk concentrated in battery chemistry breakthrough timing and marina infrastructure funding allocation. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
United States Luxury Yacht Market