
 Global Recreational Vehicle (RV) Market | 2026-2036
Global Recreational Vehicle (RV) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recreational Vehicle (RV) Market Outlook
Adventure seekers is rotating toward the center of RV demand as younger buyers prioritize experiential travel over traditional vacation formats. Thor Industries leverages extensive brand portfolio breadth to capture this demographic shift across multiple price tiers. Winnebago Industries anchors its position through manufacturing scale and direct-to-consumer digital channels. Forest River competes aggressively on volume production across towable categories.
A recreational vehicle constitutes a motorized or towable living quarters unit engineered for temporary habitation, typically incorporating integrated electrical systems, plumbing, climate control, and sleeping accommodations within a chassis-rated structure. Primary commercial purpose centers on mobile leisure accommodation for tourism, seasonal migration, and outdoor recreation activities. Motorhomes command the largest value share due to integrated drivetrain complexity and premium pricing tiers, while electric fuel type variants represent the fastest-emerging segment as battery energy density improvements enable viable range for Class B configurations. Towable RVs sustain dominant unit volumes across entry-level family segments where tow vehicle compatibility expands addressable demand.
EPA emissions protocols in the United States and EU Green Deal mobility directives in Europe are tightening compliance thresholds for internal combustion RV platforms, accelerating electrification roadmaps among established manufacturers. NHTSA vehicle safety standards govern structural integrity, braking performance, and occupant protection requirements that shape design engineering priorities and certification timelines. Stakeholders must monitor battery supply chain localization policies and charging infrastructure deployment curves as decisive variables for electric RV segment viability.
Market Dynamics
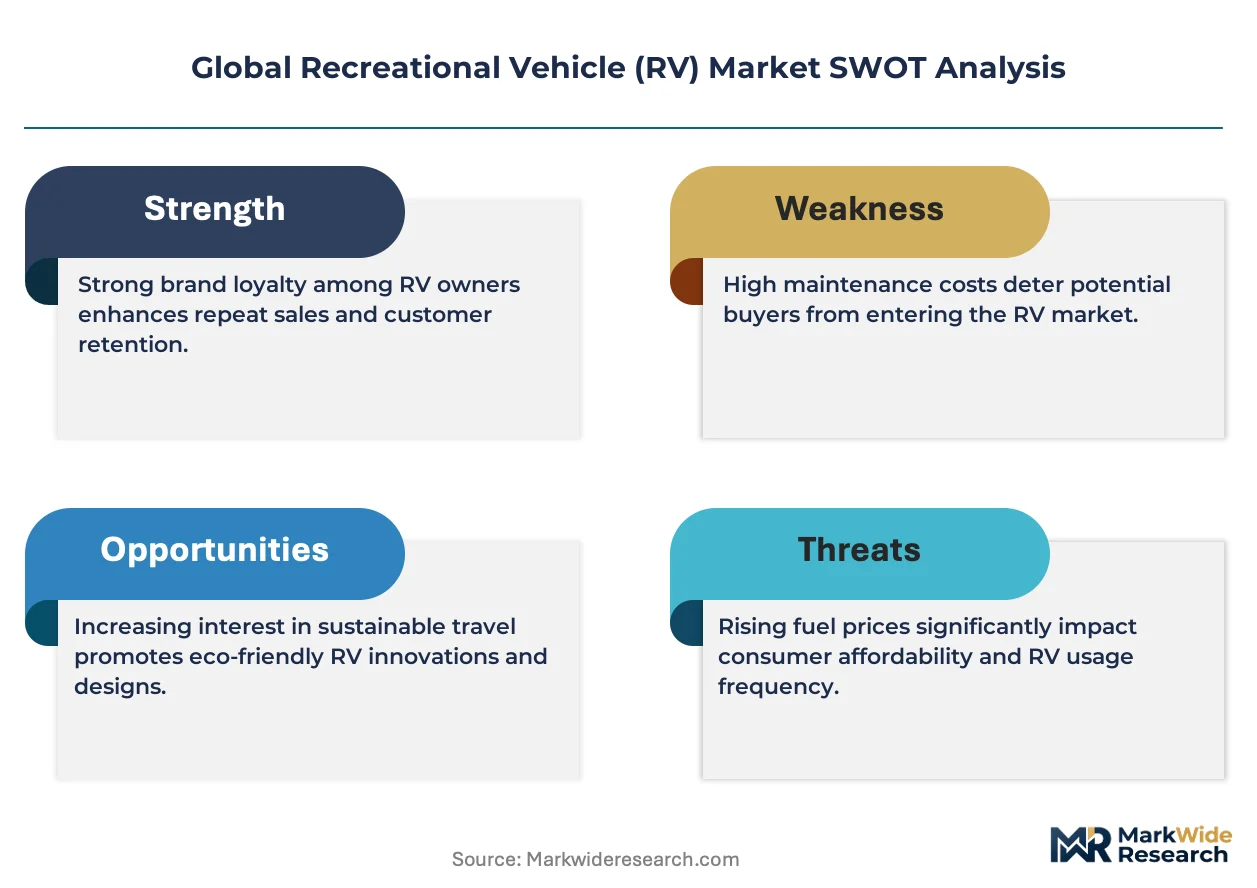
Electrification roadmaps are forcing drivetrain reengineering across motorhome platforms as battery energy density thresholds cross viability for Class B configurations, while EPA Phase 3 emissions standards compress compliance timelines for internal combustion chassis suppliers.
Growth Catalysts
- Aging Demographics:Retirees across the United States, Germany, and Japan are prioritizing mobile leisure lifestyles, expanding the addressable buyer base for premium motorhome configurations with integrated living systems.
- EU Green Deal Mobility Directives:These frameworks are mandating fleet decarbonization timelines that accelerate manufacturer investment in electric RV prototyping and charging infrastructure partnerships.
- Highway Connectivity Expansion:National park infrastructure investments in the United States and scenic route development in Norway and New Zealand are extending viable travel corridors for extended RV itineraries.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode material processing and cell manufacturing cluster in China, creating geopolitical exposure for battery-dependent electric RV production ramps.
- Chassis Cost Inflation:Heavy-duty truck platform shortages and steel price volatility are compressing gross margins for motorhome assemblers dependent on third-party drivetrain supply.
- Range Physics Constraints:Energy density limitations in current lithium-ion chemistries restrict viable electric RV configurations to Class B van conversions, excluding larger Class A motorhomes from near-term electrification.
Strategic Opportunities
- Underpenetrated Nordic Markets:Sweden and Finland exhibit low RV ownership rates relative to outdoor recreation participation, presenting whitespace for compact, thermally efficient towable designs.
- Vehicle-to-Grid Integration:Bidirectional charging capabilities are converging with residential solar adoption patterns, enabling RVs to function as mobile power assets during stationary periods.
- Direct-to-Consumer Digital Channels:Configurator-led purchasing and virtual showroom experiences are displacing traditional dealer networks, capturing margin and buyer data for manufacturers.
Industry Challenges
- Certification Timeline Compression:NHTSA structural integrity testing and EPA emissions certification cycles are extending product development schedules, delaying platform launches by 12-18 months.
- Electronics Integration Complexity:Legacy 12V electrical architectures are proving incompatible with high-voltage battery management systems, forcing complete wiring harness redesigns.
- Specialized Technician Scarcity:High-voltage certification requirements and mechatronics skill gaps are constraining service network expansion for electrified RV fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recreational Vehicle (RV) Market |
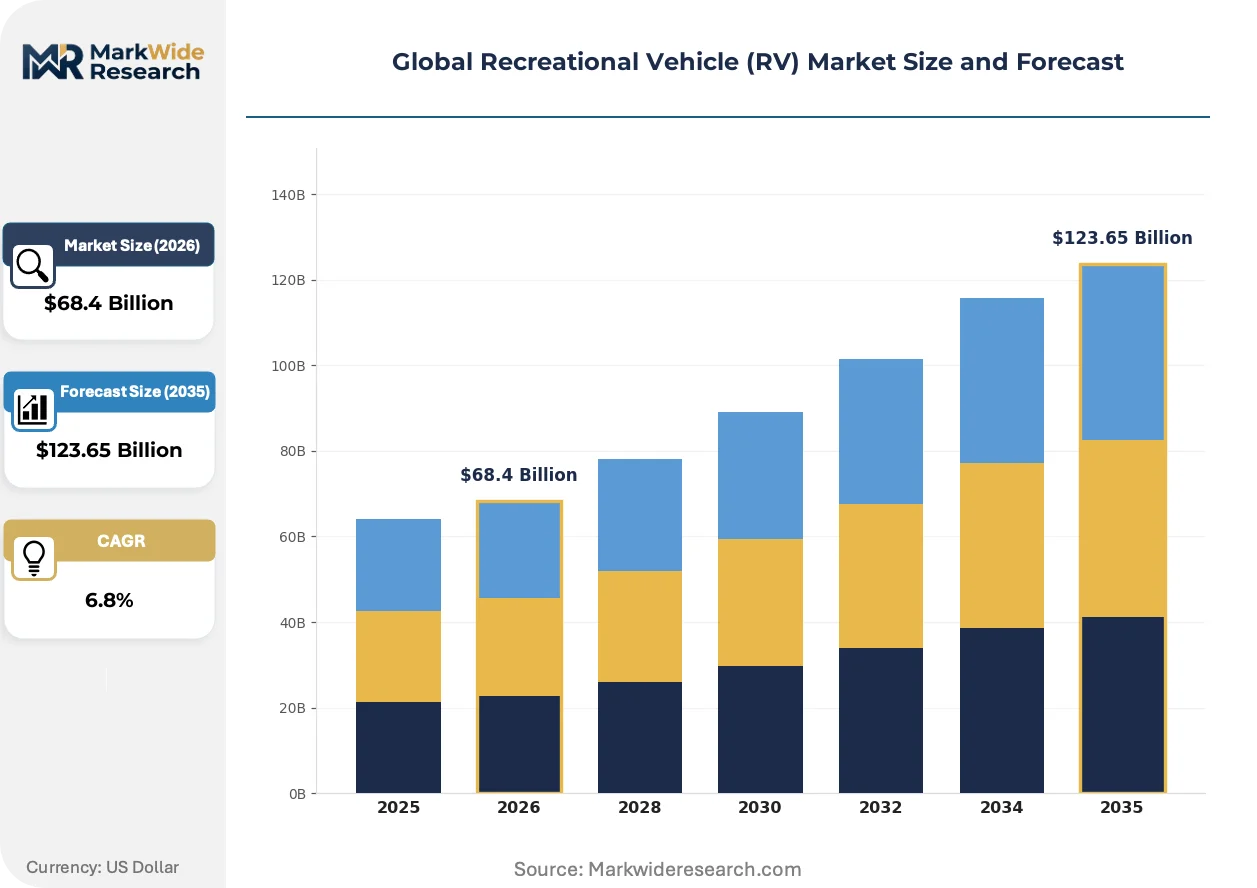
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorhomes, Towable RVs, Truck Campers, Folding Campers End User: Families, Retirees, Adventure Seekers, Tourists Fuel Type: Diesel, Gasoline, Propane, Electric Size: Small, Medium, Large, Extra Large |
| Companies Covered | Keystone RV, REV Group, Thor Industries, Newmar, Jayco, Forest River, Grand Design, Patrick Industries, Winnebago Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recreational Vehicle (RV) Market Strategic Shifts
Lightweight composite materials and smart energy management systems are compressing the tradeoff between habitable space and drivable mass, enabling configurations previously excluded from electrification roadmaps.
Structural thermoplastic composites are displacing traditional fiberglass and aluminum sidewall constructions in mid-premium motorhome segments. Thor Industries and Winnebago Industries are accelerating adoption across Class C platforms. This material transition is displacing conventional lamination processes while reducing chassis load ratings required for equivalent interior volume.
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are mandating 25% CO2 reduction from 2027 baselines, compelling chassis suppliers to integrate hybrid assist or full electric architectures. Motorhome manufacturers dependent on Ford and Mercedes-Benz van platforms face redesign cycles to accommodate modified drivetrain packaging. The Class B segment is absorbing these changes fastest due to compatible vehicle footprint and weight class.
Subscription-based access models are fragmenting traditional ownership patterns among urban millennials in the United States and Germany. Outdoorsy and RVshare peer-to-peer platforms are capturing rental demand that dealer networks previously failed to serve. This behavioral shift concentrates most visibly in coastal metropolitan corridors where storage constraints suppress purchase intent.
Global Recreational Vehicle (RV) Market Segmentation
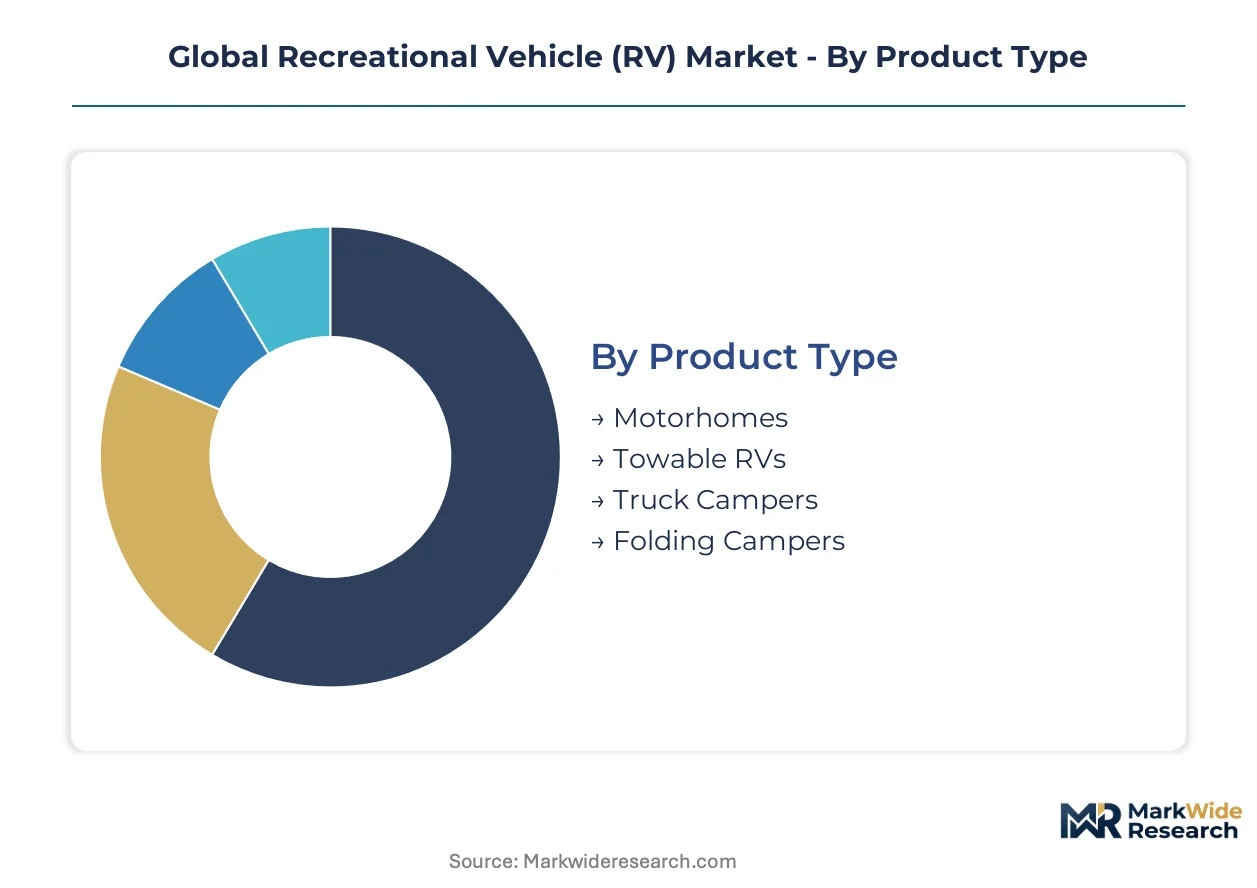
RV manufacturers configure product portfolios across four distinct segmentation axes to match heterogeneous buyer economics, mobility constraints, and energy infrastructure access. Each category shapes capital allocation, margin capture, and regulatory exposure differently across regional markets.
Product Type:
Motorhomes concentrate the highest margin pools due to integrated drivetrain complexity and premium cabin specifications, while towable RVs dominate unit economics through manufacturing standardization.
- Motorhomes:Self-propelled living quarters built on commercial van or heavy-duty truck chassis with integrated powertrain, climate systems, and wet baths. Demand clusters in the United States and Germany where highway density supports extended touring itineraries and retirees prioritize turnkey mobility.
- Towable RVs:Non-motorized units requiring external tow vehicles, spanning travel trailers and fifth-wheel configurations with expandable slide-out sections. Entry-level family segments in the United States and Australia drive volume, constrained by tow vehicle compatibility and storage infrastructure limitations.
- Truck Campers:Slide-in units mounting directly onto pickup truck beds, offering compact footprint for off-pavement access. Enthusiast buyers in the western United States and Canadian Rockies favor these for backcountry fishing and hunting access.
- Folding Campers:Collapsible tent-sided trailers reducing tow weight and storage height for compact vehicle compatibility. Price-sensitive first-time buyers in Europe and Japan select these for seasonal weekend use.
The dominant share belongs to Towable RVs, while Motorhomes is closing the gap fastest through electrification-enabled Class B configurations.
End User:
Customer lifecycle positioning determines pricing power, with retirees commanding premium configurations and adventure seekers fragmenting traditional ownership patterns through subscription access.
- Families:Multi-generational travel units prioritizing sleeping capacity, kitchen amenities, and entertainment systems for school-vacation itineraries. Demand concentrates in the United States, Australia, and France where national park infrastructure supports extended family road trips.
- Retirees:Empty-nest buyers selecting premium motorhomes with full-time livability features, residential appliances, and ergonomic accessibility. Aging demographics in the United States, Germany, and Japan expand this cohort fastest.
- Adventure Seekers:Experience-oriented millennials and Gen X buyers prioritizing off-grid capability, compact footprint, and digital nomad workspace integration. Peer-to-peer rental platforms in coastal United States metropolitan corridors and German urban centers serve this segment.
- Tourists:International visitors renting RVs for scenic route touring, particularly along Norway's fjord highways, New Zealand's South Island circuits, and Iceland's ring road.
Retirees anchor revenue concentration, while Adventure Seekers is expanding most quickly through rental platform adoption.
Fuel Type:
Powertrain selection shapes regulatory compliance timelines and supply chain exposure, with electrification roadmaps diverging sharply by vehicle size class.
- Diesel:Compression-ignition engines dominating European motorhome platforms and United States Class A configurations for torque density and towing capability. EPA Phase 3 and EU Green Deal emissions thresholds are compressing residual demand timelines.
- Gasoline:Spark-ignition powertrains prevalent in North American Class C and entry-level Class B segments where purchase price sensitivity outweighs fuel economy considerations.
- Propane:Alternative fuel conversions for off-grid cooking, heating, and refrigeration systems rather than primary propulsion, common in Australian remote-area configurations.
- Electric:Battery-electric drivetrains enabled by energy density improvements for Class B van conversions. Charging infrastructure deployment in Germany, the Netherlands, and coastal United States corridors determines near-term viability.
Diesel retains the largest installed base, while Electric is climbing the fastest as battery chemistry advances enable viable range.
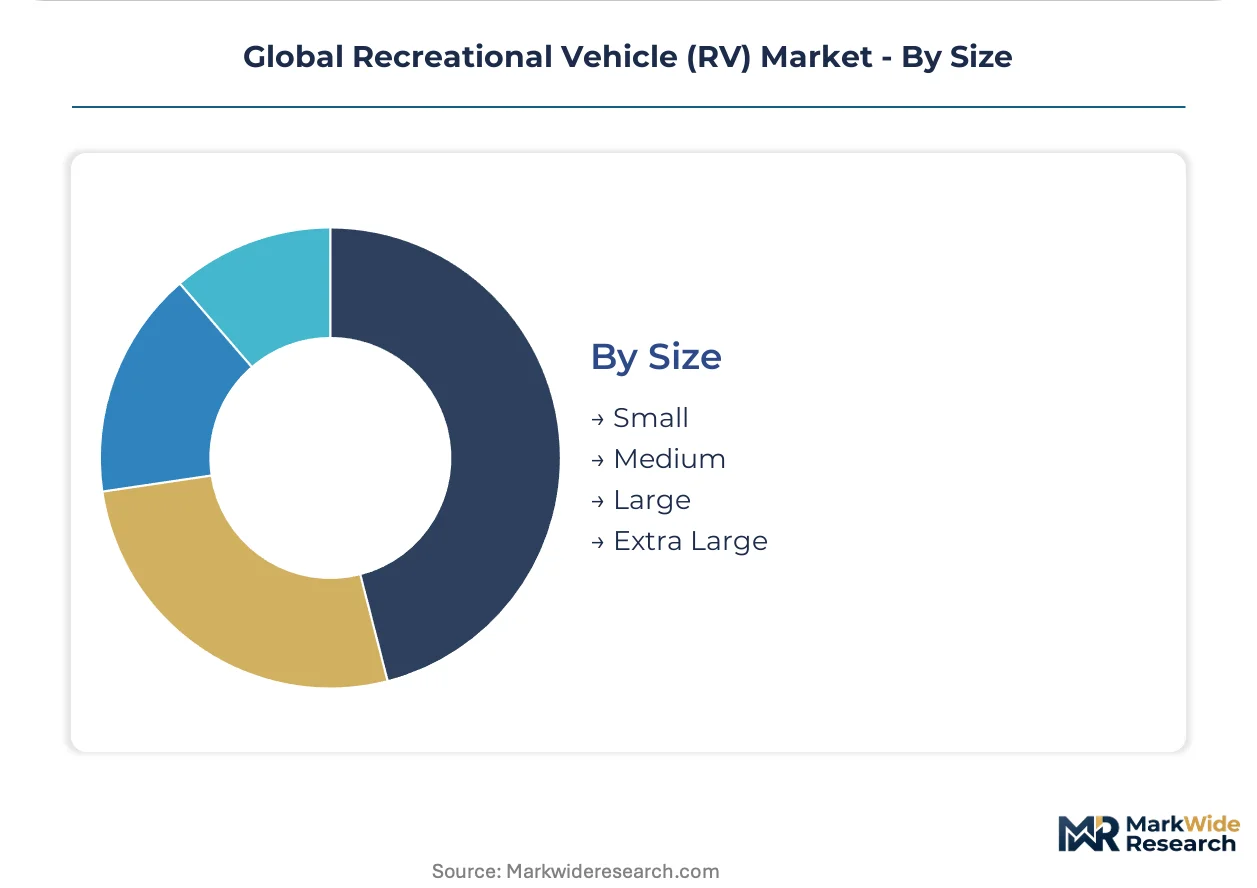
Size:
Dimensional classification structures manufacturing asset allocation, dealer inventory financing, and campground site compatibility requirements across markets.
- Small:Class B van conversions and compact truck campers under 6 meters length, optimized for urban parking and European road width constraints. Japanese kei-car regulations and Italian historic center access favor this tier.
- Medium:Class C motorhomes and mid-size travel trailers accommodating 4-6 occupants with dedicated sleeping zones. United States state park systems and Australian caravan parks standardize around these dimensions.
- Large:Class A motorhomes and fifth-wheel trailers exceeding 7.5 meters with residential-grade amenities. Full-time retirees in the United States Sun Belt and German snowbird circuits drive demand.
- Extra Large:Custom bus conversions and triple-axle fifth-wheels requiring commercial driver's license equivalents in some jurisdictions. Niche ultra-premium buyers in the United States and Saudi Arabia purchase these for extended continental touring.
Medium configurations hold the dominant position, while Small is gaining share fastest through electrification and urban storage constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System underwrites the United States' dominance, while Germany's Autobahn network and China's expanding expressway grid anchor regional demand clusters across three continents.
United States
Dispersed national park infrastructure and Sun Belt retirement migration sustain motorhome demand. EPA Phase 3 emissions standards compress compliance timelines for heavy-duty chassis suppliers. Elkhart County, Indiana concentrates manufacturing employment as Thor Industries and Forest River operate extensive assembly complexes.
Germany
EU Green Deal mobility directives accelerate electric RV prototyping investments. KBA vehicle certification requirements govern structural integrity and emissions compliance for motorhome platforms. Baden-Württemberg hosts specialized chassis engineering clusters serving premium van conversion manufacturers.
China
Expressway connectivity expansion into western provinces opens touring corridors for domestic RV adoption. MIIT new energy vehicle mandates push battery-electric drivetrain integration in commercial van platforms. Yangtze River Delta manufacturing bases supply lightweight composite materials to regional assemblers.
Japan
Aging demographics and kei-car regulatory frameworks favor compact camper configurations. METI carbon neutrality roadmaps pressure drivetrain electrification in commercial vehicle segments. Nagoya industrial corridor hosts precision manufacturing for space-efficient interior systems.
Australia
Remote-area tourism infrastructure and caravan park networks sustain towable RV demand. National heavy vehicle regulations govern trailer braking and stability standards. Queensland and New South Wales coastal corridors concentrate rental fleet operations serving international tourists.
Global Recreational Vehicle (RV) Market Competitive Environment
Listed leaders compete with private specialists across capital access and manufacturing flexibility dimensions. The vendor base concentrates around three integrated assemblers controlling premium motorhome segments, while specialized towable manufacturers fragment mid-market price tiers. Strategic archetypes span diversified conglomerates, family-owned volume producers, and component-integrated specialists. Dominant competitive moves include portfolio diversification across fuel-type variants and backward integration into chassis supply relationships.
Among Indiana-based diversified assemblers, Thor Industries and Forest River exemplify scale-driven archetypes spanning multiple brand portfolios and price segments. Winnebago Industries occupies a position within the listed manufacturer tier, representing public-market accountability pressures alongside manufacturing consolidation strategies. These three entities anchor competitive dynamics across North American motorhome and towable categories.
| Leading Market Players |
|---|
| Keystone RV |
| REV Group |
| Thor Industries |
| Newmar |
| Jayco |
| Forest River |
| Grand Design |
| Patrick Industries |
| Winnebago Industries |
| Others |
Value Chain & Pricing Dynamics
EPA Phase 3 certification gates both chassis supplier qualification and motorhome price tiering simultaneously, compressing timelines for manufacturers while amplifying cost premiums for compliant configurations. NHTSA structural integrity testing creates parallel entry barriers that stratify pricing power across integrated assemblers and specialized converters.
Pricing Analysis
Volume-discount tiering structures separate fleet purchasers from individual retail buyers across motorhome and towable categories. Price differentiation hinges on EPA emissions tier compliance and NHTSA safety certification levels, with premium configurations commanding substantial markups for integrated drivetrain complexity. Pricing pressure stems from chassis cost inflation and steel volatility, compressing margins for mid-tier assemblers. Entry-level towable segments exhibit highest buyer price sensitivity, while full-time retiree motorhome purchasers demonstrate lowest elasticity.
Supply Chain Analysis
Inventory lead times for heavy-duty truck chassis have extended substantially, forcing motorhome manufacturers into speculative ordering patterns. Supply concentrates in the United States for chassis assembly, China for lithium-ion cell manufacturing, and Germany for precision drivetrain components. Raw material dependencies span steel sheet, aluminum extrusions, and cathode-active battery materials. Single-source vulnerability in Chinese cathode processing creates geopolitical exposure. Distribution runs through independent dealer networks and emerging direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. NHTSA and EPA certification cycles create switching costs that protect incumbent positions while delaying challenger entry timelines.
For Market Incumbents: Secure backward integration into chassis supply relationships to defend against Ford and Mercedes-Benz platform allocation constraints. Fortify certification engineering capabilities to compress NHTSA testing cycles, creating speed-to-market advantages over emerging electric RV specialists. For New Entrants and Emerging Players: EPA Phase 3 fast-track certification pathways offer entry acceleration for battery-electric Class B configurations. Target underpenetrated Nordic markets with compact, thermally efficient designs optimized for Swedish and Finnish outdoor recreation participation. Pursue direct-to-consumer configurator-led purchasing to bypass established dealer network control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric drivetrain integration, favoring scaled assemblers with battery supply agreements. Long-term viability centers on manufacturers with captive chassis relationships and charging infrastructure partnerships. Monitor MIIT new energy vehicle mandate alignment as inflection indicator for Chinese market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Chassis Supply Integration | Captive Ford and Mercedes-Benz platform access locks in production capacity allocation priority. |
| Electric Drivetrain Prototyping | Battery energy density improvements enable Class B range viability for coastal corridor charging networks. |
| Direct-to-Consumer Channel Launch | Configurator-led purchasing captures margin compression from traditional dealer financing structures. |
| Lightweight Composite Adoption | Thermoplastic sidewall materials reduce chassis load ratings while expanding interior volume configurations. |
| Nordic Market Expansion | Compact thermally efficient designs address whitespace in Swedish and Finnish outdoor recreation participation. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with RV manufacturer platform engineers, Tier 1 chassis procurement directors, national park infrastructure planners, and electrification R&D leads; and secondary validation through EPA certification filings, NHTSA safety test records, IHS Markit vehicle registration databases, and EIA transportation energy consumption reports. Bottom-up unit economics triangulated against top-down market sizing across product type, fuel architecture, and regional adoption clusters.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, buyer lifecycle stage, and regional highway density. CAGRs derived from production capacity buildouts, demographic cohort expansion rates, and regulatory compliance timeline compression. Forecast inputs incorporated battery energy density improvement curves and charging infrastructure deployment schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained retiree demographic expansion and EPA Phase 3 compliance adherence; material deviation in lithium-ion supply localization or chassis platform availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Recreational Vehicle Rental Market