
 Global Foldable Inflatable Boats Market | 2026-2036
Global Foldable Inflatable Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foldable Inflatable Boats Market Analysis
Capital-intensity divergence between hull fabrication and assembly-only operators is rotating the competitive map toward integrated manufacturers. Zodiac Nautic leverages its proprietary thermobonding infrastructure to control quality from fabric to finished vessel. Sea Eagle Boats anchors its position through direct-to-consumer channel dominance in North American recreational segments. Highfield Boats competes by specializing in aluminum-hull hybrid designs that bridge rigid and inflatable performance categories.
Foldable inflatable boats are portable watercraft constructed from flexible, air-retaining fabrics—typically PVC or Hypalon—featuring collapsible frames or fully soft architectures that deflate for transport and storage; hull pressures range from 2.5 to 4.0 PSI, with welded or glued seam construction determining durability in saltwater environments. These vessels serve recreational day-boating, commercial ferrying, military rapid deployment, and rescue operations where vessel stowability outweighs rigid-hull performance. Soft Folding configurations dominate unit volumes due to lower price points and minimal storage requirements, though Hybrid Inflatable architectures capture disproportionate margin pools through aluminum-floor premiums. Military and Rescue Operations end-use segments sustain the highest specification barriers, with Hypalon and Neoprene material grades required for abrasion resistance and extended UV exposure.
ISO 6185 sets international inflatable boat construction and safety standards, while the US Coast Guard enforces flotation and labeling requirements for vessels under twenty feet. The EU Marine Equipment Directive mandates CE marking for commercial deployment in European waters, creating market access friction for non-compliant imports. Stakeholders must monitor evolving polymer sustainability mandates and Coast Guard small-craft safety rulemakings to anticipate material substitution timelines and certification cost shifts.
Market Dynamics
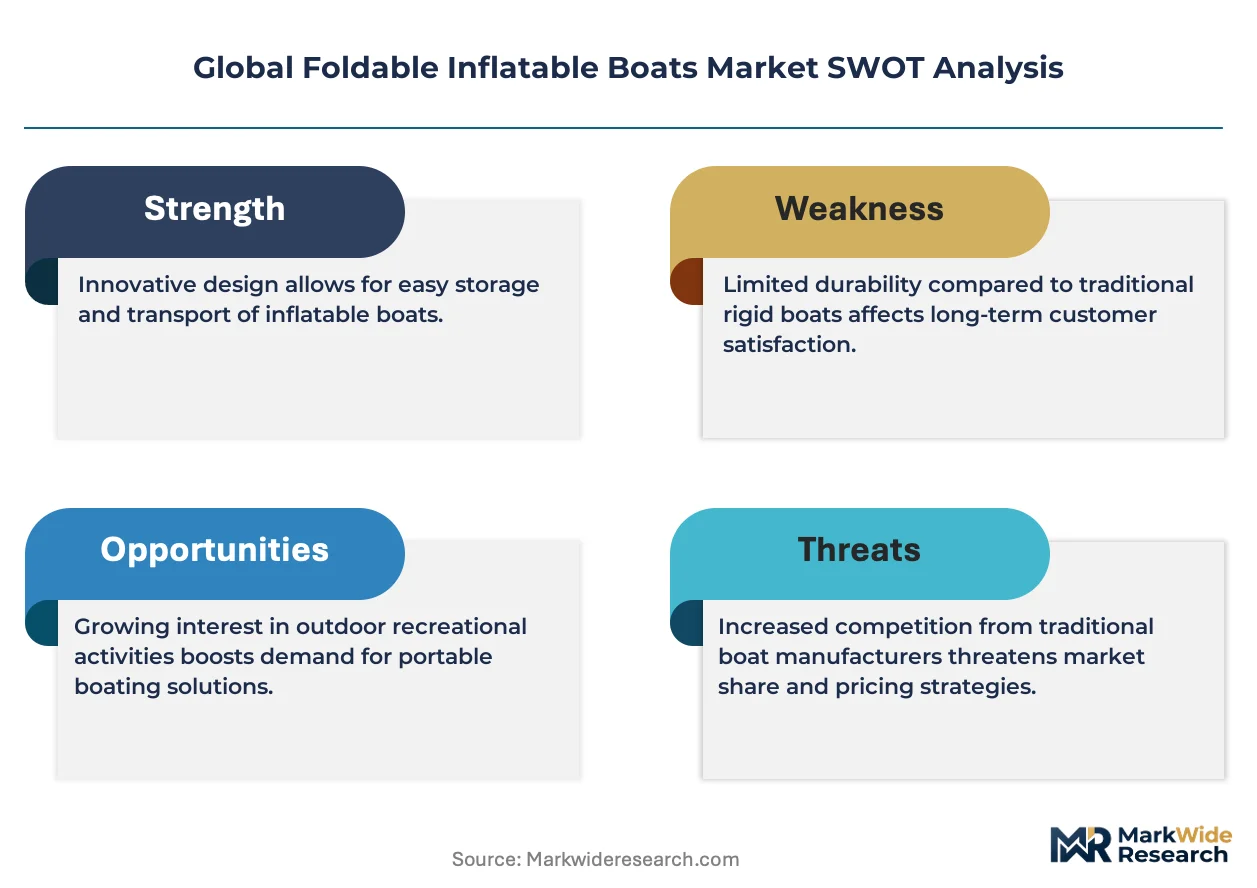
REACH compliance costs in the EU are forcing material substitution timelines, compressing margins for PVC-dependent fabricators while advantaging Hypalon-certified producers with captive polymer supply.
Growth Catalysts
- Coastal Tourism Expansion:Mediterranean charter operators in Greece and Croatia are replacing rigid tenders with soft-folding inflatables to reduce storage footprints on superyachts.
- REACH Polymer Mandates:ECHA's tightening restrictions on phthalate plasticizers are accelerating certified Hypalon adoption in commercial rescue fleets.
- Thermobonding Automation:Seam-welding robotics are reducing labor content in hull fabrication, enabling European producers to reclaim volume from Asian assembly-only competitors.
Market Restraints
- Hypalon Feedstock Concentration:Neoprene and chlorosulfonated polyethylene supply concentrates among three Japanese and Korean chemical conglomerates, exposing fabricators to input volatility.
- CE Certification Friction:The EU Marine Equipment Directive's notified-body bottlenecks extend commercial deployment timelines by four to seven months for non-EU manufacturers.
- Rigid-Hull Substitution:Aluminum RIBs from Croatian and Turkish yards are capturing price-insensitive buyers seeking planing performance in chop.
Strategic Opportunities
- Electric Outboard Convergence:Torqeedo and ePropulsion motor compatibility is opening new design specifications for silent-running wildlife tourism vessels in the Norwegian fjords.
- Direct-to-Channel Bypass:Manufacturers are establishing owned digital storefronts to capture margin previously allocated to marine retail distributors in North American recreational segments.
- Military Rapid Deployment:NATO expeditionary units are specifying air-droppable foldable craft for littoral insertion, creating demand for ultra-lightweight floorboard composites.
Industry Challenges
- Welding Technician Scarcity:Thermobonding equipment operation requires specialized certification that exceeds standard PVC adhesive training, constraining production scaling.
- Multi-Jurisdiction Certification:Simultaneous ISO 6185, US Coast Guard, and CE marking compliance demands redundant testing protocols that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foldable Inflatable Boats Market |
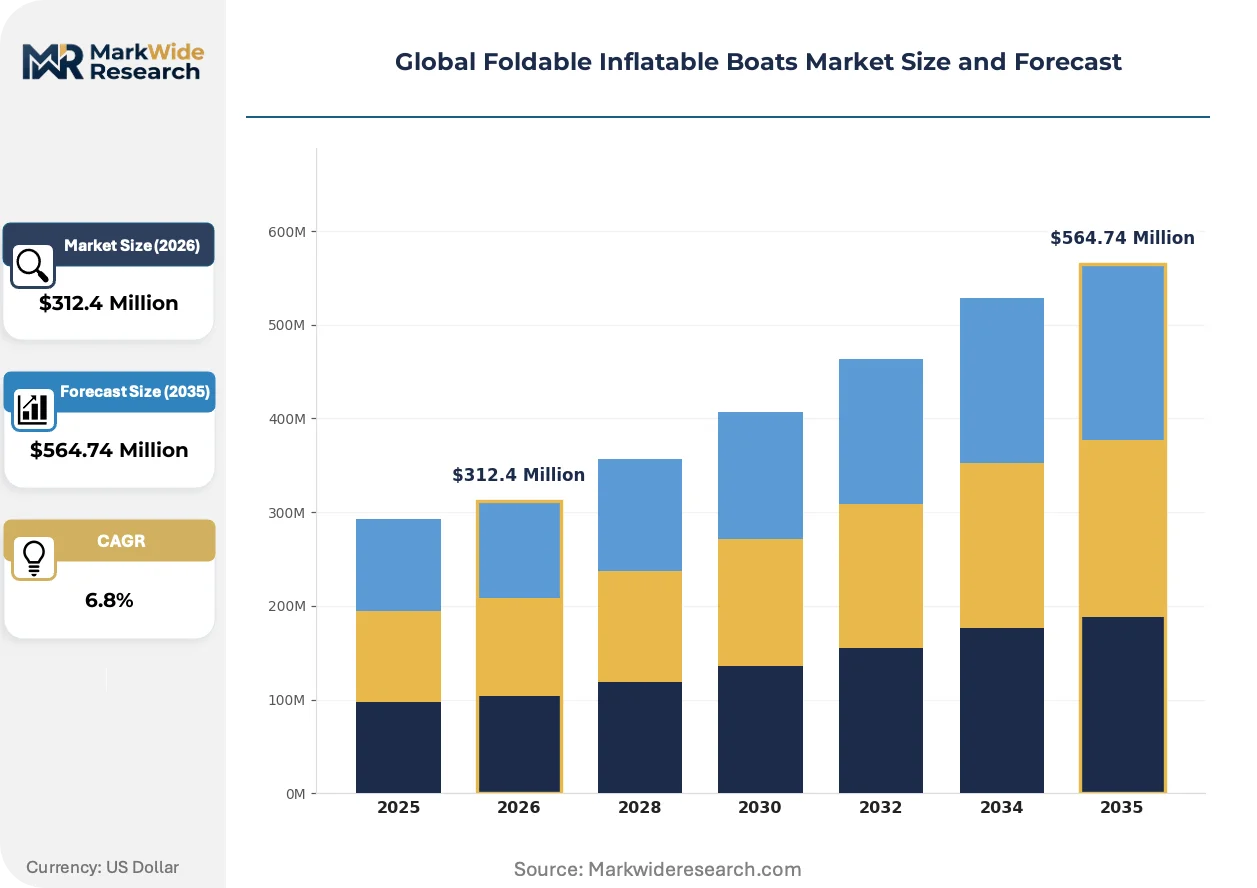
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Folding, Soft Folding, Hybrid Inflatable, Modular Inflatable Material: PVC, Hypalon, Neoprene, Nylon End User: Recreational, Commercial, Military, Rescue Operations Size: Small, Medium, Large, Extra Large |
| Companies Covered | Intex Recreation, Sea Eagle Boats, Zodiac Nautic, Highfield Boats, Achilles Inflatable Boats, AB Inflatables, Sevylor, BRIS, Walker Bay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foldable Inflatable Boats Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are restructuring competitive advantage around polymer certification and seam durability rather than price-point positioning.
Thermobonded seam construction is supplanting glued PVC assemblies in saltwater commercial applications. Coast Guard-certified rescue operators and Mediterranean ferry services are specifying welded hulls exclusively. This technology is compressing warranty claim rates and extending replacement cycles from three to seven years.
REACH Annex XVII restrictions on persistent organic pollutants are forcing PVC reformulation across European supply chains. Fabricators must requalify entire product lines under ECHA's substance evaluation timelines. Commercial operators in France and Italy are accelerating Hypalon procurement to preempt compliance discontinuities.
Charter fleet managers are consolidating procurement through marine service integrators rather than direct manufacturer relationships. These intermediaries bundle vessel supply with seasonal maintenance and emergency replacement pools. The model is most developed in Croatian and Greek island-hopping operations where downtime costs exceed capital expenditure premiums.
Global Foldable Inflatable Boats Market Segmentation
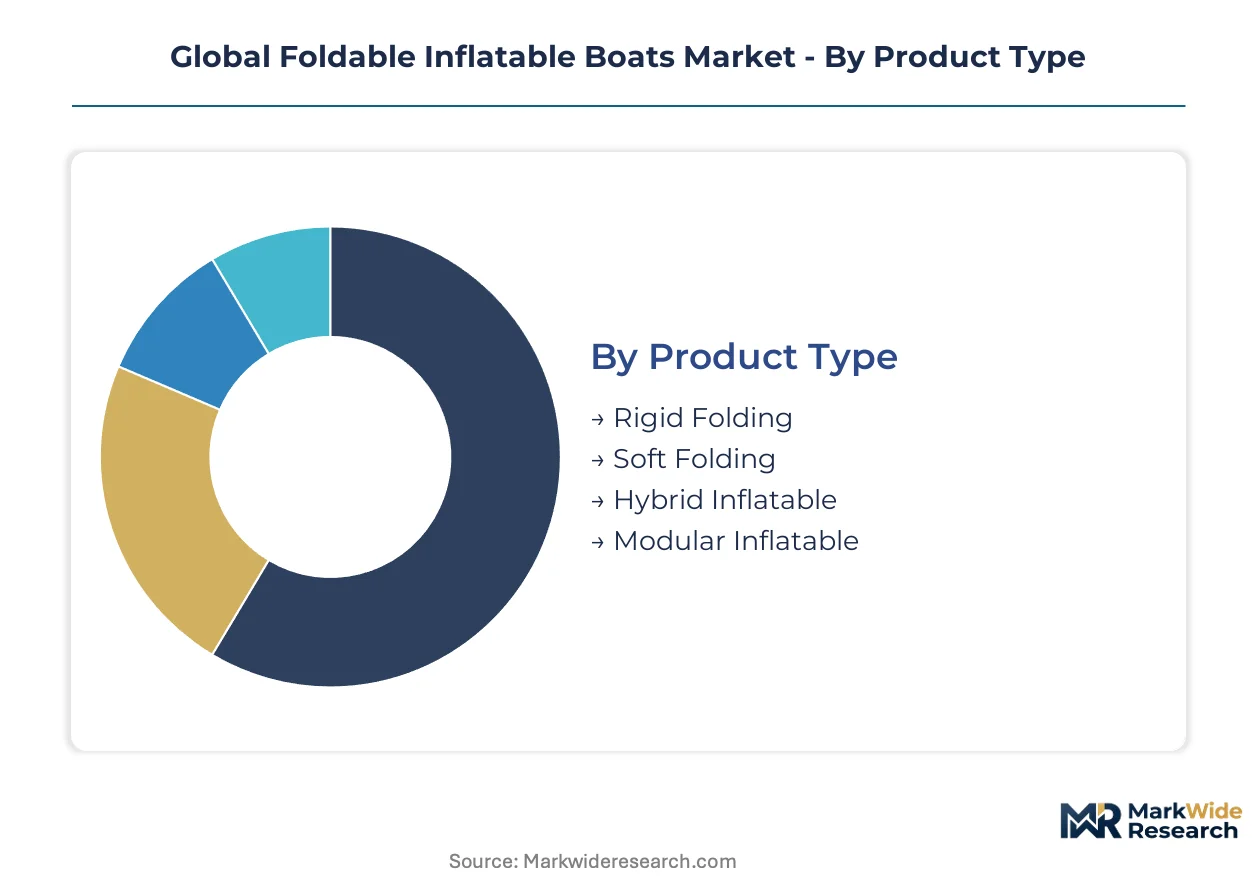
Segmentation in foldable inflatable boats reveals how vessel architecture, material chemistry, and deployment intensity map to distinct procurement channels and specification tiers. Channel access and margin structure diverge sharply across these boundaries.
Product Type:
Channel-mix patterns show soft-folding units dominating direct-to-consumer marine retail and online storefronts, while hybrid and rigid configurations concentrate in commercial integrator and defense procurement channels.
- Rigid Folding:Aluminum or composite floorboards lock into inflatable collars, delivering planing performance comparable to small RIBs. Croatian charter fleets and Turkish coastal operators specify these for chop-heavy Aegean routes where rigid-hull durability outweighs pack-down convenience.
- Soft Folding:Fully collapsible architectures with fabric or roll-up floors minimize packed volume for superyacht tender garages. Mediterranean superyacht provisioning in Greece and Croatia drives volume through marine service integrators who bundle seasonal maintenance contracts.
- Hybrid Inflatable:Combines pneumatic collars with removable rigid floor sections, bridging performance categories. NATO expeditionary units and Norwegian wildlife tourism operators source through defense and specialty commercial channels.
- Modular Inflatable:Sectional hull designs permit field reconfiguration of length and capacity. Limited commercial deployment concentrates in German and Dutch inland waterway maintenance fleets requiring transportability.
Soft Folding dominates installed base. Hybrid Inflatable is where expansion concentrates.
Material:
Cost-tier stratification separates commodity PVC from certified polymer grades, with margin pools concentrating in REACH-compliant supply chains and military-specification certifications.
- Hypalon:Chlorosulfonated polyethylene delivers superior UV resistance and abrasion tolerance for extended saltwater exposure. French and Italian rescue fleets are accelerating procurement to preempt REACH Annex XVII discontinuities in PVC plasticizer chemistries.
- PVC:Thermoplastic formulations dominate recreational price-sensitive segments through welded or glued seam construction. ECHA substance evaluation timelines are forcing reformulation costs that compress margins for fabricators without captive polymer supply.
- Neoprene:Synthetic rubber compounds provide cold-weather flexibility and chemical resistance. Norwegian fjord tourism and Baltic Sea operations specify neoprene-collared vessels for sub-zero inflation reliability.
- Nylon:Reinforced fabric substrates serve as base materials for specialty military air-droppable specifications. Ultra-lightweight floorboard composites for NATO littoral insertion units incorporate nylon weave laminates.
Hypalon commands premium pricing tiers. PVC retains volume leadership but faces substitution pressure.
End User:
Application intensity determines specification barriers, with rescue and military segments imposing material certification requirements that recreational buyers bypass entirely.
- Rescue Operations:ISO 6185 and Coast Guard flotation mandates require welded Hypalon hulls with redundant air chambers. US and Mediterranean commercial operators accept only seven-year-warranty thermobonded construction.
- Military:Rapid deployment specifications demand air-droppable weights and field-repairable architectures. NATO procurement channels specify modular floorboard systems and captive polymer traceability.
- Commercial:Ferry and charter operators balance durability against downtime costs, driving procurement through Croatian and Greek marine service integrators with seasonal replacement pools.
- Recreational:Day-boating and fishing applications prioritize pack-down dimensions and price accessibility, flowing through direct-to-consumer channels in North America and European retail networks.
Rescue Operations impose the highest specification barriers. Recreational channels represent the broadest volume base.
Size:
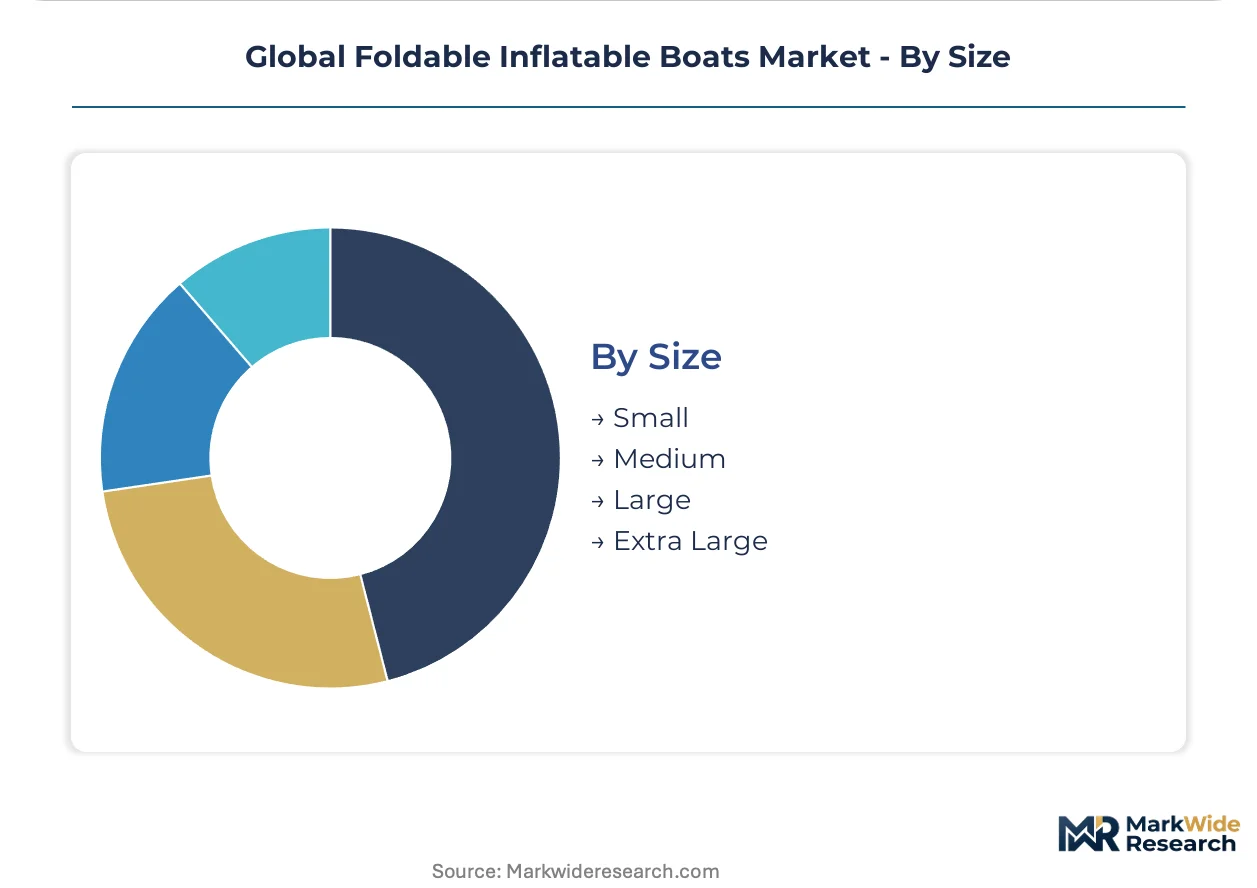
Volume-mix patterns show small and medium units dominating unit shipments, while large and extra-large configurations capture disproportionate value through aluminum-floor premiums and commercial ferry specifications.
- Medium:Three-to-four-meter lengths balance passenger capacity with transportability for superyacht tenders and coastal charter operations. Greek island-hopping fleets standardize on this footprint for dockside maneuverability.
- Small:Sub-three-meter pack-down dimensions target individual anglers and yacht owners with limited garage space. Direct-to-consumer channels in North America move the highest unit volumes at entry price points.
- Large:Five-to-six-meter architectures accommodate commercial ferry loads and dive operations. Croatian coastal operators deploy these for passenger shuttle routes between mainland marinas and island destinations.
- Extra Large:Six-meter-plus specifications serve military littoral insertion and heavy-lift rescue platforms. Limited production runs concentrate in defense contractor supply chains with multi-year procurement cycles.
Medium size anchors commercial fleet standardization. Extra Large represents the steepest expansion trajectory in defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Recreational buyers in North America prioritize pack-down convenience over material grade, while Mediterranean commercial operators accept steep Hypalon premiums to minimize fleet downtime. Military procurement channels in Northern Europe impose the most stringent specification barriers.
United States
Coastal tourism operators in Florida and California drive recreational volume through direct-to-consumer channels. The US Coast Guard enforces flotation and labeling requirements for vessels under twenty feet. Marine retail clusters in Fort Lauderdale and San Diego concentrate inventory for superyacht provisioning.
Greece
Island-hopping charter fleets in the Cyclades and Ionian islands standardize on medium-length soft-folding tenders. EU REACH Annex XVII restrictions on phthalate plasticizers are accelerating certified Hypalon adoption. Athens-based marine service integrators bundle vessel supply with seasonal maintenance contracts.
Croatia
Adriatic coastal operators deploy large-format vessels for passenger shuttles between mainland marinas and island destinations. The EU Marine Equipment Directive mandates CE marking for commercial deployment. Split and Dubrovnik harbor clusters concentrate procurement through specialized marine integrators.
Norway
Fjord wildlife tourism operators specify neoprene-collared vessels for sub-zero inflation reliability. Electric outboard convergence with Torqeedo and ePropulsion motors is opening silent-running design specifications. Bergen and Tromsø service hubs coordinate fleet specifications for Arctic expedition vessels.
France
Commercial rescue fleets in Marseille and Toulon are accelerating Hypalon procurement to preempt REACH compliance discontinuities. ECHA substance evaluation timelines are forcing PVC reformulation costs across supply chains. Mediterranean search-and-rescue operators specify welded hulls with seven-year warranties exclusively.
Global Foldable Inflatable Boats Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on price and channel access. Thermobonding infrastructure ownership separates hull fabricators from assembly-only operators. Three archetypes dominate: integrated polymer-to-vessel manufacturers, direct-to-consumer channel specialists, and aluminum-hull hybrid designers. Competitive moves concentrate on thermobonding automation investments and marine service integrator partnerships.
Among established fabricators, Zodiac Nautic and Sea Eagle Boats exemplify divergent channel strategies. Zodiac Nautic represents the integrated manufacturing archetype with captive control over fabric production. Sea Eagle Boats anchors the direct-to-consumer specialist tier in North American recreational segments. Highfield Boats occupies a hybrid-positioning niche bridging rigid and inflatable performance categories.
| Leading Market Players |
|---|
| Intex Recreation |
| Sea Eagle Boats |
| Zodiac Nautic |
| Highfield Boats |
| Achilles Inflatable Boats |
| AB Inflatables |
| Sevylor |
| BRIS |
| Walker Bay |
| Others |
Supply Flow & Price Mechanics
Ninety-day Hypalon fabric lead times from Japanese chemical conglomerates concentrate pricing power among REACH-certified producers while compressing margins for PVC-dependent fabricators facing ECHA reformulation costs. This inventory-to-pricing linkage rewards captive polymer supply and penalizes assembly-only operators without thermobonding infrastructure.
Pricing Analysis
After-sales service contracts and seasonal maintenance bundling drive lifetime value in Mediterranean charter procurement, where Greek and Croatian marine service integrators capture recurring revenue streams. Three-tier pricing structure across premium Hypalon, standard PVC-welded, and economy glued-PVC tiers segments buyers by certification grade and warranty length. Pricing pressure stems from REACH compliance costs forcing PVC reformulation, with commercial rescue fleets least price-sensitive due to downtime cost exposure and recreational North American buyers most sensitive to pack-down convenience premiums.
Supply Chain Analysis
Strategic stockpiling of Hypalon and Neoprene feedstocks dominates procurement behavior among EU commercial operators preempting ECHA substance evaluation discontinuities. Raw material supply concentrates in Japan and South Korea for chlorosulfonated polyethylene, with PVC fabric production anchored in Chinese chemical processing zones. Single-source vulnerability runs through the three Asian chemical conglomerates controlling military-specification polymer grades. Distribution runs through marine service integrators in Mediterranean harbors and direct-to-consumer digital storefronts in North American recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Foldable Inflatable Boats Market is recovering from pandemic-era coastal tourism disruption, with Mediterranean superyacht provisioning and NATO expeditionary procurement forming twin cyclical anchors.
For Market Incumbents: Fortify thermobonding automation investments to reclaim volume from Asian assembly-only competitors while accelerating captive Hypalon supply agreements with Japanese chemical conglomerates. REACH Annex XVII compliance timelines threaten PVC-dependent product lines; prioritize ISO 6185-certified welded hull production for seven-year warranty positioning in rescue and commercial ferry segments. For New Entrants and Emerging Players: CE marking fast-track partnerships with Croatian and Greek notified bodies unlock four-to-seven-month deployment timeline advantages for Mediterranean commercial procurement. White-space concentration in Norwegian fjord wildlife tourism and German inland waterway maintenance fleets offers penetrable entry points. Direct-to-consumer digital storefronts bypass marine retail distributor margins in North American recreational segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine conglomerates with underutilized thermobonding infrastructure and stranded PVC product lines requiring REACH reformulation capital. Long-term viability centers on polymer certification assets and military specification traceability. Watch NATO littoral insertion procurement cycles as inflection indicators for ultra-lightweight floorboard composite demand.| Strategic Initiative | Industry Significance |
|---|---|
| Thermobonding Automation Investment | Sea Eagle Boats and Zodiac Nautic deploy robotic seam-welding to reduce labor content and extend warranty terms. |
| REACH-Compliant Polymer Certification | French and Italian rescue fleets mandate Hypalon procurement to preempt ECHA phthalate plasticizer restrictions. |
| Direct-to-Consumer Channel Expansion | North American recreational buyers bypass marine retail distributors through owned digital storefronts. |
| Marine Service Integrator Partnerships | Athens and Split-based bundlers consolidate Croatian and Greek island-hopping fleet procurement with maintenance pools. |
| Electric Outboard Compatibility Design | Torqeedo and ePropulsion motor integration opens Norwegian fjord wildlife tourism specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing plant managers at thermobonding facilities, procurement leads at Mediterranean charter operators, marine service integrators in Greek and Croatian harbors, and aftermarket service heads at North American recreational distributors. Secondary validation drew from customs and trade data, SEC filings of listed marine equipment manufacturers, EU ECHA substance evaluation databases, and NATO procurement disclosure records. Bottom-up vessel shipment aggregation triangulated against top-down polymer consumption estimates.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product architecture, material chemistry grade, end-use intensity, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, fleet expansion rates in coastal tourism economies, and defense procurement pipeline visibility. Hypalon adoption curves, REACH compliance cost pass-through assumptions, and electric outboard penetration in Nordic markets informed scenario-weighted projections.
Decision-makers should treat outputs as directional under base assumptions of stable ECHA enforcement timelines and continued NATO expeditionary specification activity; material deviation would warrant model refresh. Revision becomes warranted when Hypalon feedstock concentration risk or CE marking notified-body bottlenecks cross threshold severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Beacon Market
Marine
Azimuth Thrusters Market
Marine
Marine Shaft Power Meter Market
Marine
Marine Gas Oil Market
Marine
Marine Salvage Services Market
Marine
Europe Recreational Boating Market
Marine
Jet Boat Market
Marine
Sailboat Market
Marine
Marine Diesel Engine Market
Marine
Integrated Bridge System for Ships Market
Marine
Deep-V Boat Market
Marine
LNG Bunkering Vessel Market
Marine
Marine Chartplotter Market
Marine
Marine Growth Removal Tool Market
Marine
Marine Stabilizers Market
Marine
Marine Fender Systems Market