
 Recreational Vehicle Rental Market | 2026-2036
Recreational Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Vehicle Rental Market Outlook
FMVSS 208 occupant crash protection certification is redrawing competitive entry barriers for fleet operators seeking liability coverage and interstate operating authority. Cruise America leverages vertically integrated maintenance infrastructure to sustain fleet uptime across its owned-branch network. Outdoorsy anchors its marketplace position through peer-to-peer host onboarding protocols that reduce capital intensity versus asset-heavy rivals. Indie Campers dominates European corridor routes with seasonal hub repositioning that maximizes vehicle utilization rates.
Recreational vehicle rental denotes the short-term commercial provision of motorized and towable living quarters, typically featuring self-contained electrical systems, freshwater storage, and sleeping accommodations for two to eight occupants, deployed for leisure travel and outdoor recreation. Motorhome rentals command premium daily rates and higher per-trip ancillary revenue, while camper van offerings attract adventure seekers seeking fuel efficiency and urban maneuverability. Online platforms now capture the dominant share of booking volume, though direct operator channels retain loyalty among repeat customers seeking fleet consistency and bundled insurance products.
NHTSA vehicle safety standards govern braking, lighting, and structural integrity requirements that rental fleets must maintain across state jurisdictions, while EPA Tier 3 emissions regulations are accelerating diesel and gasoline powertrain replacement cycles. The Department of Transportation commercial operator classifications in certain states impose additional driver qualification mandates on larger motorhome categories. Stakeholders must weigh fleet electrification timelines against charging infrastructure gaps in destination markets before committing capital to next-generation vehicle procurement.
Market Dynamics
EPA Tier 3 emissions standards are compressing diesel motorhome replacement cycles and elevating fleet compliance costs, forcing operators to accelerate capital deployment toward electrified powertrains despite charging infrastructure gaps in western national park corridors.
Growth Catalysts
- Family vacationer segment expansion:Multi-generational travel demand is elevating rental utilization rates across extended-stay itineraries, particularly in destination markets proximate to protected wilderness areas.
- FMVSS 208 certification requirements:NHTSA occupant crash protection mandates are consolidating liability coverage access around compliant fleet operators, creating operational scale advantages for certified providers.
- Peer-to-peer platform onboarding:Digital marketplace protocols are reducing host capital intensity and expanding supply-side participation among private vehicle owners in high-demand corridors.
Market Restraints
- Powertrain input cost volatility:Battery pack and semiconductor pricing instability is compressing procurement margins for electrified fleet additions.
- Western US supply concentration:Fleet density clustering around Yellowstone-Grand Teton and Utah's Mighty Five corridors creates seasonal utilization imbalances and repositioning costs.
- Commercial driver qualification mandates:Department of Transportation classification requirements for Class A motorhome categories impose additional licensing friction in certain state jurisdictions.
Strategic Opportunities
- European corridor route development:Seasonal hub repositioning across Iberian and Alpine markets offers utilization rate optimization for operators with cross-border logistics capabilities.
- Camper van adventure segment:Fuel-efficient compact offerings attract urban maneuverability-seeking travelers previously excluded from traditional motorhome categories.
- IRA clean vehicle tax credits:Federal incentive structures are offsetting electrified fleet procurement costs for qualifying commercial operators meeting domestic assembly requirements.
Industry Challenges
- EV charging infrastructure alignment:Destination market charging gaps require operators to coordinate site-specific installation partnerships before committing to battery-electric vehicle deployment.
- FMVSS 208 compliance timeline compression:Certification testing bottlenecks are extending vehicle onboarding cycles and constraining fleet expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Vehicle Rental Market |
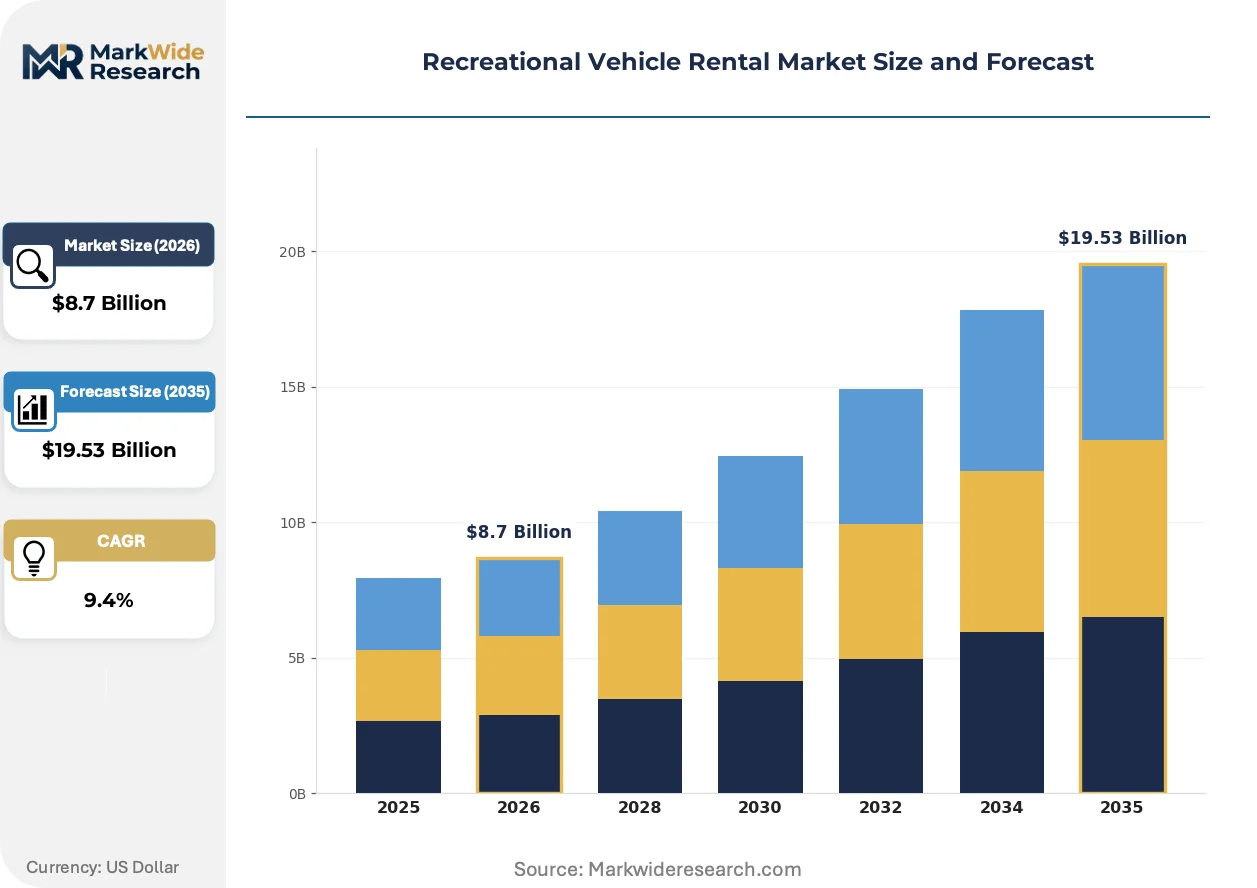
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorhome, Travel Trailer, Camper Van, Fifth Wheel Rental Duration: Daily, Weekly, Monthly, Long-term Customer Segment: Families, Couples, Adventure Seekers, Retirees Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Mobile Apps |
| Companies Covered | Cruise America, Outdoorsy, RVshare, El Monte RV, Apollo RV Holidays, Road Bear RV, McRent, Indie Campers, Escape Campervans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Vehicle Rental Market Strategic Shifts
Digital booking platforms are consolidating reservation volume while direct operator channels defend repeat customer loyalty through bundled insurance products and fleet consistency guarantees.
Telematics-enabled predictive maintenance systems are decomposing traditional reactive service models into condition-based intervention protocols. Fleet operators deploying these systems achieve measurable uptime improvements across dispersed branch networks. The technology is decomposing legacy maintenance cost structures and compressing vehicle out-of-service intervals.
EPA heavy-duty vehicle emissions standards are mandating exhaust after-treatment system retrofits and accelerating diesel powertrain obsolescence timelines. Fleet procurement committees now weight total cost of ownership calculations against regulatory sunset dates. Motorhome categories above 26,000 pounds face the most acute compliance pressure and replacement urgency.
Adventure travelers are compressing booking lead times and prioritizing vehicle flexibility over amenity density. Peer-to-peer marketplaces capture this demand through instant-confirmation mobile interfaces that bypass traditional reservation windows. This behavioral shift concentrates in western US destination markets where spontaneous itinerary changes respond to weather and trail conditions.
Recreational Vehicle Rental Market Segmentation
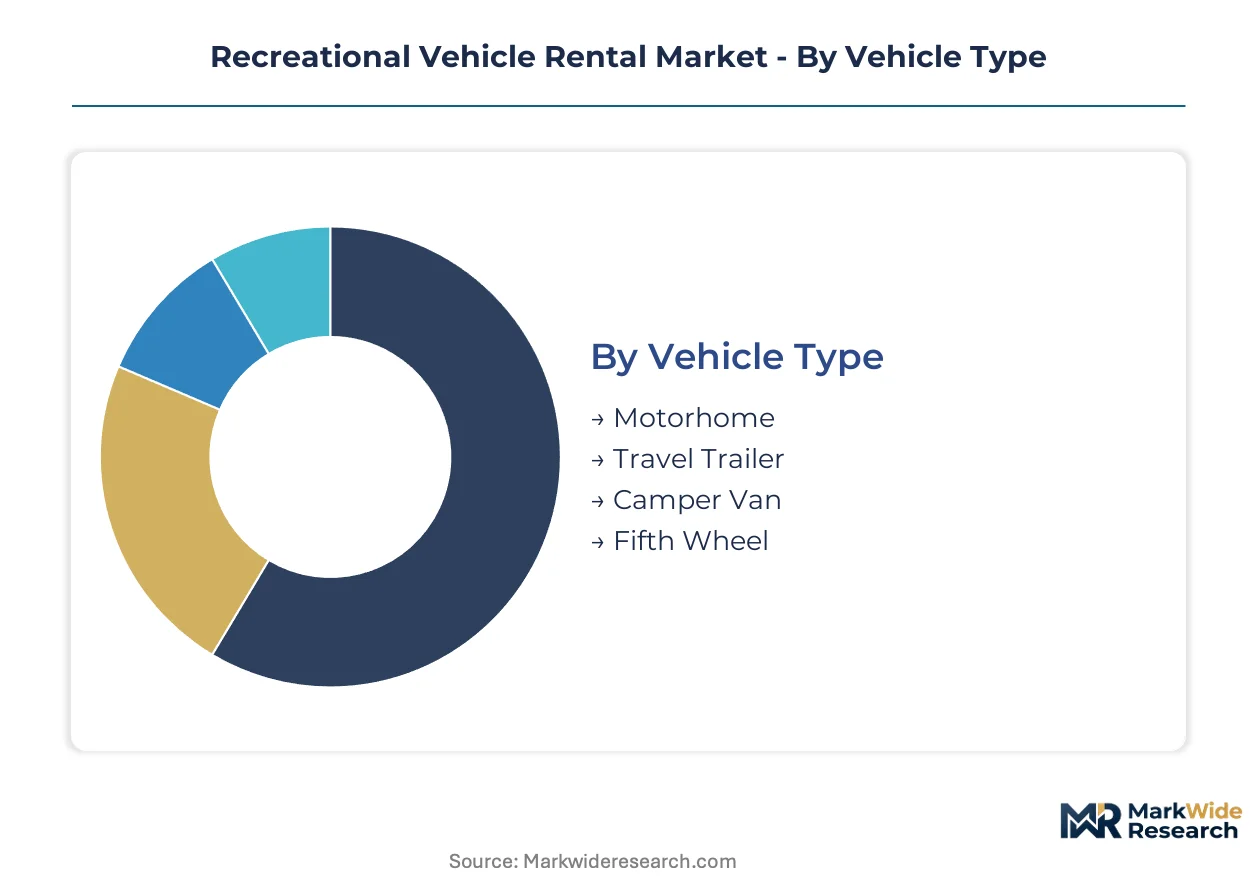
Vehicle configuration and rental duration patterns determine fleet capital allocation and revenue yield management across operator business models. Booking channel preferences are fragmenting customer acquisition economics and reshaping loyalty program design.
Vehicle Type:
Channel-mix dynamics concentrate premium motorhome bookings through direct operator channels where bundled insurance and fleet consistency justify higher daily rates, while peer-to-peer platforms dominate camper van volume through lower host capital barriers.
- Motorhome:Self-propelled units exceeding 26,000 pounds GVWR feature integrated sleeping, cooking, and sanitation systems for four to eight occupants. Demand concentrates in extended-stay western US national park corridors where multi-generational families prioritize amenity density over fuel economy, though EPA Tier 3 compliance costs are compressing diesel fleet replacement cycles.
- Camper Van:Compact Class B conversions built on commercial van chassis deliver 18-22 MPG efficiency with standing-height interiors for two to four travelers. Urban maneuverability-seeking adventure travelers in Pacific Northwest and Colorado destination markets are elevating utilization rates, with peer-to-peer supply expansion outpacing traditional fleet growth.
- Travel Trailer:Towable units requiring separate hitch vehicles range from lightweight teardrops to 35-foot luxury configurations.
- Fifth Wheel:Gooseneck-hitch designs with elevated forward sleeping quarters dominate full-time residential rental demand.
By volume, camper van rentals lead. By growth pace, motorhome premium positioning is ahead.
Rental Duration:
Cost-tier stratification separates impulse-driven short-term bookings from negotiated long-term corporate housing contracts with divergent margin profiles.
- Daily:Single-day rentals capture spontaneous adventure travelers and event-driven demand with minimal advance booking windows.
- Weekly:Seven-day itineraries dominate family vacationer utilization, particularly across Yellowstone-Grand Teton corridor routes where repositioning costs favor extended stays.
- Monthly:Extended-duration bookings attract remote workers and seasonal residents seeking furnished mobility alternatives to traditional housing.
- Long-term:Multi-month agreements serve disaster relief housing, film production crews, and corporate project assignments with predictable occupancy.
Weekly rentals generate the highest revenue per vehicle. Monthly terms are climbing the fastest as remote work normalization extends average trip duration.
Customer Segment:
Application-specific needs dictate vehicle size, amenity configuration, and insurance bundling preferences across divergent demographic profiles.
- Families:Multi-generational groups of six to eight travelers prioritize sleeping capacity and kitchen facilities, driving motorhome and large travel trailer selection.
- Couples:Empty-nester and honeymoon segments favor compact camper vans and mid-size travel trailers with premium interior finishes.
- Adventure Seekers:Trail-accessibility requirements elevate four-wheel-drive camper van and off-road trailer specifications.
- Retirees:Extended-stay flexibility and accessibility features concentrate demand in Class A motorhome categories with slide-out expansions.
Families represent the largest addressable base. Adventure seekers are expanding most quickly as peer-to-peer platforms lower entry barriers for younger demographics.
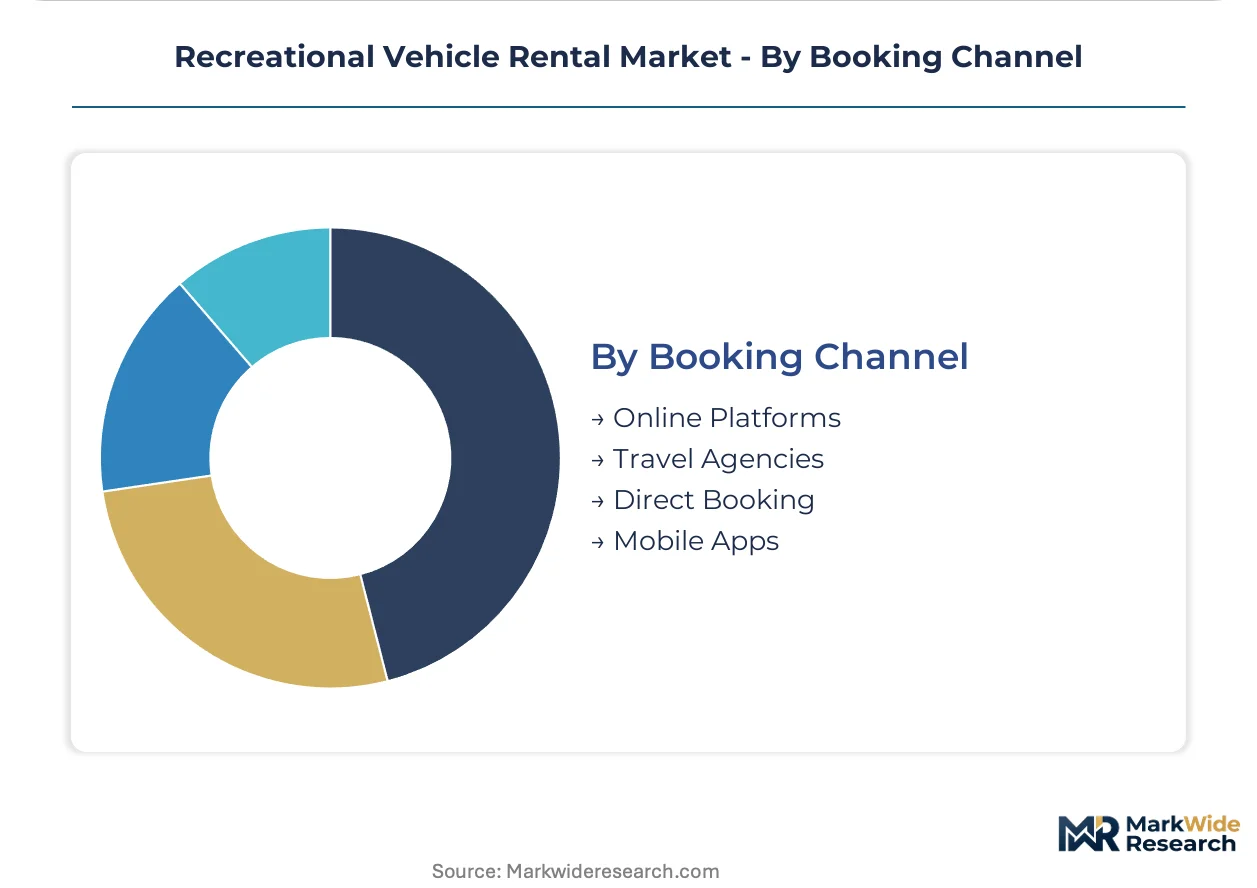
Booking Channel:
Supply concentration patterns concentrate inventory ownership in direct channels while marketplace models aggregate fragmented private fleet supply.
- Online Platforms:Aggregator websites consolidate multi-operator inventory comparison with standardized cancellation policies.
- Travel Agencies:Package bundling with airfare and lodging retains relevance in international inbound segments.
- Direct Booking:Operator-owned websites and call centers defend repeat customer loyalty through fleet consistency guarantees and membership programs.
- Mobile Apps:Instant-confirmation interfaces capture compressed booking lead times among spontaneous itinerary planners.
Direct booking maintains the highest customer lifetime value. Mobile apps are gaining share fastest as peer-to-peer marketplaces prioritize host onboarding velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Family vacationers concentrate demand in western US national park corridors, while European adventure travelers drive camper van utilization across Iberian and Alpine routes. Fleet operators reposition assets seasonally to capture these divergent buyer archetypes.
United States
Yellowstone-Grand Teton and Utah's Mighty Five corridors anchor multi-generational family demand for Class A motorhomes. EPA Tier 3 emissions standards compress diesel fleet replacement cycles above 26,000 pounds GVWR. Denver and Salt Lake City serve as seasonal hub repositioning nodes for western corridor operators.
Germany
Alpine route tourism and Oktoberfest event-driven rentals elevate camper van utilization across Bavaria and Baden-Württemberg. KBA vehicle classification requirements govern commercial operator licensing for larger motorhome categories. Munich and Stuttgart concentrate fleet maintenance infrastructure for cross-border European corridor operations.
Canada
Rocky Mountain national park access drives extended-stay motorhome demand from Calgary and Vancouver gateway cities. Transport Canada CMVSS safety standards align with US FMVSS protocols for cross-border fleet interoperability. Banff and Jasper corridor operators coordinate seasonal hub repositioning with US western networks.
Australia
Coastal highway tourism and Outback adventure routes elevate camper van and motorhome utilization across Queensland and Western Australia. Australian Design Rules govern vehicle safety compliance for commercial rental classifications. Brisbane and Perth serve as seasonal repositioning hubs for east-west corridor operations.
France
Provence-Alpes-Côte d'Azur seasonal tourism and pilgrimage route travel drive camper van demand among European adventure seekers. ANSM vehicle safety oversight applies to commercial fleet modifications and insurance classifications. Lyon and Marseille anchor Alpine-to-Mediterranean corridor repositioning networks.
Recreational Vehicle Rental Market Competitive Environment
Player mix skews toward asset-light marketplace platforms and vertically integrated fleet operators with owned-branch networks. Structure concentrates around three archetypes: peer-to-peer aggregators reducing host capital barriers, national fleet operators with maintenance infrastructure, and regional specialists dominating corridor-specific routes. Dominant competitive moves include seasonal hub repositioning for utilization optimization and telematics-enabled predictive maintenance deployment.
Within the vertically integrated tier, Cruise America exemplifies national fleet operators with captive maintenance infrastructure, while Outdoorsy occupies the peer-to-peer aggregator position reducing capital intensity for private hosts. Indie Campers represents the regional corridor specialist archetype with seasonal European hub repositioning capabilities.
| Leading Market Players |
|---|
| Cruise America |
| Outdoorsy |
| RVshare |
| El Monte RV |
| Apollo RV Holidays |
| Road Bear RV |
| McRent |
| Indie Campers |
| Escape Campervans |
| Others |
Value Chain & Pricing Dynamics
FMVSS 208 occupant crash protection certification gates both fleet qualification and daily rate stratification simultaneously, concentrating pricing power among compliant operators while elevating procurement barriers for uncertified entrants seeking liability coverage access.
Pricing Analysis
Cost-plus contracts with chassis indexation dominate motorhome procurement agreements, with Ford and Mercedes-Benz commercial van pricing tethered to steel and semiconductor commodity movements. Three-tier pricing structure across premium, standard, and economy levels separates FMVSS 208-certified Class A fleets from uncertified inventory and peer-to-peer host supply. Cost compression in the electrified motorhome tier is intensifying because battery pack input volatility outpaces OEM price stabilization. Adventure-seeking couples in the camper van segment exhibit highest price sensitivity, while multi-generational families booking extended-stay motorhomes demonstrate lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from European chassis manufacturers through Rotterdam and Hamburg port congestion have elevated lead times for Mercedes-Benz Sprinter and Fiat Ducato base platforms. Fleet manufacturing concentrates in Germany, the United States, and Canada, with final upfitting anchored in Elkhart, Indiana and RV manufacturing clusters across Ontario and British Columbia. Raw material dependencies span aluminum body panels, lithium-ion battery packs, and EPA-compliant exhaust after-treatment systems. Single-source vulnerability sits with specialized RV appliance suppliers for refrigeration and climate control units. Distribution runs through owned-branch networks for integrated operators and digital marketplace aggregation for peer-to-peer supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 3 emissions standards and electrification mandates constitute a dual regulatory inflection that will reshape fleet economics and competitive positioning across the analysis window.
For Market Incumbents: Compound fleet compliance advantages by accelerating FMVSS 208 certification coverage across remaining uncertified inventory before liability coverage access further consolidates. Expand captive maintenance infrastructure into Denver and Salt Lake City hub nodes to defend utilization rates against peer-to-peer host supply growth in western corridor markets. Prioritize backward integration into telematics-enabled predictive maintenance systems to compress vehicle out-of-service intervals below marketplace rivals. For New Entrants and Emerging Players: Differentiate on instant-confirmation mobile interfaces that capture compressed booking lead times among spontaneous adventure travelers in Pacific Northwest and Colorado destination markets. Target the underpenetrated monthly remote-worker segment with furnished mobility alternatives to traditional housing, leveraging IRA clean vehicle tax credits to offset electrified fleet procurement costs. Deploy host onboarding velocity as the primary go-to-market angle to outpace established peer-to-peer marketplace supply growth. For Investors and Strategic Acquirers: EPA heavy-duty vehicle emissions sunset dates reshape the acquisition landscape toward operators with electrification-ready fleet portfolios and site-specific charging installation partnerships in western national park corridors. Long-term viability centers on asset-light marketplace models with host density network effects or vertically integrated operators with seasonal hub repositioning capabilities. Monitor FMVSS 208 compliance timeline compression as the signal indicating certification testing bottleneck severity and fleet expansion velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Seasonal Hub Repositioning | Maximizes vehicle utilization rates across Yellowstone-Grand Teton and Utah Mighty Five corridor routes. |
| Telematics Predictive Maintenance Deployment | Decomposes reactive service models into condition-based protocols across dispersed branch networks. |
| EV Charging Infrastructure Partnership | Addresses destination market gaps before battery-electric vehicle fleet commitment. |
| Peer-to-Peer Host Onboarding Acceleration | Reduces capital intensity versus asset-heavy rivals in high-demand western corridors. |
| FMVSS 208 Certification Completion | Secures liability coverage access and interstate operating authority for fleet expansion. |
Study Parameters
A standing panel of fleet operations directors, peer-to-peer marketplace host acquisition managers, RV manufacturer procurement leads, and commercial insurance underwriters provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from NHTSA FMVSS certification databases, EPA emissions compliance filings, and state Department of Transportation commercial operator classifications. Customs and trade data, RV Industry Association shipment reports, and SEC 10-K disclosures from publicly traded fleet operators anchored supply-side quantification. Bottom-up fleet inventory analysis triangulated against top-down booking volume estimates from digital marketplace disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning vehicle configuration, rental duration tier, customer archetype, and booking channel preference. CAGRs derived from logistic diffusion curves fitted to electrification adoption patterns and regulatory compliance timelines. Industry-specific forecast inputs incorporated EPA Tier 3 replacement cycle acceleration and peer-to-peer supply elasticity estimates from host onboarding protocol analysis.
The analysis sits within stated boundaries; outcomes outside sustained family vacationer demand expansion or charging infrastructure deployment pace would require recalibration. Forecasts reflect assumptions regarding FMVSS 208 testing bottleneck resolution and battery pack input cost stabilization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Segway Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Europe Personal Watercraft Market