
 Kick Scooter Market | 2026-2036
Kick Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Kick Scooter Market Analytics
Young adult commuters is collapsing the historical dominance of recreational child buyers in the kick scooter category. Xiaomi Corporation leverages its consumer electronics supply chain to dominate the electric sub-segment with aggressive cost engineering. Segway, Inc. (Ninebot) anchors the premium tier through its proprietary self-balancing technology and fleet-grade durability. Bird Rides, Inc. competes via shared-service deployments across dense urban corridors, converting trial users into private purchasers.
A kick scooter comprises a footboard mounted between two or more wheels, with an upright steering column and handlebar assembly, typically constructed from aluminum alloy tubing with polyurethane or pneumatic tires rated for loads between 100 kg and 150 kg depending on design class. The device serves as a human-propelled or motor-assisted micro-mobility platform for short-distance personal transport in urban and suburban environments. Electric variants lead value generation due to battery integration and motor controller complexity, while folding mechanisms capture the fastest volume growth among commuters requiring multimodal transit compatibility. Aluminum construction dominates the material mix for its strength-to-weight ratio, though composite frames gain traction in performance-oriented stunt and premium segments where torsional rigidity matters.
The EU Green Deal and associated national low-emission frameworks shape product standards by mandating recyclability thresholds and restricting hazardous substances in battery packs under REACH and RoHS directives. The US Consumer Product Safety Commission and ASTM International govern mechanical safety and labeling requirements, directly influencing market access for imported units. City-level micro-mobility permitting regimes in Berlin, Barcelona, and San Francisco determine fleet operator viability and indirectly steer private purchase patterns through infrastructure investment. Stakeholders must monitor evolving battery certification mandates and sidewalk-riding restrictions that will determine which product configurations retain legal operability in priority markets.
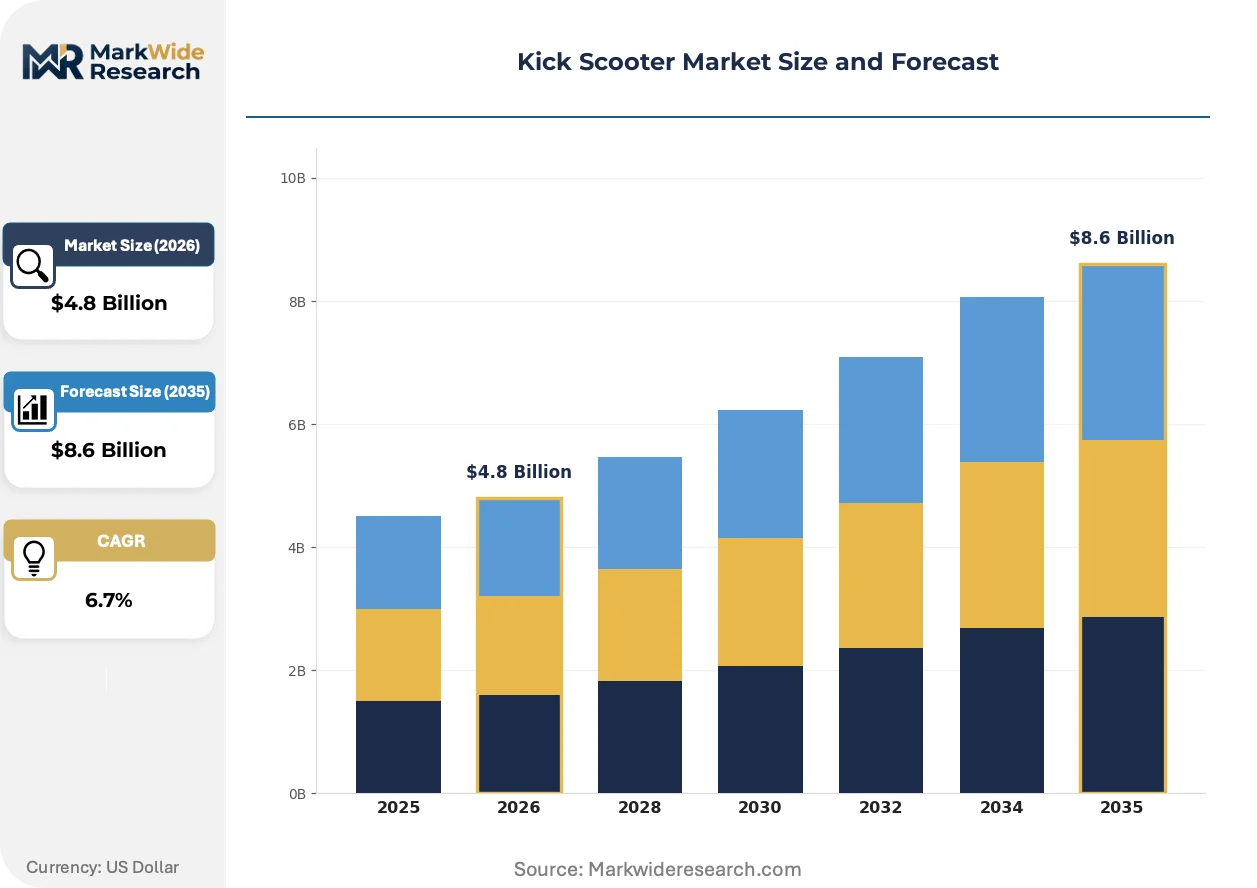
Market Dynamics
Urban micro-mobility infrastructure investment is compressing last-mile transport economics, redirecting commuter spend from public transit toward personal electric devices. Battery energy density improvements and dedicated lane construction in metropolitan cores are converging to normalize kick scooters as primary commute tools rather than recreational accessories.
Growth Catalysts
- EU Green Deal low-emission mandates:National frameworks in France, Netherlands, and Denmark restrict combustion vehicles in city centers, redirecting commuter flow toward light electric alternatives. Fleet operators and private buyers respond to infrastructure subsidies.
- Lithium-ion cell cost engineering:Battery pack integration costs decline as cylindrical cell formats standardize across consumer electronics supply chains. Electric kick scooter manufacturers capture margin expansion from shared component sourcing.
- Germany's multimodal transit integration:Deutsche Bahn and municipal operators permit folded devices on trains and trams without surcharge, collapsing friction between first-mile scooter segments and rail networks.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing hub motor manufacturers to export quota volatility and price spikes.
- Sidewalk-riding prohibition friction:Municipal ordinances in Barcelona, San Francisco, and Paris impose fines and confiscation protocols that suppress trial adoption among risk-averse commuter segments.
- Aluminum alloy input cost sensitivity:LME aluminum price volatility directly compresses frame manufacturer margins, forcing either pass-through pricing or specification downgrades on entry-tier products.
Strategic Opportunities
- India's urban last-mile gap:Metro rail expansion in Delhi, Mumbai, and Bangalore creates multimodal transfer points lacking adequate feeder connectivity. Local assembly partnerships circumvent import duty structures.
- Swappable battery standardization:Interoperable pack formats across fleet operators reduce downtime and capital intensity. TIER Mobility and Lime pilot cross-compatible docking networks in Berlin and Copenhagen.
- REACH recyclability thresholds:EU battery passport requirements create first-mover advantage for manufacturers with established closed-loop collection infrastructure and modular cell architectures.
Industry Challenges
- IP fragmentation in folding mechanisms:Patent thickets around hinge geometry and latch systems trigger licensing disputes between incumbent manufacturers and new market entrants, delaying product launches.
- Firmware-hardening skill scarcity:Motor controller programming and battery management system calibration require embedded systems expertise that concentrates in Shenzhen and Taipei talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kick Scooter Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Folding, Stunt, Traditional Target Group: Adults, Kids, Commuters, Recreational Users Material: Aluminum, Steel, Plastic, Composite Feature: Adjustable Handlebar, Shock Absorption, LED Lights, Weight Capacity |
| Companies Covered | Bird Rides, Inc., Golabs, Inc. (GOTRAX), Xiaomi Corporation, Zhejiang Okai Vehicles Co., Ltd., Jiangsu Xinri E-Vehicle Co., Ltd., Yadea Technology Group Co., Ltd., Swagtron, Lime, Segway, Inc. (Ninebot), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kick Scooter Market Evolving Landscape
Component integration is compressing device footprints while expanding functional density, collapsing the distinction between premium and mass-market feature sets. Manufacturers compete on software-defined performance rather than raw mechanical specifications.
GaN-based motor controllers are miniaturizing power electronics packaging, enabling higher switching frequencies with reduced thermal mass. Tier-one suppliers in Taiwan and South Korea deploy these semiconductors across mid-tier and premium electric kick scooter lines. The resulting powertrain density allows frame designers to reclaim space for larger battery packs without extending wheelbase dimensions.
REACH battery passport mandates force supply chain transparency down to cell chemistry and cobalt provenance. European manufacturers face compliance deadlines that favor vertically integrated producers with captive recycling partnerships. The premium segment absorbs certification costs through pricing power, while entry-tier importers confront market access barriers.
Subscription-based ownership models displace outright purchase among urban millennials and Gen Z commuters in Berlin, Amsterdam, and Stockholm. Grover and Swapfiets bundle maintenance, theft insurance, and upgrade rights into monthly fees. Fleet operators and direct-to-consumer brands both pilot these structures to capture lifetime value and reduce customer acquisition friction.
Kick Scooter Market Segmentation
Kick scooter manufacturers navigate divergent performance requirements across commuter infrastructure, recreational terrain, and shared fleet duty cycles. Segmentation reveals where battery integration, frame durability, and portability specifications create pricing power versus commoditization pressure.
Product Type:
Substitution pressure from e-bikes and bike-sharing networks concentrates heaviest on traditional human-propelled segments, while electric variants defend share through last-mile autonomy.
- Electric:Hub motor architectures rated between 250W and 500W integrate lithium-ion packs with battery management systems calibrated for regenerative braking. Demand clusters in Germany, France, and Netherlands where EU Green Deal subsidies collapse acquisition costs for urban commuters facing low-emission zone restrictions.
- Folding:Hinge mechanisms employing 6061-T6 aluminum latches enable collapsed footprints under 120cm for multimodal transit compatibility. Deutsche Bahn's surcharge-free carriage policy accelerates adoption among Berlin and Munich rail commuters bridging first-mile gaps.
- Stunt:Chromoly steel or 7000-series aluminum frames with reinforced head tubes withstand repeated impact loads from skatepark and street riding.
- Traditional:Fixed-frame designs with polyurethane wheels serve price-sensitive recreational buyers and emerging market entry segments.
Folding retains volume leadership; Electric holds the steepest expansion curve.
Target Group:
Cost tier stratification separates fleet-grade durability investments from disposable recreational purchases, with commuter segments absorbing premium pricing for theft-resistant designs.
- Commuters:Daily-use specifications demand IP54 ingress protection, pneumatic tires, and integrated lighting systems compliant with KBA visibility standards. Amsterdam and Copenhagen infrastructure investments redirect modal share from public transit toward personal electric devices.
- Adults:Load ratings exceeding 120kg and ergonomic deck geometries accommodate fitness-oriented leisure riders and short-distance neighborhood transport.
- Kids:Lower deck heights, three-wheel stability configurations, and 50kg load limits align with pediatric safety standards enforced by US CPSC and EU toy safety directives.
- Recreational Users:Occasional-use buyers prioritize color customization and collapsibility over motor power or suspension travel.
Commuters command margin concentration; Adults deliver the most stable replacement cycle visibility.
Material:
Supply concentration in Chinese aluminum smelting and Taiwanese composite fabrication shapes regional cost competitiveness and tariff exposure.
- Aluminum:6061-T6 and 7005 alloys deliver strength-to-weight ratios of 180-200 kN·m/kg, enabling sub-12kg folding electric frames. LME price volatility directly compresses manufacturer margins, forcing specification trade-offs in entry-tier products.
- Composite:Carbon fiber reinforced polymer frames from Taichung suppliers achieve torsional rigidity benchmarks for stunt and premium commuter segments where gram reduction justifies 3-4x material cost premiums.
- Steel:Chromoly tubing dominates stunt applications requiring impact absorption beyond aluminum fatigue limits.
- Plastic:Glass-filled nylon decks and fenders reduce unit costs in child-oriented and shared fleet disposable segments.
Aluminum dominates volume; Composite captures the most rapid share gains in performance tiers.
Feature:
Application-specific durability requirements separate fleet-grade feature bundling from recreational minimalism, with regulatory mandates forcing baseline specification upgrades.
- Shock Absorption:Front fork suspension with 40-60mm travel and rear elastomer damping systems reduce rider fatigue on cobblestone surfaces prevalent in historic European city centers. Paris and Barcelona sidewalk-riding prohibitions redirect demand toward vibration-isolated designs tolerant of rough asphalt.
- LED Lights:Front white and rear red illumination meeting StVZO German road traffic standards enables legal night operation where municipal ordinances mandate visibility equipment.
- Adjustable Handlebar:Telescoping stem mechanisms accommodate rider heights from 150cm to 200cm, expanding addressable household penetration.
- Weight Capacity:Reinforced deck structures rated to 150kg serve commercial delivery contractors and heavier riders excluded from standard 100kg specifications.
Shock Absorption leads feature prioritization; LED Lights face the most steepening regulatory compliance trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply battery packs and hub motors to European and North American assemblers, while Southeast Asian hubs handle aluminum frame fabrication for cost-sensitive export tiers.
Germany
KBA visibility standards and StVZO road traffic regulations mandate integrated lighting and brake systems for street-legal operation. The EU Green Deal channels infrastructure subsidies toward dedicated micro-mobility lanes in Berlin and Munich. Deutsche Bahn's surcharge-free carriage policy for folded devices accelerates multimodal adoption among rail commuters bridging first-mile gaps.
United States
ASTM International safety standards and CPSC mechanical requirements govern import access and product liability exposure. Municipal permitting regimes in San Francisco and Austin determine shared fleet operator density and indirectly steer private purchase patterns. California's CARB low-emission frameworks extend indirect support through transit-oriented development incentives.
China
MIIT battery certification mandates and GB standards for electric two-wheelers shape export-ready product configurations. Shenzhen and Dongguan industrial clusters concentrate firmware development and motor controller production for global OEM supply. Domestic demand concentrates in Hangzhou and Chengdu where metro expansion creates last-mile transfer friction.
France
ANSM and national low-emission zone policies in Paris restrict combustion vehicle access, redirecting commuter flow toward light electric alternatives. The EU Green Deal recyclability thresholds under REACH force supply chain transparency down to cell chemistry provenance. Lyon and Bordeaux micro-mobility infrastructure investments normalize kick scooters as primary commute tools rather than recreational accessories.
India
Metro rail expansion in Delhi, Mumbai, and Bangalore creates multimodal transfer points lacking adequate feeder connectivity. BIS safety standards and DGFT import duty structures favor local assembly partnerships over direct import. The PLI scheme for advanced chemistry cell manufacturing reduces battery pack costs for domestic electric kick scooter assemblers.
Kick Scooter Market Competitive Landscape
Listed leaders compete with private specialists across capital access and fleet deployment scale. The vendor base stratifies into three tiers: multinational electronics conglomerates with consumer product supply chains, dedicated micro-mobility pure-plays with fleet-grade durability expertise, and regional fabricators serving price-sensitive emerging markets. Consolidation pressure concentrates in the middle tier where scale thresholds for battery procurement and firmware development are rising. Dominant competitive moves include geographic licensing partnerships for regulatory compliance and backward integration into motor controller design.
Within the multinational electronics tier, Xiaomi Corporation and Segway, Inc. (Ninebot) occupy positions shaped by supply chain depth and proprietary technology portfolios. Among fleet-service pure-plays, Bird Rides, Inc. exemplifies the shared-deployment-to-private-purchase conversion model. These three anchors represent divergent strategic archetypes: cost-engineered consumer electronics penetration, premium-tier self-balancing technology leverage, and urban corridor trial-user acquisition.
| Leading Market Players |
|---|
| Bird Rides, Inc. |
| Golabs, Inc. (GOTRAX) |
| Xiaomi Corporation |
| Zhejiang Okai Vehicles Co., Ltd. |
| Jiangsu Xinri E-Vehicle Co., Ltd. |
| Yadea Technology Group Co., Ltd. |
| Swagtron |
| Lime |
| Segway, Inc. (Ninebot) |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for lithium-ion cylindrical cells lock in both battery pack supply access and cost visibility for electric kick scooter assemblers, insulating procurement teams from spot-market cobalt and nickel volatility while compressing margin uncertainty across the forecast period.
Pricing Analysis
Current-generation 21700-format battery packs command 15-20% premiums over legacy 18650 configurations due to energy density gains, while next-generation solid-state prototypes remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates fleet-grade durability investments from recreational disposable units. Pricing pressure stems from aluminum alloy LME volatility forcing frame manufacturers toward specification downgrades or pass-through surcharges. Fleet operators exhibit the highest price sensitivity due to capital intensity and replacement cycle compression, while commuter segments absorb premiums for theft-resistant designs and extended warranties.
Supply Chain Analysis
Neodymium magnet processing capacity in China's Inner Mongolia and Jiangxi provinces creates a chokepoint for hub motor manufacturers, exposing European and North American assemblers to export quota disruptions. Shenzhen and Dongguan industrial clusters concentrate firmware development and motor controller production, while Taichung suppliers dominate carbon fiber frame fabrication for premium segments. Supply chain risk centers on single-source vulnerability for rare earth processing and battery management system chipsets. Distribution runs through direct-to-consumer e-commerce channels and fleet operator procurement desks, with retail brick-and-mortar collapsing to test-ride showrooms in major metropolitan cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems firmware expertise concentrates in Shenzhen and Taipei talent pools, creating a capability bottleneck that determines which manufacturers can deliver software-defined performance upgrades without external engineering dependencies.
For Market Incumbents: Shield margin structures by securing captive recycling partnerships ahead of EU battery passport mandates, while accelerating in-house production of motor controllers to reduce dependency on Taiwanese semiconductor distributors facing allocation constraints from shared electronics supply chains. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission consultations opens access to German and French urban commuter segments where infrastructure subsidies collapse acquisition friction. Target India's metro rail feeder gaps through local assembly partnerships that circumvent DGFT duty structures, leveraging the PLI scheme for advanced chemistry cell manufacturing. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated assemblers with established closed-loop collection infrastructure and modular battery architectures that absorb REACH recyclability compliance costs without pricing power erosion. Watch swappable battery standardization pilots in Berlin and Copenhagen as the inflection signal for capital-light fleet operator viability.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Standardization | Cross-compatible docking networks reduce fleet downtime and capital intensity across Berlin and Copenhagen deployments. |
| Backward Integration into Motor Controllers | In-house GaN-based power electronics design reclaims margin from Taiwanese semiconductor distributors facing allocation constraints. |
| Local Assembly Partnerships | Indian domestic production circumvents DGFT import duties while capturing PLI scheme subsidies for advanced chemistry cells. |
| Closed-Loop Recycling Infrastructure | EU battery passport compliance creates first-mover advantage through established collection networks and modular cell architectures. |
| Subscription Ownership Models | Grover and Swapfiets bundles capture lifetime value among Berlin and Amsterdam millennials seeking maintenance-inclusive mobility. |
Research Methodology
Desk research of customs trade records, MIIT battery certification filings, and EU Green Deal subsidy disbursement databases preceded structured interviews with fleet operations directors, Tier 1 motor controller procurement managers, and municipal micro-mobility permitting officers. Primary fieldwork across Berlin, Shenzhen, and Mumbai validated secondary data on infrastructure investment timelines and import duty structures. Bottom-up unit economics modeling triangulated against top-down market sizing from aluminum alloy consumption and lithium-ion pack shipment data.
Variance decomposition across product type, target group, material grade, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against macroeconomic mobility indicators and infrastructure spend commitments. Modeled inputs included Deutsche Bahn multimodal integration policy enforcement, REACH recyclability threshold implementation schedules, and neodymium magnet export quota volatility scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal subsidy continuity and aluminum price band stability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as sidewalk-riding prohibition enforcement and battery passport compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market