
 Camping Trailer Market | 2026-2036
Camping Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Trailer Market Intelligence
Fragmentation of the customer base towards younger demographics and solo travelers is expanding the addressable market for camping trailers. This shift creates opportunities beyond the traditional family segment. Thor Industries leverages its extensive brand portfolio to cover multiple price points and consumer profiles. Forest River sustains a dominant manufacturing scale, enabling cost efficiencies and broad dealership networks. In contrast, SylvanSport specializes in lightweight, multi-functional trailers targeting adventure sports enthusiasts.
A camping trailer is a non-motorized recreational vehicle designed to be towed by a passenger car, SUV, or truck. These units are built on a steel or aluminum chassis with single or tandem axle configurations, providing temporary living quarters for travel. Within the product landscape, traditional Travel Trailers and Fifth-Wheel Trailers command the largest share of sales. However, lightweight Teardrop Trailers and Pop-up Trailers are experiencing high interest due to their affordability and compatibility with smaller tow vehicles.
Product design and market access are governed by stringent safety regulations. The U.S. National Highway Traffic Safety Administration (NHTSA) mandates specific standards for braking, lighting, and tires. Similarly, Germany's Kraftfahrt-Bundesamt (KBA) and Australia's Vehicle Safety Standards (ADRs) impose strict roadworthiness requirements. Manufacturers must navigate these varied international standards while innovating on features and materials to meet consumer expectations.
Market Dynamics
The central force shaping the camping trailer market is the imperative for lightweight design, driven by the rise of electric vehicles as tow cars. This necessitates a fundamental shift in material science and chassis engineering to maintain utility while reducing gross vehicle weight, expanding the addressable consumer base.
Growth Catalysts
- Domestic Tourism Policies:Government support for domestic travel in markets like Australia provides a direct stimulus, encouraging consumers to invest in recreational vehicles for local holidays and exploration.
- Lightweight Composites:The adoption of advanced materials like bonded fiberglass and aluminum superstructures enables the production of trailers towable by a wider range of smaller SUVs and passenger cars.
- Demographic Expansion:Growing interest from solo travelers and younger consumers creates demand for smaller, more affordable products like teardrop and pop-up trailers, expanding the market beyond traditional family buyers.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of core materials, specifically aluminum for frames and steel for chassis, create margin pressure and make final product pricing unpredictable for manufacturers.
- Regulatory Fragmentation:Navigating disparate safety standards, such as those from the NHTSA in the United States and the KBA in Germany, increases design, testing, and compliance costs for global manufacturers.
- Substitution from Motorized RVs:The growing popularity of compact, self-contained Class B camper vans presents a significant alternative, appealing to consumers who prefer an integrated driving and living unit.
Strategic Opportunities
- Underpenetrated Geographies:Emerging outdoor recreation markets in South America and Eastern Europe present significant growth potential as camping culture develops and disposable incomes rise.
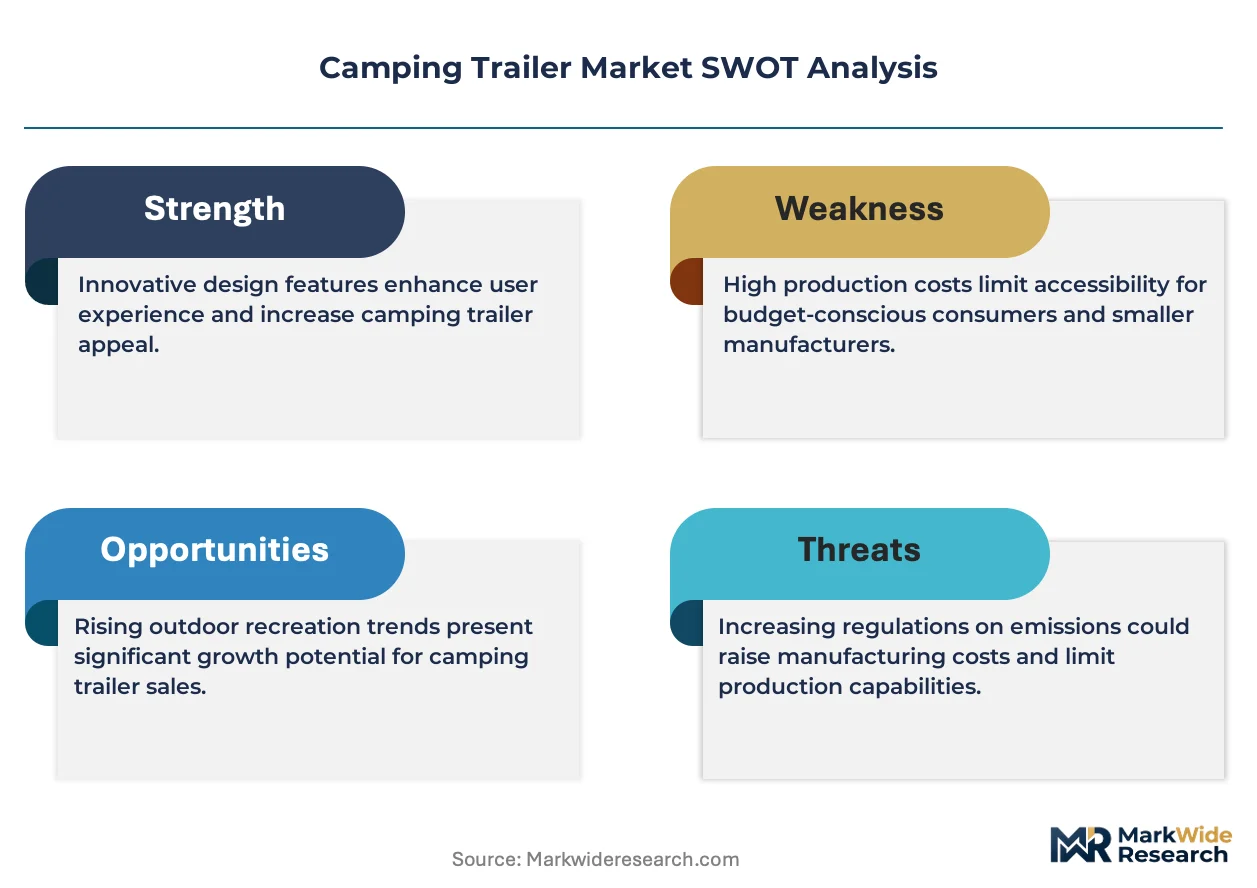
- Smart Trailer Integration:Incorporating IoT-enabled systems for power management, climate control, and security offers a clear path for product differentiation, appealing to a tech-savvy consumer segment.
- Direct-to-Consumer Channels:Developing online configurators and direct sales models can bypass traditional dealership networks, reducing costs and reaching niche buyers interested in customized or modular trailers.
Industry Challenges
- Skilled Labor Scarcity:Manufacturers face shortages of technicians skilled in composite material fabrication, advanced electrical systems, and plumbing, which can constrain production capacity and quality control.
- Component Supply Chain Bottlenecks:Reliance on a global network of suppliers for specialized components like axles, appliances, and windows exposes production schedules to significant disruption and delays.
- Certification Lead Times:The lengthy and costly process of achieving roadworthiness certification under varied international frameworks, such as Australia's ADRs, can slow the introduction of new and innovative models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Trailer Market |
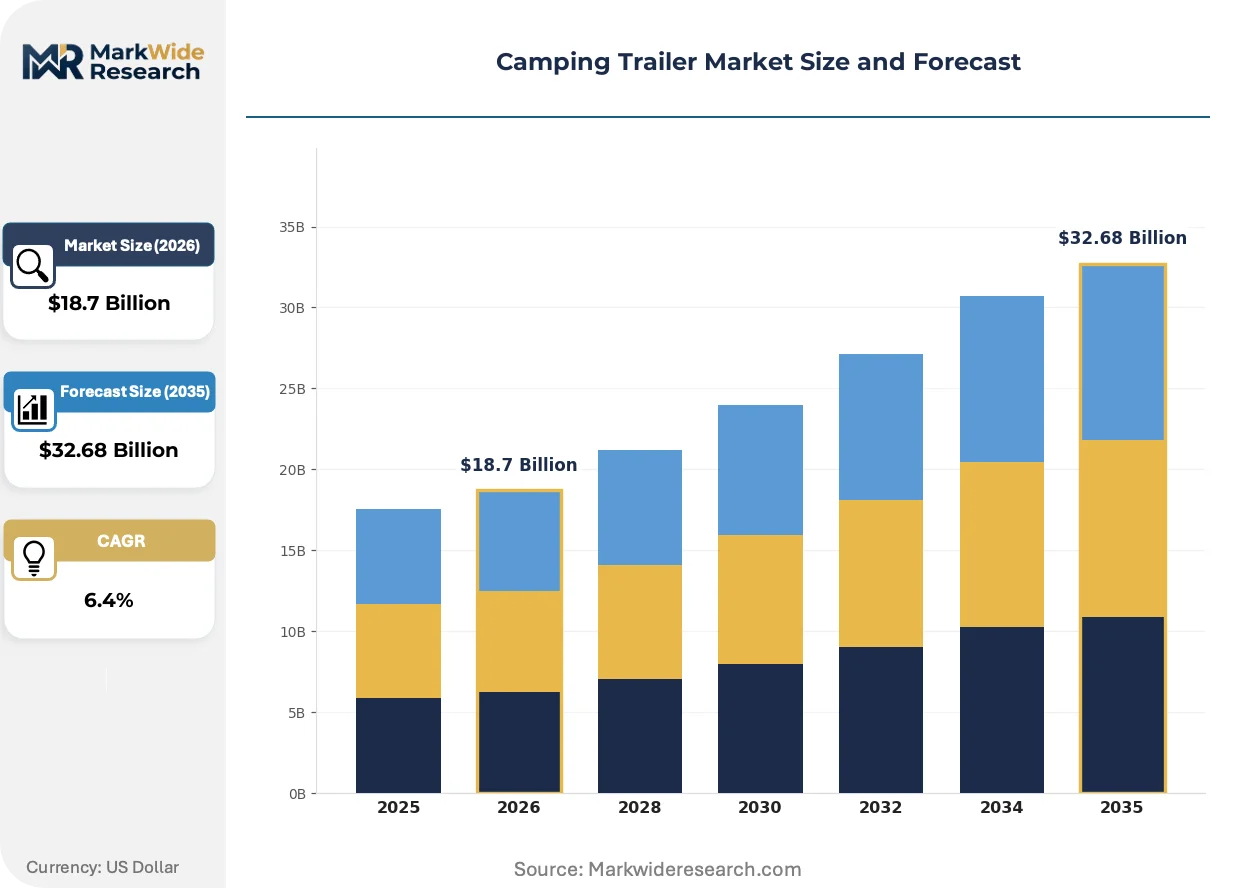
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pop-up Trailers, Fifth-Wheel Trailers, Travel Trailers, Toy Haulers, Teardrop Trailers Material: Aluminum, Fiberglass, Steel, Composite, Wood End User: Outdoor Enthusiasts, Family Campers, Adventure Seekers, Glamping Resorts, Wildlife Researchers Distribution Channel: Dealerships, Online Retailers, Rental Services, Specialty Stores, Mobile Sales Units |
| Companies Covered | Forest River, Aliner, SylvanSport, Thor Industries, Grand Design RV, Winnebago Industries, Keystone RV, Airstream, Dutchmen RV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Trailer Market Strategic Shifts & Innovations
Electrification compatibility and the pursuit of off-grid autonomy are the primary forces guiding product innovation. This dual focus drives advancements in lightweight materials to reduce the burden on electric tow vehicles and integrated solar power systems to extend independent use.
Advanced composite materials, including bonded fiberglass panels and carbon fiber reinforcements, deliver exceptional strength-to-weight ratios. These materials are being adopted by manufacturers targeting the growing segment of electric and smaller SUV owners. This material science evolution is rewriting the rules of vehicle compatibility and towing efficiency for the entire towable RV category.
European Union regulations promoting vehicle electrification and lower emissions indirectly shape trailer design priorities. This regulatory environment compels manufacturers to emphasize aerodynamics and lightweight construction to minimize the range penalty on electric tow vehicles. The teardrop and pop-up trailer segments are most impacted, seeing accelerated innovation in low-drag profiles to meet these green mobility expectations.
A significant behavioral shift is the consumer preference for shorter, more frequent excursions over traditional extended seasonal holidays. This pattern disrupts the dealership model focused on large, high-cost travel trailers, creating an opening for rental platforms and subscription-based access to smaller models. This trend is most prominent in urban-adjacent outdoor markets across North America and Europe.
Camping Trailer Market Segmentation
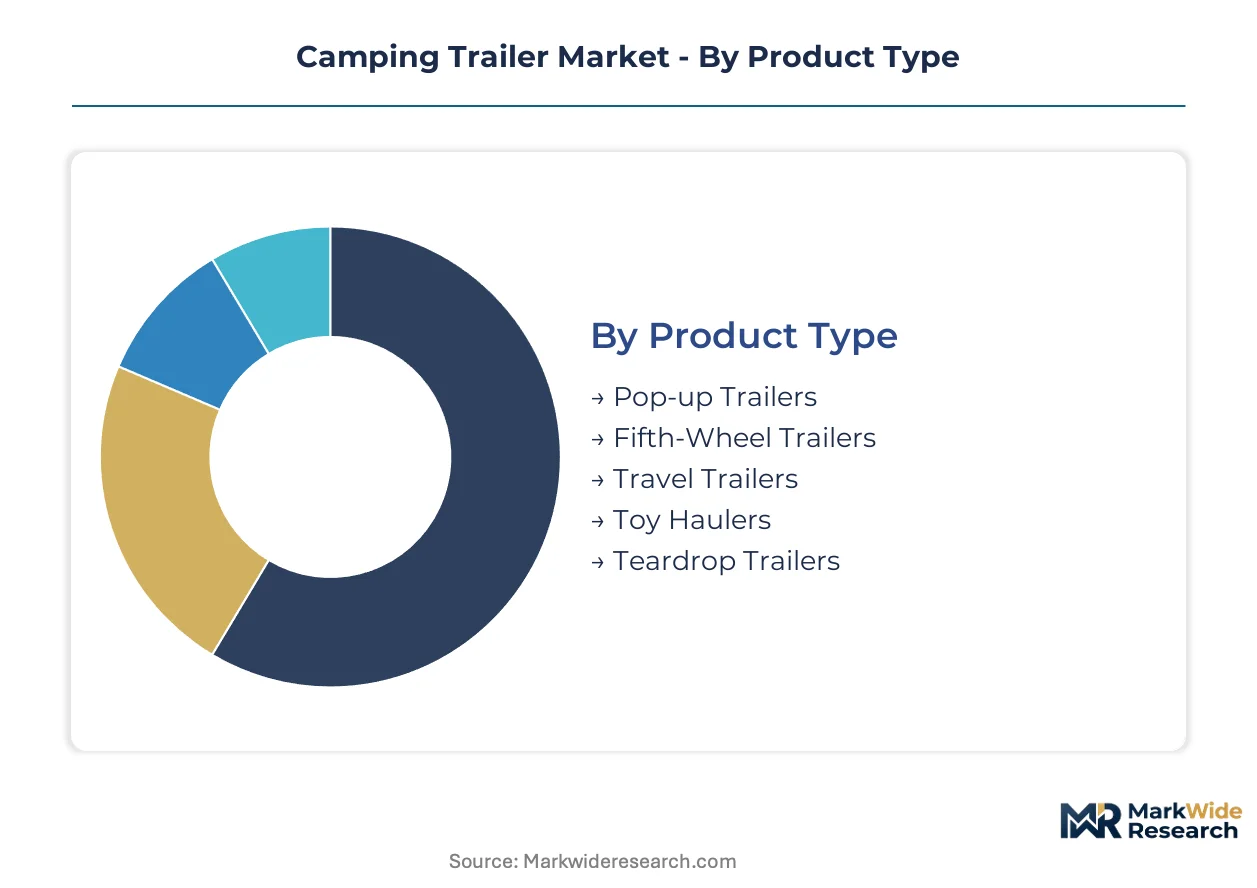
The camping trailer market exhibits diverse consumer preferences and product functionalities, necessitating a granular segmentation to understand specific demand drivers and competitive dynamics. This analysis dissects the market across key dimensions, revealing areas of concentrated investment and emerging growth trajectories for manufacturers.
Product Type:
Product type segmentation highlights the varying capital intensity required for manufacturing different trailer designs.
- Travel Trailers:These non-motorized recreational vehicles offer comprehensive living amenities, designed for extended stays and family use. Demand concentrates in North America and Australia, driven by established camping cultures and a preference for spacious, home-like accommodations.
- Fifth-Wheel Trailers:Distinguished by their distinctive hitching mechanism that overlaps the towing vehicle's bed, these trailers provide enhanced stability and often larger interior volumes. Their popularity in the United States stems from the prevalence of heavy-duty pickup trucks and consumer desire for luxury features.
- Pop-up Trailers:These compact, collapsible units feature fabric sides and a hard roof, offering affordability and easy storage for occasional campers.
- Toy Haulers:Designed with integrated garage space, these trailers transport recreational vehicles like ATVs or motorcycles, appealing to adventure sports enthusiasts.
- Teardrop Trailers:Characterized by their aerodynamic, compact design, these lightweight trailers are easily towable by smaller vehicles and target solo travelers or couples.
Most installed capacity flows through Travel Trailers. Expansion is steepest in Teardrop Trailers.
Material:
Material segmentation reflects the functional requirements and performance characteristics demanded by different end-user applications.
- Aluminum:Widely used for chassis and framing due to its high strength-to-weight ratio and corrosion resistance, enabling lighter trailer construction. Adoption is strong among manufacturers targeting fuel-efficient tow vehicles and markets with stringent weight regulations like Germany.
- Composite:Advanced materials like bonded fiberglass and carbon fiber offer superior strength, durability, and insulation properties while significantly reducing overall trailer weight. These materials gain traction in designs optimizing for electric vehicle compatibility and off-grid autonomy.
- Fiberglass:This material provides a durable, weather-resistant shell, favored for its moldability and ease of maintenance in many traditional trailer designs.
- Steel:Primarily used for chassis and structural components, steel offers robust strength and durability, particularly for larger or heavy-duty trailer applications.
- Wood:Employed for interior cabinetry and non-structural elements, wood contributes to a traditional aesthetic and offers good insulation properties.
Aluminum dominates the structural material landscape. Composite materials are gaining share fastest due to lightweight design imperatives.
End User:
End-user segmentation clarifies the diverse motivations and purchasing power that shape demand for camping trailers.
- Family Campers:This traditional segment seeks spacious, multi-berth trailers with amenities suitable for children and group activities. Demand remains consistent in mature markets such as Canada, where multi-generational outdoor recreation is a cultural norm.
- Adventure Seekers:This group prioritizes rugged, off-road capable trailers and compact, lightweight units for remote exploration. Interest is expanding in regions like South America, where extreme outdoor sports are becoming more accessible.
- Outdoor Enthusiasts:This broad segment includes individuals and groups who regularly engage in outdoor activities, often seeking versatile and durable trailers for various excursions.
- Glamping Resorts:Commercial entities utilize specialized, often luxurious, camping trailers to provide upscale outdoor accommodation experiences to their guests.
- Wildlife Researchers:Scientific teams require robust, self-sufficient trailers for extended stays in remote locations, prioritizing functionality and durability over luxury.
Family Campers represent a foundational demand base. Adventure Seekers are driving the most rapid expansion in specialized product categories.
Distribution Channel:
Distribution channel segmentation illustrates how product accessibility and sales velocity vary across different market entry points.
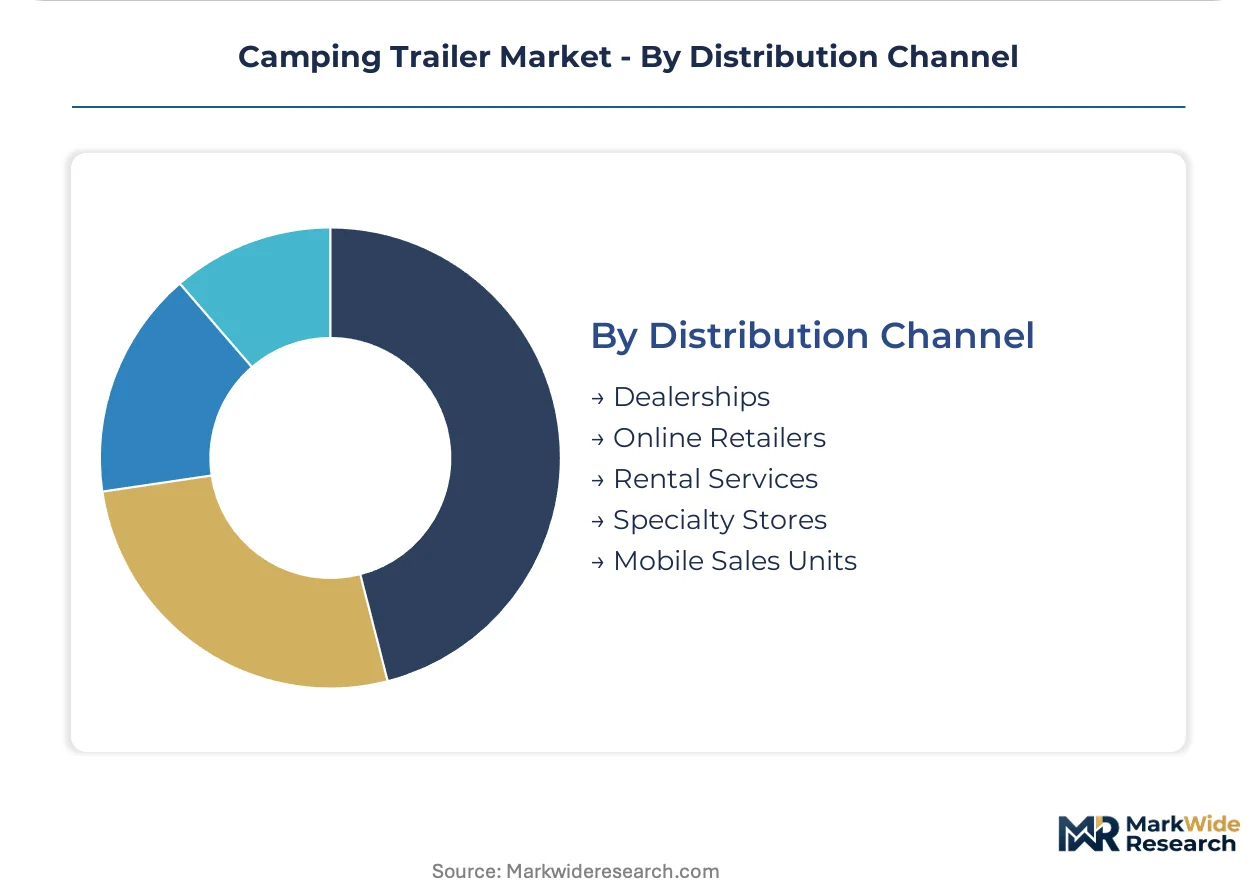
- Dealerships:Traditional brick-and-mortar outlets provide sales, financing, and maintenance services for a wide range of camping trailers. This channel remains central for larger, higher-value units, particularly in established markets like the United States.
- Rental Services:These platforms offer temporary access to trailers, appealing to consumers seeking flexibility or testing models before purchase. Their growth is notable in urban-adjacent outdoor markets across Europe, catering to shorter, frequent excursions.
- Online Retailers:E-commerce platforms facilitate direct sales and customization options, often targeting niche markets or offering smaller, more standardized trailer models.
- Specialty Stores:These outlets focus on specific trailer types, such as off-road models or teardrop trailers, providing expert advice and tailored product selections.
- Mobile Sales Units:Manufacturers or distributors use mobile setups to showcase trailers at events or remote locations, enhancing market reach and product visibility.
Dealerships maintain the largest volume of transactions. Rental Services are seeing the steepest expansion trajectory, driven by evolving consumer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States market prioritizes spacious, feature-rich travel trailers, Australia's robust domestic tourism policies drive strong demand for rugged, off-road capable models. These distinct preferences shape product development and regulatory compliance across different global markets. Manufacturers adapt designs to meet varied consumer expectations.
United States
United States consumers exhibit a strong preference for larger travel trailers and fifth-wheel models, supported by the widespread ownership of heavy-duty pickup trucks. The U.S. National Highway Traffic Safety Administration (NHTSA) enforces stringent safety standards for trailer components. Elkhart, Indiana, remains a significant manufacturing cluster, concentrating production capacity for these substantial units.
Australia
Australia's strong domestic tourism policies stimulate significant demand for durable, off-road camping trailers. The country's Vehicle Safety Standards (ADRs) dictate rigorous roadworthiness requirements for all imported and locally produced units. Victoria hosts a prominent manufacturing sector, specializing in rugged caravan designs tailored for challenging outback conditions.
Germany
German consumers increasingly seek lightweight and aerodynamic camping trailers compatible with electric tow vehicles. Germany's Kraftfahrt-Bundesamt (KBA) enforces strict roadworthiness and type approval regulations for all trailers. Bavaria demonstrates concentrated engineering expertise, driving advancements in composite materials and efficient trailer construction.
Brazil
Brazil represents an underpenetrated geography, where rising disposable incomes and a developing camping culture drive new demand for adventure-oriented trailers. The national transport agency (DENATRAN) governs vehicle safety and homologation for all towed units. São Paulo state shows nascent manufacturing activity, focusing on compact and affordable camping solutions.
Camping Trailer Market Key Industry Players
North American producers anchor one tier, focusing on scale and extensive brand portfolios, while European specialists hold niche positions with lightweight and innovative designs. The market exhibits a tiered structure, from large diversified conglomerates to specialized manufacturers. Three strategic archetypes emerge: volume manufacturers, premium innovators, and niche segment specialists. Companies pursue both portfolio diversification and geographic expansion to solidify their market positions.
At the scale-driven end, Thor Industries, Inc. represents the archetype of a diversified conglomerate, leveraging an extensive brand portfolio across multiple price points and consumer profiles. Forest River, Inc. exemplifies a volume manufacturer, maintaining a dominant manufacturing scale and broad dealership networks across North America. SylvanSport, LLC, conversely, sits within the niche segment specialist archetype, focusing on lightweight, multi-functional trailers specifically designed for adventure sports enthusiasts. These companies anchor distinct competitive strategies within the broader camping trailer market, catering to varied consumer demands.
| Leading Market Players |
|---|
| Forest River |
| Aliner |
| SylvanSport |
| Thor Industries |
| Grand Design RV |
| Winnebago Industries |
| Keystone RV |
| Airstream |
| Dutchmen RV |
| Others |
Cost & Logistics Intelligence
Electric vehicle integration necessitates fundamental material science shifts, and this demand-side pressure requires supply chains to reconfigure for lightweight components, impacting final product pricing.
Pricing Analysis
Capacity additions in North America are reshaping price floors for high-volume travel trailers. Per-unit transactional pricing dominates the market, with price differentiation stemming from customization levels and brand premium, particularly for luxury models. Pricing softness reflects increased competition from alternative RV types and volatility in raw material costs. Solo travelers and younger consumers demonstrate the highest price sensitivity, often seeking affordable teardrop and pop-up trailers, while buyers of luxury fifth-wheel units are less sensitive to price fluctuations.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of camping trailers, especially for specialized components. Geographic supply concentration for manufacturing centers on Elkhart, Indiana, Victoria, Australia, and Bavaria, Germany. The industry draws from key raw materials like aluminum and steel for structural components, alongside specialized appliances and electronics. Component supply chain bottlenecks, particularly for axles and windows, represent a persistent structural risk. Distribution runs through established dealership networks, with rental services gaining traction for smaller, more accessible models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European Union regulations promoting vehicle electrification act as a regulatory compounder, compelling manufacturers to innovate in lightweight design and aerodynamic profiles to minimize range penalties for electric tow vehicles.
For Market Incumbents: To counter the growing popularity of compact Class B camper vans, manufacturers must accelerate research and development into advanced lightweight composite materials. Diversifying product portfolios to include smaller, more agile units compatible with electric vehicles will capture new segments. Investing in proprietary chassis engineering for reduced gross vehicle weight offers a strategic advantage, reinforcing their position against new market entrants.
For New Entrants and Emerging Players: Capture underpenetrated geographies such as South America by offering adventure-oriented, rugged trailers tailored for local conditions. Target niche segments like tech-savvy solo travelers with smart trailer integration for power management and climate control. Developing direct-to-consumer channels, including online configurators for modular designs, provides a cost-effective go-to-market angle, bypassing traditional dealership overheads.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized manufacturers excelling in lightweight materials and smart technology integration. The long-term viability of the market hinges on its ability to adapt to electrification and evolving consumer preferences for shorter, more frequent trips. A signal to watch is the adoption rate of electric vehicles as primary tow cars, indicating a shift towards smaller, more efficient trailer designs for acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Material R&D | Reduces trailer weight, enabling compatibility with electric tow vehicles and expanding the addressable market. |
| Direct-to-Consumer Channel Development | Lowers sales costs and provides direct feedback, fostering product customization for niche buyers. |
| Smart Trailer Integration | Offers product differentiation through IoT-enabled features, appealing to tech-savvy consumer segments. |
| Geographic Expansion into South America | Unlocks new growth potential in emerging outdoor recreation markets with rising disposable incomes. |
| Skilled Labor Training Programs | Addresses production constraints and quality control issues by building expertise in advanced manufacturing techniques. |
Research Approach
Direct dialogue with manufacturing executives, dealership owners, material science engineers, and end-user groups informed the qualitative grounding of this analysis. Secondary validation drew from U.S. National Highway Traffic Safety Administration (NHTSA) reports, Germany's Kraftfahrt-Bundesamt (KBA) regulations, Australia's Vehicle Safety Standards (ADRs), and industry association publications. The research employed both bottom-up market sizing and top-down validation to ensure comprehensive data triangulation.
The quantitative model produced volume and value forecasts across the analysis window, segmenting by product type, material, end user, distribution channel, and regional regulatory frameworks. Compound annual growth rates (CAGRs) were derived from historical data trends and projected market dynamics. Key forecast inputs included material cost trends, electric vehicle adoption rates, and domestic tourism policy impacts on consumer investment in recreational vehicles.
Input cost volatility, regulatory shifts, and technological advancements are the dominant revision risks for market projections. Forecasts reflect assumptions documented through extensive primary and secondary research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
US Low Speed Vehicle Market