
 Watercraft Accessories Market | 2026-2036
Watercraft Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Watercraft Accessories Market Outlook
Marine-grade composite manufacturing is tilting toward automated fiber placement and resin transfer molding, cutting production cycles for hull fittings and deck hardware. Brunswick Corporation leverages its vertical manufacturing footprint to control casting and finishing of stainless steel cleats and anchor systems. Garmin Ltd. anchors its position in integrated chartplotter and sonar modules that dominate OEM fitment on new vessels. Yamaha Motor Corporation extends its aftermarket reach through proprietary rigging kits designed for outboard compatibility.
Watercraft accessories encompass functional and protective components—anchors, fenders, cleats, ropes, navigation electronics, covers, and propulsion rigging—fabricated from fiberglass, aluminum, stainless steel, and engineered polymers to withstand salt corrosion, UV degradation, and cyclic loading in marine environments. Their primary purpose is to secure vessels, protect hull integrity, enable safe docking, and support propulsion and navigation operations across recreational, commercial, and military fleets. Fiberglass and stainless steel hardware commands premium positioning in saltwater environments where galvanic corrosion resistance determines replacement cycles and total cost of ownership. The safety use case segment shows structural momentum as regulatory mandates for flotation devices, signaling equipment, and fire suppression systems expand compliance-driven refresh demand across rental fleets and private ownership.
The US Coast Guard enforces carriage requirements for personal flotation devices, visual distress signals, and fire extinguishers that directly shape product specifications and certification costs for manufacturers serving North American waters. The EU's REACH regulation and RoHS directive restrict hazardous substances in marine coatings, electrical components, and synthetic rope polymers, forcing reformulation of legacy product lines. ISO 12217 standards for small craft stability and buoyancy create harmonized testing protocols that facilitate cross-border market access but raise engineering barriers for uncertified suppliers. Stakeholders must monitor how impending EPA vessel discharge regulations and evolving EU Green Deal maritime extensions will recalibrate material specifications and compliance investment thresholds.
Market Dynamics
Recreational fleet renewal cycles are compressing as saltwater corrosion accelerates hardware replacement timelines, while REACH-mandated material reformulations force simultaneous R&D investment across coating and polymer supply chains.
Growth Catalysts
- EU REACH chemical restrictions:Reformulation mandates for marine coatings and synthetic ropes are creating compliance-driven refresh demand as rental fleets and private owners replace non-conforming inventory.
- Fiberglass-reinforced docking systems:Marina operators from Florida to the Mediterranean are upgrading aging infrastructure with corrosion-resistant composite pilings and cleats that outlast traditional timber.
- GPS-enabled navigation electronics:OEM fitment requirements for integrated chartplotter and sonar modules are standardizing across new vessel production lines.
Market Restraints
- Stainless steel input volatility:Marine-grade 316L alloy pricing fluctuations directly compress margin structures for anchor and cleat manufacturers dependent on casting operations.
- Resin supply concentration:Epoxy and vinylester formulations for fiberglass hardware concentrate among specialty chemical producers in Germany and the Netherlands, creating single-source vulnerability.
- Galvanic corrosion limitations:Dissimilar metal contact between aluminum hulls and stainless fittings restricts material pairing options in saltwater environments.
Strategic Opportunities
- US Coast Guard carriage mandates:Expanding requirements for visual distress signals and fire suppression systems on rental fleets create mandatory replacement cycles independent of discretionary spending.
- Automated fiber placement:Convergence of robotic layup with resin transfer molding is cutting production cycles for complex hull fittings, enabling mid-tier producers to compete on lead time.
- Direct-to-marina distribution:Bypassing traditional marine retail channels through dockside service contracts captures maintenance-triggered replacement demand at point of failure.
Industry Challenges
- ISO 12217 certification timelines:Stability and buoyancy testing protocols for small craft create 12-18 month product validation cycles that delay market entry for uncertified suppliers.
- Marine polymer formulation expertise:Shortage of chemists specializing in UV-resistant and salt-degradation-resistant polymer development constrains in-house R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watercraft Accessories Market |
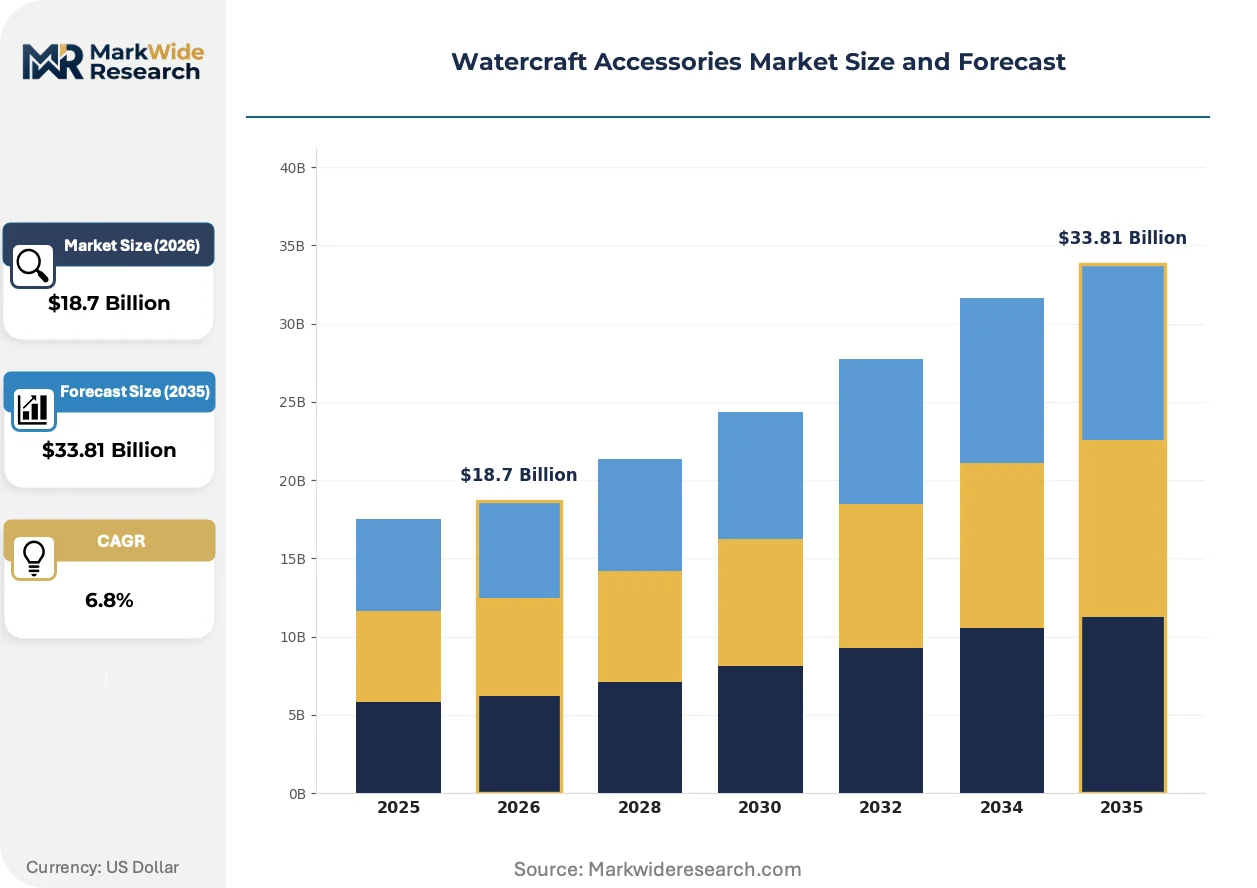
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anchors, Fenders, Cleats, Ropes Material: Fiberglass, Aluminum, Stainless Steel, Plastic Use Case: Recreational Boating, Fishing, Water Sports, Safety End User: Boat Owners, Rental Services, Dealerships, Manufacturers |
| Companies Covered | Yamaha Motor Corporation, Bombardier Recreational Products, Brunswick Corporation, Garmin Ltd., WireCo, Samson Rope Technologies, Covercraft Industries LLC, Attwood Corporation, Mercury Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watercraft Accessories Market Strategic Shifts
Digital integration and sustainable material science are reconfiguring how watercraft accessories are specified, manufactured, and distributed across recreational and commercial fleets.
Autonomous docking assistance systems combining LiDAR sensors with AI-powered thruster control are rendering obsolete manual line-handling protocols in high-traffic marinas. Superyacht operators and commercial ferry fleets are adopting these systems first, with recreational boaters following as retrofit kits reach aftermarket channels. The technology is rendering obsolete traditional cleat and fender configurations that assumed human-mediated mooring.
EPA vessel discharge regulations are tightening permissible concentrations of copper-based antifouling coatings in US waters. Manufacturers serving North American markets are accelerating investment in silicone and biocide-free alternatives that satisfy both EPA thresholds and California's more stringent port authority requirements. The regulation is compressing formulation cycles while expanding the addressable market for premium coating systems that command price premiums.
Marina operators are consolidating procurement through fleet-level maintenance contracts that bundle hardware replacement with dockage fees. This channel shift displaces traditional marine retail and chandlery relationships, concentrating purchasing power among facility management companies operating multiple coastal locations. The model is most visible in Florida and Mediterranean basin markets where seasonal fleet turnover creates predictable replacement schedules.
Watercraft Accessories Market Segmentation
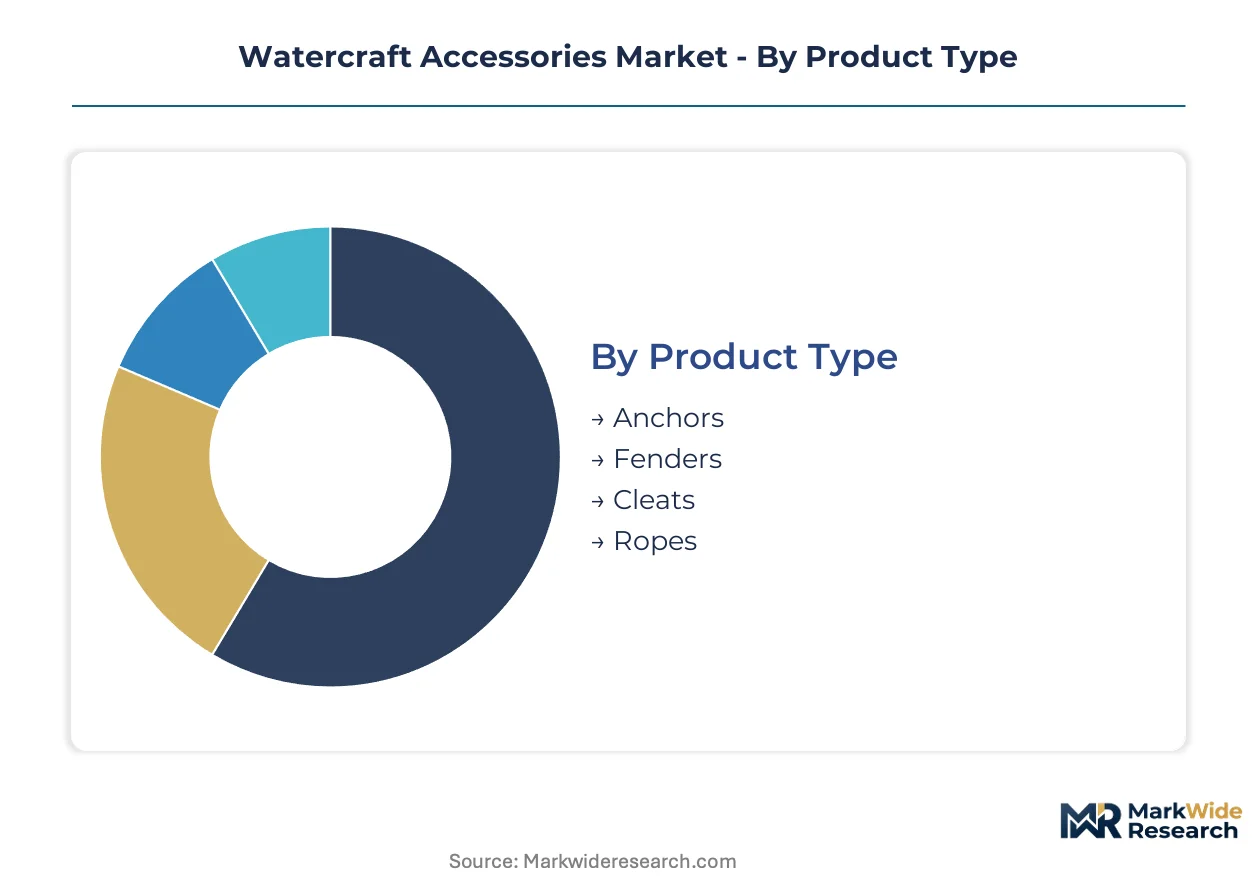
Watercraft accessories manufacturers configure product portfolios across four intersecting dimensions. Material selection determines corrosion resistance in saltwater environments, while end-user channel structure dictates pricing power and replacement cycle visibility.
Product Type:
Mature hardware categories dominate installed base volumes, though emerging smart-enabled variants are recalibrating replacement economics.
- Anchors:Cast stainless steel or galvanized iron designs with fluke geometry optimized for mud, sand, or rock seabed penetration. Demand concentrates in Mediterranean marinas and Florida's charter fleet, where regulatory mooring requirements and storm surge preparedness drive periodic replacement cycles.
- Fenders:Inflatable vinyl or solid foam bumpers protecting hull-to-dock contact surfaces. Marina operators from Barcelona to Miami are standardizing on modular fender systems that reduce line-handling labor and enable faster vessel turnaround during peak season.
- Cleats:Stainless steel or aluminum deck fixtures securing mooring lines under cyclic loading.
- Ropes:Synthetic fiber lines combining high tensile strength with UV and salt degradation resistance.
Anchors handle the majority of throughput; Fenders are expanding most quickly on share as marina infrastructure upgrades accelerate.
Material:
Cost tier stratification separates premium corrosion-resistant grades from commodity alternatives with shorter service life.
- Fiberglass:Glass-reinforced polymer composites fabricated through resin transfer molding for pilings, cleats, and structural dock hardware. EU REACH compliance mandates are accelerating displacement of timber and steel in marina infrastructure projects from the Netherlands to Greece.
- Stainless Steel:Marine-grade 316L alloy delivering superior galvanic corrosion resistance in saltwater immersion. OEM fitment on superyacht builds and commercial ferry fleets commands price premiums three to four times above aluminum alternatives.
- Aluminum:Lightweight alloy hardware prevalent in freshwater and trailerable craft applications.
- Plastic:Injection-molded engineered polymers for fender cores, chafe guards, and non-structural fittings.
Stainless Steel commands the premium tier; Fiberglass is climbing the fastest as composite manufacturing scales reduce unit economics.
Use Case:
Application context determines performance specifications and regulatory certification burdens.
- Recreational Boating:Private vessel owners upgrading navigation electronics, docking hardware, and protective covers across aging fleet bases. Florida's coastal counties and Italy's Ligurian coast concentrate discretionary spending on premium accessories.
- Fishing:Rod holders, livewell fittings, and specialized anchoring systems for commercial and sport fleets. North Sea operators and Gulf of Mexico charter services drive demand for corrosion-resistant rigging under intensive salt exposure.
- Water Sports:Tow ropes, wakeboard racks, and ski pylon hardware for recreational towing applications.
- Safety:US Coast Guard-mandated personal flotation devices, visual distress signals, and fire suppression equipment. Rental fleet compliance refresh creates non-discretionary replacement demand independent of consumer confidence cycles.
Recreational Boating anchors volume; Safety is gaining share fastest on regulatory mandate expansion.
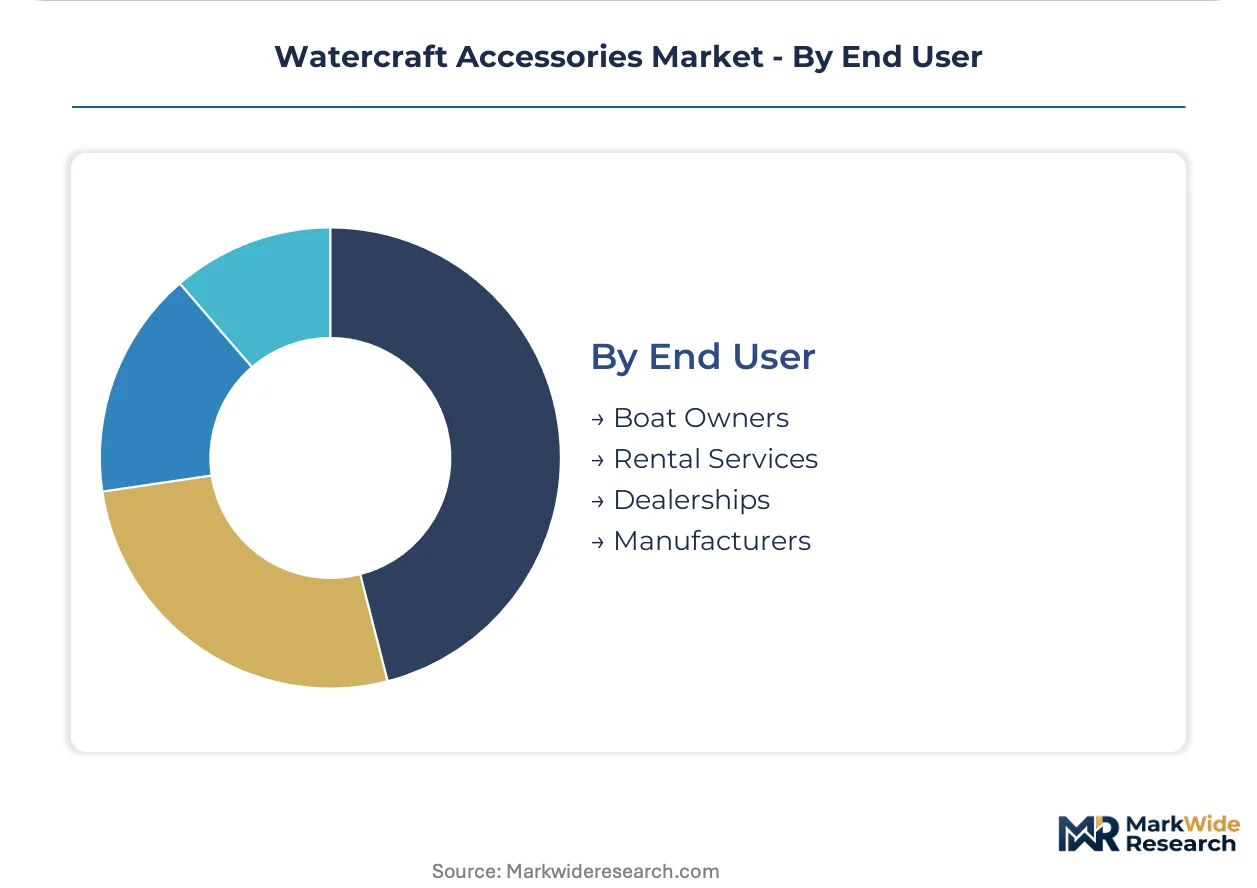
End User:
Customer type segmentation reveals divergent procurement patterns and margin structures.
- Boat Owners:Individual consumers purchasing through marine retail, online channels, or dockside service providers. Mediterranean private owners and US coastal boaters exhibit strong seasonal replacement patterns tied to pre-launch commissioning.
- Rental Services:Fleet operators sourcing safety equipment and hardware through volume contracts with mandatory compliance refresh schedules. Florida's multi-location charter companies and French Riviera rental fleets consolidate purchasing power through facility management platforms.
- Dealerships:Vessel retailers bundling accessories with new craft sales and aftermarket service.
- Manufacturers:OEM procurement of navigation electronics, propulsion rigging, and deck hardware for new vessel production lines.
Rental Services handle the majority of throughput; Boat Owners are expanding most quickly on share as direct-to-consumer channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marina operators and fleet managers concentrate purchasing power in coastal counties with high vessel density and stringent environmental enforcement. Saltwater corrosion cycles and regulatory refresh mandates create predictable replacement demand clusters.
United States
Florida's coastal counties and Gulf of Mexico charter services drive anchor and rigging replacement cycles accelerated by tropical storm exposure. The US Coast Guard enforces carriage requirements for personal flotation devices and fire extinguishers that mandate fleet-wide compliance refreshes. Miami-Dade and Fort Lauderdale marina clusters concentrate procurement through facility management platforms bundling hardware with dockage fees.
Italy
Ligurian coast private owners and Mediterranean superyacht builders sustain premium demand for stainless steel hardware and integrated navigation electronics. EU REACH chemical restrictions force reformulation of marine coatings and synthetic ropes across Italian manufacturing supply chains. Genoa and La Spezia harbor districts anchor composite manufacturing for corrosion-resistant docking infrastructure serving charter fleets.
Germany
Specialty chemical producers in Germany and the Netherlands concentrate epoxy and vinylester resin supply for fiberglass hardware fabrication. The EU Green Deal maritime extensions recalibrate material specifications for marina infrastructure projects across Baltic and North Sea coastlines. Hamburg and Bremen industrial zones supply engineered polymer formulations meeting REACH-mandated UV and salt degradation resistance standards.
France
French Riviera rental fleets consolidate safety equipment procurement through volume contracts with mandatory compliance refresh schedules. ECHA enforcement of hazardous substance restrictions in marine electrical components drives OEM fitment standardization for navigation electronics. Marseille and Nice marina operators are standardizing on modular fender systems reducing line-handling labor during peak seasonal turnover.
Australia
Queensland and New South Wales recreational boating fleets upgrade aging navigation electronics and protective covers across corrosion-accelerated replacement timelines. The country's national maritime safety regulator mandates flotation device and distress signal carriage requirements shaping product specifications. Sydney and Gold Coast coastal clusters concentrate fiberglass-reinforced docking system installations replacing timber infrastructure.
Watercraft Accessories Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Marine retail networks and direct-to-marina distribution platforms fragment end-user access, while OEM fitment agreements concentrate navigation electronics supply. Three archetypes dominate: vertically integrated marine conglomerates controlling casting and finishing operations; precision electronics specialists capturing integrated chartplotter and sonar module fitment; and rope and textile engineers supplying synthetic mooring lines. Competitive moves center on backward integration into resin formulation and geographic expansion through dockside service contracts.
Among Japan-based motor manufacturers, Yamaha Motor Corporation exemplifies the diversified marine-industrial archetype with proprietary rigging kit ecosystems. Garmin Ltd. anchors the precision electronics specialist tier, occupying a position in integrated navigation module standardization. Brunswick Corporation represents the vertically integrated conglomerate model with captive control over stainless steel hardware casting operations. These three entities collectively illustrate how scale, specialization, and channel integration define competitive positioning.
| Leading Market Players |
|---|
| Yamaha Motor Corporation |
| Bombardier Recreational Products |
| Brunswick Corporation |
| Garmin Ltd. |
| WireCo |
| Samson Rope Technologies |
| Covercraft Industries LLC |
| Attwood Corporation |
| Mercury Marine |
| Others |
Value Chain & Pricing Dynamics
German and Dutch specialty chemical producers anchor epoxy and vinylester resin supply for fiberglass hardware fabrication, concentrating margin capture upstream while downstream fabricators face pass-through pricing volatility on marine-grade 316L stainless steel alloy.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate stainless steel hardware procurement, tying anchor and cleat prices to nickel and chromium spot movements. Three-tier pricing structure across premium, standard, and economy levels separates OEM superyacht fitment from aftermarket replacement and rental fleet bulk purchasing. Pricing pressure stems from 316L alloy volatility compressing casting operation margins. Rental fleet operators exhibit highest price sensitivity due to volume contract consolidation, while superyacht builders absorb premiums for corrosion-resistant certification.
Supply Chain Analysis
Upstream feedstock for marine-grade composites concentrates in Germany, the Netherlands, and Japan, where specialty chemical producers formulate REACH-compliant epoxy and UV-resistant vinylester systems. Raw material dependencies span nickel-chromium-molybdenum alloy feedstock, glass fiber rovings, and synthetic polymer base stocks for mooring lines. Single-source vulnerability in resin formulation creates supply chain risk given limited qualified alternative suppliers. Distribution runs through facility management platforms bundling hardware with dockage fees, displacing traditional marine retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-location marina operators and fleet management platforms, fragmenting traditional marine retail relationships and compressing pricing leverage for undifferentiated hardware suppliers.
For Market Incumbents: Harden defensible positions through backward integration into resin formulation and captive control of stainless steel casting operations. Threats from autonomous docking systems displacing traditional cleat and fender configurations demand accelerated R&D investment in sensor-integrated mooring hardware. Certification investment in ISO 12217 stability protocols creates switching costs against uncertified challengers. For New Entrants and Emerging Players: Direct-to-marina service contracts in Florida and Mediterranean basin markets represent the most penetrable entry point, bypassing established retail channel gatekeepers. Mid-tier fiberglass hardware fabrication using automated fiber placement offers technology-led differentiation against legacy manufacturers. Dockside maintenance-triggered replacement demand captures point-of-failure purchasing decisions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine conglomerates holding captive casting operations and established OEM fitment relationships. Long-term viability hinges on exposure to regulatory-mandated safety equipment refresh cycles rather than discretionary recreational spending. Watch EPA vessel discharge regulation tightening on copper-based antifouling coatings as inflection signal for coating system manufacturer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive supply of REACH-compliant epoxy systems insulates margin from German-Dutch chemical producer pricing power. |
| Automated Fiber Placement Scale-Up | Robotic layup convergence cuts production cycles for complex hull fittings, enabling mid-tier competitive lead times. |
| Direct-to-Marina Distribution Contracts | Dockside service agreements capture maintenance-triggered replacement demand at point of hardware failure. |
| ISO 12217 Certification Investment | Stability and buoyancy testing protocols create 12-18 month validation barriers against uncertified market entrants. |
| Silicone-Based Antifouling Coating Development | EPA vessel discharge compliance positions manufacturers for premium pricing in California port authority jurisdictions. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings from marine conglomerates, and EU REACH substance restriction precedents preceded structured interviews with marina operations directors, fleet procurement managers, composite manufacturing engineers, and marine retail channel heads. Bottom-up triangulation across vessel registration data and top-down validation through accessory spend-per-boat estimates anchored market sizing. Primary fieldwork captured replacement cycle timing and procurement consolidation trends.
Assumptions held fixed across the analysis window include REACH chemical restriction enforcement timelines and US Coast Guard carriage mandate scope, while stainless steel alloy pricing and marina infrastructure investment cycles were modeled as variable inputs. Segmentation modeling incorporated material grade tier, end-use application context, and customer channel structure. CAGRs derived from fitted trend extrapolation against historical fleet renewal patterns and regulatory refresh mandate schedules.
Practitioners should monitor EPA vessel discharge regulation finalization and EU Green Deal maritime extension announcements for early signals requiring forecast revision. Cross-checking against IHS Markit recreational vessel production data and regional marina development permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Caravan and Motorhome Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Electric Golf Cart Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Leisure Boat Market