
 Marine Shaft Power Meter Market | 2026-2036
Marine Shaft Power Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Shaft Power Meter Market Analysis
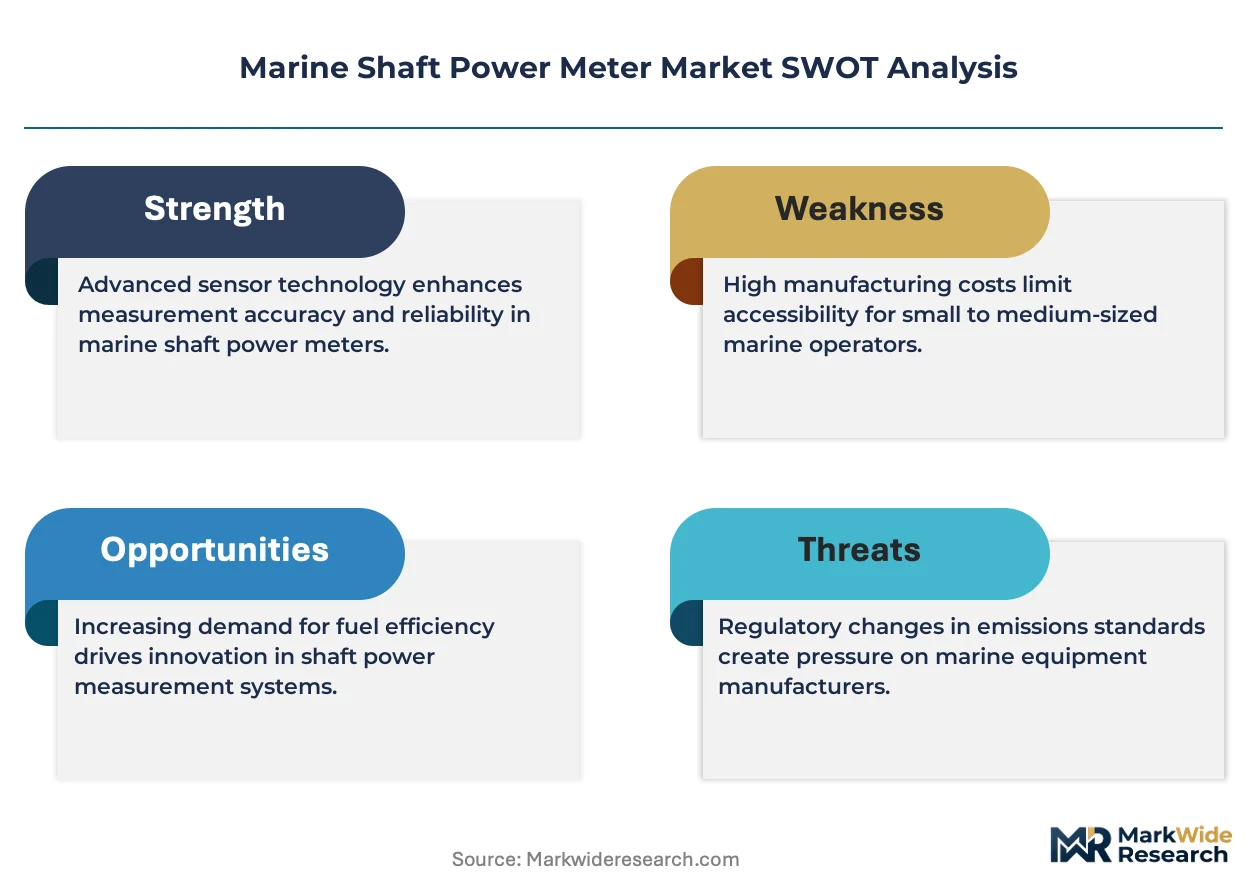
Composite sensor housings are hardening as the preferred alternative to traditional stainless steel enclosures in marine shaft power meters, cutting unit weight and extending saltwater corrosion resistance. VAF Instruments BV leverages decades of Rotterdam port proximity to sustain dominant calibration service capabilities. Kongsberg Maritime anchors its position through integrated bridge-to-engine room data architectures. Datum Electronics Limited specializes in strain-gauge torque measurement for retrofit installations on existing propulsion shafts.
A marine shaft power meter measures mechanical power transmission through propeller shafts using strain gauges, optical encoders, or magnetic pickups to capture torque and rotational speed with typical accuracy within 0.5 percent. These instruments feed engine management systems to optimize fuel consumption, schedule predictive maintenance, and verify compliance with emissions protocols. Digital meters now command the strongest margin pools as ship operators abandon analogue dial displays for real-time data logging and remote fleet analytics. Fixed installations dominate newbuild contracts, while portable meters capture growing aftermarket demand from marine surveyors and classification societies auditing vessel efficiency claims.
IMO MARPOL Annex VI and the EU MRV Monitoring, Reporting, and Verification regulation shape product certification requirements, forcing manufacturers to secure type-approval from notified bodies such as DNV and Lloyd's Register before commercial deployment. The US Coast Guard enforces equivalent standards under its domestic vessel inspection program, creating parallel compliance pathways for equipment suppliers. Stakeholders must weigh the capital cost of integrated versus standalone installations against the operational savings from continuous shaft power optimization and the regulatory risk of non-compliance penalties.
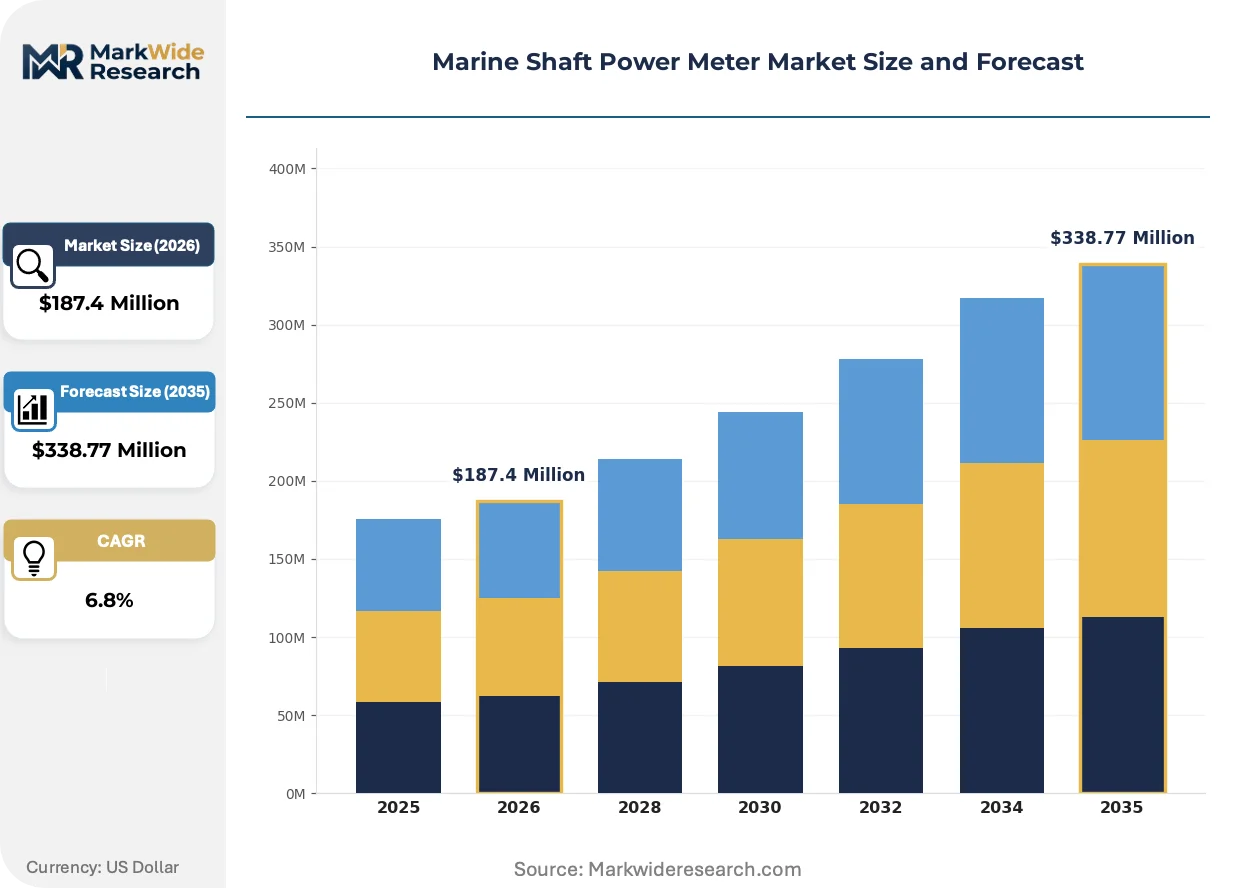
Market Dynamics
IMO MARPOL Annex VI enforcement is compressing installation timelines for shaft power meters as commercial fleets face mandatory Carbon Intensity Indicator compliance deadlines. Ship operators now treat continuous torque monitoring as essential infrastructure rather than optional efficiency instrumentation.
Growth Catalysts
- EU MRV Monitoring, Reporting, and Verification:Annual emissions reporting obligations for vessels above 5,000 gross tonnage mandate certified power measurement systems, creating baseline demand across European-flagged fleets.
- Composite sensor housings:Glass-reinforced polymer enclosures replace stainless steel in saltwater environments, cutting installation weight by 40 percent and eliminating galvanic corrosion failure modes.
- Rotterdam-Antwerp-Hamburg corridor:Europe's densest concentration of ship repair yards and classification society offices generates concentrated aftermarket demand for portable calibration and audit equipment.
Market Restraints
- Strain gauge calibration drift:Thermal cycling and mechanical fatigue in propulsion shafts degrade measurement accuracy below 0.5 percent within 18-24 months, forcing recurring service intervals.
- Type-approval concentration:DNV, Lloyd's Register, and Bureau Veritas control 90 percent of marine equipment certification, creating bottleneck delays for new product launches.
- Optical encoder substitution:Non-contact speed sensors from industrial automation sectors threaten magnetic pickup incumbents in retrofit applications where shaft access is limited.
Strategic Opportunities
- Greek and Cypriot tanker fleets:These operators lag container lines in power meter adoption, presenting white-space demand from 2,000+ crude and product carriers requiring MRV compliance upgrades.
- Wind-assisted propulsion integration:Rotor sails and kite systems require real-time shaft torque feedback to optimize hybrid sail-diesel operating points, opening new specification channels.
- Digital twin convergence:Bridge-to-engine room data architectures from Kongsberg and Wärtsilä create pull-through demand for API-compatible shaft power feeds.
Industry Challenges
- Marine electrical technician scarcity:Installation of strain-gauge bridges and signal conditioning units requires specialized skills absent from general shipyard workforces, extending commissioning timelines.
- Legacy engine control system integration:1990s-era MAN B&W and Wärtsilä engine governors lack standardized data protocols, forcing expensive custom interface development for digital meter retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Shaft Power Meter Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analogue Meters, Digital Meters, Portable Meters, Fixed Meters Application: Commercial Vessels, Fishing Boats, Research Vessels, Leisure Crafts End User: Shipbuilders, Shipping Companies, Marine Engineers, Research Institutions Installation Type: Onboard, Offboard, Integrated, Standalone |
| Companies Covered | Shoyo Engineering Co., Ltd., VAF Instruments BV, Datum Electronics Limited, Kyma A.S., Aquametro Oil & Marine AG, Kongsberg Maritime, Trelleborg Marine Systems, Binsfeld Engineering Inc., Hoppe Marine GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Shaft Power Meter Market Emerging Trajectories
Sensor miniaturization and wireless telemetry are collapsing the distinction between fixed and portable shaft power measurement systems. Equipment suppliers now compete on data architecture integration rather than raw measurement accuracy.
Optical encoder speed sensing is overtaking magnetic pickup technology in newbuild specifications. These devices eliminate electromagnetic interference from high-power propulsion motors, delivering cleaner rotational speed data to engine management computers. Korean and Chinese shipyards now specify optical systems as standard on LNG carriers and container vessels, compressing magnetic pickup market share to retrofit-only applications.
REACH substance restrictions on hexavalent chromium coatings are forcing manufacturers to switch to zinc-nickel plating for sensor housings. The regulation adds 12-15 percent to surface treatment costs but eliminates supply chain risk from restricted substance non-compliance. German and Dutch equipment suppliers have completed transitions; Southern European and Asian manufacturers face 2026 deadlines.
Ship operators now unbundle hardware procurement from calibration service contracts, treating meters as capital equipment and maintenance as separately sourced operational expenditure. This split separates equipment vendors from recurring revenue streams, pressuring VAF Instruments and Datum Electronics to build captive service networks. The pattern is most visible in German and Scandinavian owner fleets with centralized technical management functions.
Marine Shaft Power Meter Market Segmentation
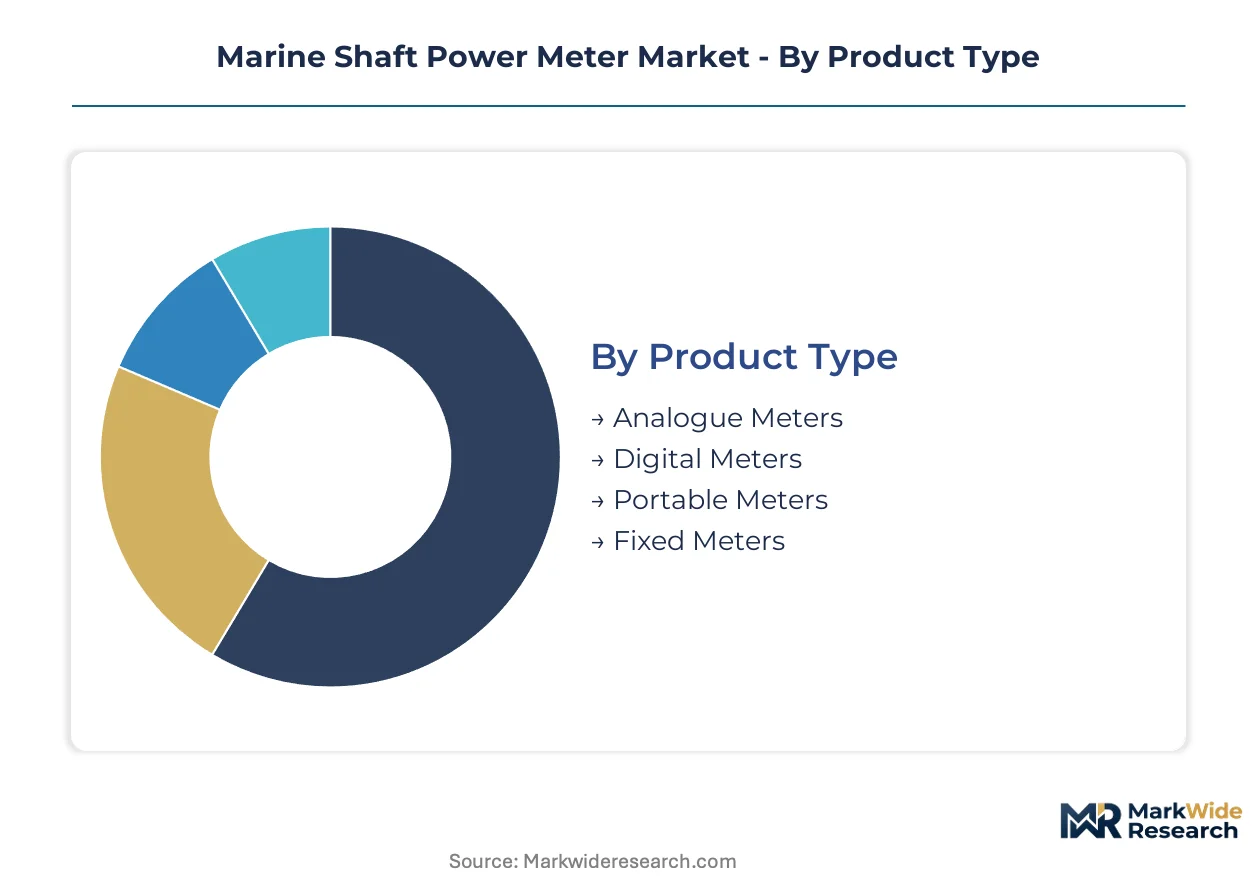
Shaft power meter procurement splits sharply between newbuild specification and retrofit replacement cycles. Equipment buyers prioritize integration depth and data architecture compatibility over raw measurement specifications. Segmentation logic tracks the divergence between capital-intensive fleet upgrades and compliance-driven spot purchases.
Product Type:
Replacement cycles accelerate as ship operators abandon legacy analogue instrumentation for connected digital systems.
- Digital Meters:Real-time data logging and remote fleet analytics capabilities command premium positioning. German and Scandinavian owner fleets with centralized technical management functions drive specification demand for API-compatible bridge-to-engine room architectures.
- Fixed Meters:Permanently installed strain-gauge bridges and signal conditioning units dominate newbuild contracts. Korean and Chinese shipyards specify these systems as standard on LNG carriers and container vessels.
- Analogue Meters:Dial-display units persist only in legacy vessel fleets with 1990s-era engine governors lacking standardized data protocols.
- Portable Meters:Marine surveyors and classification society auditors deploy battery-powered units for MRV compliance spot-checks and efficiency claim verification.
Volume placements concentrate in Fixed Meters; the faster expansion belongs to Digital Meters.
Application:
Regulatory pressure intensity varies dramatically across vessel operating profiles and trading patterns.
- Commercial Vessels:Container lines and bulk carriers above 5,000 gross tonnage face mandatory EU MRV reporting obligations. IMO Carbon Intensity Indicator deadlines compress installation timelines across European-flagged fleets.
- Research Vessels:Scientific mission requirements demand sub-0.5 percent accuracy for propulsion efficiency studies. Universities and oceanographic institutes specify calibrated torque measurement for publishable data integrity.
- Fishing Boats:Smaller tonnage vessels fall below MRV thresholds but adopt portable audit equipment for fuel cost management.
- Leisure Crafts:Superyacht owners install integrated meters for operational optimization and resale documentation value.
Commercial Vessels anchor absolute unit demand; Research Vessels post the steepest expansion trajectory per installed base.
End User:
Procurement authority fragmentation shapes vendor relationship strategies and contract structuring.
- Shipping Companies:Fleet technical managers unbundle hardware procurement from calibration service contracts. Operators treat meters as capital equipment and maintenance as separately sourced operational expenditure.
- Shipbuilders:Korean and Chinese yards specify optical encoder systems as standard, compressing magnetic pickup market share to retrofit-only applications.
- Marine Engineers:Independent consultants specify portable units for MRV compliance upgrades on Greek and Cypriot tanker fleets.
- Research Institutions:Academic buyers prioritize calibration traceability and publication-grade measurement uncertainty documentation.
Shipping Companies generate the largest contract values; Marine Engineers drive the fastest-growing service revenue segment.
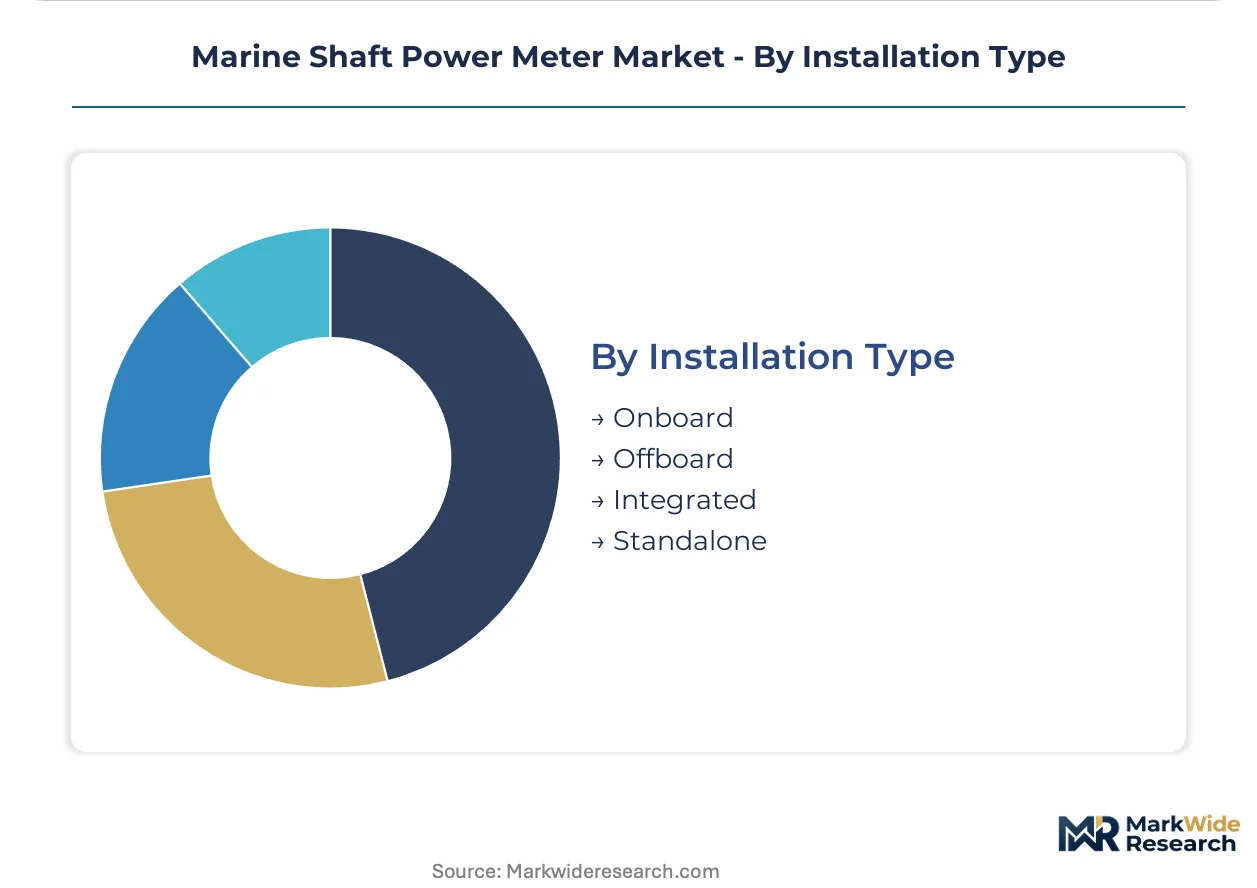
Installation Type:
Integration depth determines total cost of ownership and regulatory audit trail completeness.
- Integrated:Bridge-to-engine room data architectures from major marine automation suppliers create pull-through demand for API-compatible shaft power feeds. These installations eliminate custom interface development costs for digital retrofits.
- Onboard:Permanent sensor networks with continuous telemetry satisfy classification society type-approval requirements for MRV certification.
- Standalone:Self-contained units serve vessels with legacy engine control systems lacking standardized data protocols.
- Offboard:Shore-based analysis systems process logged data from portable meter deployments during dry-docking periods.
Integrated installations capture the premium tier; Onboard systems deliver the broadest volume penetration across fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial shipping fleet operators in Germany drive the highest absolute procurement volumes for integrated shaft power measurement systems. Rotterdam port proximity sustains dense calibration service networks across the Netherlands and Belgium.
Germany
Major shipyards and marine technology clusters in Hamburg and Bremerhaven specify bridge-to-engine room data architectures for newbuild contracts. The country's national maritime regulator enforces strict type-approval standards for emissions monitoring equipment under EU MRV implementation. Industrial concentration in Lower Saxony and Schleswig-Holstein generates captive demand for precision torque measurement systems.
Netherlands
Rotterdam-Antwerp port corridor operators treat continuous shaft power monitoring as essential fuel optimization infrastructure. REACH substance restrictions on hexavalent chromium coatings force manufacturers toward zinc-nickel plating transitions. VAF Instruments leverages decades of port proximity to sustain dominant calibration capabilities across the region.
South Korea
DSME and Hyundai Heavy Industries specify optical encoder systems as standard on LNG carriers and container vessels. The country's national shipbuilding regulator mandates emissions verification protocols aligned with IMO Carbon Intensity Indicator deadlines. Ulsan and Geoje shipyard complexes compress magnetic pickup market share to retrofit-only applications.
China
State-owned COSCO and China Merchants Energy Shipping accelerate fleet-wide power meter installations for dual carbon compliance targets. The Ministry of Ecology and Environment enforces parallel domestic standards to IMO MARPOL Annex VI requirements. Shanghai and Dalian shipbuilding bases concentrate procurement authority for integrated digital systems.
Norway
Kongsberg Maritime anchors integrated automation demand through proprietary bridge-to-engine room architectures. The Norwegian Maritime Authority enforces stringent calibration traceability for research vessel specifications. Bergen and Oslo technology clusters pull through API-compatible shaft power feeds for offshore support fleets.
Marine Shaft Power Meter Market Vendor Landscape
Strategic partnerships dominate the current landscape as equipment vendors align with marine automation platforms to secure bridge-to-engine room integration slots. The market structures around three tiers: integrated system suppliers, standalone instrument specialists, and portable audit equipment providers. Technology licensing agreements and captive service network expansion represent the two primary competitive vectors separating premium positioning from commodity hardware supply.
Among Dutch instrumentation specialists, VAF Instruments BV occupies the calibration service archetype through Rotterdam port proximity. Kongsberg Maritime exemplifies the integrated automation tier with proprietary data architecture control. Datum Electronics Limited sits within the retrofit specialist category, anchoring strain-gauge torque measurement for existing propulsion shafts.
| Leading Market Players |
|---|
| Shoyo Engineering Co., Ltd. |
| VAF Instruments BV |
| Datum Electronics Limited |
| Kyma A.S. |
| Aquametro Oil & Marine AG |
| Kongsberg Maritime |
| Trelleborg Marine Systems |
| Binsfeld Engineering Inc. |
| Hoppe Marine GmbH |
| Others |
Supply Flow & Price Mechanics
Captive calibration service networks anchor pricing power for established Dutch and German suppliers, insulating premium tiers from commodity hardware competition while forcing mid-tier vendors toward unbundled equipment-only propositions. IMO type-approval bottlenecks concentrate supplier qualification authority with DNV, Lloyd's Register, and Bureau Veritas, creating structural barriers that sustain margin pools for certified integrated systems.
Pricing Analysis
Volume placements concentrate in fixed-installation hardware with compressed margins, while digital meter architectures and captive service contracts capture the strongest margin pools. Price differentiation hinges on IMO MARPOL Annex VI certification tier and after-sales calibration bundling. Pricing pressure stems from ship operators unbundling hardware procurement from maintenance contracts, treating meters as capital equipment and service as separately sourced operational expenditure. Container lines and Scandinavian technical managers show lowest price sensitivity; Greek and Cypriot tanker operators exhibit highest sensitivity to upfront equipment costs.
Supply Chain Analysis
Dual-sourcing requirements for strain-gauge bridges and optical encoder assemblies mandate multi-supplier qualification across German, Dutch, and South Korean component vendors. Manufacturing concentrates in Germany, the Netherlands, and South Korea for precision sensor housings and signal conditioning units. Raw material dependencies include glass-reinforced polymer composites, zinc-nickel plating substrates, and semiconductor-grade optical components. Single-source vulnerability concentrates in DNV and Lloyd's Register type-approval certification, where bottlenecks delay new product launches. Distribution runs through shipyard specification channels and marine automation platform integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine shaft power meter market consolidation accelerates as IMO Carbon Intensity Indicator deadlines compress installation timelines and strain-gauge calibration drift forces recurring service investment that weaker players cannot fund.
For Market Incumbents: Anticipate optical encoder substitution threats from industrial automation sectors by deepening proprietary bridge-to-engine room data architectures. Secure exclusive calibration service contracts with Rotterdam-Antwerp-Hamburg corridor shipyards before ship operators complete unbundling transitions. Reinforce type-approval relationships with DNV and Lloyd's Register to maintain certification bottleneck advantages against emerging Asian competitors. For New Entrants and Emerging Players: Direct-to-fleet digital platforms offer the lowest barrier route for specification influence without shipyard incumbent relationships. Target Greek and Cypriot tanker fleets lagging container lines in MRV compliance upgrades. Prioritize portable audit equipment for marine surveyor certification societies before fixed-installation newbuild specifications consolidate. Emphasize API compatibility with Kongsberg and Wärtsilä automation architectures to bypass standalone hardware commoditization. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by marine automation platforms seeking bridge-to-engine room integration capabilities. Five-to-ten year viability favors vendors with captive calibration networks and type-approval certification depth over hardware-only suppliers. Watch for IMO enforcement variance on Carbon Intensity Indicator penalties as the inflection signal separating compliance-infrastructure demand from discretionary efficiency investment.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | VAF Instruments leverages Rotterdam port proximity to capture recurring revenue from European-flagged fleets. |
| Bridge-to-Engine Room Integration Partnership | Kongsberg Maritime anchors proprietary data architectures that pull through API-compatible shaft power feeds. |
| Optical Encoder Technology Transition | Korean and Chinese shipyards specify non-contact speed sensing to eliminate electromagnetic interference on LNG carriers. |
| Wind-Assisted Propulsion System Integration | Rotor sail and kite manufacturers require real-time torque feedback for hybrid sail-diesel optimization. |
| REACH Compliance Transition | German and Dutch suppliers complete zinc-nickel plating shifts before 2026 hexavalent chromium deadlines. |
Methodological Framework
Document review covered IMO MARPOL Annex VI regulatory filings, EU MRV compliance databases, and DNV type-approval registers, complemented by interviews with fleet technical managers at container lines and tanker operators, shipyard procurement officers at Korean and Chinese newbuild facilities, marine surveyors from classification societies, and calibration service technicians at Rotterdam port facilities. Secondary validation drew from Lloyd's Register equipment lists, Bureau Veritas certification records, and shipbuilding order databases. Bottom-up vessel fleet analysis triangulated against top-down marine automation platform revenue segmentation.
Cross-reference between historical installation penetration rates and expert panel input on IMO enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (digital, fixed, analogue, portable), application (commercial vessels, research vessels, fishing boats, leisure crafts), installation type (integrated, onboard, standalone, offboard), and end-user procurement authority (shipping companies, shipbuilders, marine engineers, research institutions). CAGRs derived from regression against fleet renewal cycles and regulatory deadline clustering. Industry-specific forecast inputs incorporated EU MRV reporting obligation expansion and wind-assisted propulsion hybrid system adoption curves.
Inputs from classification society certification databases and shipyard specification records were available through the study window; gaps in real-time fleet compliance audit data introduce uncertainty bands around retrofit demand timing. Forecasts reflect assumptions on IMO Carbon Intensity Indicator enforcement consistency and REACH substance restriction implementation timelines. Deviation in IMO penalty severity or flag-state enforcement variance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
North America Naval Vessels Market
Marine
Boat Steering Systems Market
Marine
Boat Ladder Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Fishing Vessel Market
Marine
Marine Beacon Market
Marine
Ballast Water Management Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Europe ROV Market
Marine
Sailboat Market
Marine
Marine Gas Oil Market
Marine
Marine Filter Market
Marine
Marine Diesel Engine Market
Marine
Marine Turbocharger Market
Marine
Jet Boat Market
Marine
Marine Shackle Market