
 Dual Circuit Brakes System Market | 2026-2036
Dual Circuit Brakes System Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Circuit Brakes System Market Foresight
Passenger car electrification is restructuring procurement priorities across brake system tiers. Bosch leverages its electromechanical brake portfolio to anchor supply contracts with European OEMs transitioning to skateboard architectures. Continental AG sustains R&D intensity in integrated brake control modules that consolidate ABS and ESC functions. ZF Friedrichshafen AG competes through manufacturing scale in hydraulic actuation systems serving commercial vehicle programs.
A dual circuit brakes system employs two independent hydraulic circuits to ensure partial braking retention upon single-circuit failure, typically configured in diagonal or front-rear split arrangements with operating pressures between 100 and 180 bar. The architecture serves as the foundational safety layer in automotive braking, mandated for road-legal vehicles across major regulatory jurisdictions. Disc brakes dominate OEM fitment in passenger cars due to thermal capacity advantages, while drum brakes retain cost-optimized positions in entry commercial vehicle axles where heat dissipation demands remain moderate. Electromechanical brakes represent the fastest-growing product category as automakers eliminate hydraulic fluids from electric vehicle platforms, though hydraulic systems still occupy the majority of current installed capacity.
NHTSA Federal Motor Vehicle Safety Standard 135 governs stopping distance and fade performance for light vehicles sold in the United States, while UN ECE R13-H establishes equivalent homologation benchmarks across European type-approval regimes. China's MIIT enforces GB standards that align with these frameworks while adding domestic electromagnetic compatibility requirements for brake-by-wire systems. Stakeholders must monitor regulatory divergence between NHTSA and UN ECE test protocols as electromechanical architectures proliferate, since conflicting certification paths could fragment development budgets across regional product variants.
Market Dynamics
Electromechanical brake architectures are fragmenting established hydraulic supply chains as electric vehicle platforms eliminate fluid-based actuation, forcing tier-one suppliers to reconfigure manufacturing footprints and R&D allocations across dual-circuit and brake-by-wire product lines.
Growth Catalysts
- NHTSA FMVSS 135 mandates:Stopping-distance thresholds for light vehicles compel OEMs to upgrade brake system thermal capacity and redundancy, accelerating replacement cycles in the US passenger car fleet.
- Commercial vehicle electrification:Fleet operators in Germany and the Netherlands are specifying electromechanical configurations for urban delivery chassis to reduce maintenance intervals and eliminate hydraulic fluid leakage risks.
- UN ECE R13-H homologation:European type-approval alignment with US fade-performance benchmarks creates regulatory convergence that simplifies cross-border platform engineering for multinational automakers.
Market Restraints
- Rare earth magnet supply concentration:Electromechanical brake motors depend on neodymium processed primarily in China, exposing cost structures to export quota volatility and geopolitical friction.
- Hydraulic component depreciation:Existing production lines for master cylinders and ABS modulators face accelerated obsolescence risk as OEMs freeze new hydraulic program development.
- Dual certification burden:Divergent NHTSA and UN ECE test protocols for brake-by-wire electromagnetic compatibility force redundant validation spending on single vehicle programs.
Strategic Opportunities
- India commercial vehicle retrofit:Stringent BS-VI emission enforcement is accelerating fleet turnover, creating aftermarket demand for upgraded dual-circuit systems in heavy-duty trucks and buses.
- Skateboard architecture integration:Brake-by-wire modules that package with battery-electric chassis rails offer tier-one suppliers pathway to capture value previously held by hydraulic component distributors.
- China MIIT GB standard alignment:Domestic electromagnetic compatibility requirements for brake-by-wire systems create first-mover advantage for suppliers achieving early MIIT certification.
Industry Challenges
- Mechatronics talent scarcity:Electromechanical brake development requires embedded software engineers with functional safety expertise, a skill set concentrated in automotive electronics rather than traditional brake engineering departments.
- Legacy ABS integration complexity:Brake-by-wire architectures must maintain backward compatibility with existing ESC and traction control calibrations, extending validation timelines for multi-platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Circuit Brakes System Market |
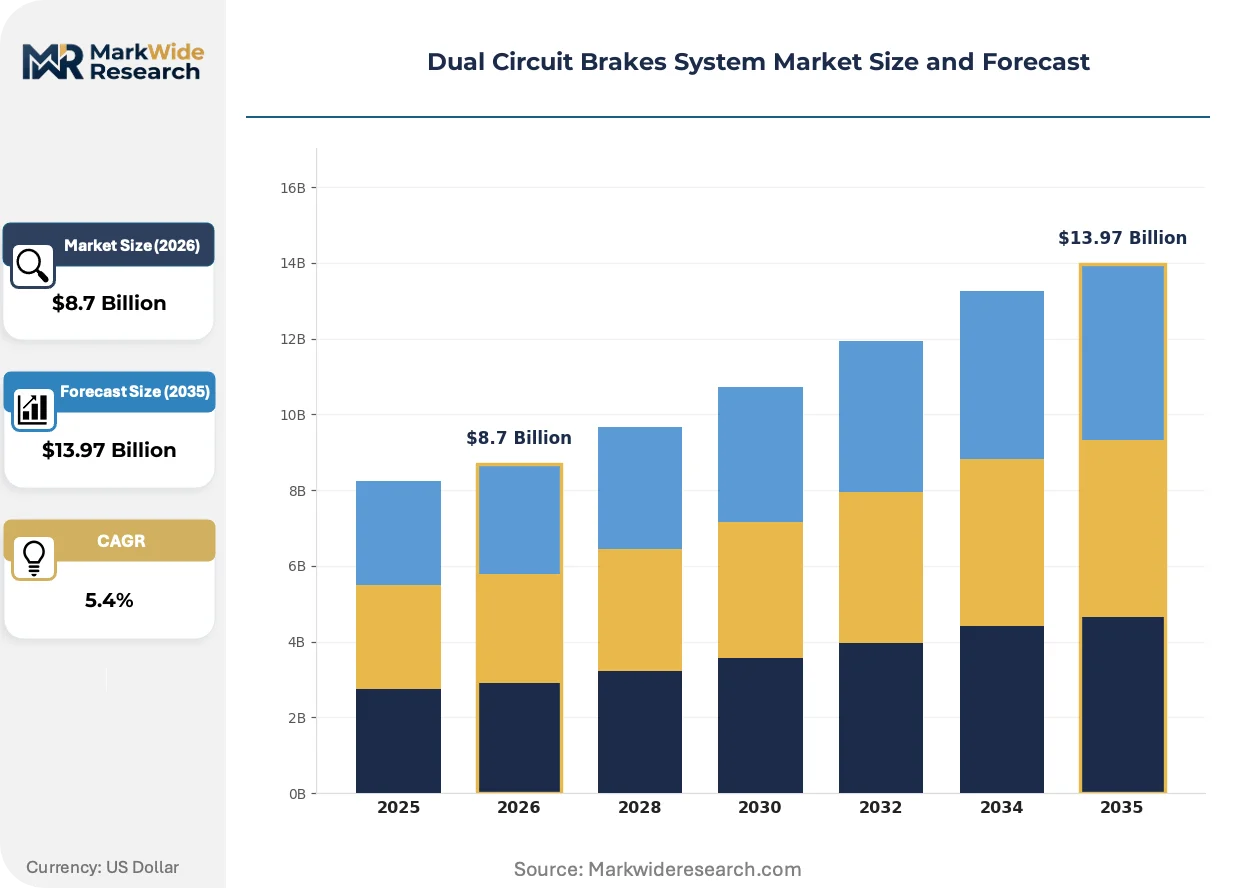
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Brakes, Disc Brakes, Hydraulic Brakes, Electromechanical Brakes Technology: ABS, EBD, ESC, Brake Assist End User: OEMs, Aftermarket Providers, Service Stations, Fleet Operators Application: Aerospace, Commercial Vehicles, Passenger Cars, Motorcycles |
| Companies Covered | Bosch, Continental AG, ZF Friedrichshafen AG, Aisin Corporation, Knorr-Bremse AG, Brembo S.p.A., Denso Corporation, Mando Corporation, WABCO Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Circuit Brakes System Market Shifts & Advancements
Brake system architecture is pivoting from hydraulic fluid transmission to electromechanical actuation, compressing established tier structures and rewiring how OEMs source safety-critical components.
Electromechanical brake-by-wire systems are decentralizing brake control authority from centralized hydraulic units to wheel-corner actuators. Passenger car OEMs adopting skateboard platforms are specifying these configurations for packaging efficiency and regenerative blending precision. This topology is decentralizing the traditional brake system value chain, displacing master cylinder and hydraulic line suppliers with motor-inverter-software integrators.
UN ECE R13-H harmonization with NHTSA fade-performance protocols is tightening test severity for thermal capacity and partial-circuit failure modes. Brake suppliers must now engineer single product variants that satisfy both regulatory regimes without regional customization. European premium passenger car programs are absorbing the bulk of compliance engineering costs, compressing margins for tier-two component specialists.
Fleet procurement of brake systems is consolidating around total-cost-of-ownership metrics that weight maintenance interval reduction against upfront hardware premiums. Commercial vehicle leasing companies in Germany are specifying electromechanical configurations despite higher acquisition costs, calculating payback through eliminated fluid changes and extended pad life. This behavioral shift is most visible in urban distribution chassis where stop-start duty cycles maximize regenerative energy recovery.
Dual Circuit Brakes System Market Segmentation
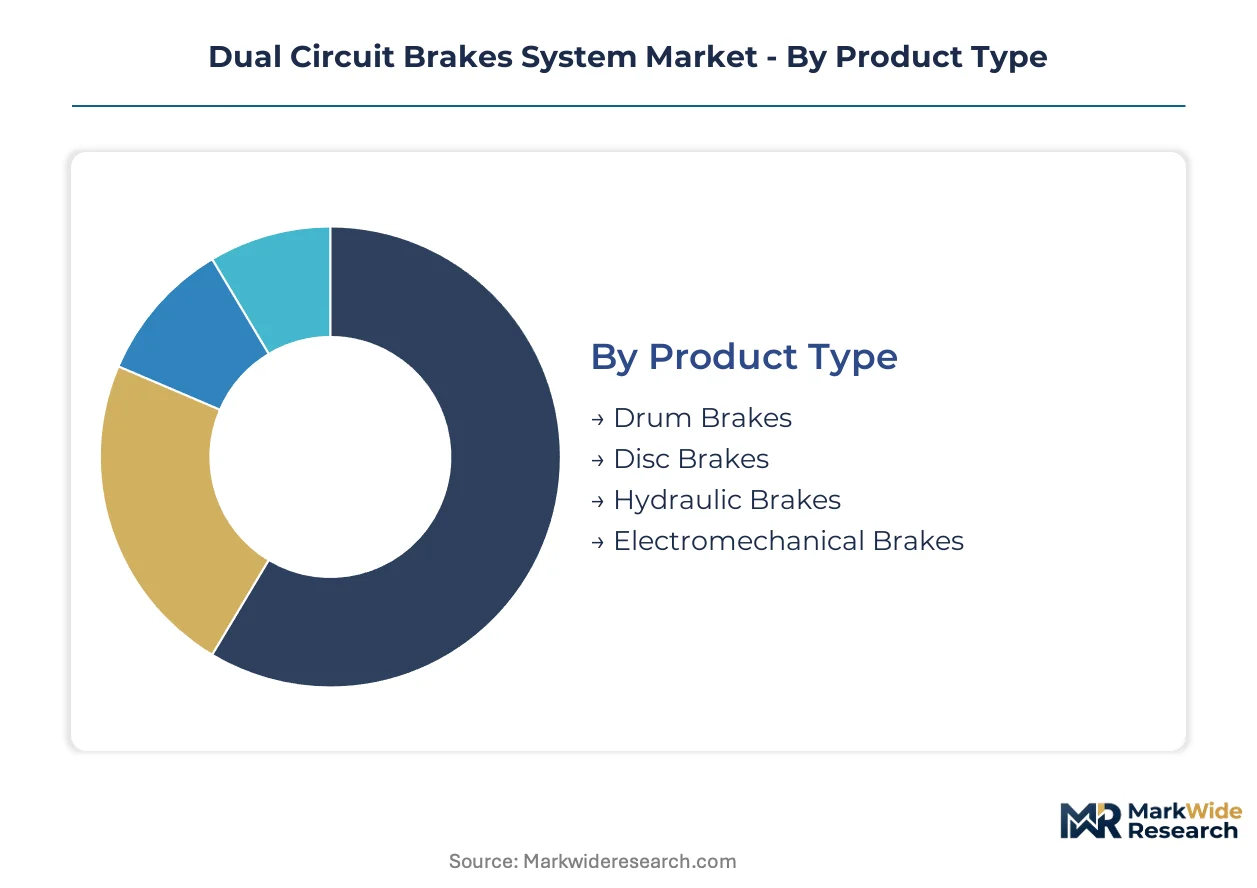
Dual circuit brake configurations vary sharply across vehicle platforms, with electromechanical architectures displacing hydraulic legacy systems in electric vehicle programs while drum brakes retain cost-sensitive commercial vehicle positions. Procurement patterns fragment across OEM direct supply, fleet operator specifications, and aftermarket retrofit channels, each demanding distinct performance certifications and service protocols.
Product Type:
Standardization dominates drum and disc brake architectures, while electromechanical systems demand platform-specific customization for skateboard chassis integration.
- Disc Brakes:Rotor-and-caliper configurations handle operating pressures between 100 and 180 bar with superior thermal capacity for repeated high-load deceleration. Passenger car OEMs in Germany specify ventilated disc variants for premium platforms, driven by NHTSA FMVSS 135 stopping-distance mandates that eliminate drum brake compliance pathways for light vehicles above compact class.
- Electromechanical Brakes:Motor-driven actuators eliminate hydraulic fluid entirely, enabling precise regenerative blending and packaging efficiency within battery-electric chassis rails. Demand concentrates with European OEMs transitioning to skateboard architectures, where Bosch and Continental anchor supply contracts through integrated brake control modules.
- Hydraulic Brakes:Dual-circuit master cylinder systems remain the majority installed base across internal combustion vehicle fleets.
- Drum Brakes:Cost-optimized configurations retain position in entry commercial vehicle axles where heat dissipation demands remain moderate.
Most installed capacity flows through Disc Brakes. Expansion is steepest in Electromechanical Brakes.
Technology:
Cost tier stratification separates mature ABS modules from premium ESC integrations requiring sophisticated sensor fusion and calibration engineering.
- ESC:Electronic Stability Control consolidates ABS, traction control, and yaw correction through integrated brake control modules that modulate individual wheel pressure during loss-of-control events. European premium passenger car programs absorb the bulk of compliance engineering costs as UN ECE R13-H harmonization tightens test severity for partial-circuit failure modes.
- ABS:Anti-lock Braking Systems prevent wheel lock-up during emergency deceleration through rapid pressure modulation, serving as the foundational safety layer mandated across road-legal vehicles. Demand persists in aftermarket retrofit channels across India commercial vehicle fleets, where BS-VI emission enforcement accelerates turnover of heavy-duty trucks and buses requiring upgraded dual-circuit configurations.
- EBD:Electronic Brakeforce Distribution optimizes front-rear braking bias based on load conditions.
- Brake Assist:Emergency braking augmentation systems detect panic pedal application and maximize hydraulic pressure.
ESC commands premium positioning in new vehicle programs. ABS maintains volume leadership through aftermarket penetration.
End User:
Customer type determines certification burden and procurement rhythm, with OEMs demanding full homologation support while fleet operators prioritize total-cost-of-ownership metrics.
- OEMs:Original equipment manufacturers specify brake systems during platform development, requiring tier-one suppliers to maintain backward compatibility with existing ESC and traction control calibrations across multi-platform deployments. Supply contracts with Bosch and Continental anchor European premium passenger car procurement, while ZF Friedrichshafen AG competes through manufacturing scale in hydraulic actuation systems.
- Fleet Operators:Commercial vehicle leasing companies in Germany and the Netherlands specify electromechanical configurations for urban delivery chassis, calculating payback through eliminated fluid changes and extended pad life despite higher acquisition costs.
- Aftermarket Providers:Independent distributors serve replacement demand for legacy hydraulic components.
- Service Stations:Maintenance facilities perform brake system inspections and component replacement per manufacturer service intervals.
OEMs capture the majority of electromechanical system volume. Fleet operators are adopting electromechanical configurations fastest.
Application:
Application maturity spans from established passenger car platforms to emerging aerospace brake-by-wire programs demanding redundant circuit architectures.
- Passenger Cars:Light vehicle platforms drive the bulk of dual-circuit brake system demand, with disc brake configurations standard across premium and mass-market segments. NHTSA brake safety mandates and UN ECE R13-H homologation standards tighten performance thresholds, forcing suppliers to engineer single product variants satisfying both regulatory regimes.
- Commercial Vehicles:Heavy-duty truck and bus programs require robust thermal capacity for sustained downhill braking, with drum brakes retaining cost-optimized positions in entry axles. Urban distribution chassis in Germany specify electromechanical configurations where stop-start duty cycles maximize regenerative energy recovery.
- Motorcycles:Two-wheeler applications demand compact dual-circuit packaging with reduced weight penalties.
- Aerospace:Aircraft braking systems employ redundant hydraulic and electromechanical architectures for fail-safe operation.
Passenger Cars absorb the majority of installed capacity. Commercial Vehicles are shifting toward electromechanical adoption fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor anchors brake system engineering for European OEM platforms transitioning to electromechanical architectures. NHTSA mandates in the United States and MIIT GB standards in China are creating divergent certification paths that reshape regional procurement priorities.
United States
Domestic light vehicle manufacturers face NHTSA FMVSS 135 stopping-distance thresholds that eliminate drum brake compliance pathways for mid-size and larger passenger cars. The Detroit Three are consolidating brake system procurement around electromechanical suppliers capable of dual-certification for cross-border platform engineering. Michigan's automotive engineering clusters concentrate validation testing for brake-by-wire electromagnetic compatibility protocols.
Germany
Commercial vehicle fleet operators in the Netherlands and Germany specify electromechanical configurations for urban delivery chassis to reduce maintenance intervals. UN ECE R13-H homologation alignment with US fade-performance benchmarks simplifies cross-border platform engineering for multinational automakers headquartered in Stuttgart and Munich. Baden-Württemberg supplier parks integrate brake control modules with skateboard battery-electric architectures.
China
Domestic electric vehicle manufacturers are eliminating hydraulic fluids from platforms under MIIT GB electromagnetic compatibility requirements for brake-by-wire systems. Shanghai and Shenzhen automotive clusters concentrate electromechanical brake motor production, though neodymium magnet supply dependence exposes cost structures to export quota volatility. BYD and NIO are specifying integrated brake control modules for new skateboard chassis programs.
India
BS-VI emission enforcement is accelerating commercial vehicle fleet turnover, creating aftermarket demand for upgraded dual-circuit systems in heavy-duty trucks and buses. The Society of Indian Automobile Manufacturers is coordinating with BIS on brake system certification alignment with UN ECE frameworks. Chennai and Pune manufacturing corridors concentrate hydraulic brake component production for domestic OEM supply and export to Middle East markets.
Japan
Domestic OEMs maintain hybrid vehicle brake system production with dual-circuit hydraulic architectures serving regenerative blending functions. METI industrial policy supports electromechanical brake R&D through automotive technology development subsidies. Toyota City and Hiroshima supplier networks integrate brake control modules with hybrid powertrain calibrations for Southeast Asian export markets.
Dual Circuit Brakes System Market Competitive Landscape
Portfolio diversification dominates the current landscape as tier-one suppliers reconfigure manufacturing footprints across hydraulic legacy and electromechanical product lines. The market structure concentrates around three strategic archetypes: diversified automotive suppliers with full-system integration capability, brake-focused specialists with thermal engineering heritage, and electronics-centric entrants from adjacent sensor and motor domains. M&A activity targets electromechanical software competencies, while capacity expansion concentrates in battery-electric vehicle production corridors.
Within the diversified supplier tier, Bosch and Continental AG exemplify full-system integrators capable of anchoring European OEM skateboard architecture contracts, while ZF Friedrichshafen AG occupies a position emphasizing manufacturing scale in hydraulic actuation systems serving commercial vehicle programs. These three German-based entities represent contrasting strategic postures: integrated brake control module development, electromechanical portfolio transition, and hydraulic legacy optimization for fleet applications.
| Leading Market Players |
|---|
| Bosch |
| Continental AG |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| Knorr-Bremse AG |
| Brembo S.p.A. |
| Denso Corporation |
| Mando Corporation |
| WABCO Holdings |
| Others |
Supply & Pricing Matrix
Captive in-house production of electromechanical brake motors anchors supply positioning and pricing power for tier-one suppliers, insulating them from neodymium magnet cost volatility while forcing tier-two hydraulic specialists into commodity pricing traps. This integration choice concentrates margin capture with Bosch and Continental in European skateboard architecture contracts, leaving dependent distributors to absorb price erosion in legacy master cylinder segments.
Pricing Analysis
Neodymium magnet cost pass-through dominates electromechanical brake pricing, with rare earth export quota volatility from China feeding directly into motor-inverter module quotations. Three-tier pricing structure across premium, standard, and economy levels separates OEM direct supply from fleet procurement and aftermarket retrofit channels, with certification grade for UN ECE R13-H homologation commanding substantial premiums. Pricing pressure stems from hydraulic component depreciation as OEMs freeze new fluid-based program development, compressing margins for ABS modulator specialists. Fleet operators in Germany exhibit lowest price sensitivity, calculating total-cost-of-ownership payback through eliminated fluid changes, while Indian aftermarket channels remain most cost-conscious.
Supply Chain Analysis
Reverse-logistics flows for brake caliper remanufacturing concentrate in Germany and the Netherlands, where fleet operators specify refurbished electromechanical actuators to reduce maintenance intervals in urban delivery chassis. Geographic supply concentration centers on China for neodymium processing, Germany for integrated brake control module assembly, and Japan for hybrid brake system calibrations. Raw material dependencies rest on rare earth magnets, high-grade aluminum castings, and semiconductor chips for motor control. Single-source vulnerability in Chinese magnet supply exposes cost structures to export quota friction. Distribution runs through OEM direct supply for electromechanical systems, with hydraulic legacy components flowing via aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with NHTSA FMVSS 135 stopping-distance mandates and UN ECE R13-H homologation convergence accelerating replacement cycles across light vehicle fleets. Compliance engineering costs concentrate in European premium platforms, creating margin capture opportunities for certified suppliers.
For Market Incumbents: Anticipate hydraulic program obsolescence by accelerating electromechanical brake-by-wire R&D allocation and securing MIIT GB certification for Chinese skateboard platform contracts. Backward integration into neodymium magnet sourcing or alternative motor topologies mitigates rare earth supply concentration risk. Certification investment in dual NHTSA-UN ECE compliance pathways defends position against emerging electronics-centric entrants from adjacent sensor domains. For New Entrants and Emerging Players: Software-defined brake control modules offer entry wedge through functional safety expertise scarce in traditional brake engineering departments. Target India commercial vehicle aftermarket retrofit demand, where BS-VI enforcement accelerates fleet turnover requiring upgraded dual-circuit configurations. Go-to-market through fleet operator direct procurement channels bypasses entrenched OEM supply relationships. For Investors and Strategic Acquirers: Roll-up economics work for brake-focused specialists with thermal engineering heritage because hydraulic-to-electromechanical transition fragments manufacturing footprints and creates distressed asset opportunities. Long-term viability favors suppliers with integrated brake control module capability spanning ABS, ESC, and brake-by-wire functions. Monitor MIIT GB electromagnetic compatibility certification timelines as inflection indicator for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Skateboard architecture contracts with European OEMs consolidate brake-by-wire module procurement around integrated suppliers. |
| Battery Supply Agreement | Electromechanical brake motor sourcing ties to EV platform battery-electric chassis rail packaging requirements. |
| Software-Defined Vehicle Investment | Brake-by-wire architectures demand embedded software engineers with ISO 26262 functional safety expertise. |
| Geographic Manufacturing Footprint | Baden-Württemberg supplier parks anchor European electromechanical brake production for skateboard platforms. |
| Charging Infrastructure Partnership | Regenerative blending precision requirements link brake system calibration to EV charging cycle optimization. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, tier-one supplier procurement patterns, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary interviews with brake system R&D directors, fleet procurement managers, aftermarket distributors, and homologation specialists informed demand-side validation. Secondary sources included NHTSA FMVSS 135 test documentation, UN ECE R13-H type-approval records, vehicle production databases, and customs trade data for hydraulic component flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeled by propulsion architecture, vehicle class, content per vehicle, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and platform transition timelines. Industry-specific forecast inputs incorporated neodymium magnet price indices and OEM skateboard architecture rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export policy shifts and brake-by-wire electromagnetic compatibility protocol divergence. Practitioners should monitor MIIT GB certification timelines and fleet operator total-cost-of-ownership model adoption for early signals of procurement pattern inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market