
 Portable Water Purifier Market | 2026-2036
Portable Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Water Purifier Market Outlook
The portable water purifier market is pivoting on a widening gulf between premium certified systems and commodity-grade alternatives. Katadyn Group anchors the premium tier through Swiss-engineered ceramic filtration and military contract relationships. Sawyer Products competes aggressively on hollow-fiber membrane cost efficiency and mass retail channel control. Vestergaard, through its LifeStraw brand, dominates humanitarian procurement with institutional buyers and disaster relief agencies.
A portable water purifier is a self-contained, manually operated device that reduces or eliminates microbiological contaminants, particulates, and chemical impurities from untreated water sources, typically achieving bacterial log reduction through physical filtration barriers, ultraviolet irradiation, or electrochemical disinfection. Gravity filters and UV purifiers lead volume shipments, with gravity systems sustaining margin pools in base-camp and emergency shelter applications while UV sterilization technology captures fastest growth among ultralight backpackers. Pump filters occupy a mature niche where replacement cartridge economics still attract recurring revenue, and bottle-integrated formats are displacing standalone units in urban travel segments.
EPA microbiological purifier standards and NSF/ANSI 53 and 42 protocols govern product legitimacy in the United States, while EU REACH and CE marking requirements shape material composition and electrical safety for UV models sold across Europe. India's BIS certification and China's GB standards for household water treatment impose additional testing burdens that filter out uncertified competitors. Stakeholders must monitor regulatory divergence between jurisdictions as emerging economies adopt stricter contaminant thresholds that could obsolete existing product lines.
Market Dynamics
Certification divergence between EPA microbiological purifier standards and emerging economy mandates is fragmenting product architectures, forcing manufacturers to maintain parallel filter housing designs and testing protocols for different export markets.
Growth Catalysts
- Trail tourism surge:Backpackers and wilderness trekkers in Indonesia, Vietnam, and the Philippines drive gravity filter adoption where tourism infrastructure gaps persist.
- NSF/ANSI 53 certification:Tightened material safety thresholds in the United States elevate consumer willingness to pay for validated systems over commodity alternatives.
- Hollow-fiber membrane cost curves:Manufacturing scale efficiencies reduce per-unit filtration costs, expanding addressable demand among price-sensitive humanitarian procurement channels.
Market Restraints
- UV lamp semiconductor dependency:Germanium and gallium supply concentration in China creates input cost volatility for ultraviolet sterilization assemblies.
- Replacement cartridge economics:Pump filter incumbents capture recurring revenue streams that lock buyers into proprietary formats, raising effective lifetime ownership costs.
- EU REACH compliance burdens:Material composition restrictions on plastic housings and O-ring seals force reformulation cycles that delay European market entry.
Strategic Opportunities
- India BIS certification gap:Uncertified competitors face exclusion from formal retail channels, creating white space for compliant entrants in tier-2 and tier-3 cities.
- Bottle-integrated formats:Urban travel segments show preference for all-in-one designs that displace standalone pump and gravity systems in airport and hotel retail.
- Disaster relief institutional procurement:United Nations and NGO tender volumes for ceramic and hollow-fiber emergency kits outpace commercial segment growth rates.
Industry Challenges
- Multi-jurisdiction testing timelines:EPA, NSF, BIS, and GB standard sequences extend certification cycles by 14-22 months for new product launches.
- Filter media integration complexity:Combining ceramic, activated carbon, and hollow-fiber layers in compact formats demands specialized polymer bonding expertise that concentrates among Swiss and German suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Water Purifier Market |
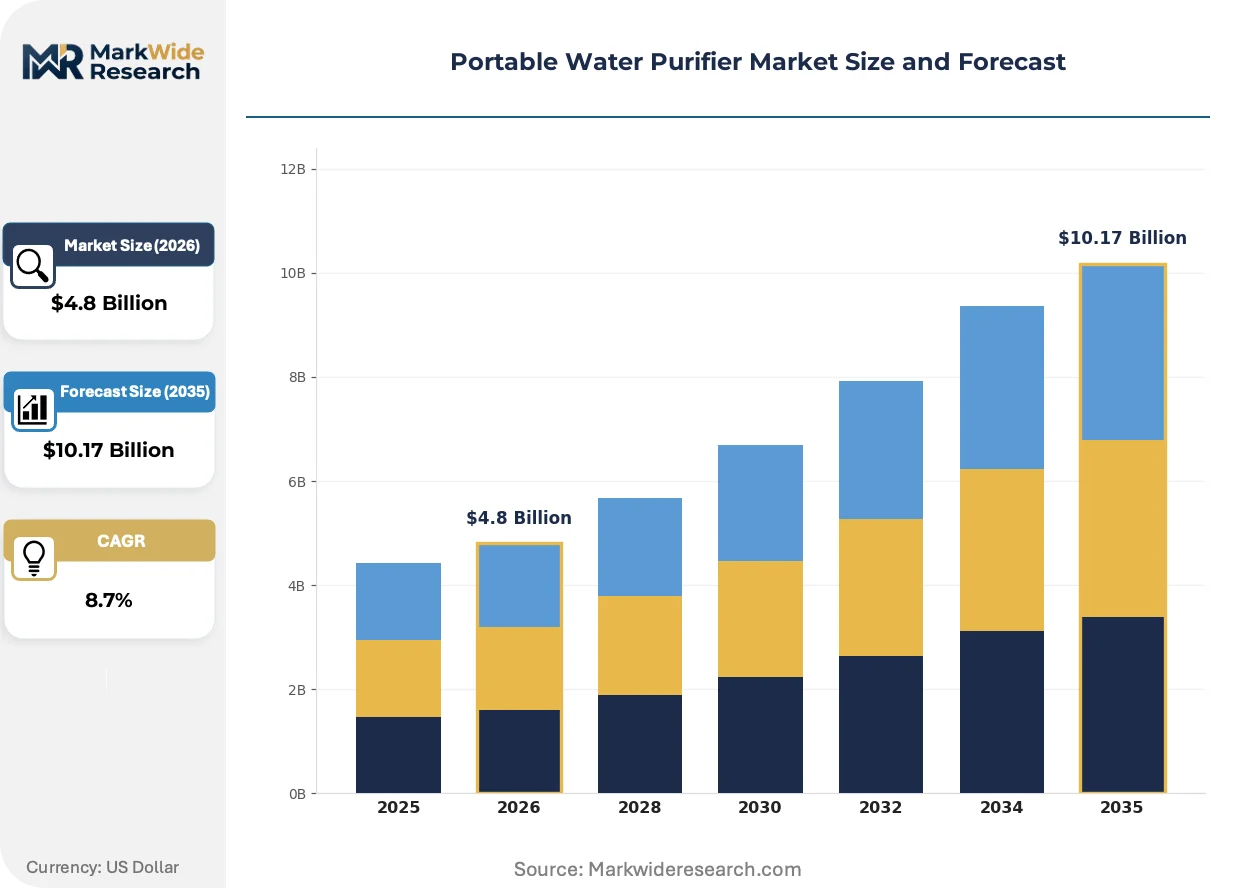
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gravity filters, UV purifiers, Pump filters, Bottle filters Use Case: Emergency preparedness, Outdoor activities, Travel, Military End User: Campers, Hikers, Travelers, Emergency responders Technology: Reverse osmosis, UV sterilization, Activated carbon, Electrochemical |
| Companies Covered | Katadyn Group, Sawyer Products, Vestergaard (LifeStraw), 3M, SteriPEN, Pentair, A. O. Smith Corporation, BRITA SE, GRAYL, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Water Purifier Market Strategic Shifts
Portable purification systems are converging with connected diagnostics and sustainable materials, compressing the gap between laboratory-grade performance and field-deployable convenience.
Electrochemical disinfection technology is modularizing across ultralight backpacking segments. Titanium electrode arrays embedded in collapsible vessels deliver viral and protozoan inactivation without filter replacement schedules. Thru-hikers on the Pacific Crest and Appalachian trails adopt these systems at accelerating rates. The format is modularizing supply chains, allowing original equipment manufacturers to source electrode subassemblies separately from vessel fabrication.
EPA's 2023 guidance on emerging contaminant testing for PFOA and PFAS in backcountry water sources is forcing redesigns of activated carbon block specifications. Manufacturers must demonstrate adsorption capacity below 70 parts per trillion to maintain purifier claims. Gravity filter systems targeting base-camp applications face the steepest reformulation costs, with several suppliers withdrawing SKUs rather than absorbing retesting expenses.
Humanitarian buyers now specify outcome-based verification rather than unit procurement, requiring suppliers to document actual health impact in deployment settings. This displaces traditional tender models based on unit cost and flow rate specifications alone. Disaster relief agencies in Southeast Asia pilot these contracts first, with procurement committees in Indonesia and the Philippines rewriting standard bidding documents to incorporate field efficacy clauses.
Portable Water Purifier Market Segmentation
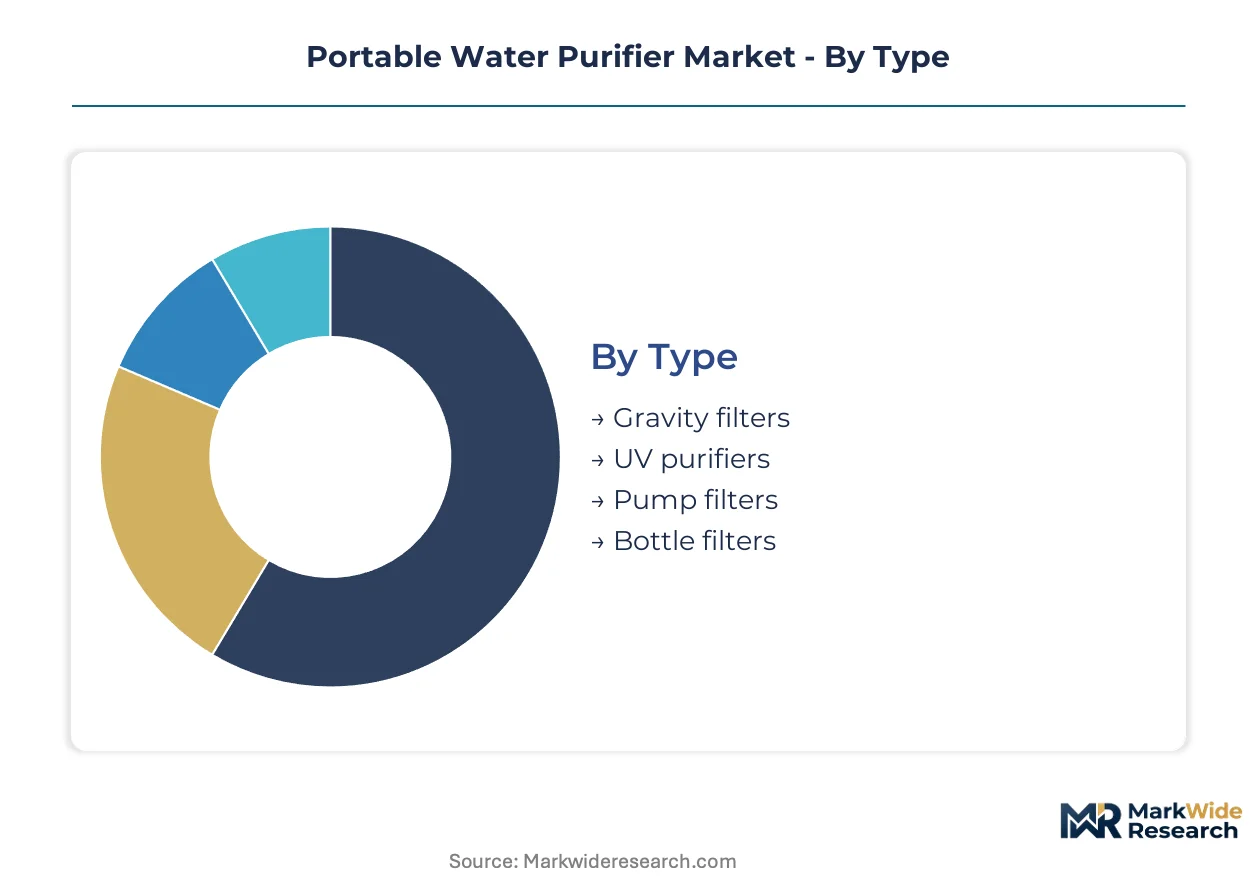
Portable water purifier purchasing decisions split sharply between weight-constrained backpackers seeking ultralight solutions and institutional buyers prioritizing certified throughput volumes. Segment boundaries blur as bottle-integrated formats absorb functions once served by standalone pump and gravity systems.
Type:
Buyers choose filtration architecture based on group size, water source turbidity, and tolerance for field maintenance.
- Gravity filters:Ceramic and hollow-fiber membrane columns suspend from elevated points, delivering batch volumes through passive head pressure. Base-camp operators in Indonesia and Vietnam favor these for group filtration where electricity access is unreliable.
- UV purifiers:Mercury-free LED or mercury-vapor lamp assemblies emit germicidal wavelengths to disrupt pathogen DNA. Ultralight backpackers on the Pacific Crest Trail adopt these formats fastest as semiconductor costs decline and battery efficiency improves.
- Pump filters:Hand-operated piston mechanisms force water through pleated microfilters. Replacement cartridge economics sustain recurring revenue for incumbent suppliers.
- Bottle filters:Integrated sip-and-filter designs combine vessel and purification in single units. Airport and hotel retail channels in Southeast Asia stock these for urban travelers.
Volume sits with gravity filters; growth tilts toward UV purifiers.
Use Case:
Application context dictates certification requirements, durability specifications, and procurement channel selection.
- Emergency preparedness:Stockpiled systems for natural disaster response require indefinite shelf stability and zero-power operation. Philippine government warehouses specify ceramic filtration for flooding season readiness.
- Outdoor activities:Backpacking and wilderness trekking demand sub-kilogram weights and multi-pathogen protection. Thru-hikers prioritize viral inactivation capabilities for backcountry water sources.
- Travel:International tourists face variable municipal water quality across destinations. Bottle-integrated formats displace pump systems in this segment.
- Military:Defense procurement mandates NSF P248 or comparable field durability standards. Swiss and German suppliers dominate tender processes.
Emergency preparedness commands procurement volumes; outdoor activities expand most quickly.
End User:
User technical sophistication and risk tolerance shape interface design and instruction complexity.
- Campers:Car-based recreational users accept heavier systems with higher flow rates. Weekend users in the United States gravitate toward pump filters with intuitive maintenance.
- Hikers:Long-distance trail users prioritize gram-scale weight reduction above all other attributes. Appalachian Trail thru-hikers drive UV and electrochemical adoption.
- Travelers:Urban and resort visitors seek plug-and-play simplicity without field assembly. Southeast Asian tourism corridors absorb disproportionate unit volumes.
- Emergency responders:Professional disaster relief personnel require validated log-reduction documentation. United Nations tenders now specify outcome-based verification rather than unit counts.
Campers generate baseline demand; hikers gain share fastest.
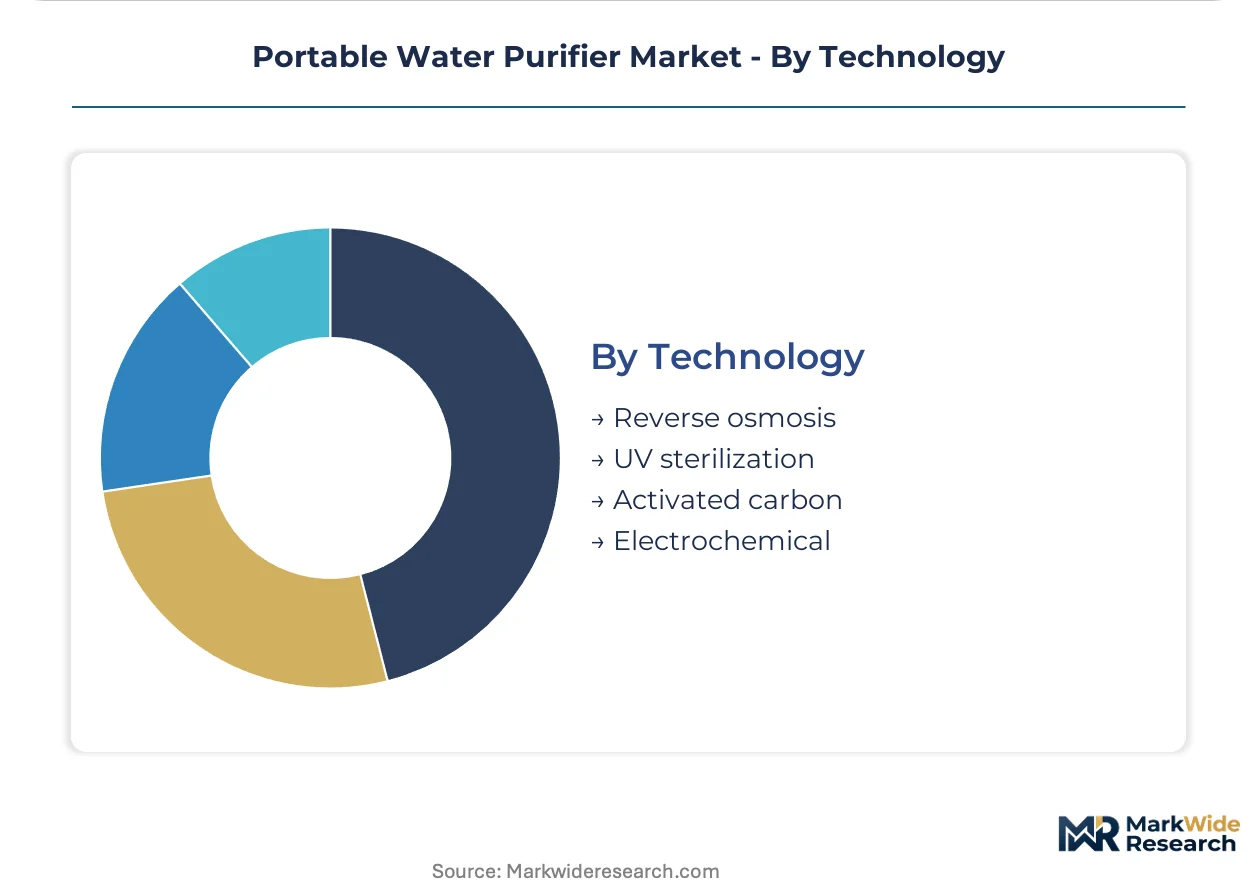
Technology:
Purification mechanism selection involves tradeoffs between pathogen spectrum coverage, energy requirements, and consumable replacement schedules.
- Reverse osmosis:Semipermeable membranes block dissolved salts, heavy metals, and microbiological contaminants through pressure-driven separation. Marine and extreme chemical contamination scenarios deploy these despite weight penalties.
- UV sterilization:Photonic disruption of nucleic acids inactivates bacteria, viruses, and protozoa without filter media. EPA microbiological purifier standards govern efficacy claims.
- Activated carbon:Porous carbon structures adsorb chemical contaminants, chlorine, and emerging pollutants including PFOA and PFAS. Reformulation costs spike under EPA guidance.
- Electrochemical:Titanium electrode arrays generate reactive oxidant species through electrolysis. Collapsible vessel formats modularize supply chains for ultralight segments.
Activated carbon dominates unit economics; electrochemical climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta's industrial corridors channel Southeast Asian demand for gravity filtration systems as flooding seasons disrupt municipal water infrastructure across Indonesia. The region's procurement patterns diverge sharply between certified premium systems for institutional buyers and commodity units for informal retail channels.
United States
Backpackers on the Pacific Crest Trail drive UV purifier adoption where gram-counting outweighs upfront cost. EPA microbiological purifier standards and NSF/ANSI 53 protocols govern product legitimacy, elevating validated systems over uncertified alternatives. Denver and Boulder outdoor retail clusters concentrate brand headquarters and field-testing operations for mountain recreation segments.
Germany
EU REACH compliance burdens reshape material specifications for plastic housings and O-ring seals bound for European markets. German engineering clusters around Munich and Stuttgart anchor ceramic filtration expertise and precision manufacturing for military contract specifications. Defense procurement mandates NSF P248 field durability standards that concentrate tender awards among domestic suppliers.
India
Tier-2 and tier-3 cities present white space for BIS-certified entrants as uncertified competitors face exclusion from formal retail channels. The Bureau of Indian Standards certification imposes testing burdens that filter out low-grade alternatives. Maharashtra and Gujarat industrial zones concentrate domestic assembly operations for price-sensitive humanitarian procurement channels.
China
Germanium and gallium supply concentration creates input cost volatility for UV lamp semiconductor assemblies manufactured in Shenzhen and Dongguan electronics corridors. GB standards for household water treatment impose additional testing protocols that delay market entry for foreign-designed products. Yangtze River Delta manufacturing bases supply hollow-fiber membrane components at scale-driven cost curves.
Philippines
Government warehouses specify ceramic filtration systems for flooding season emergency preparedness stockpiles across the archipelago. Disaster relief agencies pilot outcome-based verification contracts that displace traditional unit-cost tender models. Cebu and Davao distribution hubs channel procurement volumes for institutional buyers rewriting standard bidding documents.
Portable Water Purifier Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered structure where certification depth separates premium positioning from commodity erosion. The market fragments across Swiss-engineered ceramic specialists, hollow-fiber membrane cost leaders, and humanitarian procurement dominators. Three archetypes define competitive positioning: military-grade durability suppliers, mass retail channel controllers, and institutional outcome-based contractors. Dominant competitive moves include geographic certification sequencing and portfolio diversification into bottle-integrated formats.
Within the premium-tier archetype, Katadyn Group anchors Swiss-engineered positioning through military contract relationships. Sawyer Products occupies the cost-efficiency vector with hollow-fiber membrane scale and mass retail penetration. Vestergaard, through its LifeStraw brand, exemplifies the institutional procurement specialist serving United Nations and NGO tender channels.
| Leading Market Players |
|---|
| Katadyn Group |
| Sawyer Products |
| Vestergaard (LifeStraw) |
| 3M |
| SteriPEN |
| Pentair |
| A. O. Smith Corporation |
| BRITA SE |
| GRAYL, Inc |
| Others |
Value Chain & Pricing Dynamics
EU REACH compliance on plastic housings and O-ring seals gates qualified supply for European market access, concentrating premium-tier pricing power among German and Swiss manufacturers with pre-certified material streams. This environmental mandate forces commodity-grade competitors into parallel product architectures or exclusion, compressing mid-tier margin pools while validated suppliers capture pricing premiums.
Pricing Analysis
Throughput-based certification anchoring dominates portable water purifier pricing, with EPA microbiological purifier standards and NSF/ANSI 53 protocols commanding 40-60% premiums over uncertified alternatives. Price differentiation rests on log-reduction validation and replacement cartridge bundling, with humanitarian procurement channels squeezing suppliers on volume scale while ultralight backpackers absorb premium positioning for gram-reduced formats. Cost compression in hollow-fiber membrane tiers intensifies as Chinese manufacturing scale feeds price erosion, though semiconductor-dependent UV assemblies face upward pressure from germanium and gallium supply volatility. Institutional buyers at United Nations and NGO tenders exhibit lowest price sensitivity; informal retail channels in Southeast Asia absorb highest sensitivity.
Supply Chain Analysis
India's PLI scheme and domestic-content preferences for BIS-certified assembly are reshaping sourcing patterns, pulling final-stage manufacturing away from pure export-platform models. Component supply concentrates in China for hollow-fiber membranes and UV lamp semiconductors, Switzerland and Germany for ceramic filtration expertise, and Vietnam for gravity-filter vessel fabrication. Raw material dependencies span medical-grade polymers for filter housings, activated carbon blocks for chemical adsorption, and rare-earth elements for LED sterilization arrays. Single-source vulnerability runs through Yangtze River Delta semiconductor processing for UV assemblies. Distribution feeds through outdoor retail clusters in Denver and Boulder, humanitarian procurement hubs in Geneva and Copenhagen, and airport retail networks across Jakarta, Manila, and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable water purifier market is becoming a vertical-integration race, with control over certified filter media production and multi-jurisdiction testing infrastructure as the decisive upstream lever separating sustainable margin pools from commodity erosion.
For Market Incumbents: Anchor defensive positioning through captive supply of hollow-fiber membrane substrates and ceramic filtration expertise concentrated among Swiss and German engineering clusters. Deepen certification moats by sequencing EPA, NSF, BIS, and GB standard approvals ahead of emerging economy regulatory tightening, while acquiring electrochemical disinfection technology to offset UV semiconductor supply risk from China concentration. For New Entrants and Emerging Players: The mid-tier price-point gap between Katadyn-engineered premium systems and uncertified commodity alternatives offers white-space entry for BIS-compliant challengers in Indian tier-2 and tier-3 cities. Target disaster relief institutional procurement in Indonesia and the Philippines where outcome-based verification contracts are rewriting tender specifications, using field efficacy documentation as the go-to-market wedge against unit-cost incumbents. For Investors and Strategic Acquirers: EPA's 2023 PFOA/PFAS guidance forcing activated carbon reformulation is the leading indicator that regulatory compliance depth will consolidate supplier tiers over the five-to-ten year horizon. Acquisition focus should center on mid-scale manufacturers with existing multi-certification portfolios and polymer bonding expertise for layered filter integration, watching for inflection when humanitarian buyers fully transition to outcome-based procurement clauses in Southeast Asian tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media Production | Captive hollow-fiber membrane supply insulates margin pools from Chinese cost-curve volatility. |
| Multi-Jurisdiction Certification Sequencing | Parallel EPA, BIS, and GB approvals compress time-to-revenue across fragmented regulatory landscapes. |
| Outcome-Based Contracting Capability | Field efficacy documentation aligns with United Nations tender evolution in Southeast Asian disaster relief. |
| Electrochemical Technology Acquisition | Titanium electrode arrays reduce dependency on UV lamp semiconductor supply chains concentrated in China. |
| Bottle-Integrated Format Development | All-in-one designs capture urban travel segments displacing standalone pump and gravity systems. |
Study Parameters
Trade databases, customs records, and EPA/NSF certification registries formed the secondary backbone, supplemented by SEC filings from publicly listed component suppliers and humanitarian procurement contract disclosures. Primary fieldwork encompassed product managers at outdoor equipment manufacturers, regulatory affairs specialists navigating multi-jurisdiction approval sequences, procurement officers at United Nations agencies, and channel buyers at Denver-Boulder retail clusters. Bottom-up and top-down triangulation cross-validated shipment volumes against certification database entries and tender award documentation.
Bottom-up modeling aggregated unit economics across filtration technology tiers, while top-down verification checked aggregate market value against import-export flows and retail audit data. Segmentation dimensions spanned purification mechanism, use case context, end-user technical sophistication, and regional regulatory cluster. CAGRs derived from weighted average of historical certification timeline compression and projected adoption curves in trail tourism corridors. Forecast inputs incorporated semiconductor cost trajectories for UV assemblies and electrochemical modularization rates among Pacific Crest Trail thru-hikers.
Inputs from certification databases and humanitarian procurement registries were available through the study window; gaps in real-time inventory positioning at informal retail channels in Southeast Asia introduce uncertainty bands around volume estimates in commodity-grade tiers. Forecasts embed assumptions on regulatory timeline stability and rare-earth element supply continuity that material shifts could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Asia-Pacific Water Purifier Market