
 Water Treatment As a Service Market | 2026-2036
Water Treatment As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Water Treatment As a Service Market Intelligence
Aftermarket service revenue is rewriting capital deployment patterns across water infrastructure. Veolia leverages its integrated operations platform to bundle chemical treatment with remote monitoring, anchoring long-term municipal contracts. Xylem sustains technology leadership in membrane-based reverse osmosis systems, while SUEZ competes through specialized ion exchange services for semiconductor fabs.
Water Treatment As a Service delivers outsourced purification, disinfection, and filtration through performance-based contracts rather than asset ownership, typically specifying output quality metrics such as total dissolved solids below 10 ppm or microbial compliance per local potable standards. The model shifts balance sheet burden from municipal utilities and industrial plants to specialized operators. Reverse osmosis and UV treatment service categories capture premium pricing due to energy-intensive operations and specialized technician requirements. Membrane technology dominates installed capacity, though ozone treatment segments expand fastest in pharmaceutical and food processing applications where residual-free disinfection matters.
The US EPA enforces effluent limitation guidelines that push manufacturing plants toward third-party compliance services, while China's MEE administers dual carbon goals tightening industrial wastewater discharge permits. The EU Green Deal and REACH frameworks impose chemical usage reporting that favors service providers with centralized chemical management. Stakeholders must monitor how regulatory fragmentation across jurisdictions shapes contract structures and technology selection criteria.
Market Dynamics
Municipal balance sheet strain is compressing capital ownership timelines and accelerating performance-based contracting across water infrastructure. Utilities now prioritize operational expenditure models over asset-heavy builds, fundamentally restructuring vendor-customer relationships.
Growth Catalysts
- EPA Effluent Limitation Guidelines:US manufacturing facilities face mandated discharge reductions that exceed in-house treatment capabilities, forcing outsourced compliance partnerships.
- Semiconductor fabrication expansion:Ultra-pure water requirements at advanced nodes below 7nm drive specialized service contracts for ion exchange and membrane filtration systems.
- China's MEE discharge mandates:State-owned enterprises in the Yangtze River basin must meet tightening COD and ammonia nitrogen limits without expanding physical footprint.
Market Restraints
- Membrane supply concentration:Polyamide thin-film composite production clusters in Japan and the United States, creating vulnerability to trade flow disruptions.
- Energy cost volatility:Reverse osmosis operations consume 3-15 kWh per thousand gallons, exposing operators to electricity price swings in deregulated markets.
- Legacy infrastructure lock-in:Municipal plants with 30-50 year depreciation schedules resist full outsourcing despite operational inefficiencies.
Strategic Opportunities
- India's industrial corridor buildout:Gujarat and Tamil Nadu special economic zones lack integrated treatment infrastructure, creating greenfield service contract potential.
- Pharmaceutical residual-free mandates:FDA guidance on elemental impurities favors ozone and UV disinfection over chemical alternatives in sterile manufacturing.
- Digital twin convergence:Real-time sensor networks combined with predictive analytics enable guaranteed uptime clauses that differentiate premium service tiers.
Industry Challenges
- Certified membrane technician scarcity:Fouling diagnosis and chemical cleaning protocols require specialized training that outpaces vocational program output.
- Legacy SCADA integration friction:Municipal plants running 1990s-era control systems resist API-based remote monitoring without costly middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Treatment As a Service Market |
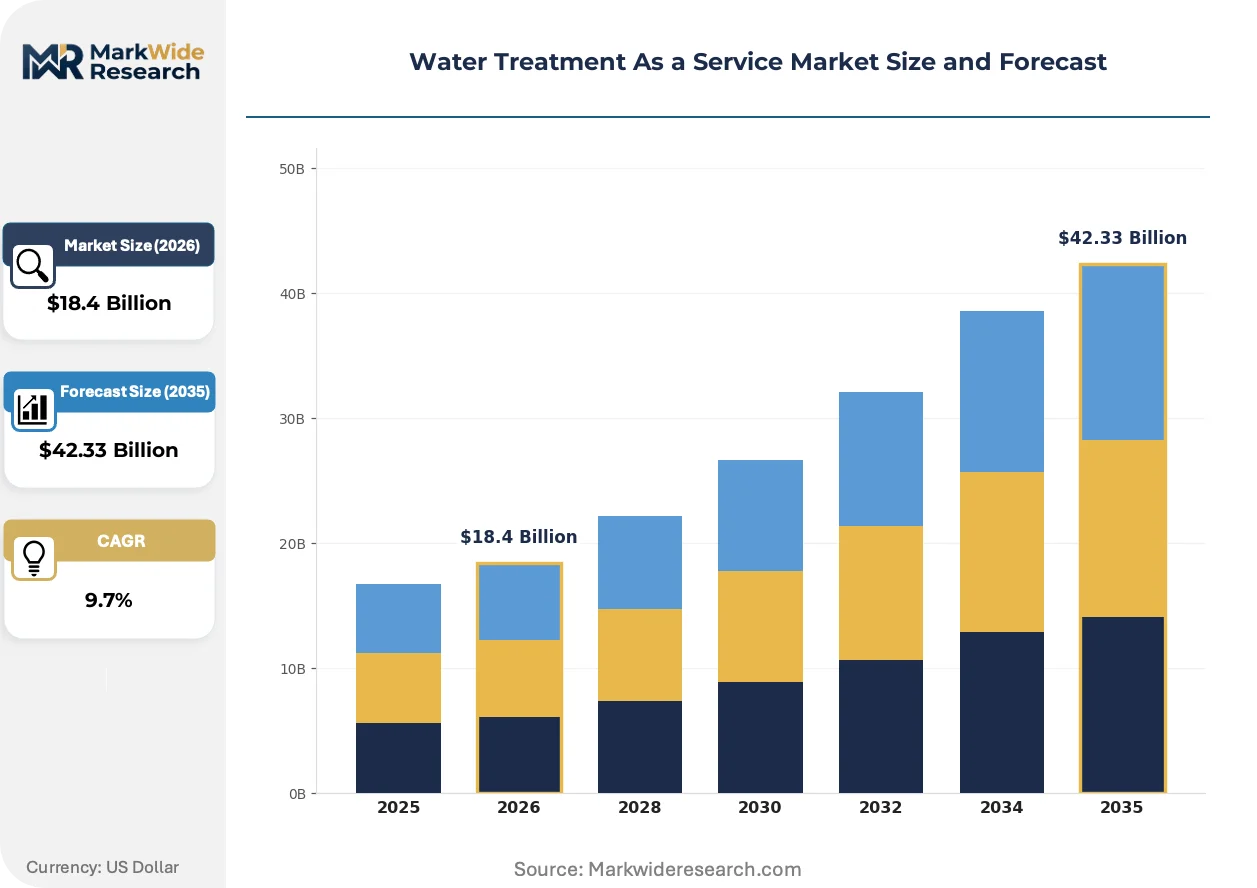
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $42.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Chemical Treatment, Filtration, Reverse Osmosis, UV Treatment Application: Municipal Water Supply, Industrial Process Water, Wastewater Management, Agriculture End User: Water Utilities, Manufacturing Plants, Schools, Hospitals Technology: Membrane Technology, Activated Sludge, Ozone Treatment, Ion Exchange |
| Companies Covered | Seven Seas Water Group, Aquatech International LLC, Waterleau, Quench USA, Inc., Chart Industries, OriginClear, Veolia, SUEZ, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Treatment As a Service Market Strategic Shifts & Innovations
Service delivery models are fragmenting into outcome-guaranteed micro-contracts that shift technical risk entirely to operators. This compression of accountability timelines is reshaping R&D priorities across the vendor base.
Membrane bioreactor technology is hybridizing with anaerobic digestion processes to slash energy intensity in high-strength industrial wastewater. Food and beverage processors in the Netherlands and Denmark are piloting these integrated systems at 40% reduced aeration demand. The convergence is hybridizing project economics and enabling shorter payback periods that accelerate municipal adoption.
The EU Green Deal's chemical footprinting requirements are forcing centralized chemical management across multi-site manufacturing portfolios. REACH Article 33 extended producer responsibility now covers process chemicals, not just products. German automotive suppliers are consolidating treatment contracts with single-service providers to streamline compliance documentation.
Performance guarantees now specify energy-per-gallon thresholds alongside quality metrics, compressing vendor accountability into unified SLA frameworks. Industrial buyers in Texas and Louisiana are unbundling capex and opex into distinct contract vehicles that separate infrastructure refresh from ongoing operations. This bifurcation is most visible in oilfield produced water treatment, where operators demand guaranteed barrels-per-day throughput independent of inlet variability.
Water Treatment As a Service Market Segmentation
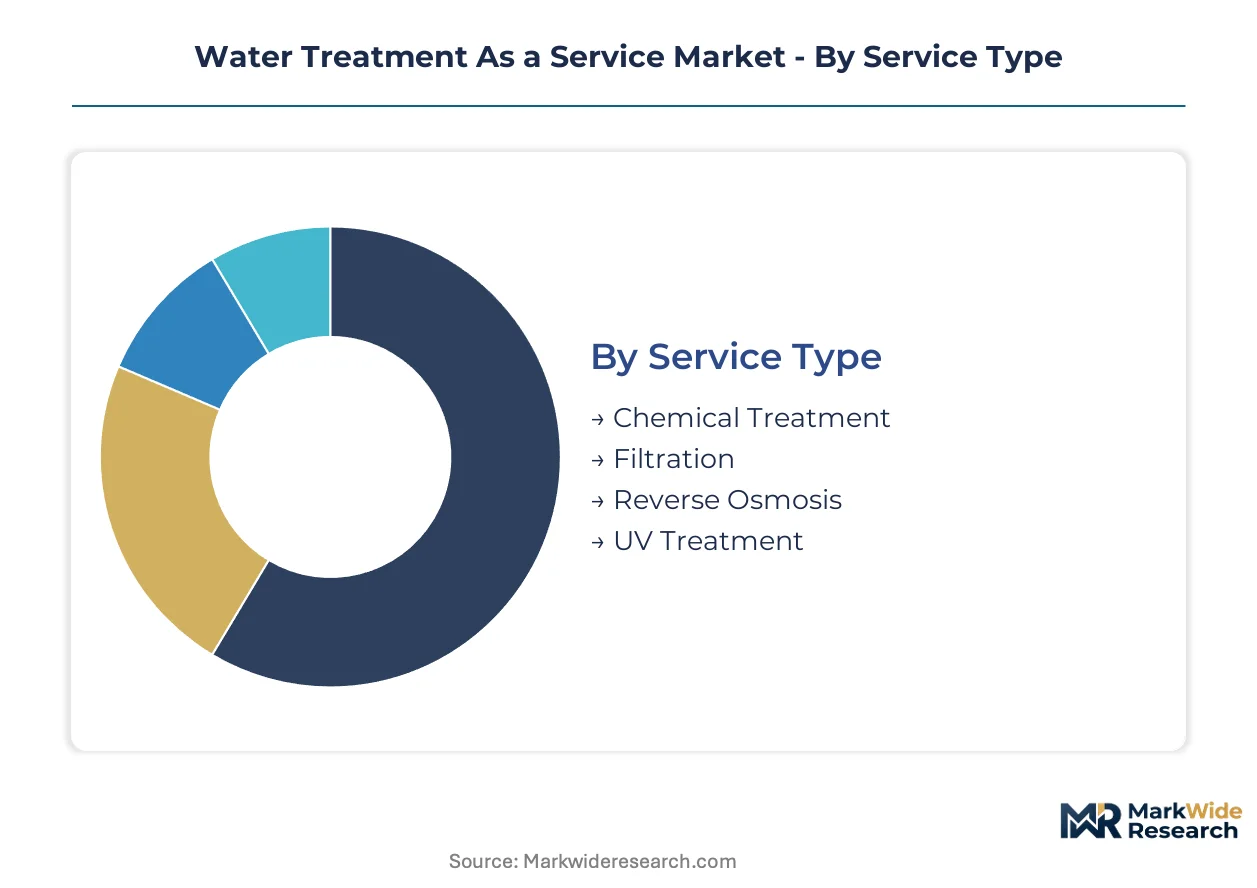
Service delivery models in water treatment fragment sharply across technical specifications and client risk appetites. Contract structures, regulatory exposure, and energy intensity vary dramatically by segment, forcing vendors to maintain parallel capability stacks.
Service Type:
Mature chemical dosing contracts dominate municipal accounts, while membrane-based services command premium positioning in industrial corridors.
- Reverse Osmosis:Pressure-driven membrane separation removes dissolved salts and organics, achieving total dissolved solids below 10 ppm. Semiconductor fabs in Taiwan and South Korea specify these services for sub-7nm node production, where ultrapure water quality gates yield thresholds.
- Chemical Treatment:Coagulation, flocculation, and pH adjustment protocols delivered through bulk chemical management contracts. US municipal utilities favor this model for capital avoidance, particularly in Rust Belt cities with aging lime softening infrastructure.
- Filtration:Granular media and cartridge-based particulate removal for pre-treatment and polishing stages. Food processors in the Netherlands deploy these services to meet EU Green Deal discharge requirements without on-site chemical storage.
- UV Treatment:Mercury or LED-based disinfection for chlorine-resistant pathogens and residual-free effluent. Pharmaceutical sterile manufacturing lines in Germany specify UV services to satisfy EMA guidance on elemental impurity control.
Reverse osmosis handles the majority of throughput; UV treatment is the fastest mover on share.
Application:
Volume concentration tilts toward municipal accounts, though margin accretion follows industrial process complexity.
- Industrial Process Water:Boiler feed, cooling tower makeup, and rinse water purification for manufacturing continuity. Texas petrochemical complexes and Louisiana refineries outsource these services to guarantee throughput independent of inlet quality swings.
- Wastewater Management:Effluent treatment for regulatory compliance and water reuse. China's Yangtze River basin state-owned enterprises contract these services to meet MEE ammonia nitrogen and COD limits without footprint expansion.
- Municipal Water Supply:Potable water treatment for distribution network injection. Indian utilities in Gujarat and Tamil Nadu special economic zones are greenfield adopters, lacking legacy infrastructure to displace.
- Agriculture:Irrigation water desalination and nutrient recovery for controlled-environment growing. Israeli greenhouse operators and Spanish Almería producers drive contract innovation around brine management.
Industrial process water commands pricing power; wastewater management is expanding most steeply on regulatory compulsion.
End User:
Procurement sophistication diverges between rate-regulated utilities and risk-managed industrial operators.
- Manufacturing Plants:Automotive, electronics, and pharmaceutical producers with zero-discharge or closed-loop mandates. German automotive suppliers consolidate multi-site contracts to streamline REACH Article 33 compliance documentation.
- Water Utilities:Municipal and regional authorities prioritizing operational expenditure models over capital builds. US EPA effluent limitation guidelines accelerate outsourcing as in-house capabilities fall behind tightening discharge standards.
- Hospitals:Healthcare facilities requiring Legionella control and sterile water for dialysis and surgical applications. Joint Commission accreditation standards in the US drive specification of third-party monitoring and validation.
- Schools:Educational institutions with intermittent occupancy patterns and limited maintenance staffing. California and Texas districts favor subscription models for lead and copper rule compliance without dedicated plant operators.
Manufacturing plants generate the densest contract values; water utilities represent the broadest addressable base.
Technology:
Installed capacity clusters on membrane platforms, though biological and oxidative alternatives gain ground on energy and chemical footprint metrics.
- Membrane Technology:Microfiltration, ultrafiltration, nanofiltration, and reverse osmosis in modular or immersed configurations. Polyamide thin-film composite elements from Japanese and US suppliers anchor system performance, creating supply concentration risk.
- Ozone Treatment:Corona discharge or UV-generated ozone for oxidation and disinfection without chemical residuals. Pharmaceutical and food processing applications in Denmark and the Netherlands favor this technology for sterile manufacturing compliance.
- Activated Sludge:Conventional and advanced biological nutrient removal for carbonaceous and nitrogenous load reduction. Municipal plants in legacy US infrastructure markets retain these systems despite aeration energy intensity.
- Ion Exchange:Selective resin-based removal of dissolved ions for ultrapure water and metals recovery. Semiconductor fabs specify these services for polishing stages after reverse osmosis, particularly for boron and silica control at advanced nodes.
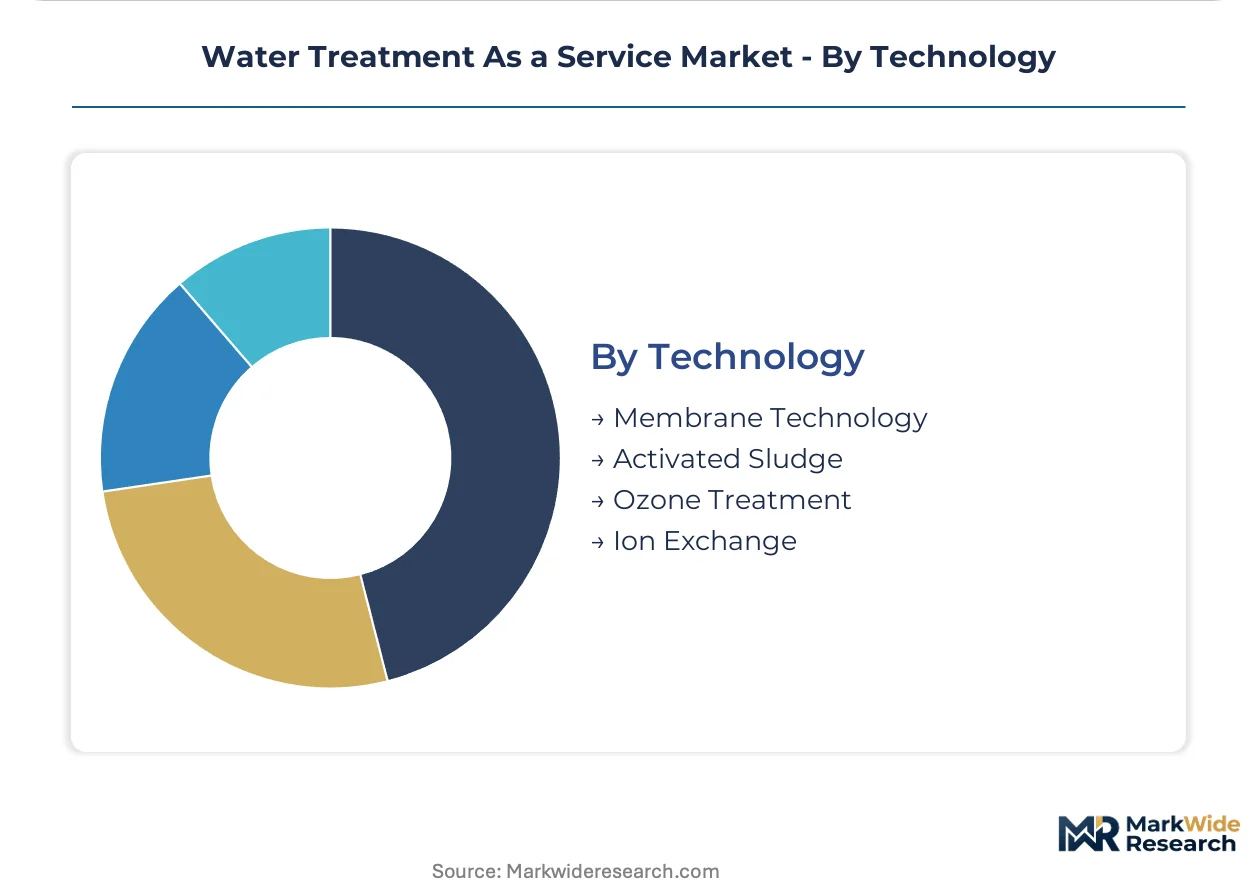
Membrane technology carries the dominant installed base; ozone treatment is climbing the fastest on residual-free regulatory preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US municipalities prioritize capital avoidance through operational expenditure models, while Chinese industrial operators face discharge mandates without footprint expansion, and European pharmaceutical manufacturers demand residual-free disinfection protocols.
United States
Rust Belt cities with aging lime softening infrastructure and Texas-Louisiana petrochemical complexes drive outsourced treatment demand. The EPA's tightening effluent limitation guidelines push manufacturing facilities toward third-party compliance partnerships. Houston and Lake Charles refineries unbundle capex and opex into distinct contract vehicles for produced water throughput guarantees.
China
State-owned enterprises in the Yangtze River basin industrial corridor contract wastewater services to meet MEE ammonia nitrogen and COD limits. The country's dual carbon goals tighten industrial discharge permits without expanding physical plant footprints. Suzhou and Wuxi semiconductor fabrication clusters specify ultrapure water services for sub-7nm node production.
Germany
Automotive suppliers consolidate multi-site treatment contracts to streamline REACH Article 33 extended producer responsibility documentation. The EU Green Deal's chemical footprinting requirements force centralized chemical management across manufacturing portfolios. Stuttgart and Wolfsburg supplier parks anchor service contract innovation around compliance documentation efficiency.
India
Gujarat and Tamil Nadu special economic zones lack integrated treatment infrastructure, creating greenfield service contract potential. The country's PLI scheme for advanced manufacturing accelerates industrial water demand without legacy infrastructure displacement. Ahmedabad and Chennai industrial corridors represent the fastest-expanding addressable base for performance-based contracting.
Netherlands
Food and beverage processors pilot membrane bioreactor-anaerobic digestion hybrids at 40% reduced aeration demand. EU Green Deal discharge requirements favor service providers with centralized chemical management. Eindhoven and Rotterdam industrial zones enable shorter payback periods that accelerate municipal adoption of integrated biological systems.
Water Treatment As a Service Market Key Industry Players
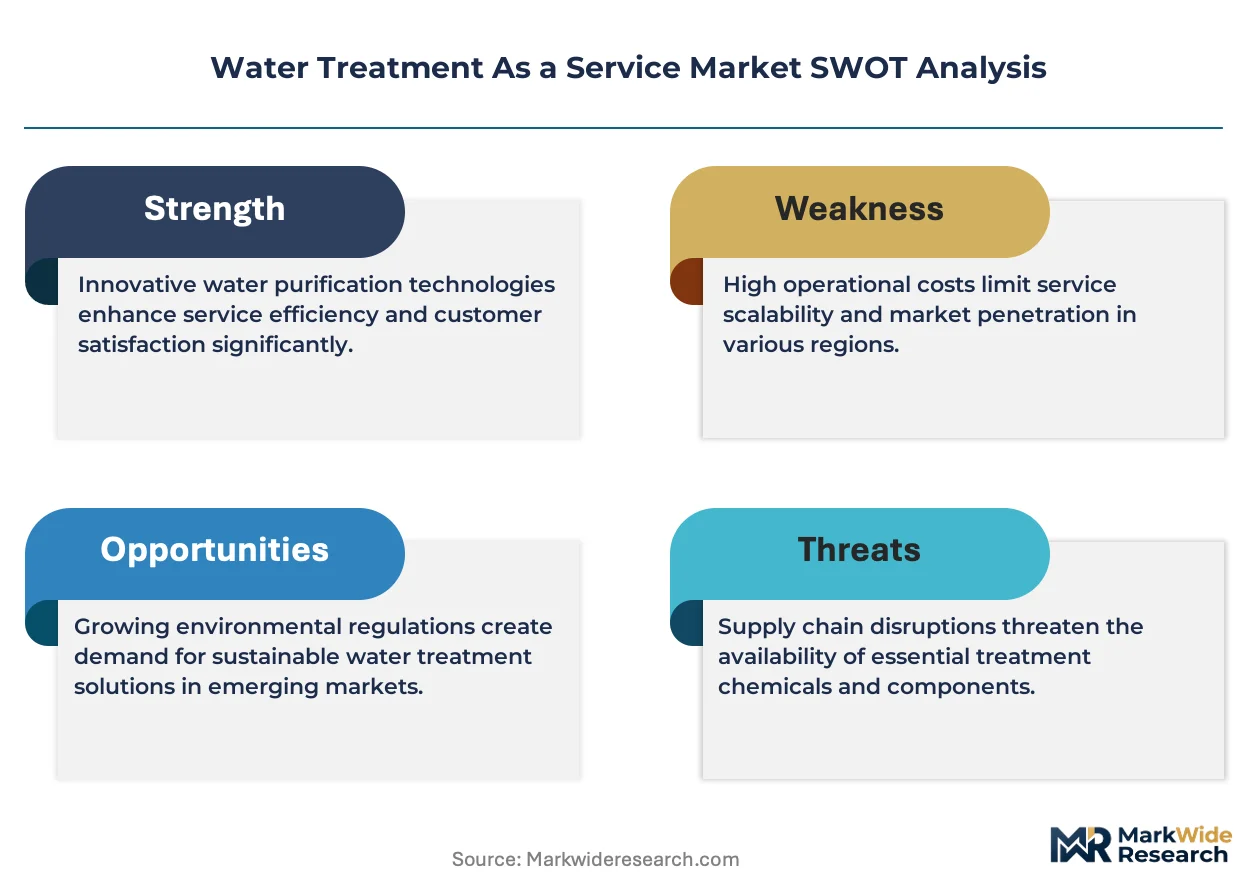
Capability concentration sits with technology-integrated operators; scale advantage sits with diversified environmental service conglomerates. The market structures around three tiers: full-service environmental multinationals, specialized membrane technology providers, and regional water service contractors. Strategic moves center on bundling chemical treatment with remote monitoring platforms and securing long-term municipal outsourcing contracts.
Within the integrated operations tier, Veolia and SUEZ exemplify the convergence of chemical management with regulatory compliance services. Xylem occupies a position representing specialized membrane technology leadership. These three anchors demonstrate how vendor-customer relationships restructure around performance guarantees rather than asset ownership, with each exemplifying distinct archetypes of technology integration, regulatory expertise, and operational scale.
| Leading Market Players |
|---|
| Seven Seas Water Group |
| Aquatech International LLC |
| Waterleau |
| Quench USA, Inc. |
| Chart Industries |
| OriginClear |
| Veolia |
| SUEZ |
| Xylem |
| Others |
Cost & Logistics Intelligence
Pacific Rim container freight corridors carry polyamide thin-film composite membranes from Japanese and US manufacturing hubs, with shipping cost volatility feeding directly into reverse osmosis service pricing tiers and compressing margins for operators locked into long-term performance contracts.
Pricing Analysis
Long-term offtake agreements anchor municipal outsourcing contracts at fixed per-gallon rates, while spot arrangements dominate emergency industrial compliance engagements. Price differentiation rests on energy intensity guarantees and membrane replacement cadence, with semiconductor fabs paying premiums for sub-7nm ultrapure water specifications. Pricing pressure stems from electricity cost volatility in deregulated Texas and Louisiana markets, where reverse osmosis operations consume 3-15 kWh per thousand gallons. Municipal utilities exhibit highest price sensitivity due to rate-regulated revenue caps, whereas pharmaceutical manufacturers prioritize residual-free compliance over unit economics.
Supply Chain Analysis
Extended payment terms from membrane OEMs to system integrators stretch working capital cycles, with supply-chain finance facilities increasingly bridging installation-to-commissioning gaps. Polyamide thin-film composite production clusters in Japan and the United States, while UV lamp manufacturing concentrates in Germany and China. Raw material dependencies span specialized resins, precision pressure vessels, and ceramic membrane substrates. Single-source vulnerability around Japanese membrane suppliers exposes operators to trade flow disruptions. Distribution runs through regional service hubs that co-locate chemical inventory with technician deployment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water Treatment As a Service sits in early-cycle expansion as municipal balance sheet strain accelerates performance-based contracting adoption ahead of traditional infrastructure replacement timelines.
For Market Incumbents: Pre-empt membrane supply concentration risk by securing dual-source agreements with Japanese and US composite manufacturers before trade policy shifts tighten availability. Anchor long-term municipal contracts with bundled remote monitoring platforms that raise switching costs for rate-regulated utilities facing EPA effluent limitation compliance deadlines.
For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu special economic zones, where greenfield industrial corridors lack legacy infrastructure and PLI scheme incentives accelerate manufacturing water demand without incumbent displacement costs. Lead with membrane bioreactor-anaerobic digestion hybrids that slash aeration energy intensity, differentiating against established chemical treatment providers.
For Investors and Strategic Acquirers: Regional water service contractors with certified membrane technician training programs and established municipal relationships represent the most defensible acquisition profile. Monitor MEE discharge mandate enforcement intensity in China's Yangtze River basin as the inflection signal for outsourced wastewater service penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive polyamide thin-film composite supply secures margin control against Japanese and US supplier concentration. |
| Digital Twin Platform Deployment | Real-time sensor networks enable guaranteed uptime clauses that differentiate premium service tiers for semiconductor fabs. |
| Multi-Site Chemical Management Consolidation | Centralized REACH Article 33 compliance documentation streamlines procurement for German automotive supplier parks. |
| Certified Technician Training Program Expansion | Fouling diagnosis capability scarcity creates defensive moats around long-term municipal outsourcing contracts. |
| Membrane Bioreactor Hybrid System Rollout | 40% aeration energy reduction accelerates payback periods for food processors facing EU Green Deal discharge requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility directors, industrial plant engineers, membrane system OEM technical leads, and chemical treatment service account managers. Secondary validation drew from EPA effluent limitation guideline filings, MEE discharge permit databases, EU Green Deal implementation progress reports, and SEC 10-K disclosures from publicly traded water service conglomerates. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates across the analysis window.
Calibration against historical municipal outsourcing adoption curves and industrial compliance spending patterns shaped the projection framework. Segmentation dimensions modeled include service type, application vertical, end-user procurement sophistication, and technology platform energy intensity. CAGRs were derived from regression analysis of contract renewal rates and new installation pipelines. Forecast inputs incorporated electricity price trajectory assumptions and membrane replacement cycle benchmarks.
Sensitivities concentrate around regulatory enforcement intensity in China's Yangtze River basin and EPA guideline implementation timelines in US manufacturing corridors. Forecasts reflect documented assumptions regarding municipal capital budget constraints and semiconductor fabrication capacity expansion plans. Macroeconomic contraction, tariff escalation on Japanese membrane imports, or breakthroughs in energy-efficient biological treatment alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Smart Water Softeners Market