
 Water Treatment Ozone Generator Market | 2026-2036
Water Treatment Ozone Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Water Treatment Ozone Generator Market Insights
Project finance and municipal leasing structures are fragmenting the competitive landscape for ozone generator procurement, enabling smaller water utilities to access advanced oxidation without upfront capital burdens. Xylem Inc. leverages its integrated digital platform to bundle ozone systems with predictive maintenance contracts. SUEZ anchors European utility relationships through long-term service agreements. Mitsubishi Electric competes on high-frequency power supply efficiency in large-scale corona discharge installations.
A water treatment ozone generator produces ozone gas through corona discharge, ultraviolet radiation, or electrolytic methods, typically achieving concentrations of 6-12% by weight for industrial applications, then dissolving this powerful oxidant into water streams to destroy pathogens, degrade organic micropollutants, and precipitate dissolved metals. Corona discharge technology dominates installed capacity due to its energy efficiency at scale, while electrolytic methods are gaining traction in decentralized and aquaculture settings where compact footprint matters. Municipal end users represent the largest value pool, though industrial wastewater pretreatment for pharmaceutical discharge compliance shows the fastest expansion trajectory.
The EPA's Stage 2 DBPR and the EU Drinking Water Directive's revised contaminant thresholds compel utilities to validate ozone CT values and bromate formation control, tightening equipment certification requirements. ISO 9001 and NSF/ANSI 61 product safety standards shape manufacturer market access, particularly for components contacting potable water. Stakeholders must monitor evolving PFAS destruction validation protocols and their implications for ozone-hydrogen peroxide advanced oxidation process design standards.
Market Dynamics
The EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule is forcing municipal utilities to abandon chlorine-based systems for ozone oxidation, compressing capital replacement cycles and reshaping vendor procurement patterns across North American water infrastructure.
Growth Catalysts
- Stage 2 DBPR compliance:The EPA's trihalomethane limits compel chlorine displacement in municipal treatment plants, accelerating ozone generator retrofit mandates.
- PFAS destruction protocols:Emerging validation standards for per- and polyfluoroalkyl substance remediation position ozone-hydrogen peroxide advanced oxidation as the preferred destruction pathway.
- Aging infrastructure replacement:United States water utilities face pipe and treatment plant obsolescence, funneling federal infrastructure funds toward modern oxidation systems.
Market Restraints
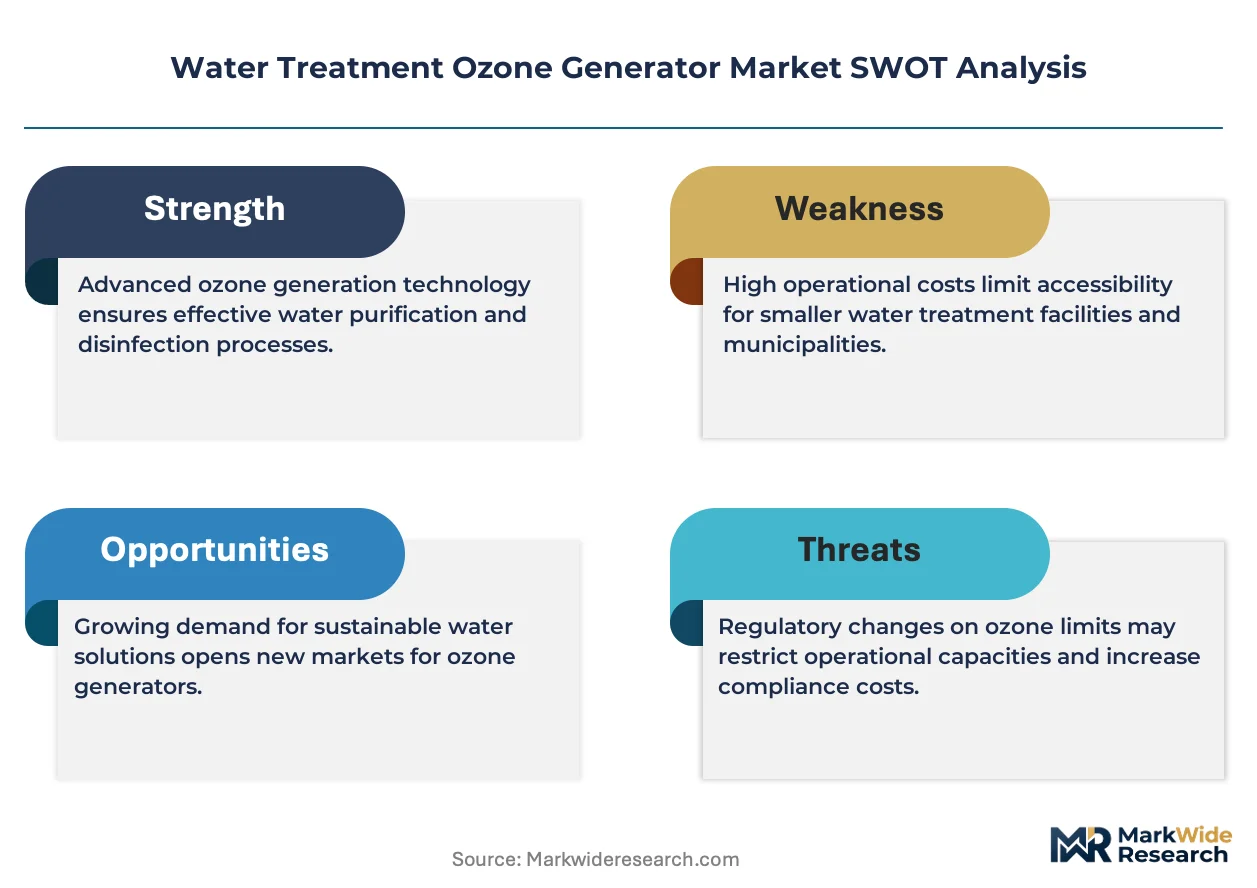
- Energy cost volatility:Corona discharge ozone generation consumes substantial electricity, exposing operators to utility rate fluctuations that compress operating margins.
- Specialized component supply:High-frequency power supplies and dielectric materials concentrate among German and Japanese component suppliers, creating import dependency risks.
- Bromate formation control:The EPA mandates rigorous ozone CT value validation to limit carcinogenic byproduct generation, adding engineering complexity and compliance cost.
Strategic Opportunities
- Decentralized aquaculture systems:Electrolytic ozone generators address footprint constraints in land-based fish farming operations, opening compact-system demand outside municipal utilities.
- Pharmaceutical wastewater pretreatment:Discharge compliance for active pharmaceutical ingredients creates industrial end-use expansion beyond traditional potable water applications.
- Project finance structures:Municipal leasing and performance contracting enable smaller utilities to access advanced oxidation without upfront capital expenditure.
Industry Challenges
- Ozone system integration:Legacy SCADA and control architectures in aging treatment plants require costly retrofit engineering to accommodate modern generator automation.
- Specialized technician scarcity:Corona discharge maintenance and dielectric replacement demand skilled electromechanical expertise that utilities struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Treatment Ozone Generator Market |
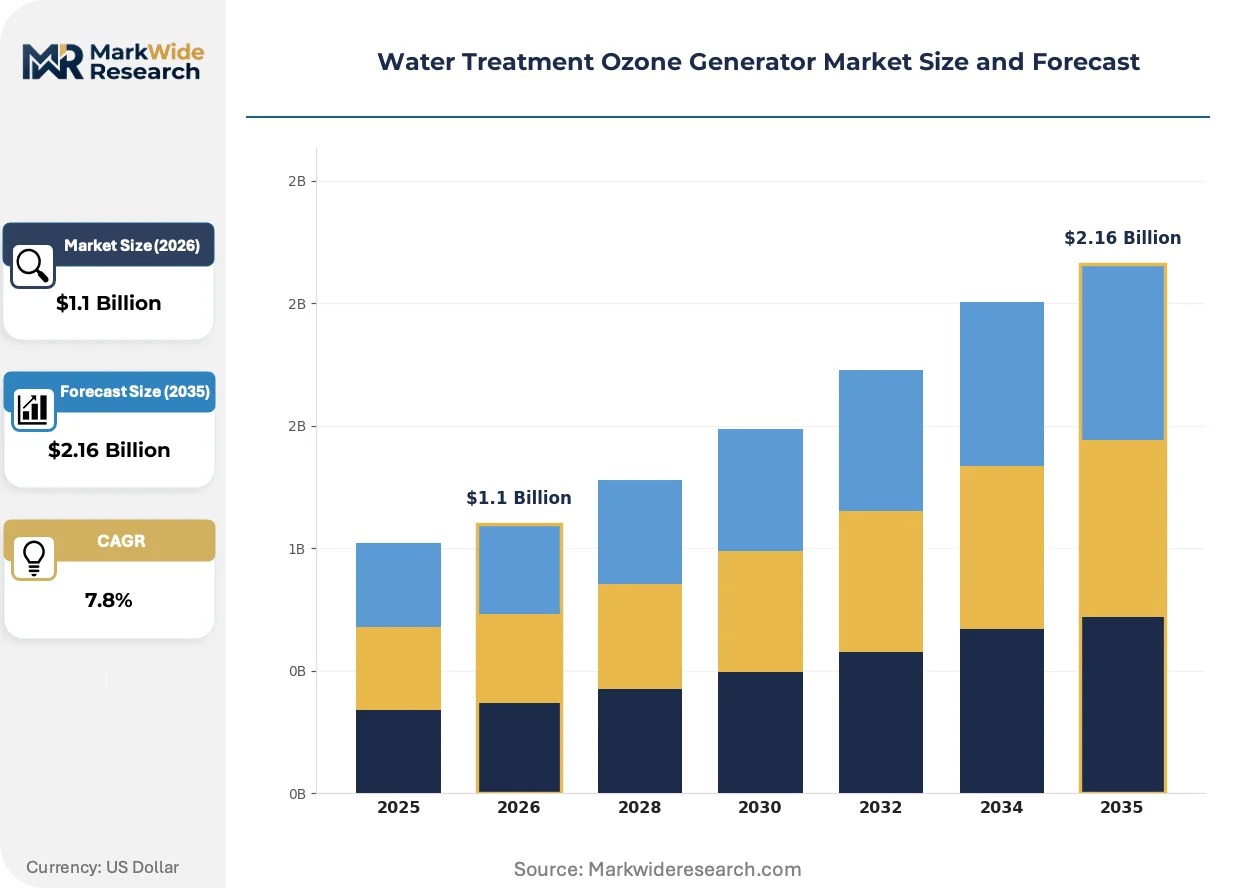
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $2.16 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Corona Discharge, Ultraviolet, Electrolytic, Chemical End User: Municipal, Industrial, Residential, Aquaculture Application: Drinking Water Treatment, Wastewater Treatment, Swimming Pools, Aquariums Installation: On-Site, Off-Site, Mobile Units, Fixed Systems |
| Companies Covered | Xylem Inc., SUEZ, Mitsubishi Electric, EBARA Technologies, Veolia, Evoqua Water Technologies, Faraday Ozone, Toshiba, Lenntech Water Treatment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Treatment Ozone Generator Market Trends and Innovations
Electrolytic ozone generation is collapsing the footprint requirements that historically constrained deployment, while regulatory tightening on disinfection byproducts accelerates technology substitution across treatment plant vintages.
Electrolytic ozone generation uses proton-exchange membrane cells to produce ozone directly from water rather than dry air or oxygen feed gas. Aquaculture operators and decentralized treatment facilities are adopting these systems for sub-500 gram-per-hour applications where space constraints dominate. The technology is collapsing minimum viable plant size thresholds, enabling ozone treatment in locations previously restricted to chemical dosing.
The EU Drinking Water Directive's revised contaminant thresholds are tightening bromate limits and micropollutant monitoring requirements. European utilities must validate advanced oxidation process performance through enhanced analytical protocols. German and French municipal operators are prioritizing ozone-UV hybrid systems to meet these standards while managing energy consumption.
Performance-based service contracts are displacing traditional equipment procurement in municipal segments. Water utilities in California and Texas now contract for guaranteed disinfection outcomes rather than capital asset ownership. This model transfers operational risk to equipment vendors and compresses supplier margins while extending customer lock-in duration.
Water Treatment Ozone Generator Market Segmentation
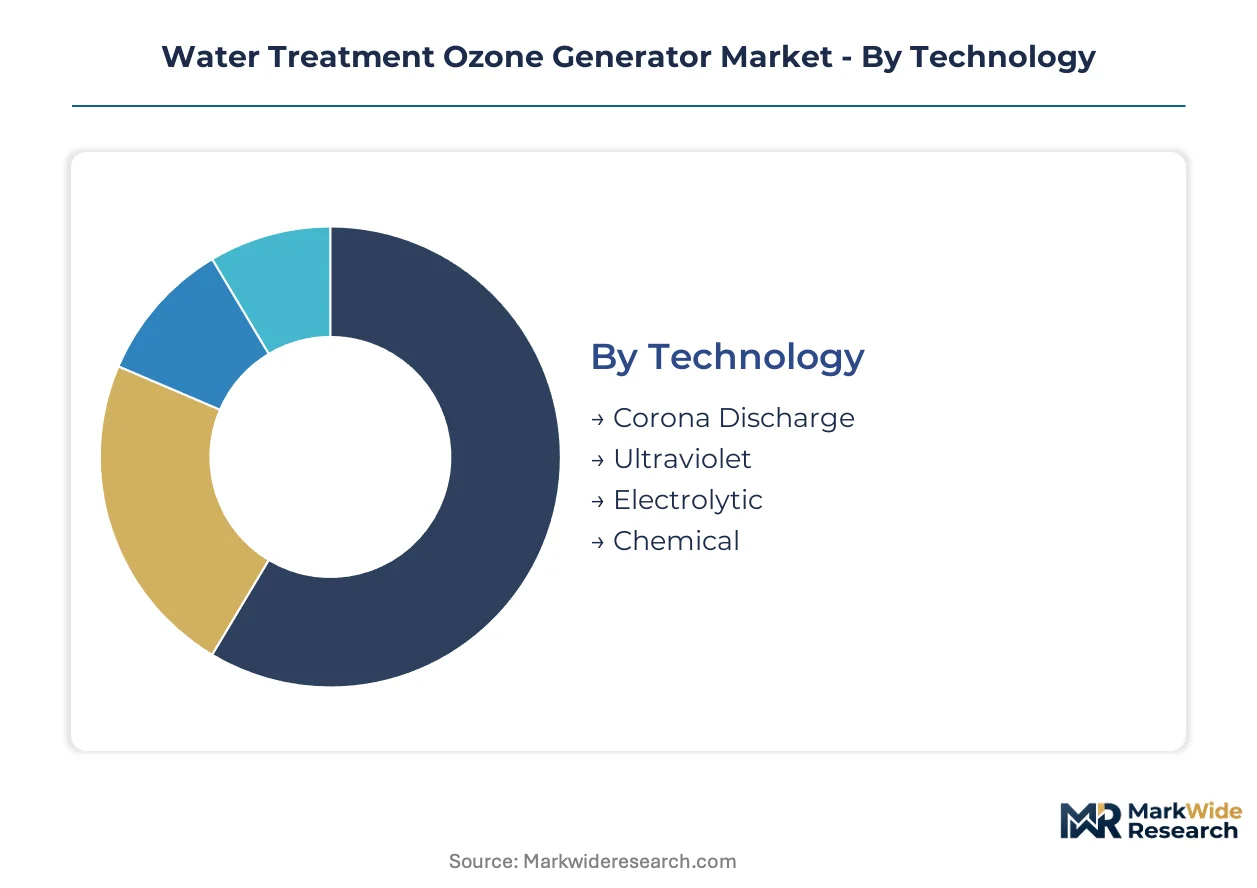
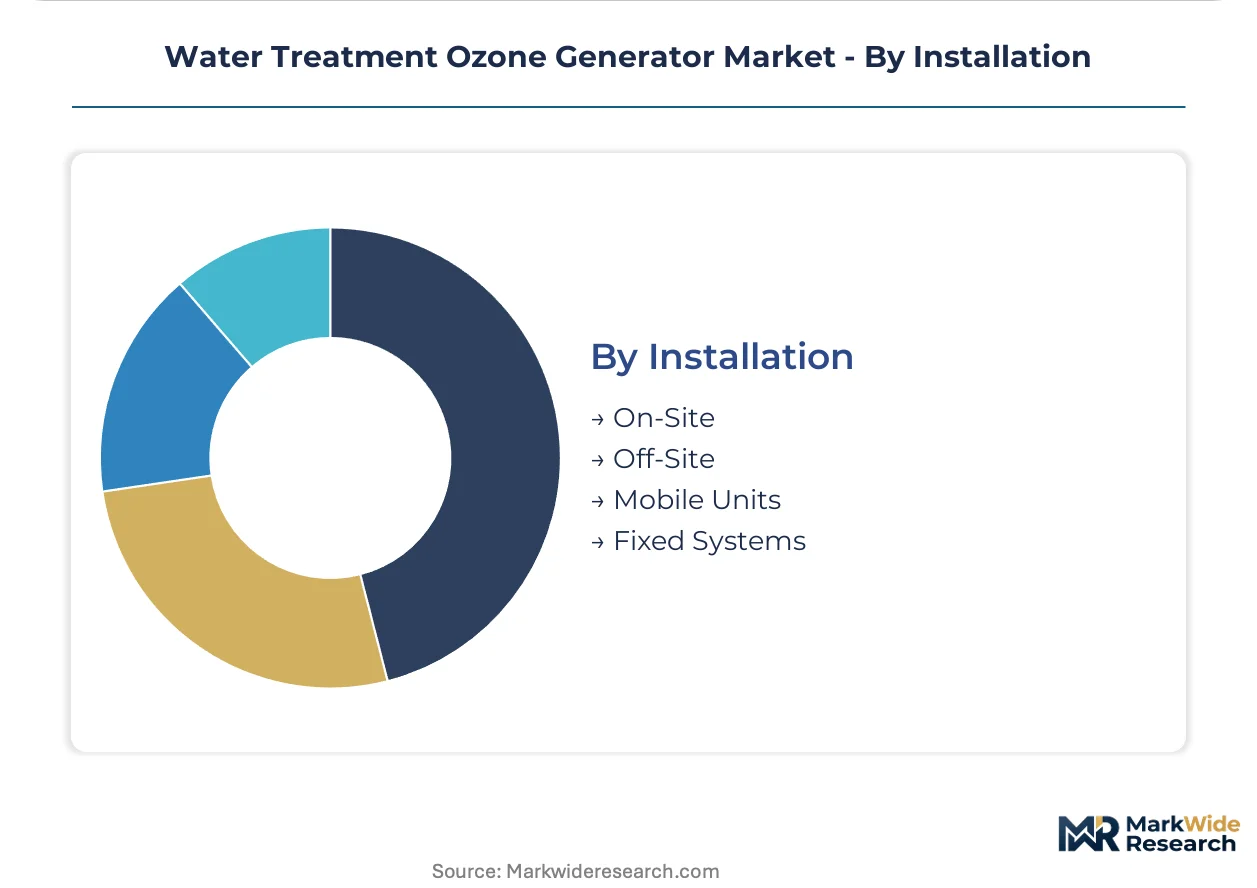
Segmentation in the water treatment ozone generator market reveals divergent equipment lifecycles and replacement velocities. Municipal utilities operate on 15-20 year capital cycles while industrial end-users refresh systems every 7-10 years, creating asynchronous demand pulses across technology categories.
Technology:
Corona discharge systems turn over slowest due to capital intensity and infrastructure lock-in, while electrolytic units refresh fastest as membrane technology advances accelerate.
- Corona Discharge:High-voltage dielectric barrier systems generate ozone concentrations of 6-12% by weight from dry air or oxygen feed gas. Demand concentrates in United States municipal utilities facing EPA Stage 2 DBPR compliance deadlines, where energy efficiency at scale outweighs higher upfront capital.
- Electrolytic:Proton-exchange membrane cells produce ozone directly from water without compressed gas infrastructure. Aquaculture operators in Norway and Japan are adopting these systems for land-based fish farming where footprint constraints dominate site selection.
- Ultraviolet:Low-concentration ozone generation suits small-scale residential and recreational water applications.
- Chemical:Peroxide-based ozonation methods serve niche laboratory and pharmaceutical validation environments.
Corona discharge anchors the volume base while electrolytic gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive municipal procurement from operational-expense-driven industrial contracting models.
- Municipal:City and county water utilities deploy large-scale systems for cryptosporidium inactivation and taste-and-odor control. United States infrastructure replacement programs funnel federal funds toward ozone retrofits as chlorine displacement accelerates under tightening trihalomethane limits.
- Industrial:Pharmaceutical manufacturers and chemical processors use ozone for wastewater pretreatment and active ingredient destruction. German and Swiss facilities lead adoption as EU micropollutant monitoring requirements tighten discharge standards.
- Residential:Point-of-entry systems serve high-end home water treatment in contamination-prone groundwater regions.
- Aquaculture:Land-based fish farming operations deploy compact electrolytic units for pathogen control in recirculating systems.
Municipal procurement dominates absolute spending while industrial applications climb the fastest as discharge compliance tightens across manufacturing jurisdictions.
Application:
Volume concentration tracks potable water infrastructure scale, with wastewater and recreational segments operating at fractional throughput.
- Drinking Water Treatment:Municipal potable water plants use ozone for primary disinfection and organic precursor oxidation. United States utilities prioritize this application as EPA Stage 2 DBPR mandates compress replacement timelines for aging chlorine-based infrastructure.
- Wastewater Treatment:Industrial and municipal effluent polishing employs ozone for pharmaceutical micropollutant degradation and color removal. Swiss and German facilities are expanding capacity as EU Drinking Water Directive thresholds extend to indirect potable reuse pathways.
- Swimming Pools:Commercial and residential aquatic facilities substitute ozone for chlorine to reduce chloramine formation.
- Aquariums:Public and private display facilities use low-dose ozonation for water clarity and pathogen suppression.
Drinking water treatment commands the installed base while wastewater applications expand most quickly as micropollutant regulations proliferate.
Installation:
Customer type and mobility requirements split procurement between permanent infrastructure and contingent deployment models.
- On-Site:Permanent generator installations at treatment plants integrate with existing headworks and contactor infrastructure. United States municipal utilities favor this model for long-term capital asset accounting and operational control.
- Off-Site:Centralized ozone generation with liquid ozone or concentrated gas distribution serves clustered industrial parks. Belgian and Dutch chemical corridors use this configuration to achieve economies of scale across multiple discharge points.
- Mobile Units:Trailer-mounted systems address temporary treatment needs during plant maintenance or emergency response.
- Fixed Systems:Skid-mounted permanent installations serve smaller utilities and industrial facilities with predictable throughput.
On-site installation holds the majority position while off-site configurations gain traction in industrial cluster geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented German and Japanese component suppliers dominate high-frequency power supply and dielectric material shipments, while import-dependent utilities in water-stressed regions accelerate localized assembly partnerships to mitigate currency exposure and lead-time volatility.
United States
Municipal utilities in California, Texas, and the Great Lakes states deploy corona discharge systems for cryptosporidium inactivation under EPA Stage 2 DBPR mandates. The Infrastructure Investment and Jobs Act channels federal capital toward aging treatment plant replacement in the Ohio River Valley and Southwest. Phoenix and San Antonio anchor the largest retrofit concentrations as chlorine displacement accelerates in surface water-dependent systems.
Germany
Rhine-Ruhr and Bavarian chemical processors expand ozone-hydrogen peroxide capacity for pharmaceutical micropollutant destruction ahead of EU Drinking Water Directive enforcement. The country's national water regulator tightens bromate monitoring protocols for municipal operators. Stuttgart and Frankfurt municipal utilities pioneer ozone-UV hybrid installations to balance energy efficiency with enhanced oxidation performance.
China
Yangtze River Delta municipalities retrofit secondary disinfection infrastructure as surface water quality standards tighten under MEE directives. Domestic membrane and power supply manufacturers erode import dependency for mid-scale installations. Shanghai and Suzhou industrial parks deploy centralized off-site ozone generation for clustered electronics and pharmaceutical discharge compliance.
Japan
Land-constrained aquaculture operators in Kyushu and Shikoku adopt electrolytic systems for recirculating fish farm pathogen control. METI efficiency standards accelerate membrane cell technology iteration for sub-500 gram-per-hour applications. Nagoya and Osaka equipment fabricators supply compact generators to Southeast Asian shrimp farming operations.
Netherlands
Randstad utilities validate advanced oxidation process performance for indirect potable reuse pathways under EU micropollutant thresholds. Belgian-Dutch chemical corridor operators share centralized ozone generation infrastructure across multiple discharge points. Rotterdam and Antwerp industrial clusters negotiate long-term service contracts rather than capital procurement for oxidation capacity.
Water Treatment Ozone Generator Market Competitive Landscape
On the supply side, the industry is consolidating around integrated water technology platforms and fragmenting at the component tier. Large-scale system vendors bundle predictive maintenance and digital monitoring to extend customer lock-in. Three strategic archetypes dominate: full-service water technology conglomerates, specialized electrochemical equipment fabricators, and regional power electronics suppliers. Competitive moves center on municipal leasing structure innovation and electrolytic membrane technology licensing.
Within the integrated platform tier, Xylem Inc. and SUEZ exemplify service-contract anchoring strategies, while Mitsubishi Electric occupies a position bridging power electronics specialization with large-scale corona discharge system supply. These three represent divergent geographic origins and corporate structures—US-based, French multinational, and Japanese industrial conglomerate respectively—yet each sit within distinct competitive vectors: digital bundling, long-term utility relationships, and high-frequency efficiency optimization.
| Leading Market Players |
|---|
| Xylem Inc. |
| SUEZ |
| Mitsubishi Electric |
| EBARA Technologies |
| Veolia |
| Evoqua Water Technologies |
| Faraday Ozone |
| Toshiba |
| Lenntech Water Treatment |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese membrane cell manufacturing is compressing electrolytic generator pricing while tightening margins for corona discharge specialists, forcing tier-2 suppliers toward extended payment terms and inventory financing to retain municipal procurement relationships.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures with three-tier differentiation across NSF/ANSI 61 certified premium systems, standard municipal configurations, and economy-grade aquaculture units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are exporting excess membrane capacity at distressed pricing. Municipal utilities exhibit lowest price sensitivity due to federal infrastructure funding availability, while aquaculture operators face acute margin pressure.
Supply Chain Analysis
Extended payment terms from German and Japanese dielectric suppliers are straining working capital for system integrators assembling corona discharge equipment. High-frequency power supply manufacturing concentrates in Germany, Japan, and South Korea, while proton-exchange membrane production draws from Chinese and Japanese chemical processors. Supply chain risk centers on single-source vulnerability for specialized ceramic dielectrics. Distribution runs through direct municipal procurement channels in North America and long-term service contracting in European utility markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water treatment ozone generator market is approaching a platform-economics inflection as predictive maintenance APIs and SCADA integration standards create winner-take-most dynamics among bundled service providers.
For Market Incumbents: Build switching-cost moats through predictive maintenance platform lock-in. Deepen backward integration into dielectric ceramic production to offset German and Japanese supplier pricing power. Invest in ISO 9001 certification at component tier to disqualify emerging Asian competitors from municipal procurement pools. Threat: electrolytic technology substitution in sub-500 gram-per-hour applications. For New Entrants and Emerging Players: Establish a beachhead in decentralized aquaculture systems where footprint constraints override brand loyalty. Target pharmaceutical wastewater pretreatment in German and Swiss industrial corridors where discharge compliance urgency outpaces incumbent response times. Go-to-market angle: membrane cell technology licensing to regional fabricators lacking electrochemical expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrolytic sub-500 gram-per-hour manufacturing as Chinese membrane capacity expands. Long-term viability favors vertically integrated platforms with captive service revenue streams over pure-play equipment vendors. Acquisition target archetype: regional power electronics specialists with METI or CE certification pathways. Signal to watch: municipal leasing penetration rates above threshold levels indicating preference shift from ownership to outcome-based contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Accelerates electrolytic generator localization in Southeast Asian aquaculture markets. |
| Performance Contracting Expansion | Transfers operational risk to vendors while extending California and Texas utility lock-in duration. |
| Dielectric Ceramic Backward Integration | Reduces dependency on German and Japanese component suppliers for corona discharge systems. |
| Predictive Maintenance Platform Launch | Creates recurring revenue streams and raises switching costs for Xylem and SUEZ municipal accounts. |
| EU Drinking Water Directive Pre-Certification | Secures early-mover advantage in bromate monitoring protocol compliance for Rhine-Ruhr utilities. |
Research Methodology
The analysis maps corona discharge, electrolytic, ultraviolet, and chemical generation sub-sectors, each validated through municipal utility procurement officers, industrial wastewater plant managers, aquaculture operations directors, and aftermarket service technicians. Primary interview findings triangulate against EPA enforcement databases, EU Drinking Water Directive implementation reports, MEE surface water quality directives, and METI efficiency standard filings. Secondary sources include customs records for high-frequency power supply trade flows, municipal bond prospectuses for infrastructure spending patterns, and patent filings for membrane cell technology. Bottom-up equipment shipment data reconciles with top-down utility capital expenditure surveys.
Forecast assumptions hold fixed EPA Stage 2 DBPR compliance deadlines, EU micropollutant threshold enforcement timelines, and METI efficiency standard phase-in schedules across the projection horizon. Modeled segmentation spans technology type, end-user category, application, and installation configuration. CAGRs derive from equipment replacement velocity differentials between municipal 15-20 year cycles and industrial 7-10 year refresh patterns. Industry-specific inputs include electricity rate trajectories affecting corona discharge operating economics and membrane cost curves for electrolytic systems.
Stress conditions across bromate formation control stringency, power supply import tariff regimes, and PFAS destruction protocol validation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Global Desalination System Market