
 Storm Water Cleaning Services Market | 2026-2036
Storm Water Cleaning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Storm Water Cleaning Services Market Analytics
Preventive maintenance contracts is narrowing the margin gap between reactive emergency cleaning and scheduled infrastructure upkeep across the storm water services value chain. Clean Harbors, Inc. leverages its hazardous waste disposal network to bundle storm water remediation with downstream waste handling. Veolia Environmental Services anchors its competitive position through long-term municipal concession agreements in dense urban watersheds. Hydro International differentiates via proprietary vortex separation technology that reduces sediment removal frequency for industrial clients.
Storm water cleaning services encompass the mechanical extraction, treatment, and disposal of pollutants from urban runoff collection systems, typically involving vacuum extraction at 15-20 inches of mercury, sediment dewatering, and hydrocarbon separation before discharge or landfill disposal. These services prevent flooding, protect receiving water quality, and ensure regulatory compliance for municipal separate storm sewer systems and industrial storm water permits. Vacuum truck deployment dominates revenue generation due to capital intensity and crew specialization requirements, while bioremediation represents the fastest-expanding technology segment as municipalities phase out chemical treatment near sensitive ecological receptors. Oil-water separation commands premium pricing in industrial facility contracts where sheen detection triggers immediate regulatory reporting obligations.
The EPA enforces National Pollutant Discharge Elimination System storm water permits that mandate regular inspection and maintenance of municipal collection infrastructure, directly expanding addressable service demand. State-level Departments of Environmental Quality in Texas, Florida, and Louisiana impose additional coastal discharge standards that exceed federal baselines, creating regional compliance complexity for national service providers. Stakeholders must monitor how evolving Total Maximum Daily Load allocations for nitrogen and phosphorus reshape the technical specifications that municipalities include in procurement documents.
Market Dynamics
The EPA's tightening National Pollutant Discharge Elimination System compliance timelines are compressing maintenance cycles for municipal separate storm sewer systems, forcing municipalities to convert reactive emergency contracts into preventive service agreements with specialized vacuum truck operators.
Growth Catalysts
- Hurricane frequency along the Gulf Coast:Coastal flooding events in Texas, Florida, and Louisiana are accelerating capital allocation toward resilient drainage infrastructure and recurring cleaning contracts.
- EPA NPDES permit enforcement:Municipalities face escalating penalties for discharge violations, expanding the addressable market for inspection and maintenance services.
- Bioremediation technology maturation:Phytoremediation and microbial treatment systems are displacing chemical approaches near wetlands and ecological receptors, opening new service categories.
Market Restraints
- Vacuum truck capital intensity:Specialized hydro-excavation vehicles require substantial upfront investment, limiting new entrant participation and concentrating supply among established fleet operators.
- Diesel fuel cost volatility:Vacuum extraction and transport operations remain dependent on fossil fuel inputs, compressing margins during energy price spikes.
- Landfill capacity constraints:Sediment and hydrocarbon-laden waste streams face disposal bottlenecks in coastal states with limited hazardous waste infrastructure.
Strategic Opportunities
- Industrial facility bundling:Oil-water separation and sheen response services command premium pricing at petrochemical complexes and refineries seeking integrated environmental compliance partners.
- Smart sensor integration:IoT-enabled catchment monitoring is converging with predictive maintenance platforms, enabling condition-based service dispatch before blockages trigger flooding.
- Total Maximum Daily Load alignment:Nitrogen and phosphorus allocation frameworks are reshaping municipal procurement specifications, creating openings for nutrient-targeted treatment technologies.
Industry Challenges
- Certified operator scarcity:Hazardous waste endorsement and confined space entry qualifications limit workforce scalability during storm surge demand spikes.
- Legacy infrastructure compatibility:Aging brick-and-concrete collection systems in northeastern cities require adapted vacuum extraction techniques that increase crew time and equipment wear.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storm Water Cleaning Services Market |
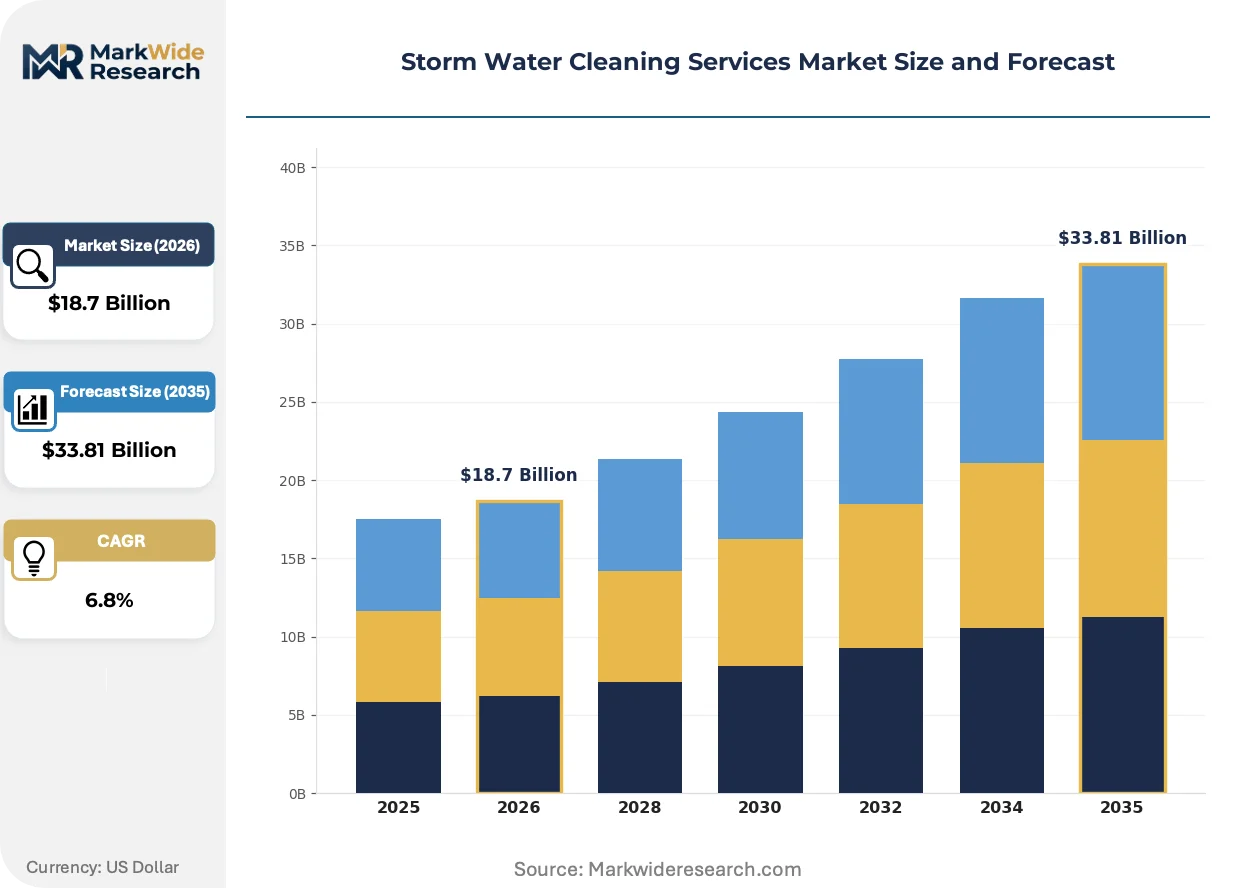
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Vacuum Trucks, Drainage Cleaning, Oil-Water Separation, Water Quality Testing Application: Municipalities, Construction Sites, Industrial Facilities, Residential Areas Technology: Bioremediation, Chemical Treatment, Mechanical Cleaning, Manual Cleaning End User: Government Agencies, Environmental Consultants, Property Owners, Contractors |
| Companies Covered | Clean Harbors, Inc., Veolia Environmental Services, DBi Services, Hydro International, River City Environmental, Inc., Storm Water Maintenance, LLC, Northwest Storm Water Management, LLC, Clean Water Services, Advanced Drainage Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storm Water Cleaning Services Market Evolving Landscape
Vortex separation and bioremediation technologies are displacing conventional chemical treatment and passive sedimentation in storm water cleaning workflows. Equipment manufacturers and service providers are racing to integrate predictive diagnostics with mechanical extraction capabilities.
Vortex separation technology is hybridizing with automated screening and grit removal systems to create continuous-flow treatment trains that reduce manual cleaning frequency. Industrial facility operators in chemical manufacturing and petroleum refining are adopting these integrated systems to minimize sheen-triggered regulatory reporting events. The technology is compressing the traditional service interval from quarterly to annual maintenance cycles in high-sediment applications.
The EPA's National Pollutant Discharge Elimination System permit renewal requirements are mandating documented inspection frequencies and maintenance records for municipal separate storm sewer systems. Municipal procurement departments are embedding these compliance specifications into multi-year concession agreements with performance penalties for missed intervals. Gulf Coast municipalities in Texas and Louisiana are responding by consolidating previously fragmented district-level contracts into watershed-scale service awards.
Outcome-based service contracts are displacing unit-rate pricing for vacuum truck deployment in municipal storm water maintenance. Procurement officers in dense urban watersheds are shifting payment structures toward guaranteed system performance metrics rather than per-hour or per-mile billing. This transition is most visible in Florida municipalities managing aging combined sewer overflow infrastructure where flooding liability exposure drives risk transfer to service providers.
Storm Water Cleaning Services Market Segmentation
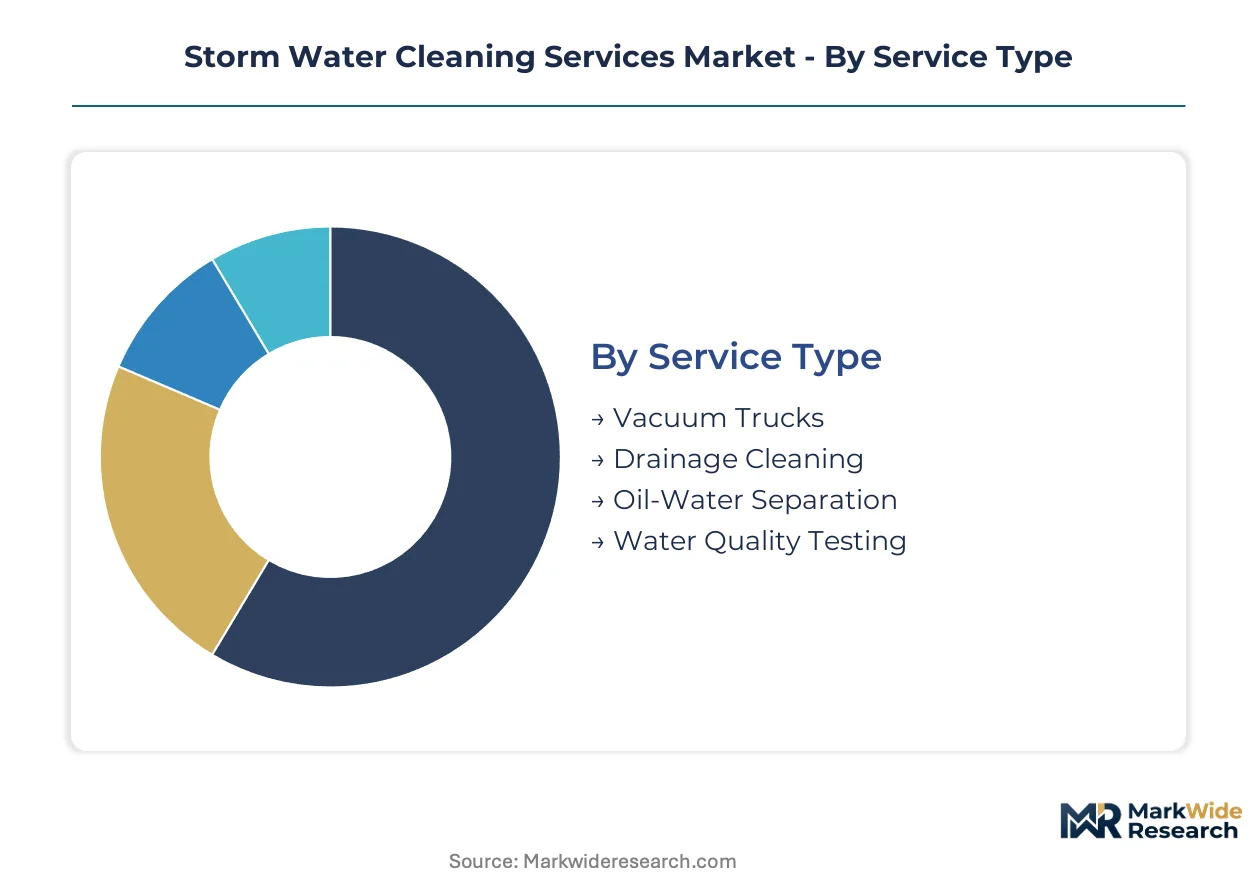
Storm water cleaning services fragment across four distinct dimensions that determine pricing power, contract duration, and equipment requirements. Service type and technology selection drive capital intensity, while application and end-user categories shape compliance complexity and procurement cycles.
Service Type:
Vacuum trucks operate on compressed maintenance cycles measured in weeks, whereas water quality testing contracts extend across quarterly or annual reporting periods. Drainage cleaning and oil-water separation occupy intermediate frequencies tied to seasonal runoff patterns.
- Vacuum Trucks:Hydro-excavation vehicles deploy suction at 15-20 inches of mercury to extract sediment, debris, and hydrocarbons from catch basins and storm drains. Municipalities across Texas, Louisiana, and Florida are consolidating district-level contracts into watershed-scale awards that specify minimum fleet capacity and response time guarantees.
- Drainage Cleaning:High-pressure jetting and mechanical auguring clear blockages from culverts, pipes, and conveyance systems. Construction sites in hurricane-prone coastal zones drive episodic demand spikes preceding and following storm seasons.
- Oil-Water Separation:Coalescing plate separators and flotation systems extract petroleum sheen before discharge. Industrial facilities in petrochemical corridors pay premium rates for immediate response capabilities that prevent regulatory reporting triggers.
- Water Quality Testing:Laboratory analysis of runoff samples for total suspended solids, heavy metals, and nutrient loads. Government agencies bundle testing services with maintenance contracts to satisfy EPA NPDES permit documentation requirements.
Vacuum trucks anchor the volume base while water quality testing gains share at the steepest rate as documentation mandates tighten.
Application:
Cost tier stratification separates capital-intensive municipal concessions from transactional construction site work. Industrial facilities occupy the premium tier due to hazardous material handling premiums and liability exposure.
- Municipalities:Cities and counties maintain separate storm sewer systems under EPA NPDES permits that mandate documented inspection frequencies. Long-term concession agreements in dense urban watersheds now include performance penalties for missed maintenance intervals.
- Industrial Facilities:Petrochemical complexes, refineries, and manufacturing plants require oil-water separation and sheen response under multi-media environmental permits. Texas and Louisiana regulators impose coastal discharge standards exceeding federal baselines.
- Construction Sites:Temporary erosion control and sediment removal during active development phases. Contractors purchase services on unit-rate or per-event pricing rather than multi-year commitments.
- Residential Areas:Homeowner association contracts for private storm water retention ponds and drainage easements. This segment concentrates in master-planned communities across Florida and coastal Texas with mandatory drainage assessments.
Municipalities command the largest contract values while industrial facilities deliver the highest margins per service hour.
Technology:
Technology maturity spans established mechanical methods through emerging biological approaches. Chemical treatment faces displacement near ecological receptors as regulatory tolerance for residual toxicity declines.
- Mechanical Cleaning:Vacuum extraction, jetting, and grit removal equipment physically separate pollutants from runoff. Gulf Coast municipalities favor mechanical approaches for reliability during hurricane response when biological systems face overload conditions.
- Bioremediation:Phytoremediation and microbial treatment systems metabolize hydrocarbons and nutrients without chemical residuals. Wetland-adjacent facilities in Louisiana and Florida are phasing in bioremediation to satisfy state-level ecological discharge standards.
- Chemical Treatment:Flocculating agents and disinfectants precipitate or neutralize contaminants. Application is narrowing to industrial settings with contained treatment trains and no direct ecological discharge pathways.
- Manual Cleaning:Crew entry into confined spaces for debris removal in legacy brick-and-concrete systems. Aging infrastructure in northeastern cities requires adapted techniques that increase labor hours and safety equipment deployment.
Mechanical cleaning dominates current deployment while bioremediation is climbing the fastest as chemical restrictions expand.
End User:
Procurement authority and technical sophistication vary sharply across end-user categories. Government agencies specify compliance metrics while property owners prioritize cost minimization.
- Government Agencies:Municipal public works departments and environmental quality divisions issue RFPs with embedded EPA NPDES specifications. Texas, Florida, and Louisiana state agencies are consolidating previously fragmented procurement into watershed-scale contracts.
- Environmental Consultants:Engineering firms subcontract field services for client remediation projects and compliance auditing. This channel demands flexible mobilization and detailed documentation for litigation support.
- Property Owners:Commercial real estate and industrial site operators purchase reactive services for flooding events or permit violations. Price sensitivity limits contract duration and preventive service uptake.
- Contractors:Construction and infrastructure developers require temporary erosion control and dewatering services. Demand fluctuates with building permit issuance and federal infrastructure spending cycles.
Government agencies provide the most stable revenue base while environmental consultants are expanding most quickly as outsourcing of field services accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Gulf Coast municipalities exhibit the lowest price sensitivity due to hurricane-driven emergency mandates, while residential homeowner associations in Florida master-planned communities negotiate aggressively on recurring drainage assessments.
United States
Gulf Coast municipalities in Texas, Louisiana, and Florida are consolidating fragmented district-level contracts into watershed-scale service awards with performance guarantees. The EPA's National Pollutant Discharge Elimination System permit renewal requirements mandate documented inspection frequencies and maintenance records. Houston, New Orleans, and Miami-Dade represent the densest clusters of vacuum truck deployment due to combined sewer overflow infrastructure and coastal flooding liability exposure.
Canada
Ontario and British Columbia municipalities face spring runoff and autumn leaf debris challenges that compress seasonal maintenance windows. Environment and Climate Change Canada enforces federal Fisheries Act provisions protecting fish-bearing waters from urban runoff contamination. The Greater Toronto Area anchors demand for mechanical cleaning services where aging brick-and-concrete collection systems require adapted vacuum extraction techniques.
Germany
Industrial facilities in the Rhine-Ruhr and Bavarian chemical corridors require oil-water separation under stringent state water authority discharge standards. The Federal Water Act implements EU Water Framework Directive requirements for integrated river basin management. Stuttgart and Munich public works departments bundle storm water maintenance with wastewater infrastructure concessions.
United Kingdom
London and Southeast England utilities manage combined sewer overflow events through Thames Tideway Tunnel infrastructure investments. The Environment Agency enforces permits under the Environmental Permitting Regulations for industrial storm water discharges. Greater Manchester and Birmingham are retrofitting Victorian-era drainage systems with smart sensor integration for predictive maintenance dispatch.
Australia
New South Wales and Queensland councils face intense rainfall variability between drought and flood cycles that strains maintenance scheduling. The national Water Quality Guidelines inform state-level storm water management policies administered by environmental protection authorities. Sydney and Melbourne metropolitan areas concentrate demand for bioremediation technologies near wetland-adjacent developments.
Storm Water Cleaning Services Market Competitive Landscape
National environmental service conglomerates and regional vacuum fleet operators split the market through divergent capital deployment strategies. The vendor base concentrates among established fleet operators with hazardous waste endorsements, creating barriers for new entrants lacking confined space entry certifications. Two archetypes dominate: integrated environmental compliance platforms bundling remediation with downstream waste handling, and specialized mechanical extraction firms competing on response time guarantees. Competitive moves center on municipal concession consolidation and technology licensing for vortex separation systems.
Within the integrated compliance tier, Clean Harbors, Inc. and Veolia Environmental Services occupy positions defined by hazardous waste network density and long-term municipal concession anchoring. Hydro International exemplifies technology-differentiated positioning through proprietary separation equipment that reduces maintenance frequency. These three companies represent the strategic spectrum from waste-handling bundling through equipment-enabled service compression.
| Leading Market Players |
|---|
| Clean Harbors, Inc. |
| Veolia Environmental Services |
| DBi Services |
| Hydro International |
| River City Environmental, Inc. |
| Storm Water Maintenance, LLC |
| Northwest Storm Water Management, LLC |
| Clean Water Services |
| Advanced Drainage Systems, Inc. |
| Others |
Value Network & Pricing Analysis
The Houston Ship Channel freight corridor anchors cost dynamics across the storm water services value chain, where diesel fuel volatility and vacuum truck fleet concentration in Texas and Louisiana shape both upstream supply decisions and downstream municipal contract pricing tiers.
Pricing Analysis
After-sales revenue from preventive maintenance contracts and emergency response retainers drives lifetime customer value, displacing pure transactional vacuum truck deployment. Three-tier pricing structure across premium, standard, and economy levels separates watershed-scale municipal concessions with performance guarantees from per-event construction site work and reactive residential calls. Cost compression in the standard tier is intensifying because diesel fuel represents 35-40 percent of operating costs for vacuum extraction services. Industrial facilities exhibit the lowest price sensitivity due to regulatory reporting liability, while residential homeowner associations negotiate aggressively on recurring drainage assessments.
Supply Chain Analysis
Export-control regimes on specialized hydro-excavation vehicle components, particularly vacuum blower assemblies and high-pressure pump systems, limit equipment flow from German and Japanese manufacturers to North American fleet operators. Vacuum truck manufacturing concentrates in the United States, Canada, and Germany, with chassis fabrication drawing from Detroit-based OEM supply chains. Raw material dependencies include high-grade steel for vacuum vessels, specialized rubber compounds for suction hoses, and precision-machined aluminum for blower housings. Single-source vulnerability persists for 4,000-gallon capacity vacuum blower units produced by two dominant suppliers. Distribution runs through authorized dealer networks with factory-direct service agreements for municipal fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified operator scarcity for hazardous waste endorsement and confined space entry qualifications constrains fleet expansion and emergency surge capacity, creating durable competitive moats for incumbent vacuum truck operators with established training pipelines.
For Market Incumbents: Insulate market position by securing exclusive municipal concession renewals in hurricane-prone Gulf Coast watersheds before EPA NPDES permit consolidation accelerates. Prioritize backward integration into sediment dewatering and hazardous waste disposal to capture margin currently leaked to third-party landfill operators. The emerging threat of IoT-enabled predictive maintenance platforms from industrial automation vendors demands rapid certification investment in smart sensor integration capabilities. For New Entrants and Emerging Players: Establish a beachhead in bioremediation service categories where phytoremediation and microbial treatment expertise remains scarce among legacy mechanical extraction firms. Target wetland-adjacent industrial facilities in Louisiana and Florida facing state-level ecological discharge standards that exceed federal baselines. A specialized go-to-market angle combining rapid-response sheen remediation with documented compliance reporting addresses immediate regulatory pain points. For Investors and Strategic Acquirers: EPA NPDES permit renewal requirements reshaping the acquisition landscape toward service providers with documented maintenance records and watershed-scale contract portfolios. Long-term viability over the next decade hinges on exposure to municipal concession agreements rather than transactional construction site work. Acquisition target archetype: regional vacuum fleet operators with hazardous waste endorsements and confined space entry certifications in underserved northeastern markets. The signal to watch is consolidation velocity in Texas and Louisiana municipal procurement departments.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Capacity Expansion | Additional vacuum truck deployment captures watershed-scale municipal contracts consolidating across Gulf Coast states. |
| Backward Integration into Waste Disposal | In-house sediment dewatering and landfill access eliminates third-party margin extraction and improves contract profitability. |
| Smart Sensor Platform Partnership | IoT-enabled catchment monitoring converges with predictive maintenance dispatch before blockages trigger flooding liability. |
| Bioremediation Capability Buildout | Phytoremediation and microbial treatment expertise satisfies state-level ecological discharge standards near wetland receptors. |
| Certified Operator Training Pipeline | Proprietary hazardous waste endorsement and confined space entry programs ensure workforce scalability during storm surge demand spikes. |
Research Methodology
Operator-level perspectives from municipal public works directors, vacuum truck fleet managers, industrial environmental compliance officers, and hazardous waste disposal facility operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA NPDES permit databases, state Department of Environmental Quality enforcement records, and municipal procurement contract filings. Customs data on vacuum truck chassis imports, diesel fuel price indices, and landfill capacity reports provided quantitative anchors. Bottom-up service revenue estimates triangulated against top-down infrastructure spending projections.
Scenario-bracketing across hurricane frequency variants, diesel fuel price bands, and EPA enforcement intensity levels framed the analytical envelope. The forecast framework modeled service type segmentation, technology adoption curves, application-tier contract durations, and end-user procurement authority structures. CAGRs derived from fitted growth curves applied to documented municipal contract values and industrial facility spending patterns. Key inputs included Gulf Coast capital allocation trends for resilient drainage infrastructure and bioremediation technology maturation timelines.
Stress conditions across diesel cost spikes, landfill capacity constraints, and certified operator availability shortages were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPA NPDES permit renewal timelines and state-level coastal discharge standard evolution. Material shifts in hurricane frequency patterns or federal infrastructure spending authorization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Packaged Water Treatment System Market