
 Global Tire Recycling Market | 2026-2036
Global Tire Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tire Recycling Market Outlook
Aftermarket rubber compound sales is narrowing as tire manufacturers build captive pyrolysis capacity. Michelin Group leverages vertical integration into tire-derived fuel and recovered carbon black streams. Liberty Tire Recycling anchors North American collection density through its drop-off center network. Genan Holding A/S specializes in large-scale mechanical shredding for civil engineering applications.
Tire recycling encompasses the recovery of rubber, steel, and textile fibers from end-of-life pneumatic tires through thermal, mechanical, or chemical processes, yielding particle sizes from 25 mm shreds to 40 mesh crumb. Pyrolysis operations recover oil and carbon black at temperatures between 400°C and 700°C in oxygen-free environments. Crumb rubber production dominates volume flows into asphalt modification, where polymer content enhances binder elasticity and rutting resistance. Devulcanization remains the smallest segment by throughput but commands premium pricing for revulcanized compounds returning to new tire manufacturing.
The EPA regulates tire-derived fuel combustion under the Resource Conservation and Recovery Act, while the EU's REACH framework governs chemical registration for recovered carbon black and pyrolysis oil. Japan's METI sets material recovery targets that shape export demand for processing equipment. Stakeholders must monitor regulatory divergence between jurisdictions that classify pyrolysis outputs as products versus waste, as this classification determines market access and investment returns.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing waste-to-product timelines and forcing capital reallocation toward pyrolysis infrastructure. This regulatory pressure is virtualizing traditional mechanical shredding economics by elevating chemical recovery pathways.
Growth Catalysts
- Asphalt Modification Mandates:State transportation agencies in the US specify crumb rubber percentages in binder formulations. Polymer-enhanced asphalt extends pavement lifecycle and reduces maintenance frequency.
- REACH Registration Pathways:ECHA guidance on recovered carbon black classification enables chemical product status for pyrolysis outputs. This unlocks broader industrial offtake beyond fuel applications.
- Producer Responsibility Schemes:Germany's end-of-life tire regulations obligate manufacturers to finance collection and processing. This creates guaranteed feedstock flows for recycling operators.
Market Restraints
- Natural Gas Price Volatility:Pyrolysis reactors consume substantial thermal energy. European gas price spikes since 2022 have compressed plant operating margins and delayed project commissioning.
- Collection Infrastructure Concentration:Rural regions in India and Southeast Asia lack dense drop-off networks. Feedstock logistics costs escalate with distance from shredding facilities.
- Devulcanization Yield Ceilings:Current chemical and microwave processes recover 60-70% of original rubber properties. This technical limitation caps premium pricing for revulcanized compounds.
Strategic Opportunities
- Brazilian Civil Engineering Uptake:ANVISA approval processes for crumb rubber in construction materials are streamlining. Megaproject pipelines in São Paulo and Rio de Janeiro create volume anchors.
- Carbon Black Substitution:Tire manufacturers seek virgin carbon black alternatives amid Scope 3 emissions scrutiny. Recovered grades from pyrolysis qualify for sustainability certifications.
- Digital Feedstock Marketplaces:Blockchain-tracked tire collection platforms are emerging. These channels reduce intermediary layers and improve price transparency for generators and processors.
Industry Challenges
- Pyrolysis Operator Certification:ISO 15270 compliance timelines for tire-derived fuel facilities extend 18-24 months. This delays revenue recognition for new plant investments.
- Steel Contamination Standards:Magnetic separation systems must achieve 99.5% ferrous removal for textile fiber recovery. Equipment calibration demands specialized maintenance technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tire Recycling Market |
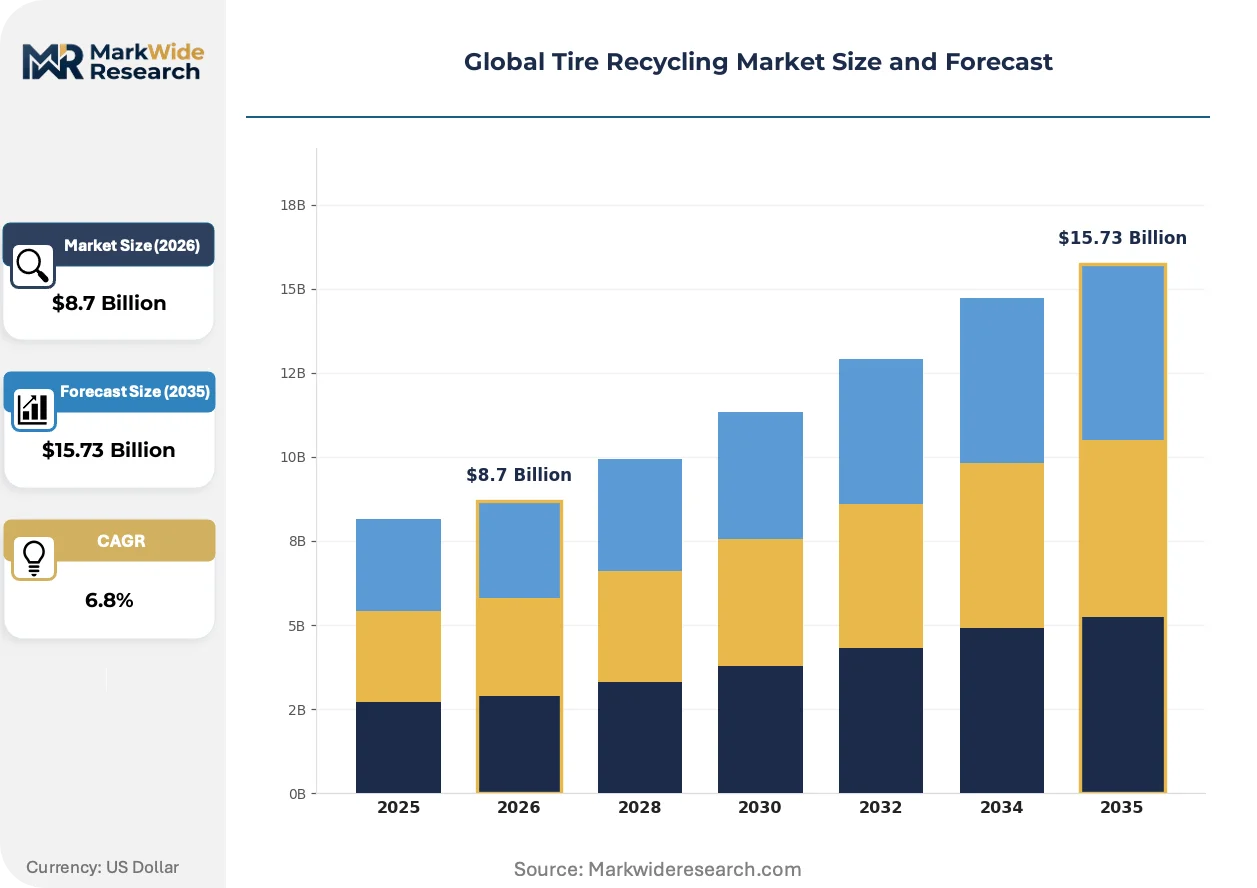
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Drop-off Centers, Mobile Collection, Curbside Pickup, Retail Partnerships Recycling Process: Mechanical Shredding, Pyrolysis, Devulcanization, Crumb Rubber Production End Use: Asphalt Modification, Playground Surfaces, Sports Fields, Fuel Substitute Material Type: Passenger Tires, Truck Tires, Off-the-Road Tires, Others |
| Companies Covered | Michelin Group, Entech Inc., Liberty Tire Recycling, Wastefront AS, reRubber, LLC, Genan Holding A/S, Bridgestone Corporation, GRP Limited, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tire Recycling Market Strategic Shifts
Thermal and chemical recovery pathways are converging with digital traceability systems. This convergence is compressing certification timelines and enabling premium pricing for verified sustainable materials.
Microwave devulcanization is virtualizing conventional chemical bath processes. Tire retreaders and compounders in Germany and Japan are piloting continuous-feed systems. This technology is virtualizing batch production economics by cutting energy intensity and enabling real-time quality adjustment.
The EU's CSRD disclosure requirements now capture Scope 3 emissions from tire sourcing. Automotive OEMs are mandating recycled content certificates from tier-one suppliers. European rubber compounders are responding by securing long-term offtake agreements with pyrolysis operators to lock in verified carbon black streams.
Construction procurement teams are unbundling asphalt binder specifications from traditional petroleum suppliers. State DOTs in California and Texas now accept performance-graded binders with 15-20% crumb rubber substitution. This specification shift is most visible in US federal highway projects where lifecycle cost analysis overrides first-cost bidding.
Global Tire Recycling Market Segmentation
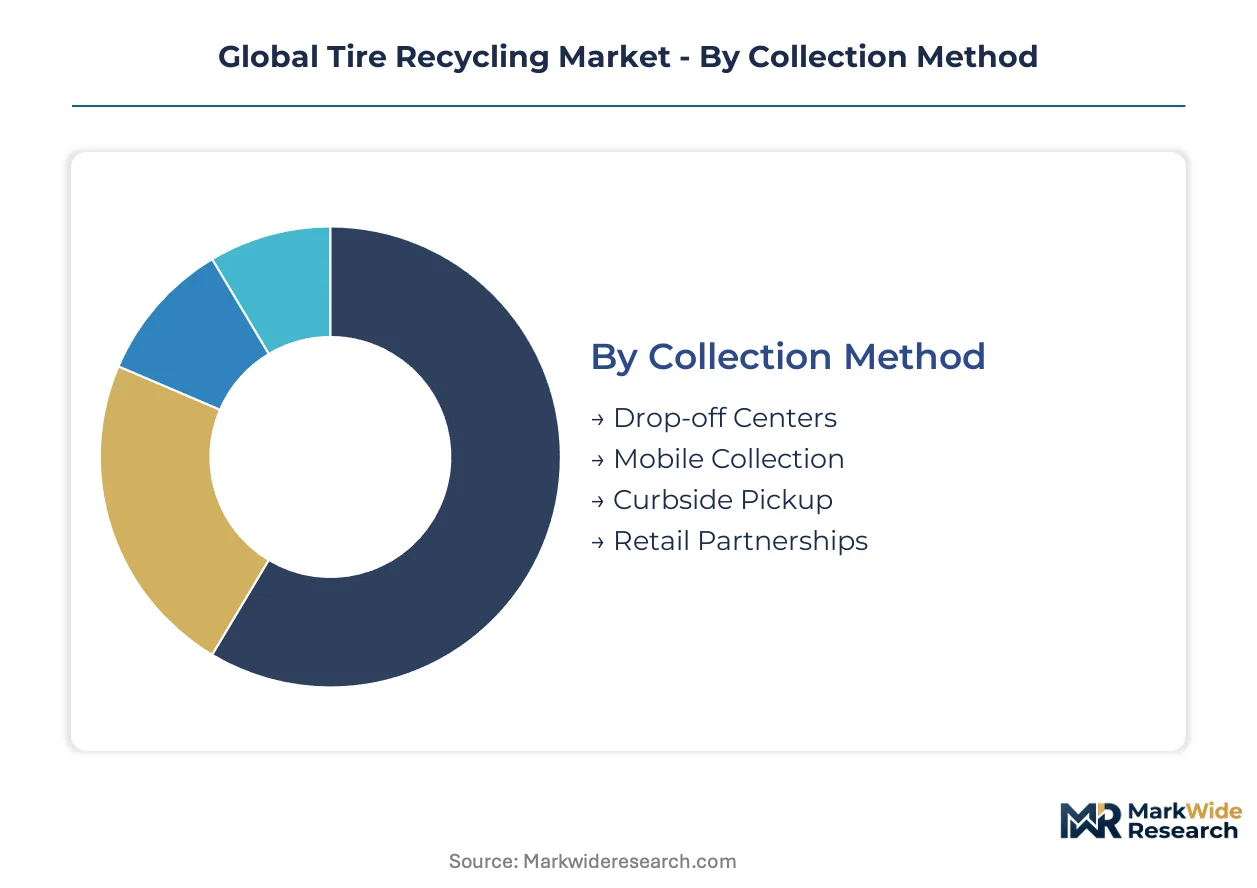
Segmentation in tire recycling reveals how feedstock logistics, processing technology selection, and end-use specification interlock to determine margin capture. Each dimension carries distinct capital intensity profiles and regulatory exposure that shape operator strategy.
Collection Method:
Geography dictates which collection infrastructure achieves density economics versus stranded cost structures.
- Drop-off Centers:Fixed-site facilities aggregate end-of-life tires from consumers and small commercial generators. Liberty Tire Recycling anchors North American density through this model, with rural coverage gaps in India and Southeast Asia elevating logistics costs for distant processors.
- Mobile Collection:Fleet-based operations serve industrial generators and fleet operators with scheduled pickup routes. Germany's producer responsibility schemes guarantee feedstock volumes that justify dedicated truck deployment, compressing collection cycle times.
- Curbside Pickup:Municipal waste integration captures residential tires at marginal incremental cost. Japan's METI material recovery targets shape municipal program design, with contamination rates higher than commercial streams.
- Retail Partnerships:Tire dealer networks provide install-and-haul convenience. Partnerships concentrate in urban corridors where dealer density matches shredding facility proximity.
Drop-off centers hold installed capacity. Mobile collection is rotating up the share rankings.
Recycling Process:
Cost tier separation distinguishes commodity mechanical processing from premium chemical recovery pathways.
- Mechanical Shredding:Size reduction through granulators and cracker mills yields 25 mm shreds to 40 mesh crumb. This baseline technology dominates volume flows into civil engineering applications, with Genan Holding A/S operating large-scale European capacity.
- Pyrolysis:Thermal decomposition at 400°C to 700°C in oxygen-free environments recovers oil, carbon black, and syngas. EU Green Deal circular economy mandates are accelerating plant investments, though European natural gas price volatility since 2022 has compressed operating margins.
- Devulcanization:Chemical and microwave processes break sulfur crosslinks to restore rubber elasticity. Current yield ceilings of 60-70% original properties cap premium pricing for revulcanized compounds returning to tire manufacturing.
- Crumb Rubber Production:Cryogenic or ambient grinding creates specified particle sizes for binder modification. State DOT specifications in California and Texas now mandate 15-20% crumb rubber substitution in performance-graded asphalt.
Mechanical shredding commands volume share. Pyrolysis is climbing the fastest on capital deployment metrics.
End Use:
Application type determines specification stringency and pricing power across construction, recreation, and energy recovery markets.
- Asphalt Modification:Crumb rubber enhances binder elasticity and rutting resistance in polymer-enhanced asphalt. US federal highway projects prioritize lifecycle cost reductions over first-cost bidding, expanding procurement from state transportation agencies.
- Playground Surfaces:Impact-absorbing tiles and poured-in-place systems utilize 10-30 mesh crumb with polyurethane binders. ANVISA approval streamlining in Brazil is opening megaproject pipelines in São Paulo and Rio de Janeiro.
- Sports Fields:Synthetic turf infill specifications balance performance, heat retention, and migration control. Regulatory scrutiny of microplastic release is shifting specification toward encapsulated or alternative infill materials.
- Fuel Substitute:Tire-derived fuel combustion in cement kilns and pulp mills operates under EPA Resource Conservation and Recovery Act permitting. ISO 15270 compliance timelines of 18-24 months delay revenue recognition for new facilities.
Asphalt modification anchors volume offtake. Playground surfaces are expanding most quickly on specification upgrades.
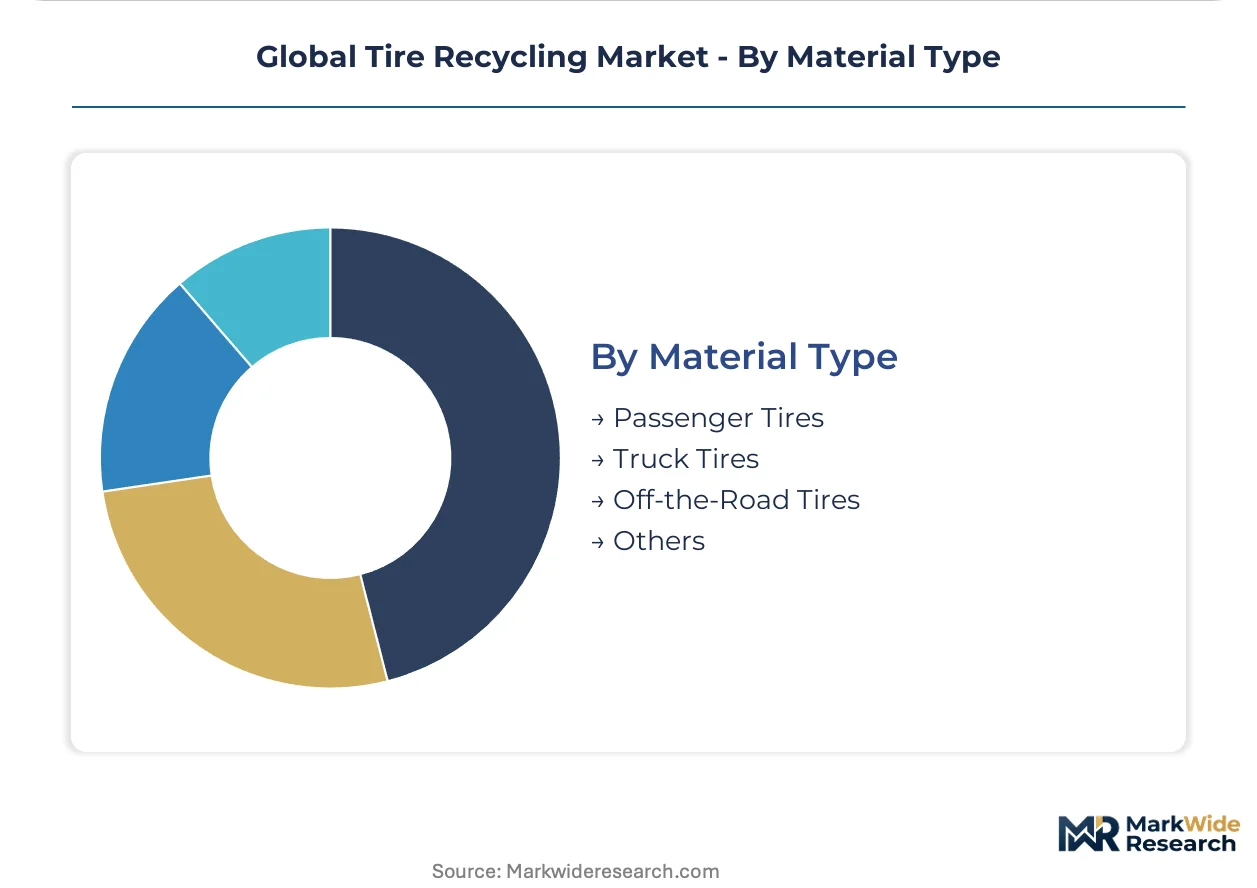
Material Type:
Volume concentration and processing economics vary substantially by tire category scale and construction complexity.
- Passenger Tires:High-unit-volume feedstock with standardized construction and steel-belted radial design. Collection density concentrates in urban corridors across Germany, Japan, and the United States.
- Truck Tires:Heavier construction with thicker tread sections and higher natural rubber content. Retreading economics compete with recycling for viable casings, constraining feedstock availability.
- Off-the-Road Tires:Mining and construction equipment tires present extreme size and handling challenges. Specialized shredding equipment and logistics networks serve this low-volume, high-mass segment.
- Others:Agricultural, aircraft, and motorcycle tires with niche specifications and dispersed generation patterns. Collection infrastructure gaps elevate per-unit processing costs.
Passenger tires dominate feedstock tonnage. Truck tires are gaining share fastest on natural rubber recovery value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes tire-derived materials primarily through pyrolysis pathways for recovered carbon black, while the United States concentrates volume into crumb rubber for asphalt modification. China deploys mechanical shredding for civil engineering fill at scale. Brazil and Japan diverge toward playground surfaces and material recovery targets respectively.
Germany
End-of-life tire regulations under producer responsibility schemes guarantee feedstock flows to pyrolysis operators. The EU Green Deal's circular economy mandates accelerate chemical recovery plant investments. Industrial clusters in North Rhine-Westphalia host shredding facilities serving Ruhr Valley construction markets.
United States
State transportation agencies in California and Texas specify crumb rubber percentages in performance-graded asphalt binders. EPA Resource Conservation and Recovery Act permitting governs tire-derived fuel combustion. Collection density concentrates through Liberty Tire Recycling's drop-off center networks across urban corridors.
China
Municipal infrastructure projects absorb high volumes of mechanically shredded tire material for road base and drainage applications. MIIT industrial policy encourages resource recovery equipment manufacturing. Yangtze River Delta provinces cluster shredding capacity near Shanghai construction material hubs.
Brazil
ANVISA approval streamlining for crumb rubber in construction materials accelerates megaproject procurement. São Paulo and Rio de Janeiro municipal governments specify impact-absorbing surfaces for public playgrounds. Southeast Brazil concentrates collection infrastructure serving Atlantic coast urban corridors.
Japan
METI material recovery targets shape municipal curbside pickup program design for residential tire streams. Automotive OEMs mandate recycled content certificates from tier-one rubber compounders. Kanto region processors supply verified carbon black streams to Tokyo-Yokohama manufacturing clusters.
Global Tire Recycling Market Competitive Environment
Capability concentration sits with integrated tire manufacturers possessing captive pyrolysis technology; scale advantage sits with specialized recycling operators commanding collection network density. The market structures around three archetypes: vertically integrated tire OEMs, independent mechanical processors, and chemical recovery specialists. Dominant competitive moves include backward integration into feedstock supply and strategic offtake agreements with asphalt producers.
Among tire OEMs with recycling operations, Michelin Group and Continental AG exemplify the integrated archetype through upstream control over tire-derived fuel and recovered carbon black streams. Liberty Tire Recycling anchors North American collection density. Genan Holding A/S occupies a position among large-scale mechanical shredding specialists serving civil engineering applications.
| Leading Market Players |
|---|
| Michelin Group |
| Entech Inc. |
| Liberty Tire Recycling |
| Wastefront AS |
| reRubber, LLC |
| Genan Holding A/S |
| Bridgestone Corporation |
| GRP Limited |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Ruhr Valley freight corridors connecting North Rhine-Westphalia shredding facilities to Dutch port terminals impose differential logistics costs that fragment pricing power across mechanical processing tiers and concentrate margin capture with pyrolysis operators possessing captive carbon black certification.
Pricing Analysis
Long-term offtake contracts dominate recovered carbon black streams, locking automotive OEMs into fixed-volume agreements with certified pyrolysis operators. Spot markets persist for crumb rubber in asphalt modification, where state DOT procurement cycles drive volume volatility. Price differentiation hinges on ECHA REACH registration status and ISO 15270 compliance timelines. Cost compression in mechanical shredding intensifies because natural gas price spikes compress operating margins. Municipal asphalt contractors exhibit highest price sensitivity; tire manufacturers with Scope 3 targets show lowest.
Supply Chain Analysis
Upstream feedstock flows concentrate through Germany's producer responsibility schemes, Japan's METI-mandated curbside programs, and Liberty Tire Recycling's North American drop-off density. Pyrolysis reactors draw from steel-belted passenger tire streams; devulcanization plants source higher-natural-rubber truck tire feedstock. Single-source vulnerability concentrates in EU carbon black certification bodies. Distribution runs through construction material hubs serving state transportation agencies and cement kiln operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
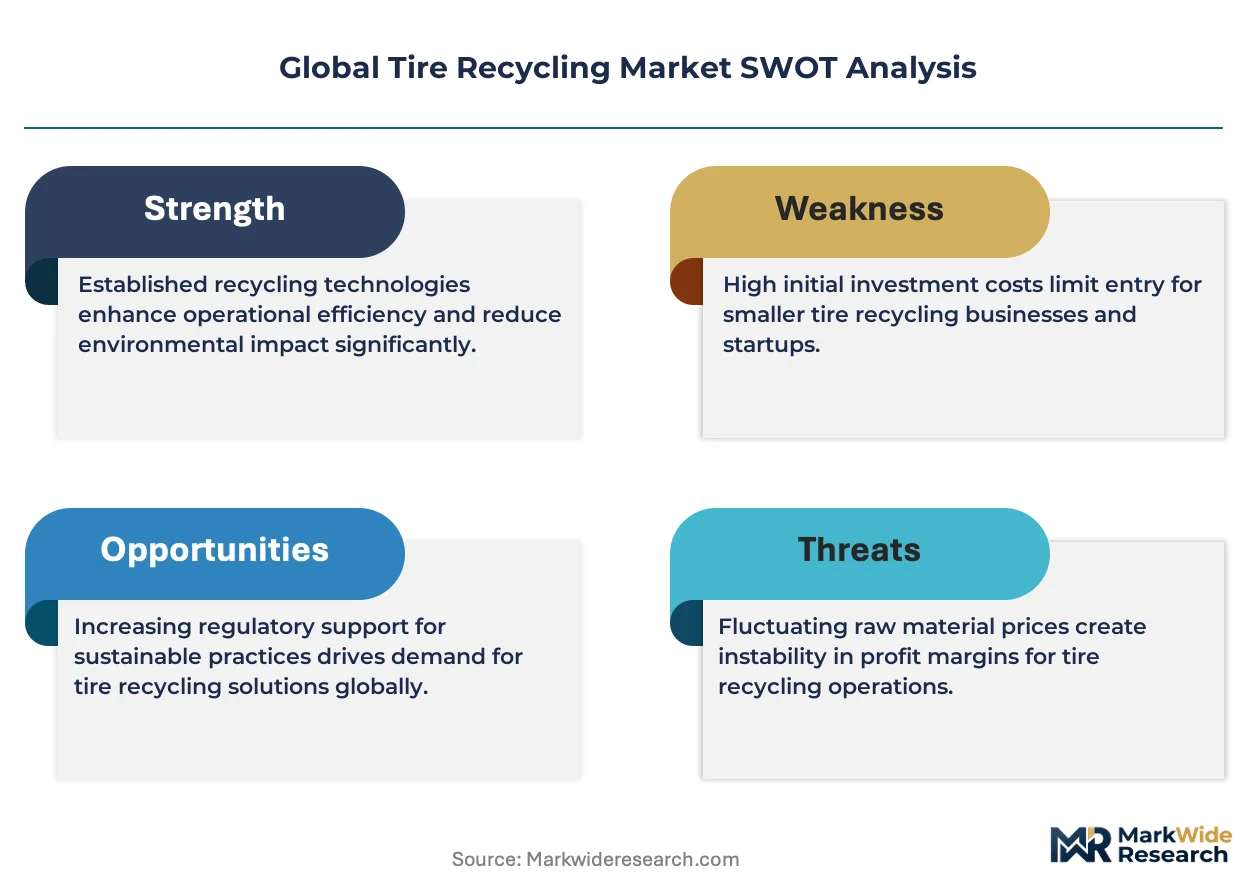
Specialized pyrolysis engineering talent and ECHA registration expertise constitute binding constraints that limit scalable entry, concentrating returns with incumbent operators who secured certification pathways early.
For Market Incumbents: Harden feedstock security through backward integration into mobile collection fleets serving industrial tire generators. Expand pyrolysis capacity in Germany's Ruhr Valley industrial cluster to capture EU Green Deal circular economy procurement preferences. ISO 15270 certification investment protects against emerging devulcanization technology substitution.
For New Entrants and Emerging Players: Pursue Brazilian civil engineering verticals where ANVISA approval streamlining accelerates megaproject crumb rubber procurement. Southeast Asia's collection infrastructure gaps present white-space opportunities for blockchain-tracked tire marketplace platforms. Go-to-market leverage rests on digital feedstock traceability rather than capital-intensive shredding assets.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated tire OEMs spinning non-core recycling operations amid vertical integration fatigue. Five-to-ten-year viability favors chemical recovery specialists with ECHA-registered carbon black streams over mechanical processors facing commodity margin compression. Signal to monitor: state DOT specification shifts beyond 20% crumb rubber substitution thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Secures guaranteed feedstock flows under Germany's producer responsibility mandates. |
| ECHA REACH Registration Investment | Unlocks chemical product classification for pyrolysis outputs beyond fuel applications. |
| Pyrolysis Capacity Expansion | Captures automotive OEM demand for Scope 3-compliant recovered carbon black. |
| Digital Feedstock Marketplace Launch | Reduces intermediary layers in tire collection through blockchain-tracked provenance. |
| Long-term Asphalt Supply Agreement | Locks state DOT procurement volumes for crumb rubber in performance-graded binders. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with pyrolysis plant operators, ECHA regulatory affairs specialists, state DOT procurement officers, and tire manufacturer sustainability directors; and secondary validation against EPA RCRA permitting databases, EU ECHA registration filings, Japan METI material recovery reports, and customs trade data for tire-derived fuel exports. Bottom-up capacity assessments triangulated with top-down end-use demand modeling.
Forecast inputs incorporated processing technology deployment rates, regulatory compliance timelines, and feedstock logistics cost structures across the projection horizon. Segmentation dimensions modeled collection method, recycling process technology, end-use application, and material type. CAGRs derived from volume-flow analysis anchored in state DOT specification mandates and EU circular economy investment cycles. Natural gas price volatility and carbon black substitution elasticities shaped scenario boundaries.
Sensitivities concentrate around ECHA classification rulings for pyrolysis outputs, natural gas price trajectories affecting reactor economics, and state DOT crumb rubber mandate adoption rates. Cross-checking against EPA tire-derived fuel combustion statistics and EU ETS carbon price benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Green Technology and Sustainability Market
Environment & Sustainability
Water Testing Market
Environment & Sustainability
US Environmental Testing Market
Environment & Sustainability
Europe Nitrogen Oxide Control Systems Market
Environment & Sustainability
Global SCADA in Water and Wastewater Management Market
Environment & Sustainability
Quality Monitoring Sensor for Water Market
Environment & Sustainability
Zero Liquid Discharge Market
Environment & Sustainability
Global Enhanced Water Market
Environment & Sustainability
North America Municipal Solid Waste Management Market
Environment & Sustainability
Enriched Biochar Market
Environment & Sustainability
Solar Waste Recycling Market
Environment & Sustainability
Asia-Pacific Air Quality Control System Market
Environment & Sustainability
Sustainable Construction Market
Environment & Sustainability
UAE E-Waste Management Market
Environment & Sustainability
Carbon Capture and Sequestration Market
Environment & Sustainability
Global Oil Spill Management Market