
 Global Waste Management Equipment Market | 2026-2036
Global Waste Management Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waste Management Equipment Market Foresight
Steel-reinforced polymer composites is restructuring baler drum and conveyor belt economics across the waste management equipment industry. Marathon Equipment leverages backward integration into compaction chamber fabrication to sustain margin control on heavy-duty municipal units. Tomra Systems ASA dominates optical sorting architectures with sensor fusion platforms that anchor premium positioning in electronic scrap processing. Wastequip competes through geographic density in North American distribution, where its dealer network controls aftermarket parts velocity for roll-off containers and compactors.
Waste management equipment comprises mechanical and automated systems engineered to collect, transport, process, and dispose of solid and liquid waste streams, typically operating at throughput rates exceeding 50 tons per hour in industrial configurations and integrating hydraulic compression ratios of 4:1 to 6:1 in modern compactor designs. These systems serve municipalities, industrial generators, and recycling operators by reducing waste volume, recovering recyclable fractions, and preparing refuse for landfill burial or thermal conversion. Shredders and crushers capture the largest installed base due to universal deployment across municipal and construction debris flows, though optical sorting and magnetic separation technologies are expanding fastest as contamination standards tighten. Separators command elevated margin pools because sensor calibration and software upgrades generate recurring revenue streams distinct from capital equipment sales.
The EPA enforces landfill methane capture mandates under the Clean Air Act that compel operators to install gas collection and flaring equipment, while the EU Green Deal's circular economy action plan imposes binding recycling targets that drive optical sorting and separator procurement across member states. Japan's METI promotes domestic waste-to-energy capacity through feed-in tariff structures that require specialized boiler and emission control investments. Stakeholders must monitor how fragmented national recycling targets reshape equipment specification standards and determine whether to prioritize modular system architectures or integrated turnkey offerings.
Market Dynamics
Automated sorting architectures are compressing labor dependencies across municipal and industrial waste streams, forcing equipment manufacturers to recalibrate around sensor fusion platforms and modular retrofit kits rather than monolithic system sales.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding recycling targets across member states are accelerating replacement cycles for optical sorting and magnetic separation equipment in Germany and France.
- Waste-to-energy feed-in tariffs:Japan's METI tariff structures are driving specialized boiler and emission control investments for urban incineration capacity.
- Steel-reinforced polymer composites:These materials are extending baler drum lifespans and reducing conveyor belt maintenance intervals across Brazilian recycling infrastructure.
Market Restraints
- Specialized hydraulic component supply:Precision compression cylinders for 6:1 ratio compactors concentrate among German and Japanese foundries, creating input bottlenecks.
- Sensor calibration complexity:Optical sorting platforms require proprietary software ecosystems that lock operators into single-vendor upgrade paths.
- Landfill methane capture retrofit costs:EPA Clean Air Act mandates compel smaller municipal operators to divert limited capital toward gas collection rather than front-end processing equipment.
Strategic Opportunities
- Modular retrofit architectures:Brazil's expanding domestic recycling infrastructure favors upgradeable sorting lines over greenfield integrated systems.
- Sensor-as-a-service revenue streams:Separator vendors can unbundle software calibration and algorithm updates from capital equipment transactions.
- Construction debris processing:Shredder deployment for concrete and asphalt recovery remains underpenetrated in Japanese urban demolition markets.
Industry Challenges
- Electromechanical technician scarcity:Hydraulic system maintenance and PLC programming skills lag equipment complexity in German and Japanese service networks.
- Legacy compactor integration:Municipal fleets running 15-20 year old hydraulic units face firmware incompatibility with modern telematics and route optimization software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waste Management Equipment Market |
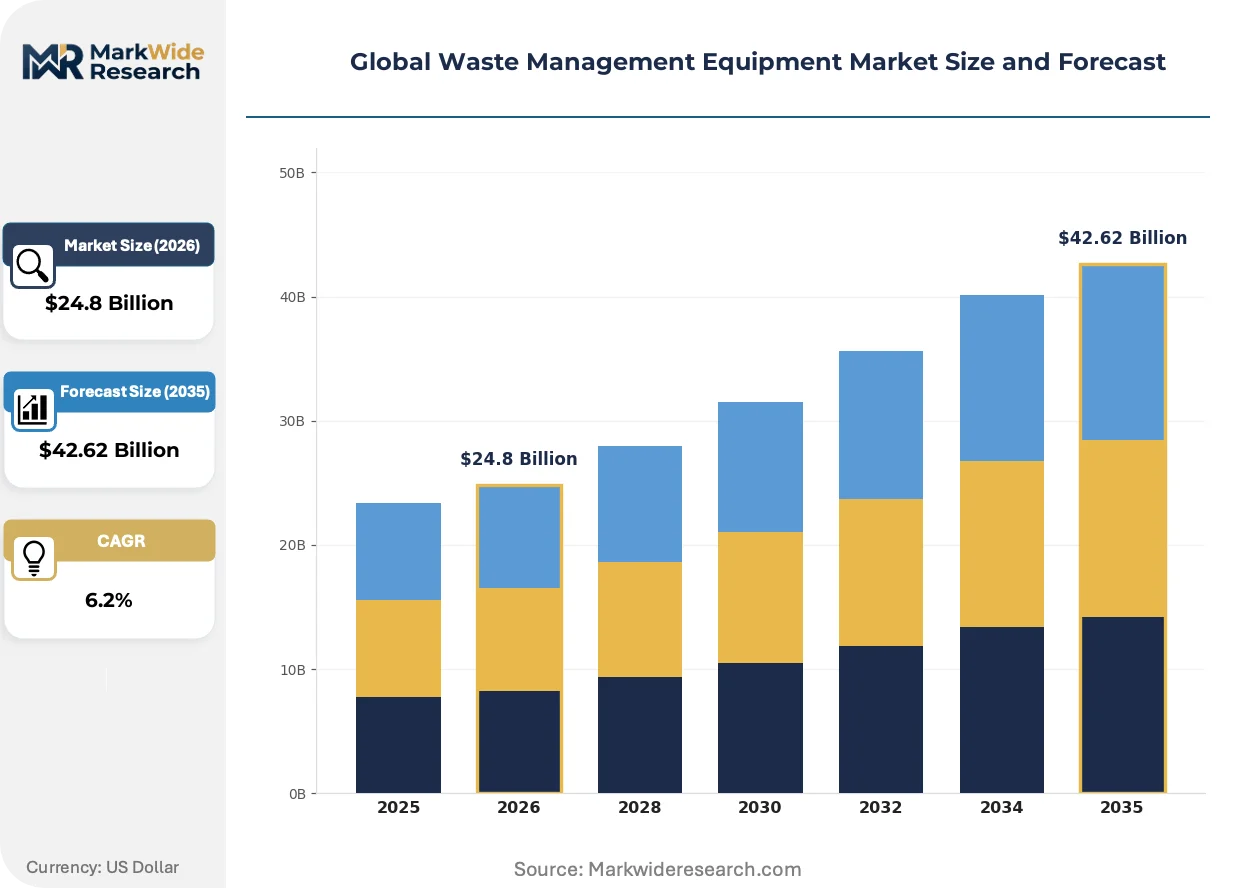
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $42.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compactors, Balers, Shredders, Conveyors, Separators, Crushers Technology: Magnetic Separation, Optical Sorting, Air Classification, Trommel Screens, Rotary Kiln, Autoclave Application: Municipal Solid Waste, Electronic Scrap Processing, Industrial Refuse, Construction Debris, Organic Composting, Hazardous Waste Management End User Industry: Public Utilities, Manufacturing Plants, Recycling Facilities, Waste-to-Energy Units, Agricultural Operations, Landfill Sites |
| Companies Covered | Marathon Equipment, Tomra Systems ASA, Wastequip, Machinex, SSI Shredding Systems, CP Manufacturing, Terex Corporation, BHS, Dover Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waste Management Equipment Market Shifts & Advancements
Equipment intelligence is migrating from centralized control rooms to edge-computing nodes embedded in collection vehicles and processing lines, compressing response times for contamination detection and route optimization.
Near-infrared spectroscopy paired with machine vision is rewriting contamination detection economics for single-stream recycling facilities. MRF operators in Germany and Japan are deploying these fused sensor arrays at throughput rates exceeding 50 tons per hour. The technology is compressing manual sorting headcount while elevating purity premiums for PET and fiber bales.
REACH substance restrictions and RoHS compliance deadlines are forcing redesigns of electronic scrap processing lines across EU member states. Equipment vendors must eliminate restricted flame retardants from control panel housings and sensor enclosures. Separator manufacturers serving WEEE flows in France and the Netherlands are accelerating material certification timelines to maintain market access.
Performance-based service contracts are displacing traditional capital purchase models for municipal fleet operators. Cities in Brazil and Japan now contract for guaranteed uptime and tonnage throughput rather than owning compaction and collection assets outright. This shift concentrates risk with OEMs while extending equipment lifecycle accountability across 10-15 year horizons.
Global Waste Management Equipment Market Segmentation
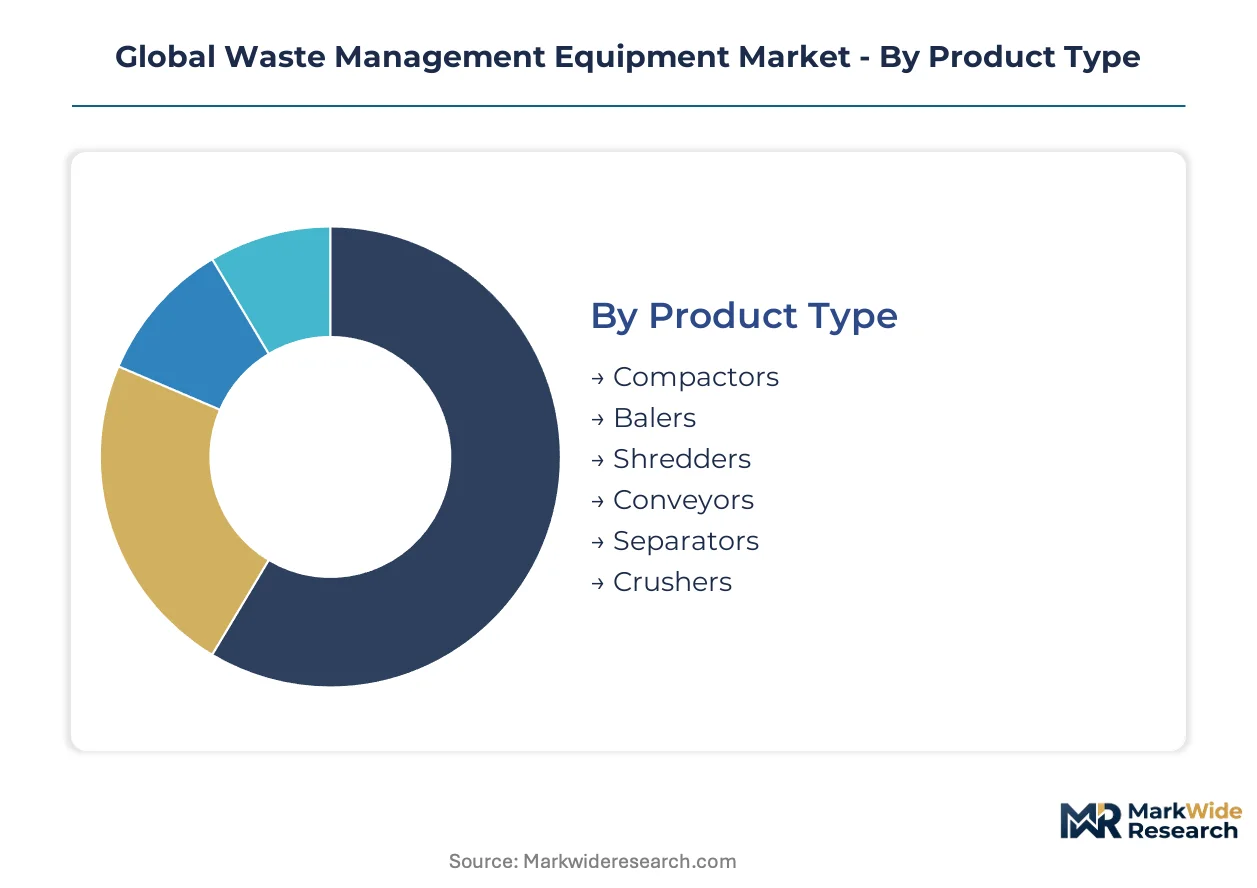
Equipment segmentation in waste management tracks how municipal fleet renewal cycles and industrial contamination standards reshape procurement priorities across mechanical and automated system categories. Technology-driven replacement waves concentrate capital deployment in sensor-intensive architectures while legacy hydraulic units face accelerated obsolescence.
Product Type:
Replacement cycle economics favor equipment categories with modular upgrade paths and extended service intervals over monolithic system architectures.
- Compactors:Hydraulic compression systems achieving 4:1 to 6:1 volume reduction ratios through precision cylinder arrays. German municipal fleets prioritize these units for residential collection routes where route density justifies capital intensity.
- Balers:Steel-reinforced polymer composite drums extend operational lifespan while reducing maintenance downtime. Brazilian recycling infrastructure deploys these for fiber and plastic densification ahead of export logistics.
- Shredders:Universal deployment across construction debris and municipal streams with high torque rotor designs.
- Conveyors:Belt systems integrating magnetic head pulleys for ferrous recovery in single-stream MRF configurations.
- Separators:Near-infrared and machine vision platforms generating recurring software calibration revenue.
- Crushers:Jaw and impact configurations for concrete aggregate recovery in urban demolition markets.
Shredders sit at the top of the volume ranking, with separators climbing the fastest.
Technology:
Procurement decisions increasingly weight sensor fusion capabilities against mechanical reliability metrics in high-throughput processing environments.
- Magnetic Separation:Permanent magnet and electromagnetic drum configurations recovering ferrous fractions from shredded automobile and appliance hulks. Japanese steel mills demand high-purity scrap feedstocks that elevate specification requirements for gauss intensity and belt speed synchronization.
- Optical Sorting:Near-infrared spectroscopy paired with machine vision achieving contamination detection at 50+ tons per hour throughput. German MRF operators deploy these arrays to meet EU Green Deal recycling purity mandates for PET and fiber bale premiums.
- Air Classification:Density-based separation of light plastics from glass and stone fractions in mixed construction debris.
- Trommel Screens:Rotating drum configurations sizing compost and aggregate streams by particle diameter.
- Rotary Kiln:Thermal processing units for medical and hazardous waste volume reduction.
- Autoclave:Steam sterilization systems for infectious medical waste prior to landfill disposal.
Magnetic separation commands the largest installed base, though optical sorting gains share fastest on contamination standard tightening.
Application:
End-use demand fragmentation requires equipment vendors to calibrate between standardized municipal specifications and specialized industrial throughput requirements.
- Municipal Solid Waste:Automated collection and sorting systems deployed across urban fleet procurement programs. French and German cities prioritize optical sorting integration to meet binding landfill diversion targets under EU circular economy mandates.
- Electronic Scrap Processing:Sensor fusion platforms handling WEEE streams with REACH and RoHS compliance requirements. Dutch and French facilities demand certified material handling for restricted flame retardant elimination.
- Industrial Refuse:Heavy-duty shredder and compactor configurations for manufacturing byproduct densification.
- Construction Debris:Concrete and asphalt recovery systems with magnetic separation for rebar extraction.
- Organic Composting:Trommel screening and windrow turning equipment for agricultural and municipal biowaste.
- Hazardous Waste Management:Autoclave and rotary kiln thermal treatment for infectious and chemical refuse streams.
Municipal solid waste anchors procurement volume, while electronic scrap processing expands most quickly on regulatory compliance deadlines.
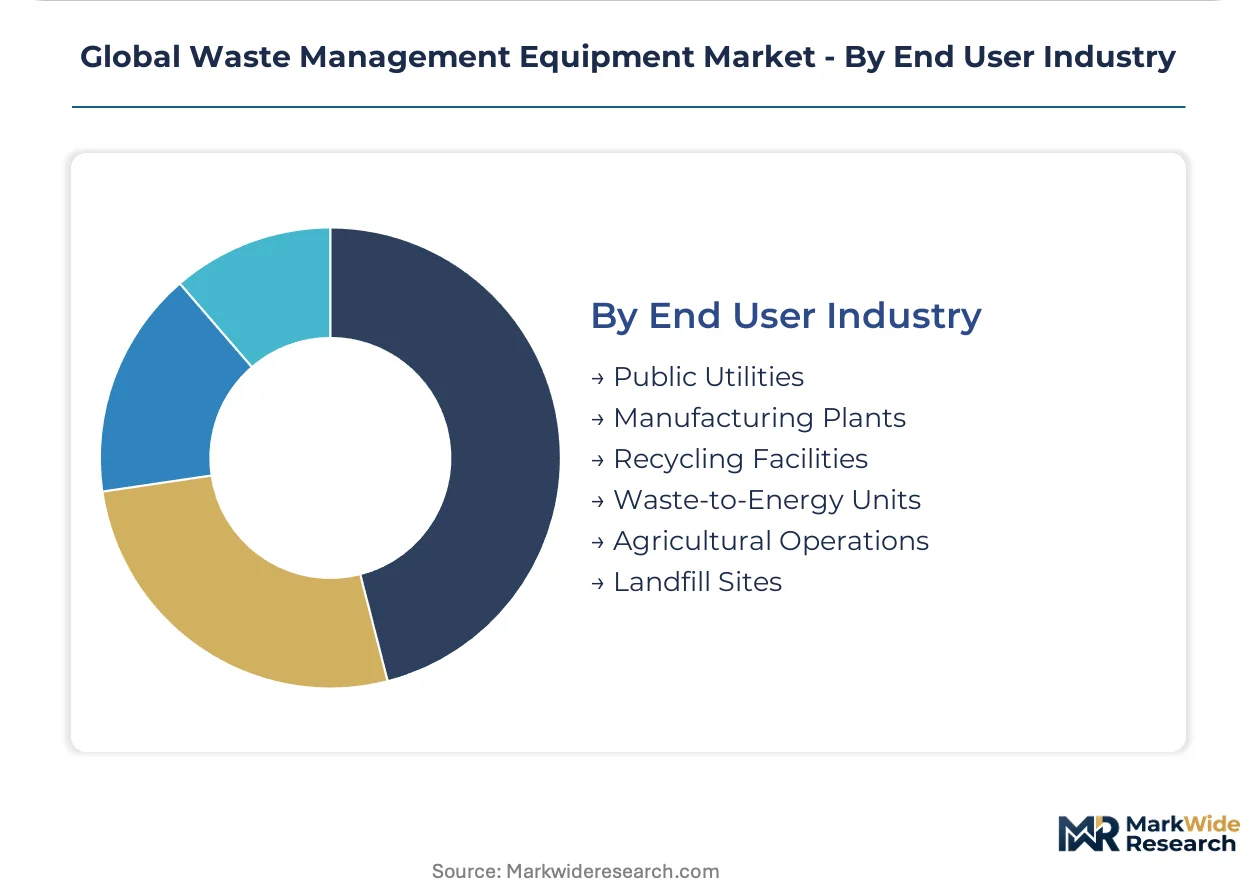
End User Industry:
Customer type determines contract structure preference between capital purchase, performance-based service agreements, and modular retrofit arrangements.
- Public Utilities:Municipal fleet operators contracting for guaranteed uptime and tonnage throughput rather than asset ownership. Brazilian and Japanese cities now structure 10-15 year equipment lifecycle accountability with OEMs.
- Recycling Facilities:MRF operators investing in sensor fusion platforms to capture purity premiums for commodity bale sales. German operators lead deployment of fused near-infrared and machine vision arrays.
- Manufacturing Plants:Industrial generators deploying on-site balers and compactors for byproduct volume reduction.
- Waste-to-Energy Units:Boiler and emission control investments driven by Japan METI feed-in tariff structures.
- Agricultural Operations:Composting and anaerobic digestion feedstock preparation equipment.
- Landfill Sites:Gas collection and flaring equipment mandated under EPA Clean Air Act methane capture requirements.
Public utilities represent the deepest customer pool, with recycling facilities showing the steepest technology investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal fleets anchor procurement intensity for automated collection systems, with EU Green Deal mandates compressing replacement cycles across member states. Japan's waste-to-energy expansion and Brazil's recycling infrastructure build-out concentrate demand in distinct equipment categories.
Germany
Municipal operators in North Rhine-Westphalia and Bavaria deploy optical sorting arrays to meet binding landfill diversion targets. The EU Green Deal's circular economy action plan mandates recycling rates that accelerate equipment replacement in Frankfurt-Rhine-Main and Stuttgart industrial clusters. German foundries supply precision hydraulic cylinders for 6:1 compression ratio compactors, creating captive input advantages for domestic OEMs.
Japan
METI feed-in tariff structures drive specialized boiler and emission control investments for urban incineration capacity. Tokyo and Osaka metropolitan governments contract for performance-based equipment uptime rather than asset ownership. Kanto region MRF operators deploy near-infrared spectroscopy platforms at throughput rates exceeding 50 tons per hour.
Brazil
São Paulo and Rio de Janeiro scale domestic recycling infrastructure with modular retrofit architectures preferred over greenfield systems. ANVISA compliance requirements shape medical waste autoclave specifications. Steel-reinforced polymer composite drums extend baler operational lifespans across Brazilian fiber and plastic densification facilities.
United States
EPA Clean Air Act methane capture mandates compel landfill operators to prioritize gas collection equipment over front-end processing assets. Texas and California municipal fleets run 15-20 year old hydraulic units facing firmware incompatibility with modern telematics. Southeast recycling facilities concentrate demand for magnetic separation and trommel screening configurations.
France
Île-de-France MRF operators invest in sensor fusion platforms to capture purity premiums for PET and fiber bale sales. REACH substance restrictions force redesigns of electronic scrap processing lines with certified material handling for restricted flame retardant elimination. Lyon and Marseille industrial zones anchor WEEE flow processing capacity.
Global Waste Management Equipment Market Competitive Landscape
Global majors compete with regional champions across sensor technology and hydraulic system fabrication, producing a tiered structure where scale-driven OEMs anchor municipal fleet procurement while specialized fabricators capture retrofit niches. Equipment vendors cluster into three archetypes: integrated compaction system builders, optical sorting platform specialists, and geographic density players controlling aftermarket parts velocity. Consolidation pressure concentrates in separator manufacturing where software ecosystems lock operators into single-vendor upgrade paths, while partnership strategies dominate among baler and conveyor suppliers seeking steel-reinforced polymer composite sourcing.
Among North American equipment builders, Wastequip occupies a position exemplifying geographic density strategy through dealer network control, while Marathon Equipment represents backward integration into compaction chamber fabrication. Tomra Systems ASA anchors the premium-tier optical sorting segment. These three names illustrate how competitive positioning stratifies across mechanical reliability, sensor fusion capability, and aftermarket service density rather than converging on uniform technology platforms.
| Leading Market Players |
|---|
| Marathon Equipment |
| Tomra Systems ASA |
| Wastequip |
| Machinex |
| SSI Shredding Systems |
| CP Manufacturing |
| Terex Corporation |
| BHS |
| Dover Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up equipment specialists anchor supply discipline across the waste management equipment landscape, compressing vendor counts in hydraulic component fabrication while enforcing contract-based pricing structures that pass through alloy and sensor input volatility to municipal fleet operators.
Pricing Analysis
Input-cost pass-through from German and Japanese foundries concentrates pricing pressure on precision hydraulic cylinder arrays for 6:1 compression ratio compactors. Three-tier pricing structure across premium, standard, and economy levels separates sensor-fusion optical sorting platforms from mechanical separators and legacy hydraulic units. Municipal buyers in Brazil exhibit highest price sensitivity due to constrained capital budgets, while Japanese waste-to-energy operators accept premium positioning for guaranteed uptime contracts. Cost compression in standard-tier compactors is intensifying because Brazilian and German foundries face alloy surcharge volatility.
Supply Chain Analysis
EU local-content rules under the Green Deal's circular economy action plan are reshaping sourcing patterns for optical sorting platforms and magnetic separation equipment. Component fabrication concentrates in Germany, Japan, and China, with precision hydraulic cylinders and near-infrared sensor arrays drawing from specialized foundries and semiconductor packaging facilities. Supply chain risk centers on single-source vulnerability for proprietary sensor calibration software that locks operators into single-vendor upgrade paths. Distribution runs through authorized dealer networks controlling aftermarket parts velocity for roll-off containers and compactor maintenance kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
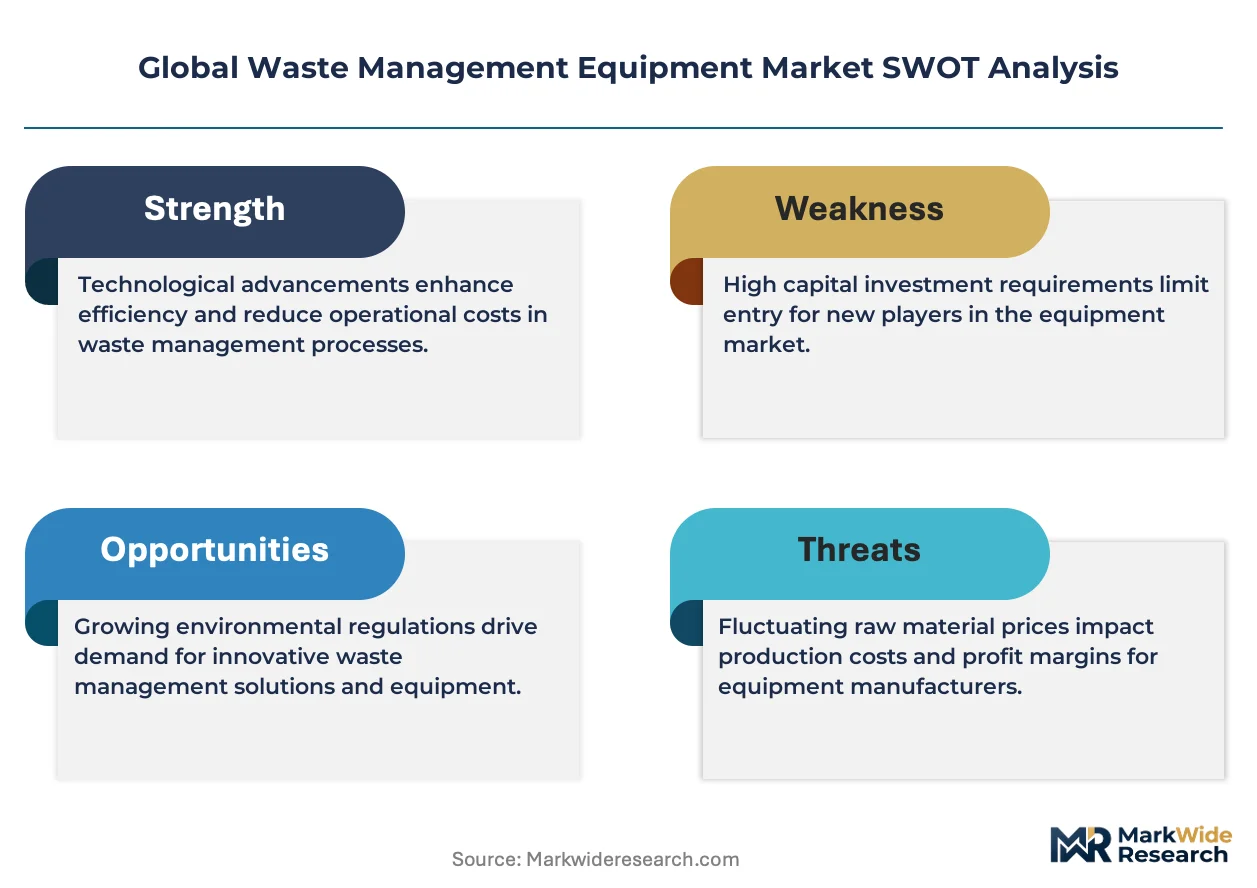
The waste management equipment market functions as a regulatory compounder where EU Green Deal landfill diversion mandates and EPA methane capture requirements create sustained replacement demand across municipal fleet procurement cycles.
For Market Incumbents: Cement sensor-fusion platform dominance by acquiring specialized separator software vendors before emerging entrants can unbundle calibration services. Lock municipal fleet operators into 10-15 year performance-based contracts that concentrate lifecycle accountability and block retrofit competition from modular architecture specialists. Prioritize backward integration into steel-reinforced polymer composite drum fabrication to defend margin control against Brazilian recycling infrastructure cost pressure. For New Entrants and Emerging Players: Mid-sized Brazilian recycling facilities running 15-20 year old hydraulic units represent the most penetrable buyer archetype for modular retrofit kits that bypass greenfield capital intensity. Target Japanese urban demolition markets for concrete and asphalt recovery shredders where magnetic separation for rebar extraction remains underpenetrated. Lead with sensor-as-a-service revenue models that unbundle software calibration from capital equipment transactions. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hydraulic component fabricators lacking optical sorting software ecosystems. Long-term viability over a 5-10 year window hinges on separating equipment vendors with recurring calibration revenue from mechanical-only players exposed to commodity margin compression. Monitor EU member state recycling target acceleration as the primary inflection signal for optical sorting platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Fabrication | Marathon Equipment's captive supply of steel-reinforced polymer drums controls baler maintenance economics. |
| Sensor-as-a-Service Unbundling | Separator vendors converting Tomra Systems ASA's software lock-in into recurring revenue streams beyond capital sales. |
| Modular Retrofit Architecture Deployment | Brazilian MRF operators bypass greenfield costs with upgradeable sorting lines from Machinex and CP Manufacturing. |
| Performance-Based Fleet Contracting | Tokyo and São Paulo municipal governments shift 10-15 year equipment risk to OEMs through guaranteed uptime structures. |
| Geographic Density Dealer Expansion | Wastequip's North American aftermarket parts velocity for roll-off containers creates switching cost barriers. |
Research Methodology
Coverage spans Germany, Japan, Brazil, the United States, and France, with primary inputs from each market combining structured interviews with municipal fleet procurement directors, MRF operations managers, hydraulic system maintenance technicians, and aftermarket parts distributors alongside secondary validation from EPA enforcement databases, EU Green Deal implementation reports, METI feed-in tariff filings, and ANVISA medical waste equipment registrations. Bottom-up equipment shipment tallies triangulate against top-down municipal capital expenditure surveys.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon, modeling segmentation dimensions including equipment product type, separation technology, waste stream application, and end-user industry with regional regulatory cluster overlays. CAGRs derive from equipment replacement cycle analysis and fleet procurement pipeline tracking, with specific inputs from EU landfill diversion target compliance timelines and Japanese waste-to-energy capacity expansion schedules.
Underlying measurement precision varies by segment; optical sorting and separator categories carry tighter precision than legacy hydraulic compactor estimates due to proprietary software revenue disclosure gaps. Forecasts reflect assumptions around regulatory enforcement continuity and alloy input price stability, with revision risk concentrated in EPA mandate delay scenarios and EU recycling target relaxation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market