
 Indonesia Gravity-Based Water Purifier Market | 2026-2036
Indonesia Gravity-Based Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Gravity-Based Water Purifier Market Intelligence
Traditional retail distribution is fragmenting across Indonesia's gravity-based water purifier sector as e-commerce platforms and direct-to-community networks gain share alongside conventional store networks. PT Unilever Indonesia Tbk leverages its extensive FMCG retail footprint to sustain nationwide shelf presence, while Nazava Water Filters (Pt Holland) specializes in ceramic filter systems for rural penetration. Culligan Indonesia competes through service-oriented direct sales channels that anchor premium positioning in urban centers.
Indonesia gravity-based water purifiers operate through passive gravitational filtration using ceramic, activated carbon, or combined media cartridges without electrical dependency, typically achieving flow rates of one to three liters per hour depending on filter configuration and source water turbidity. These systems serve households and institutions lacking reliable electricity or pressurized municipal supply. Multi-stage filters capture expanding margin pools as consumers upgrade from basic ceramic units, while NGO Projects within the application dimension represent the fastest-growing structural channel as development organizations scale safe water programs across Eastern Indonesia.
BIS Indonesia standards and the Ministry of Health's drinking water quality regulations shape product certification requirements, with SNI marking mandatory for commercial distribution and local assembly incentives reinforcing domestic manufacturing. The national government's rural water and sanitation programs channel procurement toward certified suppliers, tightening market access for uncertified imports. Stakeholders must monitor evolving SNI technical specifications and sub-national procurement decentralization to align compliance investment with where public funding flows.
Market Dynamics
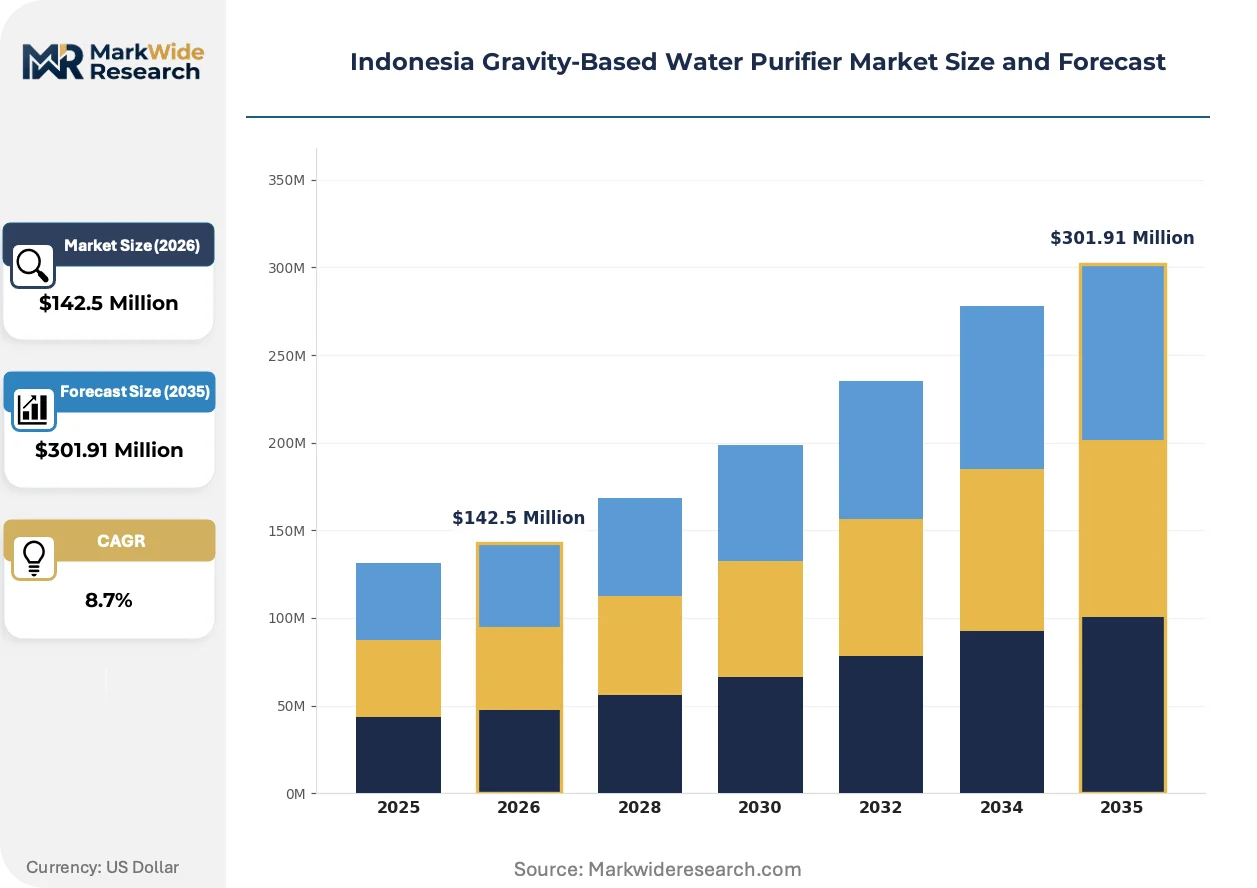
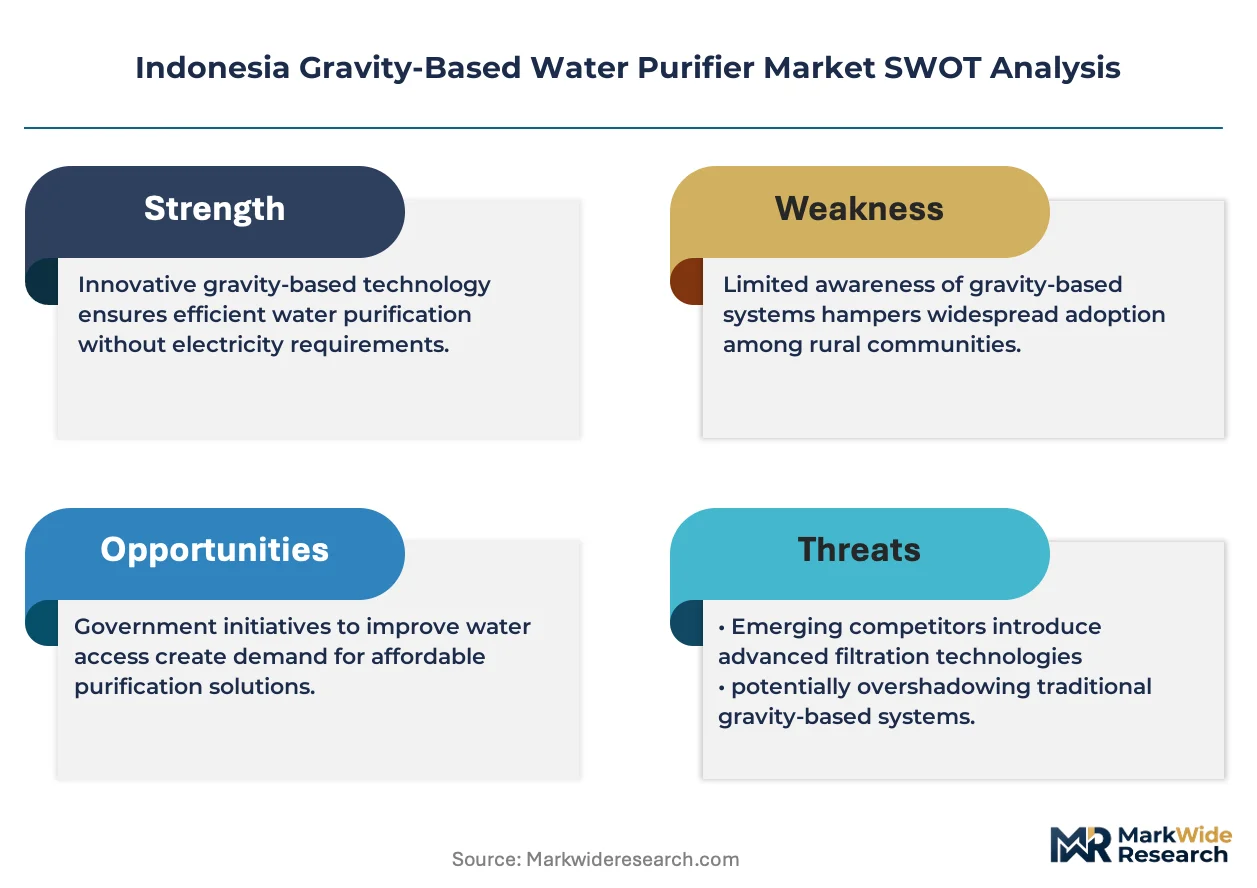
Rural electrification gaps and uneven piped water infrastructure across Indonesia's archipelago are locking gravity-based filtration into the dominant household water treatment modality, with SNI certification requirements now filtering supplier participation.
Growth Catalysts
- Ministry of Health drinking water regulations:Tightening bacteriological standards for household treatment devices are disqualifying uncertified imports and consolidating demand around SNI-marked domestic assembly.
- Eastern Indonesia NGO procurement:Development organization scaling of safe water programs across Papua, Maluku, and Nusa Tenggara is creating institutional volume anchors for ceramic filter suppliers.
- Groundwater contamination clustering:Heavy metal and bacterial contamination in Java's shallow aquifers is pushing peri-urban households toward multi-stage gravity systems as primary drinking water sources.
Market Restraints
- Ceramic cartridge import dependency:Domestic producers lack precision kiln capacity, forcing reliance on Chinese and Indian ceramic media suppliers subject to freight volatility.
- SNI certification timeline friction:Ministry of Industry testing protocols extend commercialization cycles by 8-14 months for new filter configurations.
- Reverse osmosis unit substitution:Falling prices of small-scale electric RO systems in electrified urban cores are capturing premium household segments.
Strategic Opportunities
- Sumatra hinterland penetration:Aceh, North Sumatra, and Riau provinces show household treatment underpenetration above 60% with improving road access enabling direct-to-community distribution.
- Activated carbon-ceramic convergence:Hybrid media configurations capturing chlorine, VOCs, and pathogens in single housings command 40-60% price premiums over basic ceramic units.
- Sub-national procurement decentralization:District-level budget authority under Pamsimas rural water programs is opening tender access beyond Jakarta-centric suppliers.
Industry Challenges
- Field technician scarcity:Filter maintenance training programs remain concentrated in Java, leaving Eastern Indonesia service networks thin.
- Legacy distributor credit terms:Traditional FMCG wholesalers demand 90-120 day payment cycles that strain working capital for ceramic filter specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Gravity-Based Water Purifier Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Purifiers, Ceramic Filters, UV Filters, Multi-Stage Filters Application: Household Use, Educational Institutions, Community Centers, NGO Projects Distribution Channel: Retail Stores, E-Commerce, Wholesale Distributors, Direct Sales End User: Residential Customers, Schools, Small Businesses, Organizations |
| Companies Covered | Advance Product (Semangat Sejahtera Bersama, PT), Culligan Indonesia, Kent RO Systems Ltd., Nazava Water Filters (Pt Holland), PT Toray International Indonesia, PT Coway International Indonesia, PT Unilever Indonesia Tbk, Toclas Corporation, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Gravity-Based Water Purifier Market Strategic Shifts & Innovations
Filtration media engineering and procurement channel restructuring are compressing product lifecycles and rewiring how Indonesian households access certified water treatment. These shifts favor suppliers with flexible manufacturing footprints and direct community relationships.
Silver-impregnated ceramic formulations are collapsing the performance gap between passive gravity systems and pressurized alternatives. Rural health clinics and boarding schools in Central Java are adopting these units at replacement rates of 18-24 months. The technology is collapsing price resistance in institutional segments previously captive to electric UV systems.
SNI 19-6728 technical specifications for household water filters are tightening allowable lead and cadmium leach rates from ceramic media. Local assemblers in Tangerang and Surabaya are requalifying supply chains to maintain marking eligibility. The standard revision most affects basic single-stage units targeting price-sensitive rural households in East Java.
Village cooperative bulk purchasing is displacing individual household transactions in Kalimantan and Sulawesi. Water user associations aggregate orders of 50-200 units, negotiating directly with manufacturers and bypassing district-level retailers. This channel shift concentrates volume with suppliers maintaining field sales teams in Makassar, Samarinda, and Manado.
Indonesia Gravity-Based Water Purifier Market Segmentation
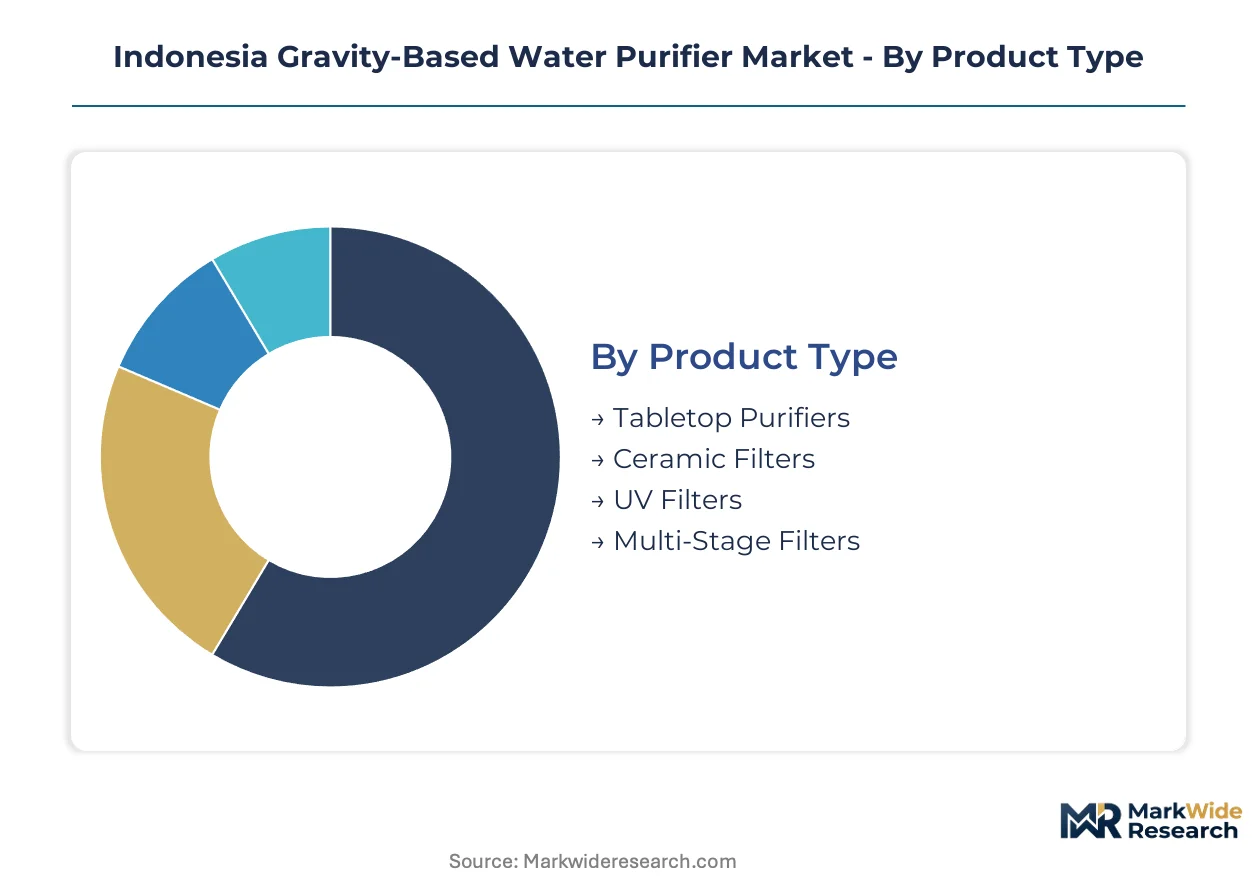
Gravity-based water purifier segmentation in Indonesia reflects infrastructure asymmetry across the archipelago. Product configurations and procurement channels diverge sharply between Java's electrified urban cores and Eastern Indonesia's off-grid communities.
Product Type:
Filtration technology selection tracks electricity availability and source water contamination profiles across Indonesian households and institutions.
- Tabletop Purifiers:Compact plastic housings with single ceramic or carbon cartridges dominate urban apartment dwellers in Jakarta and Surabaya. These units address space constraints in dense settlements while meeting SNI bacteriological standards without plumbing modifications.
- Ceramic Filters:Silver-impregnated ceramic candles with pore sizes of 0.2-0.5 microns capture bacterial and protozoan pathogens in rural Java and Sumatra. Demand concentrates in peri-urban districts where shallow well contamination from agricultural runoff drives household treatment adoption.
- UV Filters:Battery-powered ultraviolet sterilization add-ons extend ceramic filtration in Eastern Indonesia health clinics and boarding schools. These hybrid configurations command premium positioning where electricity is intermittent but bacterial load is high.
- Multi-Stage Filters:Combined ceramic-activated carbon-sediment housings address heavy metal and chemical contamination in industrial zones of Banten and West Java. Established volume favors ceramic filters; emerging adoption favors multi-stage configurations.
Established volume favors ceramic filters; emerging adoption favors multi-stage configurations.
Application:
Institutional procurement patterns split between government-funded rural programs and household self-provisioning across Indonesia's development gradient.
- Household Use:Individual family units in Central Java and East Java purchase 2-5 liter capacity units through retail and cooperative channels. These transactions represent the baseline volume anchor for domestic assemblers.
- Educational Institutions:Boarding schools and madrasahs in Yogyakarta and East Java deploy 20-50 liter community units with institutional SNI certification. Ministry of Education procurement guidelines now mandate certified filtration for school feeding programs.
- Community Centers:Village health posts and prayer halls in Sulawesi and Kalimantan aggregate demand through water user associations. Bulk purchasing of 10-20 unit lots bypasses traditional distributor markups.
- NGO Projects:Development organization deployment across Papua, Maluku, and Nusa Tenggara is climbing the fastest. Safe water program scale-up by international and local NGOs creates volume anchors for ceramic filter specialists with field service capacity.
Household use anchors current revenue; NGO projects are expanding most quickly.
Distribution Channel:
Channel selection reflects working capital constraints and geographic reach requirements across Indonesia's fragmented retail landscape.
- Retail Stores:Traditional FMCG wholesalers in Java's district capitals stock entry-level units with 90-120 day payment terms. These channels strain ceramic filter specialists lacking Unilever-scale balance sheets.
- E-Commerce:Tokopedia and Shopee platforms capture urban millennial demand in Jakarta, Bandung, and Medan. Logistics integration with third-party couriers enables next-day delivery of replacement cartridges.
- Wholesale Distributors:Regional aggregators in Makassar, Samarinda, and Manado supply Eastern Indonesia retailers. These intermediaries concentrate procurement volume for manufacturers maintaining field sales teams.
- Direct Sales:Manufacturer field representatives negotiate village cooperative orders in Kalimantan and Sulawesi. This channel eliminates distributor margins but requires localized technician training networks.
Retail stores hold established volume; direct sales channels are gaining share fastest in Eastern Indonesia.
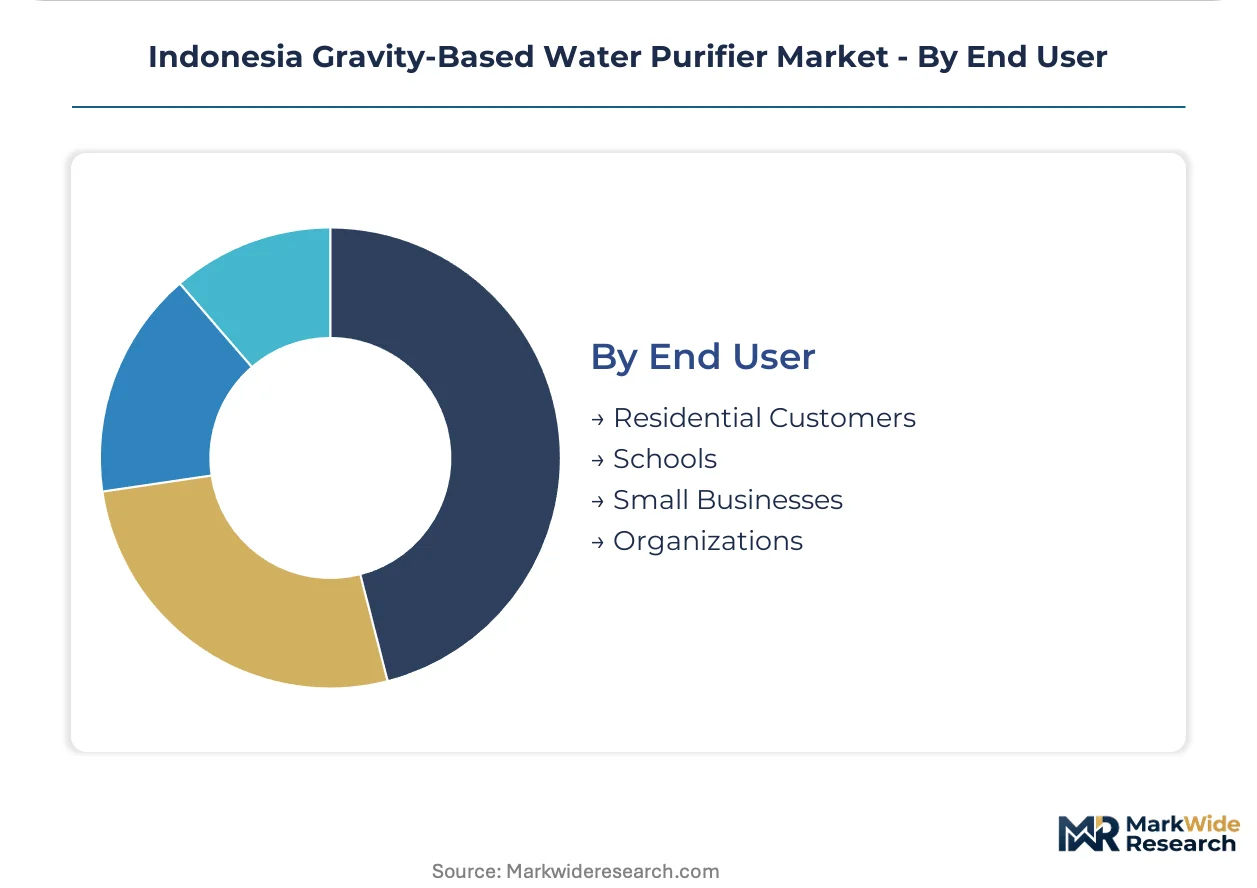
End User:
Customer type determines unit specification, certification tier, and service requirements across Indonesia's water treatment market.
- Residential Customers:Individual households in Java's peri-urban zones prioritize SNI-certified units with visible ceramic cartridges. Price sensitivity limits uptake of multi-stage configurations in this segment.
- Schools:Public and private educational institutions in Central Java and East Java require institutional-grade certification and maintenance contracts. Ministry of Health inspections drive compliance investment.
- Small Businesses:Warung food vendors and small clinics in Sumatra urban centers need compact, portable units with rapid cartridge replacement. These users balance cost against customer-facing hygiene standards.
- Organizations:Corporate CSR programs and religious foundations purchase bulk volumes for community distribution. Tender participation requires SNI marking and district-level procurement registration.
Residential customers dominate unit volume; organizational procurement shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Java's electrified urban corridors while Eastern Indonesia's procurement channels operate on thinner margins. Sumatra's hinterland markets command intermediate premiums reflecting logistics complexity. Sub-national program decentralization is redistributing volume anchors across the archipelago.
Java
Peri-urban households in Banten and West Java face heavy metal contamination in shallow aquifers, driving multi-stage filter adoption. Ministry of Health drinking water regulations mandate SNI certification for institutional procurement, tightening supplier qualification. Surabaya and Tangerang host domestic assembly clusters where local producers requalify supply chains to meet revised SNI 19-6728 leach-rate standards.
Sumatra
Aceh, North Sumatra, and Riau provinces show household treatment underpenetration above 60 percent with agricultural runoff contaminating shallow wells. Pamsimas rural water programs channel district-level budget authority toward certified suppliers, bypassing Jakarta-centric procurement. Medan anchors wholesale distribution networks serving the island's western corridor with improving road access enabling direct-to-community penetration.
Sulawesi
Village cooperative bulk purchasing displaces individual transactions in Kalimantan and Sulawesi as water user associations aggregate orders. Ministry of Education procurement guidelines now mandate certified filtration for school feeding programs, institutionalizing demand. Makassar concentrates regional procurement volume for manufacturers maintaining field sales teams and technician training networks.
Kalimantan
Community centers and village health posts aggregate demand through water user associations negotiating directly with manufacturers. District-level tender access under decentralized rural water programs opens procurement beyond traditional distributor channels. Samarinda hosts wholesale aggregators supplying Eastern Indonesia retailers with SNI-marked units.
Eastern Indonesia
Development organization scaling of safe water programs across Papua, Maluku, and Nusa Tenggara creates institutional volume anchors for ceramic filter specialists. NGO procurement represents the fastest-growing structural channel as field service capacity determines supplier selection. Manado and Jayapura concentrate field technician deployment despite thin maintenance training infrastructure.
Indonesia Gravity-Based Water Purifier Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in media and cartridge supply. The vendor base stratifies between FMCG-scale balance sheets capable of sustaining 90-120 day wholesale credit cycles and ceramic filter specialists dependent on working capital efficiency. Three archetypes dominate: multinational consumer goods platforms with existing retail footprints, dedicated water treatment specialists with field service networks, and regional assemblers leveraging local procurement registration. Competitive moves concentrate on direct-to-community channel expansion and hybrid media configuration development to capture premium positioning.
Among Indonesia-based operations, PT Unilever Indonesia Tbk and Nazava Water Filters (Pt Holland) exemplify divergent scale-specialist positioning, while Culligan Indonesia occupies the service-oriented direct sales tier. PT Unilever Indonesia Tbk represents the FMCG-platform archetype with nationwide shelf presence through existing retail infrastructure. Nazava Water Filters (Pt Holland) anchors the ceramic-specialist segment with rural penetration capabilities. Culligan Indonesia sits within the premium urban-direct channel, competing through service contracts rather than retail velocity. These three patterns illustrate how working capital depth, field technician networks, and certification compliance interact to determine viable positioning across Java's urban cores and Eastern Indonesia's institutional procurement channels.
| Leading Market Players |
|---|
| Advance Product (Semangat Sejahtera Bersama, PT) |
| Culligan Indonesia |
| Kent RO Systems Ltd. |
| Nazava Water Filters (Pt Holland) |
| PT Toray International Indonesia |
| PT Coway International Indonesia |
| PT Unilever Indonesia Tbk |
| Toclas Corporation |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
Tangerang and Surabaya assembly clusters anchor domestic production capacity, with kiln-equipped facilities commanding pricing power over ceramic cartridge configurations while import-dependent assemblers absorb freight volatility in their landed cost structures.
Pricing Analysis
Configured-to-order hybrid media systems command 40-60% premiums over standard ceramic-only units. Three-tier pricing structure across premium, standard, and economy levels stratifies by SNI certification tier and after-sales service bundling. Cost compression in entry-level segments is intensifying because village cooperative bulk purchasing aggregates demand and squeezes distributor markups. Households in peri-urban Java show highest price sensitivity, while institutional buyers in Eastern Indonesia prioritize field service availability over unit cost.
Supply Chain Analysis
Upstream ceramic media feeds from Chinese and Indian kiln operators, with activated carbon sourcing from coconut shell processors in Indonesia and the Philippines. Domestic assemblers draw from imported ceramic candles, plastic housings from local injection molders, and silver nitrate for impregnation. Single-source vulnerability concentrates in precision ceramic manufacturing where Indonesian producers lack technical capacity. Distribution runs through regional wholesale aggregators in Makassar and Samarinda serving Eastern Indonesia retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where SNI certification requirements create regulatory entrenchment that locks out uncertified imports and consolidates volume around compliant domestic assemblers.
For Market Incumbents: Harden certification compliance investment to exploit Ministry of Industry testing protocol timelines that extend rival commercialization cycles. Deepen field technician training networks in Eastern Indonesia to capture NGO procurement volume anchors. Vertical integration into activated carbon processing from local coconut shell supply secures margin against import-dependent competitors.
For New Entrants and Emerging Players: Establish a beachhead in Sumatra's hinterland provinces where household treatment underpenetration exceeds 60% and Pamsimas decentralization opens tender access. Aceh and North Sumatra present the most penetrable geography with improving road access enabling direct-to-community distribution bypassing legacy FMCG wholesalers. Lead with hybrid ceramic-carbon configurations targeting agricultural runoff contamination in peri-urban districts.
For Investors and Strategic Acquirers: Long-term, this sits as a rural infrastructure play because electrification gaps and piped water asymmetry lock gravity-based filtration into the dominant treatment modality across the archipelago. Acquisition targets should field ceramic specialists with established SNI marking and deployed technician networks in Eastern Indonesia. Watch NGO safe water program scale-up rates as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Media Configuration Development | Silver-impregnated ceramic-activated carbon convergence captures 40-60% price premiums in peri-urban Java. |
| Field Technician Network Expansion | Localized maintenance capacity in Papua and Maluku determines NGO procurement supplier selection. |
| SNI Certification Requalification | Revised SNI 19-6728 leach-rate standards filter market access for Tangerang and Surabaya assemblers. |
| Village Cooperative Direct Sales | Bulk purchasing aggregation in Kalimantan and Sulawesi bypasses 90-120 day distributor credit cycles. |
| Activated Carbon Backward Integration | Coconut shell processing capture secures margin against imported carbon media freight volatility. |
Research Approach
A spread of perspectives from ceramic filter manufacturers, rural water program procurement officers, Ministry of Health regulatory leads, and village cooperative administrators converged on the working assumptions. Primary field engagement combined with secondary validation from SNI technical specifications, Pamsimas program disbursement records, and customs import data for ceramic media. Bottom-up unit shipment estimates triangulated against top-down household treatment penetration rates across Indonesian provinces.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by filtration technology type, application tier, distribution channel, and end-user archetype. CAGRs derived from province-level adoption curves weighted by population density and groundwater contamination clustering. Forecast inputs incorporated rural electrification timelines and sub-national procurement decentralization under Pamsimas implementation.
Sensitivities concentrate around SNI certification timeline extensions, ceramic cartridge import tariff adjustments, and NGO program funding volatility. Cross-checking against Ministry of Health household treatment device registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
Malaysia Water Purifier Market