
 India Desalination Systems Market | 2026-2036
India Desalination Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Desalination Systems Market Foresight
The Jal Jeevan Mission is repositioning desalination from niche coastal infrastructure to mainstream municipal planning across peninsular India. Thermax Ltd leverages its captive engineering base to dominate EPC contracts for thermal desalination plants. Aquatech International LLC anchors its India presence through membrane technology leadership in industrial zero-liquid-discharge integrations.
Desalination systems remove dissolved salts and minerals from seawater or brackish sources through pressure-driven membrane separation or thermal distillation processes, typically achieving total dissolved solids below 500 ppm for potable compliance. Reverse osmosis leads installed capacity due to lower energy intensity versus thermal alternatives, while multi-effect distillation retains share where waste heat from power generation creates cost advantages. Municipal water supply commands the largest application share as Chennai, Mumbai, and Gujarat cities face acute freshwater stress.
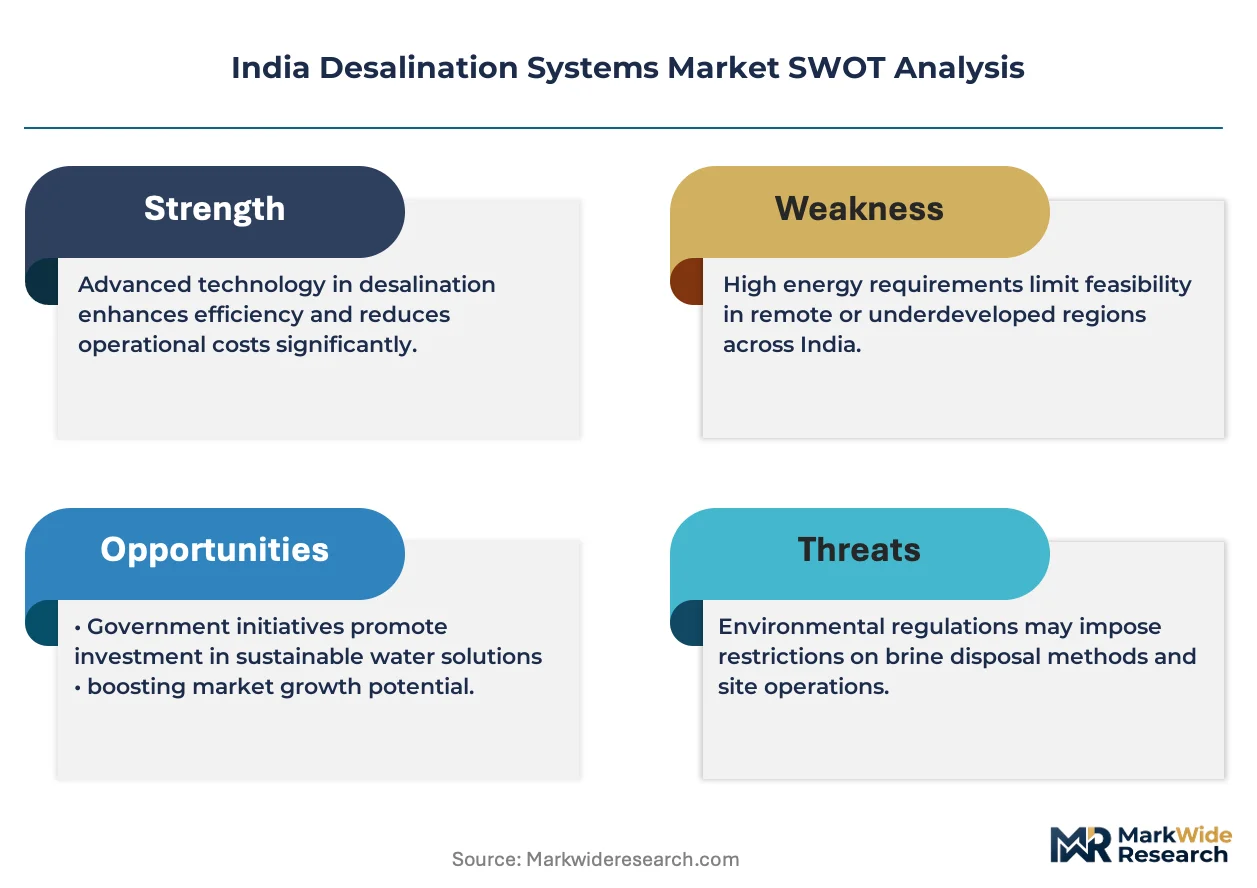
BIS certification requirements for membrane modules and CEA guidelines on power-plant water consumption shape product standards and procurement eligibility. The PLI scheme for advanced chemistry cell manufacturing indirectly amplifies industrial water demand as battery gigafactories locate in water-scarce states. Stakeholders must monitor state-level tariff rationalization and coastal regulation zone amendments that could alter project economics for large-scale installations.
Market Dynamics
Membrane technology cost compression is collapsing the historical premium between reverse osmosis and thermal distillation, forcing EPC contractors to rebid entire project portfolios around energy-recovery device economics rather than fuel linkage assumptions.
Growth Catalysts
- Jal Jeevan Mission:The national rural water supply program mandates piped water for all households, redirecting state budgets toward coastal desalination as inland sources fail. Municipal corporations in Tamil Nadu and Gujarat now prioritize membrane plants in their capital expenditure plans.
- Petrochemical corridor expansion:Refineries along the Gujarat coast require ultrapure process water at volumes exceeding local freshwater availability. Zero-liquid-discharge mandates from the Central Electricity Authority intensify brine management investments.
- CEA thermal power guidelines:The regulator's water consumption limits for coastal plants create captive demand for multi-effect distillation units sited adjacent to generation facilities.
Market Restraints
- Membrane import dependence:Polyamide thin-film composite modules rely on Korean and Japanese suppliers, exposing project timelines to shipping volatility and currency fluctuation.
- Brine disposal constraints:Coastal Regulation Zone amendments restrict offshore discharge pipe routing, forcing costly evaporation pond construction or tanker transport to deep-water zones.
- Power tariff unpredictability:State electricity boards revise industrial rates without notice, destroying operating cost models for energy-intensive reverse osmosis facilities.
Strategic Opportunities
- Battery gigafactory water demand:The PLI scheme for advanced chemistry cells concentrates manufacturing in water-scarce Maharashtra and Gujarat, creating industrial desalination demand unrelated to traditional coastal users.
- Hybrid thermal-membrane configurations:Waste heat integration from refineries enables thermal distillation pre-treatment followed by reverse osmosis polishing, reducing specific energy consumption below standalone membrane benchmarks.
- Smart city water infrastructure:AMRUT 2.0 funding for urban rejuvenation includes real-time monitoring and automated chemical dosing systems that optimize membrane cleaning cycles.
Industry Challenges
- Skilled operator scarcity:Remote coastal plants struggle to retain certified membrane technicians capable of troubleshooting high-pressure pump failures and membrane fouling diagnostics.
- BIS certification timelines:Module testing protocols at the Bureau of Indian Standards facilities extend procurement lead times by four to six months, delaying project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Desalination Systems Market |
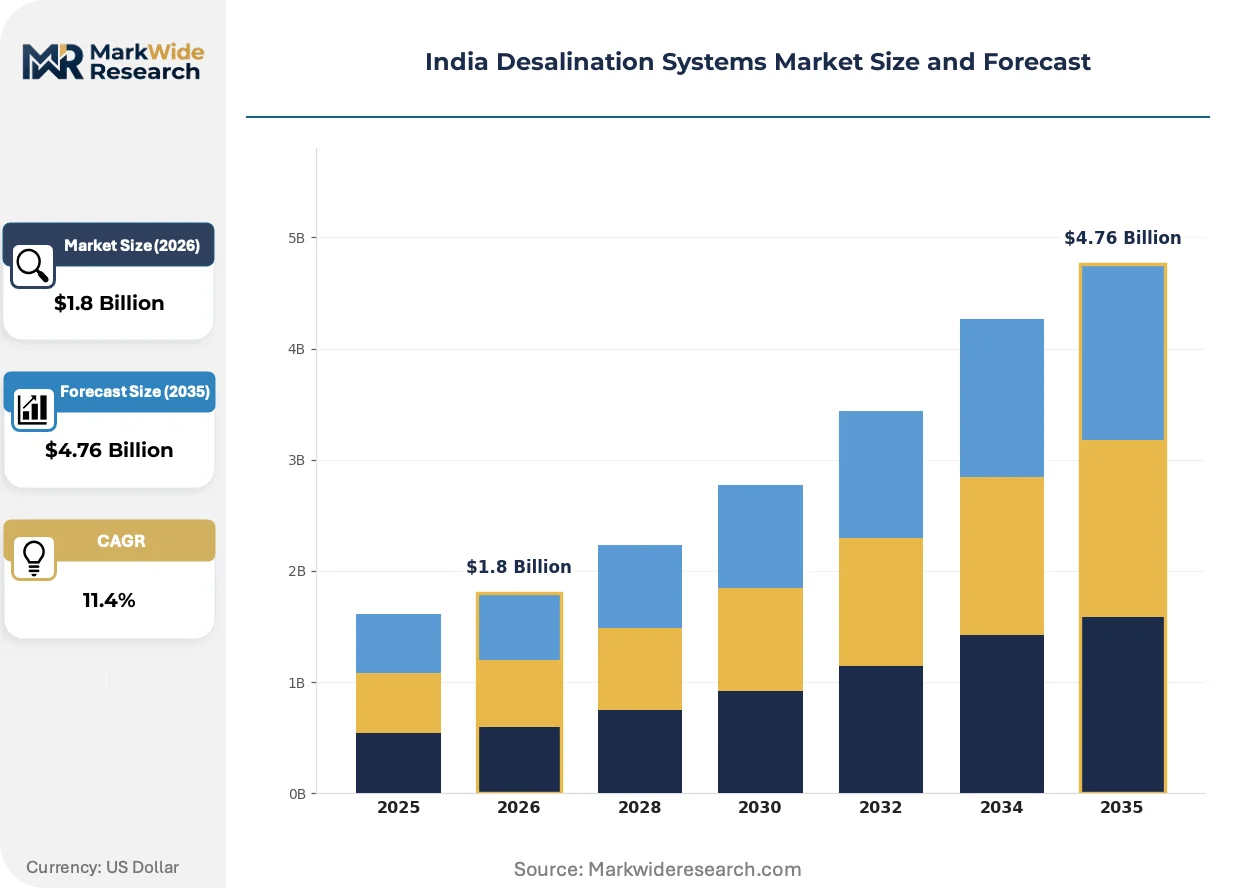
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reverse Osmosis, Multi-Effect Distillation, Multi-Stage Flash, Electrodialysis Application: Municipal Water Supply, Industrial Process Water, Agriculture Irrigation, Power Generation End User: Government, Private Sector, NGOs, Energy Companies Installation: Onshore, Offshore, Mobile Units, Fixed Facilities |
| Companies Covered | Aquatech International LLC, Thermax Ltd, SUEZ SA, Evoqua Water Technologies, DuPont, Veolia Environnement, IDE Technologies Ltd, Acciona SA, WABAG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Desalination Systems Market Shifts & Advancements
Energy recovery device integration and digital twin deployment are compressing operating expenditure spreads between established membrane suppliers and new market entrants.
Pressure exchanger technology is unifying the previously separate equipment categories of high-pressure pumps and energy recovery devices into single-skid packages. Municipal water authorities in Gujarat are specifying these integrated units for new 100 MLD plants. The technology is unifying vendor qualification criteria around hydraulic efficiency guarantees rather than component-level specifications.
The Central Electricity Authority's 2023 notification on water consumption norms for thermal power plants mandates specific water use limits for coastal facilities. Plants exceeding these thresholds face generation penalty clauses. Coastal units in Tamil Nadu are responding by retrofitting multi-effect distillation capacity to meet compliance deadlines.
Engineering-procurement-construction contracts now bundle fifteen-year operations and maintenance obligations with initial capital deployment. Industrial buyers in the petrochemical sector are accepting higher upfront capex in exchange of guaranteed output water quality and energy consumption ceilings. This model is most visible in the Dahej and Hazira industrial corridors where refinery operators lack in-house water treatment expertise.
India Desalination Systems Market Segmentation
Desalination procurement patterns in India diverge sharply across technology maturity, application water quality specifications, and buyer risk tolerance. Understanding these fault lines clarifies why membrane suppliers and thermal EPC contractors rarely compete for the same contracts.
Technology:
Cost per cubic meter and energy access determine technology selection across Gujarat and Tamil Nadu project pipelines.
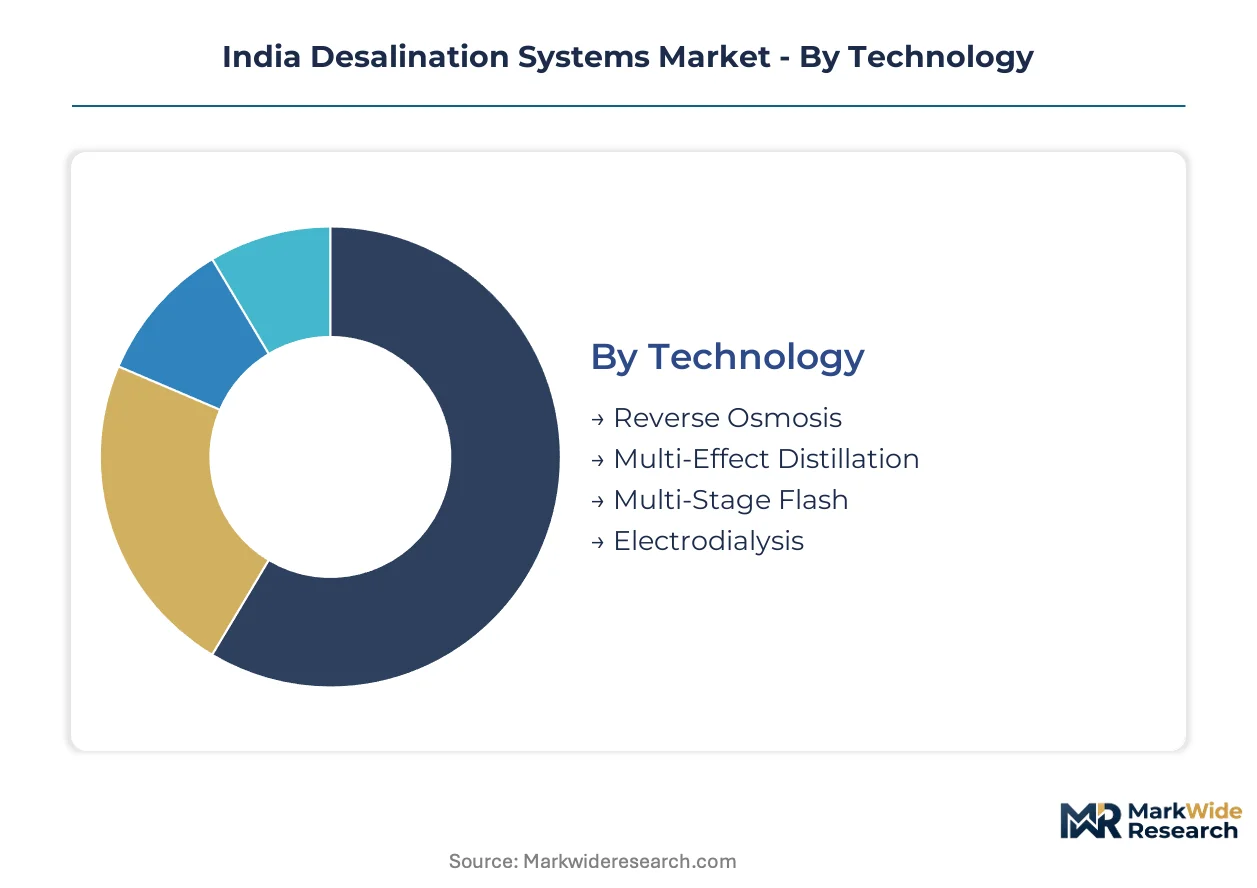
- Reverse Osmosis:Pressure-driven membrane separation through polyamide thin-film composite modules achieves potable-grade output below 500 ppm total dissolved solids. Municipal corporations in Chennai and Surat specify RO for new 100 MLD plants where grid power reliability has improved; energy recovery device integration now compresses operating costs toward thermal parity.
- Multi-Effect Distillation:Vacuum-driven thermal distillation through successive evaporation-condensation stages produces ultrapure distillate using waste heat from adjacent power generation. CEA water consumption mandates for coastal thermal plants are accelerating MED retrofits in Tamil Nadu where captive heat sources eliminate fuel cost volatility.
- Multi-Stage Flash:Flash evaporation across multiple pressure chambers delivers large-volume output but requires substantial thermal energy input; limited to refinery-integrated installations in Gujarat with assured steam supply.
- Electrodialysis:Ion-selective membrane electrochemical separation targets brackish water with moderate salinity; deployed in Gujarat agricultural zones where groundwater TDS ranges between 1,500-3,000 ppm and energy costs prohibit full reverse osmosis.
Reverse osmosis leads volumes today; multi-effect distillation is gaining share fastest.
Application:
Water quality specifications and buyer procurement authority create distinct competitive arenas.
- Municipal Water Supply:Piped drinking water mandates under Jal Jeevan Mission are redirecting state budgets toward coastal desalination as inland sources fail. Tamil Nadu and Gujarat municipal corporations now prioritize membrane plants in capital expenditure plans; BIS certification requirements for potable compliance extend procurement timelines.
- Industrial Process Water:Refineries and petrochemical corridors along the Dahej and Hazira belts require ultrapure process water exceeding local freshwater availability. Zero-liquid-discharge mandates from CEA intensify brine management investments; EPC contracts bundle fifteen-year O&M obligations with initial deployment.
- Agriculture Irrigation:Brackish water desalination for greenhouse horticulture and export-oriented crop zones; limited penetration due to price-sensitive farmer cooperatives and erratic power supply in rural Maharashtra and Karnataka.
- Power Generation:Boiler feedwater and cooling tower makeup for coastal thermal plants; CEA notification on specific water use limits creates captive demand for multi-effect distillation retrofits.
Municipal water supply dominates installed base; industrial process water is climbing the fastest.
End User:
Procurement sophistication and payment security separate viable contract opportunities from stranded assets.
- Government:State water boards and municipal corporations with sovereign payment guarantees but bureaucratic tendering cycles; Jal Jeevan Mission funding flows through this channel for rural piped water schemes.
- Private Sector:Refinery operators and petrochemical majors with in-house engineering capabilities accepting higher upfront capex for guaranteed output quality; prefer build-own-operate models over pure EPC.
- NGOs:Community-scale installations in drought-affected districts; limited to donor-funded pilot projects with constrained operational sustainability.
- Energy Companies:Thermal power generators responding to CEA water consumption norms; captive desalination adjacent to generation facilities with waste heat integration.
Government contracts anchor current revenue; private sector engagements are expanding most quickly.
Installation:
Site constraints and capital deployment flexibility shape EPC bidding strategies.
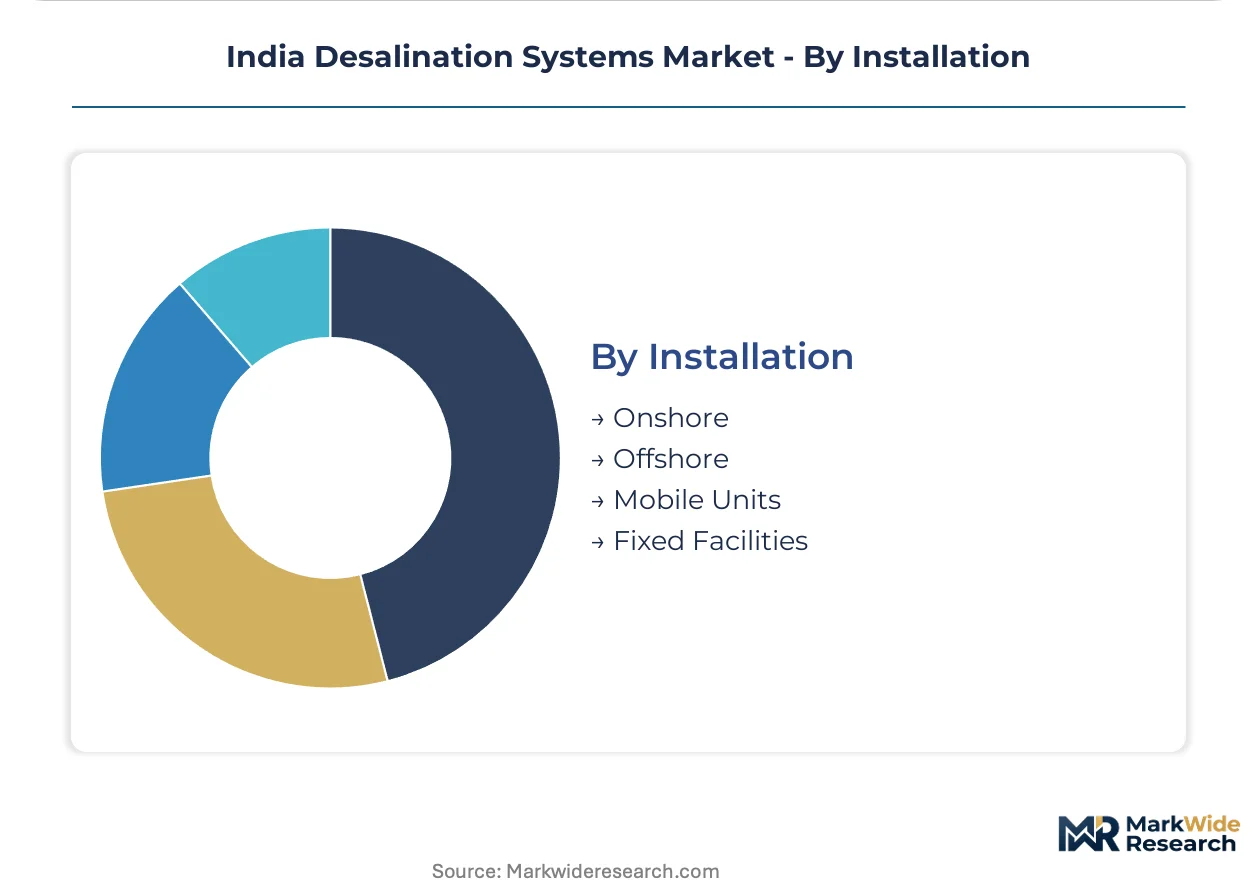
- Onshore:Permanent coastal installations with dedicated intake structures and brine discharge pipelines; Coastal Regulation Zone amendments restrict offshore pipe routing and extend permitting timelines.
- Offshore:Platform-mounted units for island territories and remote industrial facilities; limited to Andaman and Nicobar administration projects and select refinery offshore platforms.
- Mobile Units:Containerized membrane skids for emergency drought response and temporary industrial commissioning; Gujarat Disaster Management Authority maintains fleet for seasonal deployment.
- Fixed Facilities:Large-scale permanent infrastructure with integrated pretreatment and post-treatment trains; standard for municipal 100 MLD plants and refinery process water systems.
Fixed facilities command current capacity; mobile units are gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled membrane technicians and thermal process engineers concentrate in Gujarat and Tamil Nadu, anchoring India's desalination deployment capacity. State water boards leverage this talent pool to execute municipal scale-ups. Coastal industrial corridors compete for the same engineering resources.
Gujarat
Dahej and Hazira petrochemical corridors drive ultrapure process water demand exceeding local freshwater availability. CEA guidelines on thermal power plant water consumption mandate captive desalination retrofits. The state water board prioritizes membrane plants in Surat municipal expansion plans.
Tamil Nadu
Chennai municipal corporation faces acute freshwater stress from depleted aquifers and monsoon variability. Jal Jeevan Mission funding redirects state budgets toward coastal membrane infrastructure. Coastal thermal plants in Tuticorin retrofit multi-effect distillation to meet CEA compliance deadlines.
Maharashtra
Battery gigafactories under the PLI scheme for advanced chemistry cells concentrate manufacturing in water-scarce Pune-Nashik corridors. Industrial buyers accept bundled fifteen-year O&M contracts with guaranteed output quality. Refinery clusters in Mumbai generate captive demand for hybrid thermal-membrane configurations.
Andhra Pradesh
Visakhapatnam industrial belt requires process water for steel and petrochemical operations. State-level mandates for coastal city water security accelerate technology adoption. The Vishakhapatnam Port Trust explores offshore platform-mounted units for island territory supply.
Karnataka
Bengaluru's technology manufacturing ecosystem strains inland water resources, creating indirect coastal desalination demand through inter-basin transfer schemes. BIS certification requirements for membrane modules extend procurement timelines for state water infrastructure. Mangalore refinery operations anchor thermal distillation capacity on the west coast.
India Desalination Systems Market Competitive Landscape
Capital-heavy EPC contractors compete with asset-light technology licensors for contract control. The vendor base splits between integrated engineering groups bidding turnkey installations and specialized membrane suppliers providing core process packages. Three archetypes dominate: domestic conglomerates with captive fabrication, international technology licensors with local joint ventures, and regional water utilities with in-house project development capability. Competitive moves center on bundling long-term O&M obligations with initial capital deployment and securing waste heat integration partnerships with adjacent power or refinery operators.
Among domestic integrated players, Thermax Ltd anchors the thermal EPC segment through its captive engineering base. Aquatech International LLC exemplifies the international technology licensor archetype with membrane-focused positioning. SUEZ SA and Veolia Environnement occupy positions as global water majors adapting European technology platforms to Indian coastal conditions.
| Leading Market Players |
|---|
| Aquatech International LLC |
| Thermax Ltd |
| SUEZ SA |
| Evoqua Water Technologies |
| DuPont |
| Veolia Environnement |
| IDE Technologies Ltd |
| Acciona SA |
| WABAG |
| Others |
Supply & Pricing Matrix
Pressure exchanger unification of high-pressure pumps and energy recovery devices is collapsing the capital cost gap between reverse osmosis and thermal distillation while simultaneously concentrating procurement power around integrated skid suppliers. This technology transition forces EPC contractors to rebid entire project portfolios around hydraulic efficiency guarantees rather than component-level specifications, reshaping both margin structures and vendor qualification criteria across Gujarat and Tamil Nadu.
Pricing Analysis
Project-based EPC contracting with bundled fifteen-year O&M obligations dominates commercial structures, with price differentiation driven by BIS certification tier and energy consumption guarantee levels. Cost compression in membrane modules is intensifying because Korean and Japanese suppliers face currency volatility, eroding margins at the standard tier while premium thermal-membrane hybrid configurations retain pricing power. Municipal water boards exhibit highest price sensitivity due to Jal Jeevan Mission budget constraints, whereas petrochemical majors prioritize guaranteed output quality over upfront capex minimization.
Supply Chain Analysis
Single-source vulnerability sits with polyamide thin-film composite membrane production concentrated in South Korea and Japan, with high-pressure pump castings drawing from Germany and China. Raw material dependencies span specialized polymer resins, precision ceramic components for energy recovery devices, and corrosion-resistant alloys for thermal distillation vessels. Tariff exposure on Korean membrane imports creates procurement timeline risk as DGFT duty adjustments ripple through project economics. Distribution runs through EPC contractors with captive fabrication facilities in Gujarat, who integrate imported membrane packages into turnkey installations for state water boards and industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India desalination market compounds steadily as aquifer depletion across peninsular India forces permanent structural demand for coastal freshwater infrastructure. Jal Jeevan Mission funding commitments provide visible revenue visibility for EPC contractors and technology suppliers alike.
For Market Incumbents: Deploy waste heat integration partnerships as the primary defensive lever. Thermal EPC contractors should lock exclusive arrangements with coastal power generators and refineries in Gujarat and Tamil Nadu to secure captive heat sources that new membrane-only entrants cannot replicate. Incumbents must simultaneously invest in BIS certification pre-positioning to extend procurement lead time advantages against emerging Korean membrane suppliers seeking direct Indian market access. For New Entrants and Emerging Players: State water utilities with deteriorating fiscal positions represent the most penetrable channel partner type for build-own-operate contract structures. New entrants should target Maharashtra's battery gigafactory corridor, where PLI scheme manufacturing concentration creates industrial desalination demand unrelated to traditional coastal user archetypes. A specialized zero-liquid-discharge integration capability enables differentiation from established municipal-focused competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional EPC contractors with captive fabrication facilities because state-level procurement rules favor bidders with demonstrated local project execution records. The long-term viability window centers on fifteen-year O&M contract annuity streams rather than capital deployment cyclicality. Watch CEA notification enforcement intensity as the inflection signal—accelerated compliance deadlines for thermal plant water consumption limits would trigger immediate MED retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Waste Heat Integration Partnership | Captive steam access from Tuticorin thermal plants eliminates fuel cost volatility for MED operators. |
| Membrane Module Localization | Domestic polyamide thin-film composite production reduces BIS certification timelines and import duty exposure. |
| Hybrid Thermal-Membrane Configuration | Dahej refinery operators achieve specific energy consumption below standalone RO benchmarks through staged distillation. |
| Fifteen-Year O&M Bundling | Industrial buyers in Hazira corridor accept higher upfront capex for guaranteed output quality ceilings. |
| Mobile Unit Fleet Expansion | Gujarat Disaster Management Authority deployment protocols create recurring revenue for containerized skid suppliers. |
Research Methodology
Bottom-up municipal and industrial capacity modeling reconciled against top-down EPC contractor order book tracking forms the analytical core of this study. Primary interviews with state water board procurement officers, thermal power plant engineering heads, petrochemical facility managers, membrane supplier technical directors, and BIS certification laboratory staff were cross-validated against secondary sources including CEA water consumption notifications, Coastal Regulation Zone amendment filings, PLI scheme administrative guidelines, and state-level tender documentation from Tamil Nadu and Gujarat.
Input-output matrices map technology adoption across reverse osmosis, multi-effect distillation, multi-stage flash, and electrodialysis configurations against end-use segments and regional regulatory clusters throughout the projection horizon. Segmentation dimensions cover technology maturity, application water quality specifications, buyer procurement authority, and site installation constraints. CAGRs were derived from installed capacity build-out trajectories, with forecast inputs incorporating Jal Jeevan Mission funding allocation patterns and CEA compliance deadline schedules.
Revisions become necessary when Coastal Regulation Zone amendments restrict offshore discharge routing, PLI scheme battery manufacturing locational decisions shift away from water-scarce states, or state electricity board tariff revisions alter operating cost models for energy-intensive facilities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Plant Based Water Filter Market