
 Point of Entry Water Treatment Systems Market | 2026-2036
Point of Entry Water Treatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Entry Water Treatment Systems Market Intelligence
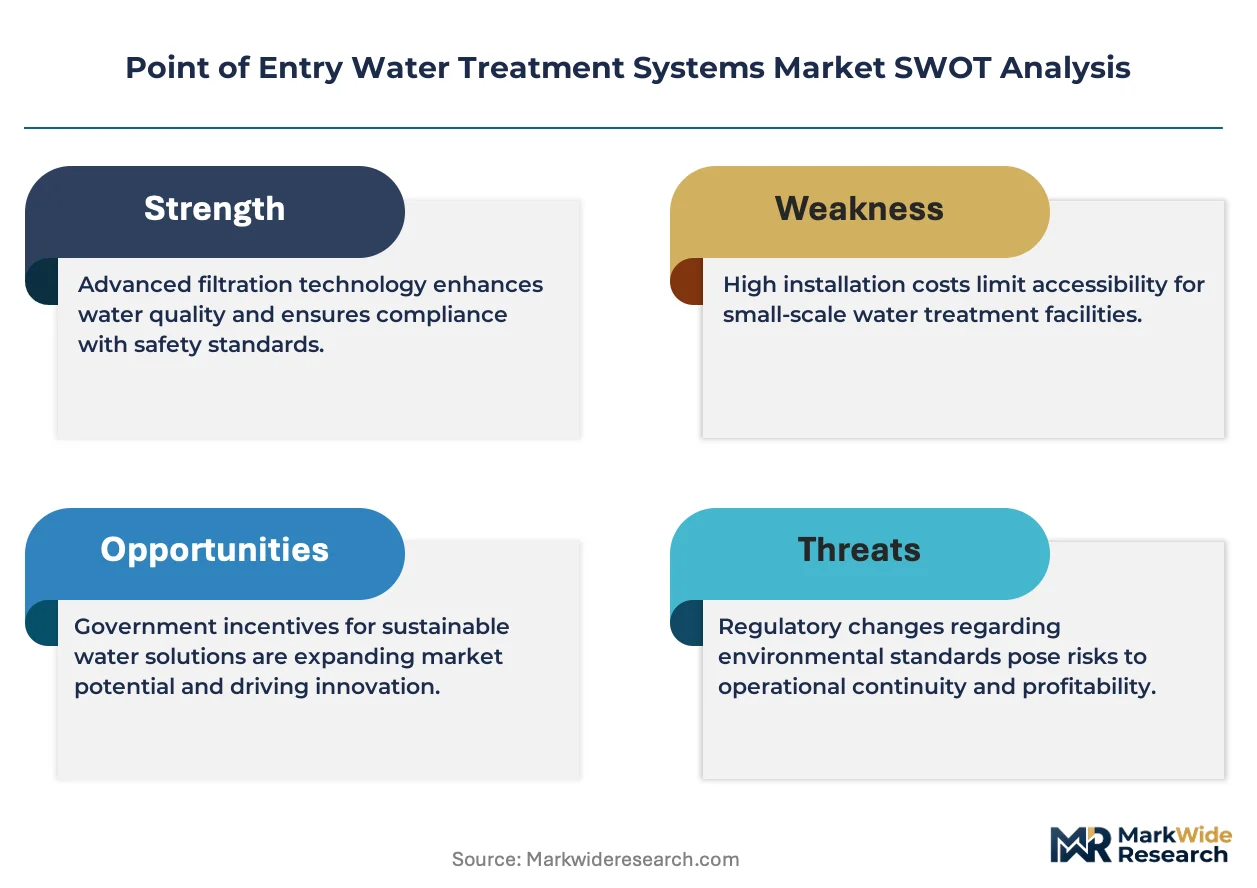
The global push towards meeting WHO guidelines for drinking-water quality is expanding the addressable market for whole-building treatment solutions, particularly in regions with aging infrastructure. Pentair plc leverages its extensive distribution network to serve both residential and commercial end-users with a diverse product portfolio. A.O. Smith Corporation competes by integrating its water treatment technologies with its established water heater business. 3M Company differentiates through its focus on advanced filtration media and material science innovations.
Point of entry water treatment systems are comprehensive solutions installed where the main water line enters a property. These systems, often incorporating multi-stage processes like sediment filtration followed by UV purification, treat all incoming water for contaminants. Filtration systems and water softeners represent mature categories, especially within the large residential segment. Higher-margin opportunities exist with reverse osmosis units and UV purifiers, which are seeing increased use in commercial and light industrial applications for high-purity water.
Regulations from bodies like the U.S. EPA, Europe's ECHA under REACH, and China's MEE set permissible limits for contaminants, directly influencing system design and performance requirements. NSF/ANSI standards provide third-party certification for material safety and contaminant reduction claims, shaping market access and buyer confidence. Navigating the patchwork of regional standards and certifications remains a critical competency for manufacturers seeking to scale their operations.
Market Dynamics
The market's central dynamic is the tension between rising public and regulatory demands for contaminant removal and the high capital cost of advanced treatment technologies. Stricter limits on emerging contaminants are compelling upgrades from basic filtration to multi-stage systems.
Growth Catalysts
- Stricter Regulations:Frameworks like the EU's Drinking Water Directive, which lowers limits for contaminants like lead and legionella, mandate infrastructure upgrades and expand the market for certified point of entry systems.
- Hospitality Sector Demand:Hotels and restaurants require consistent water quality for guest satisfaction and equipment longevity, driving adoption of commercial-grade softeners, filters, and UV purifiers to protect brand standards.
- Urbanization in Developing Economies:Rapid urban development in countries like India creates concentrated demand for new residential and commercial installations where municipal water quality is inconsistent or under-supplied.
Market Restraints
- High Initial Investment:The significant upfront cost of whole-building reverse osmosis or multi-stage filtration systems remains a primary barrier for individual homeowners and small to medium-sized enterprises.
- Installation Complexity:Retrofitting comprehensive POE systems into older buildings with non-standard plumbing configurations presents significant technical challenges and increases installation costs, deterring adoption.
- Fragmented Certification Landscape:Manufacturers face complexity and added costs navigating a patchwork of regional standards, such as NSF/ANSI in the US and specific GB standards in China, to achieve market access.
Strategic Opportunities
- Light Industrial Applications:Untapped demand exists in light industrial sectors like microelectronics fabrication and biotechnology labs that require high-purity water but fall below the scale of heavy industrial treatment.
- Smart System Integration:Integrating IoT sensors for real-time water quality monitoring and predictive maintenance alerts creates new service-based revenue streams and enhances product value for end-users.
- Latin American Expansion:Markets in Brazil and Mexico, characterized by growing middle-class populations and concerns over municipal water reliability, offer significant greenfield opportunities for residential and commercial systems.
Industry Challenges
- Skilled Technician Scarcity:A shortage of technicians trained to install, service, and troubleshoot integrated systems combining filtration, softening, and UV purification creates service bottlenecks and limits expansion capacity.
- Compliance and Certification Timelines:The lengthy and expensive process of achieving and maintaining certifications like NSF/ANSI for new materials or contaminant reduction claims can delay product launches.
- Legacy Infrastructure Integration:Ensuring compatibility and performance when connecting modern, high-pressure POE systems with aging municipal water lines and internal building plumbing is a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Entry Water Treatment Systems Market |
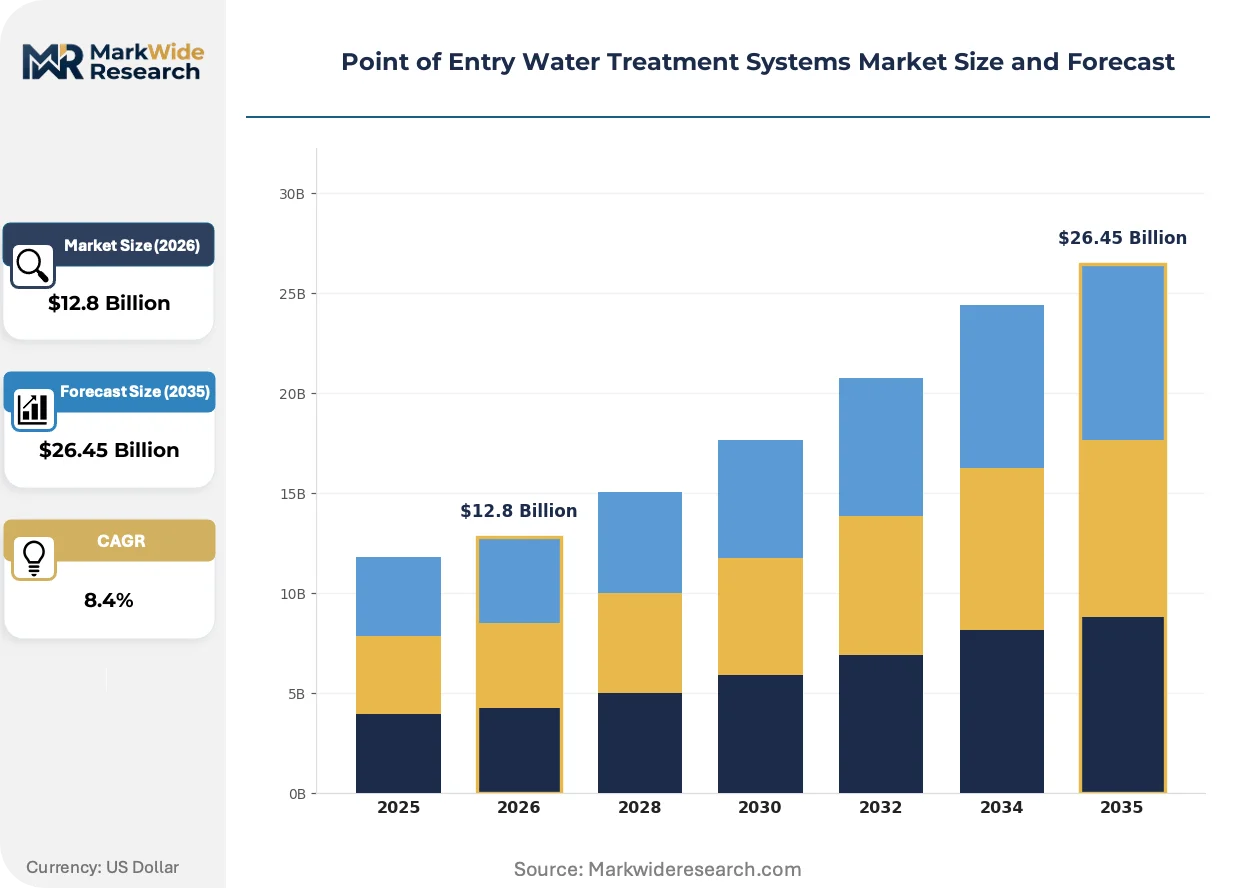
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, UV Purifiers, Reverse Osmosis Units, Softening Systems Technology: Membrane Technology, Ultraviolet Technology, Activated Carbon, Ion Exchange End User: Residential, Commercial, Industrial, Hospitality Application: Drinking Water, Irrigation, Industrial Processing, Aquaculture |
| Companies Covered | A.O. Smith Corporation, Pentair plc, Culligan International Company, 3M Company, DuPont de Nemours Inc., BWT Holding GmbH, Watts Water Technologies Inc., Best Water Technology AG, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Entry Water Treatment Systems Market Strategic Shifts & Innovations
The market is shifting from passive filtration to active, data-driven water quality management. This evolution is driven by material science advancements, new regulatory pressures on specific contaminants, and changing commercial procurement models that prioritize performance and uptime over initial capital cost.
Advanced filtration media, including catalytic carbon and nanotechnology-enhanced polymers, provide targeted removal of specific contaminants like PFAS and pharmaceuticals. Commercial sectors, particularly food and beverage processing, are adopting these specialized materials to meet stringent quality standards. This move toward contaminant-specific treatment is rewriting performance benchmarks beyond basic chlorine and sediment removal.
Heightened regulatory focus from bodies like the U.S. EPA on emerging contaminants is a powerful market force. The establishment of enforceable limits for substances like PFAS compels municipalities, commercial building owners, and homeowners to invest in new treatment technologies. Consequently, systems with third-party certification for PFAS reduction, such as those meeting NSF/ANSI standards, are gaining significant traction.
A transition from outright capital purchase to subscription-based "Water-as-a-Service" models is gaining momentum in the commercial space. This approach replaces large upfront investments with a recurring operational fee covering system installation, consumables, and guaranteed performance. This service-centric model is most prominent within the hospitality and healthcare verticals in North America and Europe.
Point of Entry Water Treatment Systems Market Segmentation
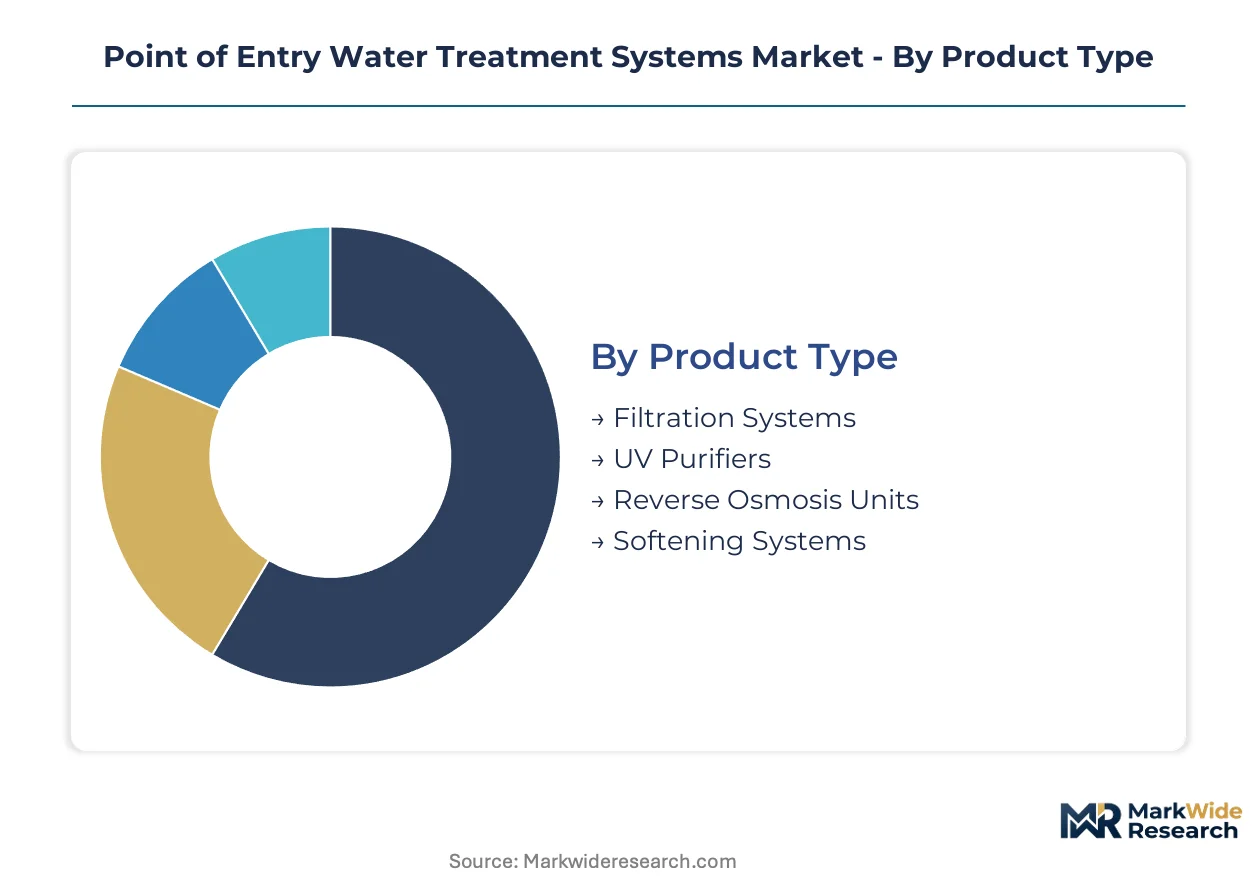
The point of entry water treatment systems market segments across various dimensions, reflecting the diverse needs for water quality improvement and contaminant removal. Understanding these segments is crucial for manufacturers to align product development with specific end-user requirements and regulatory compliance across different regions.
Product Type:
The upgrade and replacement cycle significantly influences demand across various point of entry product types, as older systems are replaced with more advanced solutions addressing new contaminant concerns.
- Reverse Osmosis Units:These systems utilize semi-permeable membranes to remove dissolved solids, salts, and microscopic contaminants, producing high-purity water. Demand concentrates in commercial and light industrial applications in Europe where stringent water quality standards are enforced for specific processes.
- UV Purifiers:UV purifiers employ ultraviolet light to inactivate bacteria, viruses, and other microorganisms without chemicals, ensuring microbiological safety. The hospitality sector in India increasingly adopts these systems to guarantee guest safety and meet local health regulations.
- Filtration Systems:These systems remove suspended solids, sediment, chlorine, and other particulate matter, improving water clarity and taste.
- Softening Systems:Water softeners remove hardness-causing minerals like calcium and magnesium, preventing scale buildup in pipes and appliances.
Filtration Systems sits at the top of the volume ranking, with Reverse Osmosis Units climbing the fastest.
Technology:
Performance drivers and contaminant profiles dictate the selection of specific water treatment technologies within this market, with innovations focusing on efficiency and targeted removal.
- Membrane Technology:This category encompasses microfiltration, ultrafiltration, nanofiltration, and reverse osmosis, providing physical barriers against particulates and dissolved substances. Its advanced capabilities are critical for high-purity water requirements in the US biotechnology industry.
- Ultraviolet Technology:Ultraviolet technology employs germicidal UV lamps to disinfect water by destroying the DNA of pathogens, offering chemical-free sterilization. Commercial laundries and food processing facilities in Germany increasingly rely on UV for pathogen control.
- Activated Carbon:Activated carbon filters effectively adsorb organic compounds, chlorine, odors, and tastes from water, improving palatability.
- Ion Exchange:Ion exchange resins remove specific ions from water, primarily used for softening, demineralization, and selective contaminant removal.
Membrane Technology provides the highest purity outcomes, while Activated Carbon offers broad-spectrum organic contaminant removal.
End User:
The diverse needs and regulatory environments of different end-user segments shape the adoption patterns for point of entry systems, from individual homes to large industrial complexes.
- Residential:Residential users, including single-family homes and multi-unit dwellings, seek solutions for taste, odor, and health-related contaminants from municipal or well water sources. Concerns over emerging contaminants like PFAS in US households drive significant demand for certified systems.
- Commercial:Commercial end-users, encompassing offices, retail spaces, and educational institutions, prioritize consistent water quality for employee health, equipment protection, and operational efficiency. Stricter legionella prevention guidelines in European public buildings accelerate investment in advanced treatment.
- Industrial:Industrial facilities require specialized water treatment for process water, boiler feed, and cooling towers, often demanding very high purity levels.
- Hospitality:Hotels, restaurants, and resorts utilize POE systems to ensure consistent water quality for guest satisfaction, food preparation, and equipment longevity.
Residential end-users represent the largest volume segment, with Hospitality demonstrating rapid expansion in urban centers.
Application:
Specific application requirements drive the selection of water treatment systems, influencing both technology choice and system scale to meet diverse functional needs.
- Drinking Water:Drinking water applications demand systems that meet stringent potable water standards, ensuring safety and palatability for human consumption. Public health directives from WHO and national regulators like the EPA compel upgrades in older municipal supply areas.
- Industrial Processing:Industrial processing requires high-purity water for manufacturing, cooling, and boiler feed, where contaminant presence can lead to equipment damage or product defects. Microelectronics fabrication in Japan relies on ultra-pure water to prevent yield losses.
- Irrigation:Water treatment for irrigation focuses on removing suspended solids and undesirable minerals to protect crops and irrigation systems.
- Aquaculture:Aquaculture applications require specific water quality parameters to support aquatic life, involving filtration and disinfection to prevent disease.
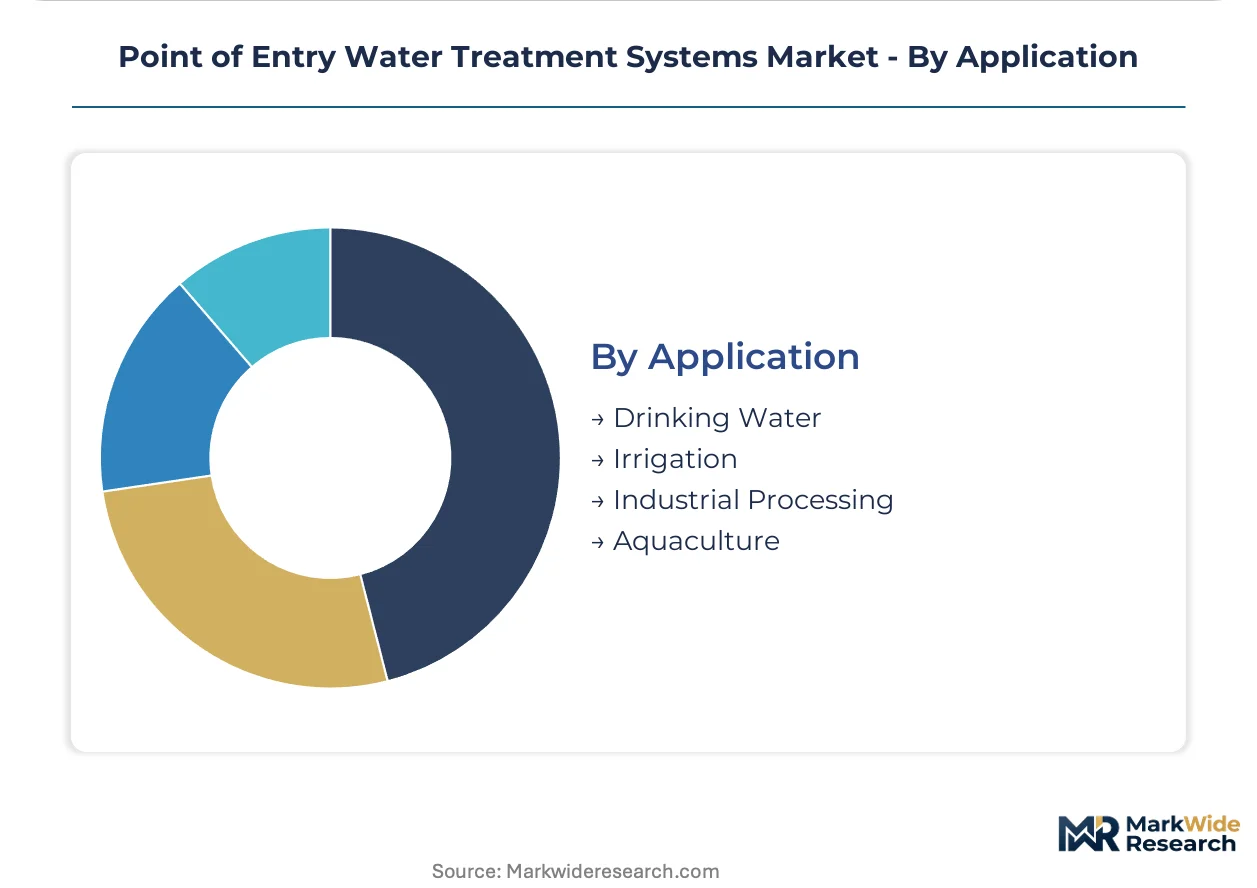
Drinking Water applications generate the broadest market demand, while Industrial Processing presents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for point of entry water treatment systems concentrates where skilled engineering workforces and regulatory compliance expertise are established. This global market sees significant activity driven by urbanization and industrial growth. Diverse regional needs shape technology adoption and investment patterns.
United States
Demand for residential and commercial systems in the United States is driven by concerns over emerging contaminants like PFAS. The U.S. EPA's establishment of enforceable limits for these substances compels upgrades across municipalities and private properties. Major tech and biotech clusters in California and Massachusetts require ultra-pure water for critical processes.
Germany
German industrial sectors require high-purity water for manufacturing and process lines. ECHA regulations under REACH influence material safety and contaminant limits for water treatment components. Commercial laundries and food processing facilities in Bavaria increasingly rely on UV for pathogen control.
India
India's rapid urbanization and hospitality sector expansion drive demand for reliable water treatment solutions. Local health regulations and the Bureau of Indian Standards (BIS) influence product specifications. New residential and commercial installations in the Delhi-NCR region require comprehensive systems due to inconsistent municipal water quality.
China
China's industrial growth and focus on environmental protection accelerate the adoption of advanced water treatment. The Ministry of Ecology and Environment (MEE) sets strict permissible limits for industrial discharge and drinking water quality. Manufacturing hubs in the Yangtze River Delta heavily invest in systems for process water and wastewater treatment.
Brazil
Brazil's growing middle-class population and concerns about municipal water reliability create greenfield opportunities. The National Health Surveillance Agency (ANVISA) regulates water quality for human consumption and industrial use. Urban expansion in São Paulo generates significant demand for residential and commercial point of entry systems.
Point of Entry Water Treatment Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure for point of entry water treatment systems. The market features established conglomerates offering broad portfolios alongside specialized technology providers focused on niche applications. Strategic partnerships for distribution and technology licensing are common competitive moves.
Among the established players, Pentair plc leverages its extensive distribution network to serve diverse end-users across residential and commercial segments. A.O. Smith Corporation integrates its water treatment technologies with its established water heater business, expanding its market reach. 3M Company differentiates through its focus on advanced filtration media and material science innovations, targeting specific contaminant removal challenges.
| Leading Market Players |
|---|
| A.O. Smith Corporation |
| Pentair plc |
| Culligan International Company |
| 3M Company |
| DuPont de Nemours Inc. |
| BWT Holding GmbH |
| Watts Water Technologies Inc. |
| Best Water Technology AG |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
The global cost of PVC resin, a key input for water treatment system components, cascades into tiered pricing structures across the point of entry market. This commodity benchmark influences both component manufacturing costs and final system prices.
Pricing Analysis
Bundled service contracts, encompassing system installation, maintenance, and consumable replacements, dominate commercial sector pricing. Subscription-based "Water-as-a-Service" models gain traction in hospitality and healthcare verticals. Price differentiation occurs based on system certification level, such as NSF/ANSI compliance, and the extent of after-sales service included. Pricing pressure stems from intense competition among manufacturers offering similar filtration technologies. Residential homeowners exhibit higher price sensitivity compared to large industrial facilities requiring guaranteed high-purity water.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by large commercial buyers to mitigate supply disruptions. Component manufacturing concentrates in China, India, and Germany for specialized membranes and UV lamps. The market relies on specialized polymers for membranes, activated carbon for filtration media, and quartz glass for UV purifiers. Geopolitical tensions pose a structural risk to the global supply of rare earth elements used in advanced filtration media. Distribution runs through a hybrid model combining direct sales for large industrial projects and extensive distributor networks for residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Point of Entry Water Treatment Systems Market functions as a stable compounder, driven by the continuous global push for improved drinking water quality and stricter contaminant regulations.
For Market Incumbents: Deploy advanced R&D into PFAS removal technologies to maintain a competitive edge against emerging filtration solutions. Market incumbents like Pentair plc must leverage their extensive distribution networks to offer comprehensive service packages, including real-time monitoring. Investing in certification for new materials under U.S. EPA guidelines will solidify market leadership.
For New Entrants and Emerging Players: Begin with targeting underserved light industrial applications requiring high-purity water, such as microelectronics fabrication in emerging markets. New entrants can penetrate the market by offering modular, IoT-enabled systems for small to medium-sized enterprises. A strong go-to-market angle involves providing flexible "Water-as-a-Service" models that reduce upfront capital expenditure for commercial clients.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology providers offering innovative solutions for emerging contaminants like PFAS. The market offers long-term viability over a 5-10 year window, driven by escalating regulatory demands and urbanization. Investors should seek acquisition targets with proprietary filtration media or advanced sensor integration capabilities. The signal to watch involves increasing government mandates for specific contaminant removal in municipal water supplies.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Membrane Development | Creates higher-purity water solutions for industrial processing, meeting stringent quality standards in Germany. |
| IoT-Enabled System Rollout | Enhances predictive maintenance and real-time water quality monitoring for hospitality clients in North America. |
| Latin American Market Entry | Capitalizes on greenfield opportunities for residential systems due to inconsistent municipal water quality in Brazil. |
| PFAS Certification Investment | Establishes credibility and market access for residential systems addressing U.S. EPA regulations. |
| Service Model Expansion | Reduces capital expenditure barriers for commercial customers, particularly in the European healthcare vertical. |
Research Approach
Bottom-up residential and commercial end-user modeling reconciled against top-down component supplier tracking forms the analytical core of this study. This approach integrates primary interviews with water treatment plant operators, procurement managers in hospitality, system installers, and R&D directors. Secondary validation draws from U.S. EPA reports, EU Drinking Water Directive documents, industry association publications, and company financial filings. This triangulation ensures robust market sizing and segmentation.
An input-output matrix links market drivers to segment-specific outcomes across the analysis window. The analytical framework models demand across product type, technology, end-user, and application dimensions. Compound Annual Growth Rates (CAGRs) derive from historical data trend analysis and future growth projections for each segment. Key forecast inputs include urbanization rates in India and new contaminant regulatory limits in the United States.
Several conditions sit outside the modeled scope, including short-term geopolitical conflicts and sudden, unforeseen technological breakthroughs. Forecasts reflect documented assumptions regarding economic stability and regulatory enforcement. Deviation in global supply chain stability or the emergence of entirely new water treatment paradigms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Plant Based Water Filter Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Global RO Water Purifier Market