
 GCC Water Purifier Market | 2026-2036
GCC Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Water Purifier Market Intelligence
Multi-source component procurement is restructuring supply dynamics for GCC water purifier manufacturers. Culligan International Company leverages captive membrane sourcing networks across Gulf free zones. A.O. Smith Corporation anchors its regional position through localized assembly and temperature-calibrated systems for Gulf climates. Kent RO Systems competes via dense distributor networks in Indian expatriate communities concentrated across the UAE and Qatar.
GCC water purifiers are electromechanical filtration systems designed to reduce total dissolved solids, microbial contamination, and residual desalination byproducts from municipal and brackish water supplies, typically operating at feed pressures between 40 and 80 psi for reverse osmosis stages. RO Purifiers dominate value capture due to Gulf consumers' salinity concerns and SASO-mandated performance thresholds, while UV Purifiers sustain faster growth in commercial food-service applications where flow rate and chemical-free operation matter. Offline Stores still control the majority of unit transactions, though Online Retail is displacing traditional channels among younger demographics in the UAE and Bahrain.
SASO's technical regulations for electrical appliances, the UAE's ECAS conformity scheme, and Qatar's Ministry of Municipality water quality standards collectively shape product certification requirements and import clearance timelines across the six Gulf states. Manufacturers must navigate divergent labeling and testing protocols, which favors regionally established players with in-house compliance teams. Stakeholders should monitor Saudi Arabia's evolving building codes for mandatory pre-installation filtration in new residential developments.
Market Dynamics
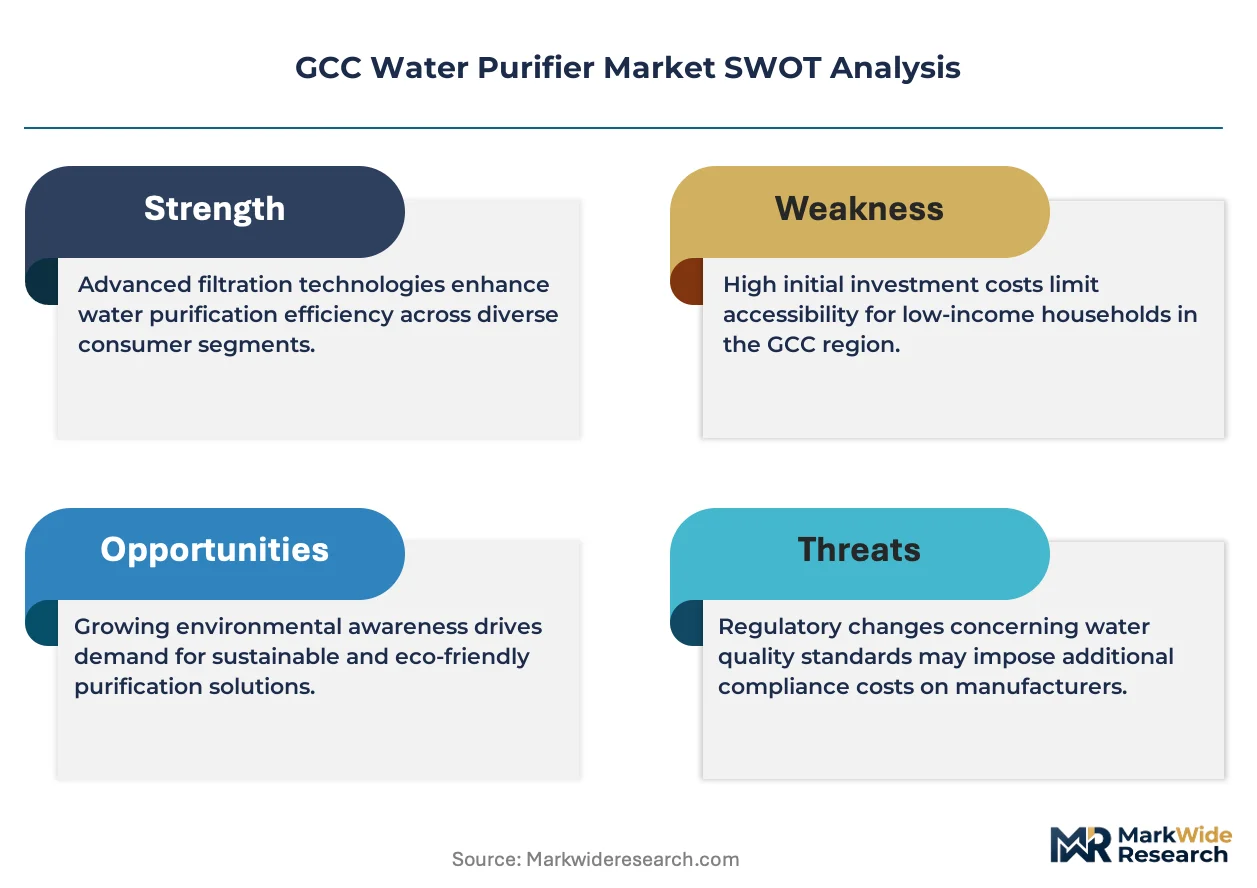
Desalination-dependent municipalities across the Gulf Cooperation Council are tightening potable water standards, forcing residential and commercial buyers toward multi-stage certified systems that can handle high-salinity feed water and residual treatment byproducts.
Growth Catalysts
- SASO Certification Mandates:Saudi Arabia's technical regulations for electrical appliances now require performance thresholds that only reverse osmosis systems with certified membranes can reliably meet, redirecting procurement toward compliant suppliers.
- Indian Expatriate Households:Dense concentrations of Indian nationals across the UAE and Qatar sustain demand for familiar RO technology brands, creating a built-in customer base for established filtration players.
- RO Membrane Efficiency Gains:Advances in thin-film composite membrane chemistry have reduced energy consumption per liter of purified water, making residential systems economically viable for Gulf households previously dependent on bottled water.
Market Restraints
- Membrane Import Concentration:Critical RO membrane supply concentrates in East Asian manufacturing hubs, exposing GCC assemblers to shipping cost volatility and extended lead times for replacement cartridges.
- Brackish Water Variability:Inland Saudi Arabia and northern Oman present feed water chemistries that prematurely foul standard membranes, requiring costly pre-treatment configurations that compress margins.
- ECAS Conformity Timelines:The UAE's product registration scheme imposes extended testing protocols that delay market entry for new entrants without established in-country representation.
Strategic Opportunities
- Bahrain's Underserved Northern Governorate:Lower penetration rates in Bahrain's second-tier cities present white space for distributor network expansion before competitors establish channel lock-in.
- Commercial Food-Service UV Applications:Restaurants and catering operations across Qatar are adopting chemical-free ultraviolet systems for high-flow applications where taste neutrality matters.
- Kuwait's Mandatory Pre-Installation Codes:Evolving building regulations for new residential developments create a captive specification channel for integrated filtration systems at the construction stage.
Industry Challenges
- Multi-Jurisdiction Labeling Complexity:Divergent Arabic-English bilingual requirements across Saudi Arabia, the UAE, and Qatar force manufacturers to maintain separate packaging SKUs, inflating inventory carrying costs.
- Field Service Technician Scarcity:Shortages of certified technicians capable of diagnosing membrane fouling and pressure-vessel integrity issues constrain after-sales revenue capture and customer retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Water Purifier Market |
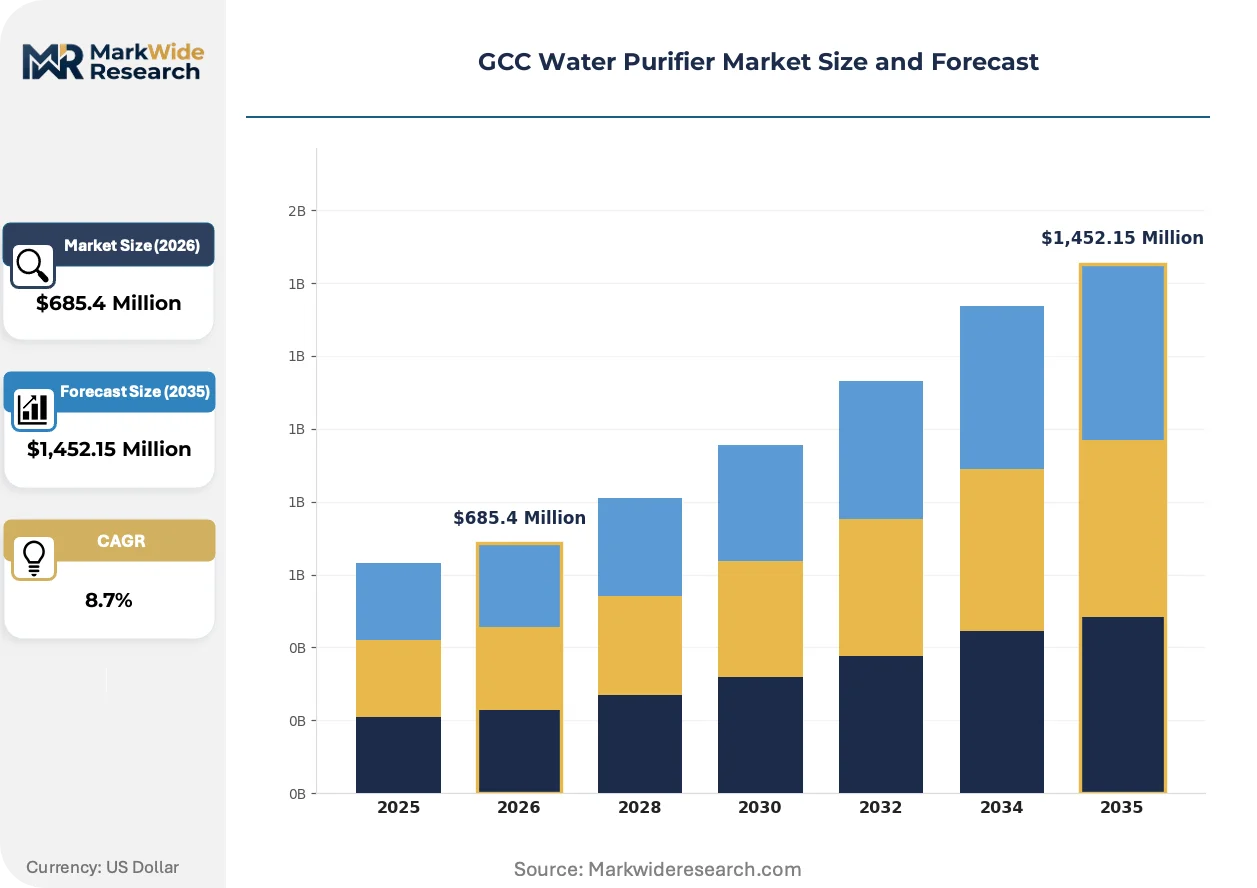
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RO Purifiers, UV Purifiers, Activated Carbon Filters, Distillers Technology: Reverse Osmosis, Ultraviolet, Microfiltration, Ion Exchange End User: Residential, Commercial, Industrial, Healthcare Distribution Channel: Online Retail, Offline Stores, Direct Sales, Distributors |
| Companies Covered | Culligan International Company, Panasonic Corporation, A.O. Smith Corporation, Eureka Forbes, 3M Company, LG Electronics, Kent RO Systems, Coway Co., Ltd., Pentair, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Water Purifier Market Strategic Shifts & Innovations
Electromechanical filtration architectures are converging with smart monitoring capabilities and climate-calibrated engineering, compressing the traditional divide between residential convenience and commercial-grade water quality assurance.
Thin-film composite reverse osmosis membranes are consolidating their position as the dominant purification technology for Gulf residential applications. Households across Saudi Arabia's Riyadh-Jeddah corridor are adopting these systems at accelerating rates due to salinity concerns and SASO-mandated performance floors. The technology is consolidating supplier margins around membrane replacement cycles rather than initial equipment sales.
SASO's evolving technical regulations for electrical appliances are reshaping import clearance procedures and product testing obligations across the six Gulf states. Manufacturers now face extended conformity assessment timelines that favor established players with in-house compliance teams over new market entrants. Saudi Arabia's residential sector bears the brunt of these changes, with distributors pre-certifying entire product lines to avoid customs delays.
Younger demographics across the UAE and Bahrain are abandoning traditional electronics souks in favor of direct-to-consumer online channels for water purifier purchases. E-commerce platforms are displacing offline retail for initial research and price comparison, though complex installation requirements sustain dealer involvement for final fulfillment. This channel rotation is most visible in Dubai's expatriate-heavy residential towers where convenience and transparent pricing outweigh established retail relationships.
GCC Water Purifier Market Segmentation
GCC water purifier procurement patterns diverge sharply across installation settings, purification technologies, and purchase channels. Understanding these fault lines reveals where replacement cycles compress and where specification decisions concentrate purchasing power.
Product Type:
Upgrade cycles vary dramatically by purification architecture, with membrane-based systems commanding shorter replacement intervals than passive filtration alternatives.
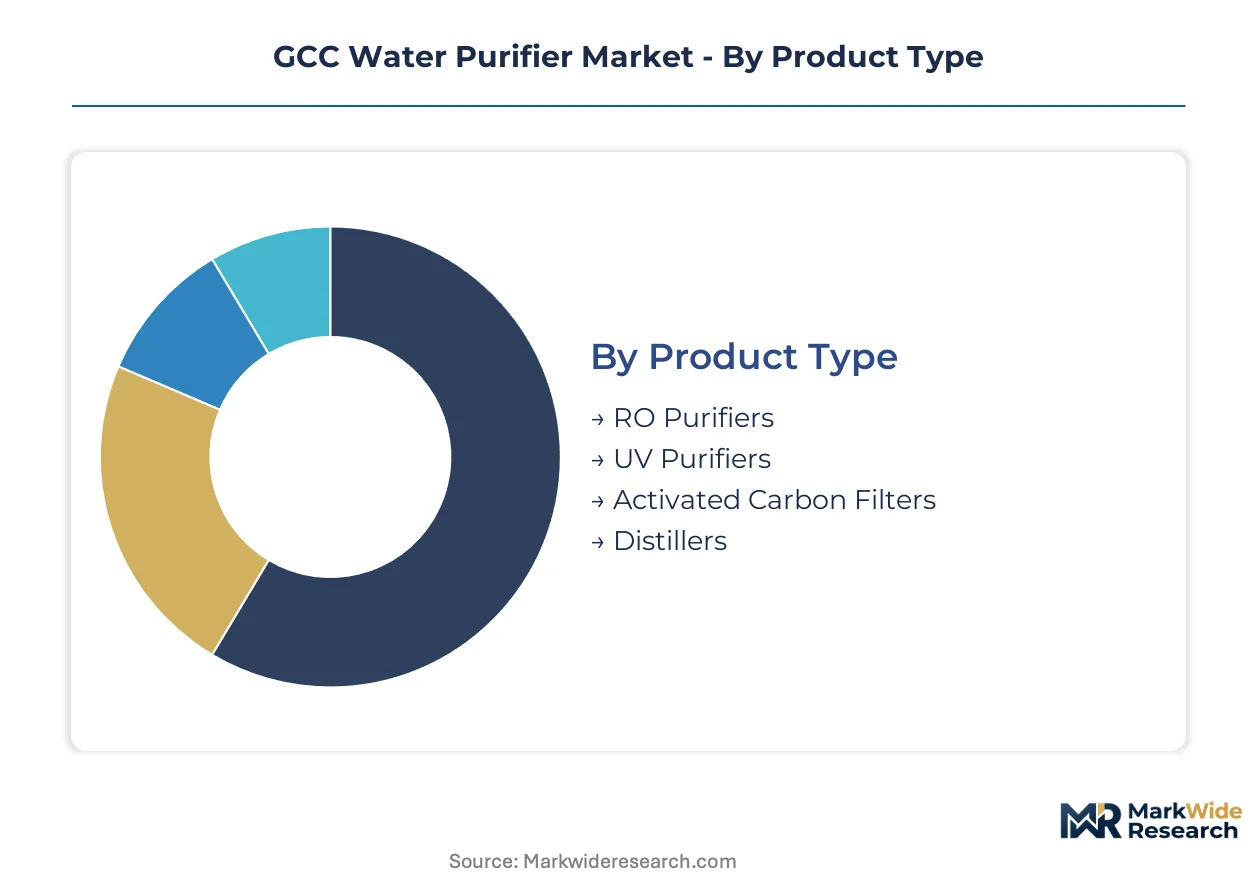
- RO Purifiers:Multi-stage reverse osmosis systems with thin-film composite membranes dominate residential installations across Saudi Arabia's Riyadh-Jeddah corridor. SASO certification mandates and consumer salinity concerns sustain premium positioning despite higher energy consumption and cartridge replacement costs.
- UV Purifiers:Ultraviolet systems utilizing mercury-vapor or LED lamp arrays deliver chemical-free disinfection for commercial food-service applications in Qatar's hospitality sector. Flow rate advantages and taste neutrality drive adoption where volume throughput outweighs dissolved solids removal requirements.
- Activated Carbon Filters:Adsorption-based units target chlorine residual and organic compound reduction in secondary treatment configurations.
- Distillers:Thermal evaporation systems occupy niche medical and laboratory applications requiring absolute purity verification.
Volume placements concentrate in RO Purifiers; the faster expansion belongs to UV Purifiers.
Technology:
Cost tiers separate established membrane technologies from emerging filtration approaches competing on operational simplicity and reduced maintenance burden.
- Reverse Osmosis:Pressure-driven semipermeable membrane separation achieves dissolved solids rejection rates exceeding 95% for Gulf brackish water feeds. Saudi Arabian municipalities specify RO pre-treatment for new residential developments, embedding the technology in construction-phase procurement.
- Ultraviolet:Electromagnetic disinfection at 254 nanometers inactivates pathogens without chemical residuals, satisfying MOHAP guidelines for Dubai's commercial kitchen installations where flow continuity matters.
- Microfiltration:Porous membrane barriers rated 0.1-10 microns target suspended particulate and protozoan cyst removal.
- Ion Exchange:Resin-based softening and deionization systems address hardness and specific ionic contaminants in industrial process water loops.
Revenue concentrates in Reverse Osmosis; Microfiltration is climbing the fastest among emerging alternatives.
End User:
Application context dictates performance specifications, with healthcare and industrial segments imposing validation requirements absent from residential procurement.
- Residential:Household installations across the UAE's Dubai-Abu Dhabi axis prioritize compact under-sink configurations with automated shutoff and filter-life indicators. Indian expatriate communities sustain demand for familiar RO brands with established service networks.
- Commercial:Food-service, hospitality, and office installations in Bahrain's retail corridors specify high-capacity systems with redundant filtration stages and compliance documentation for health inspections.
- Industrial:Manufacturing process water and boiler feed applications require customized pre-treatment trains with conductivity monitoring and automated regeneration cycles.
- Healthcare:Dialysis centers and clinical laboratories demand validated systems meeting SFDA medical device standards for endotoxin and bacterial control.
Unit volumes concentrate in Residential; specification value per installation peaks in Healthcare.
Distribution Channel:
Customer type and purchase urgency shape channel selection, with younger demographics abandoning traditional retail for digital discovery while complex installations sustain dealer involvement.
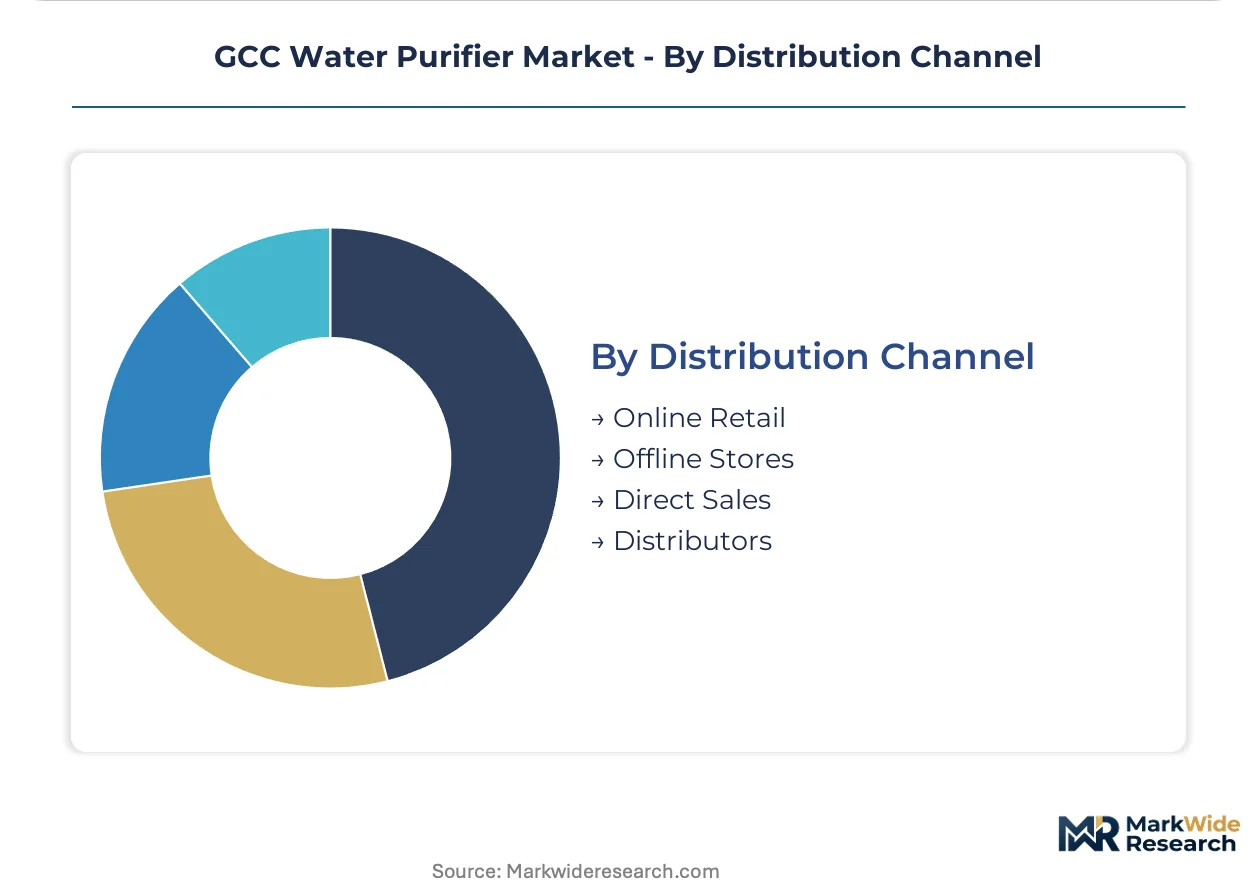
- Online Retail:E-commerce platforms capture initial research and price comparison among UAE and Bahrain consumers under 35, though final fulfillment typically requires technician-coordinated delivery for pressure testing and warranty activation.
- Offline Stores:Electronics souks and hypermarket appliance sections across Saudi Arabia and Oman remain dominant for tactile evaluation and immediate availability, particularly for first-time buyers seeking installation guidance.
- Direct Sales:Manufacturer-employed representatives target commercial and industrial accounts with customized proposal development and service contract bundling.
- Distributors:Independent dealer networks provide geographic coverage in Kuwait's peripheral governorates and Oman's interior regions where direct manufacturer presence remains thin.
Transaction volume concentrates in Offline Stores; Online Retail is gaining share fastest among replacement purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desalination infrastructure and brackish groundwater reserves anchor water purifier demand across the six Gulf Cooperation Council states. Municipal treatment standards and residential quality concerns drive procurement toward certified multi-stage filtration systems.
Saudi Arabia
Residential installations accelerate across Riyadh and Jeddah as SASO certification mandates tighten performance thresholds for electrical appliances. The Saudi Standards, Metrology and Quality Organization requires documented membrane efficiency testing that favors established suppliers with in-country compliance infrastructure. Eastern Province industrial zones sustain commercial demand for high-capacity pre-treatment systems.
United Arab Emirates
Younger demographics in Dubai and Abu Dhabi shift procurement toward online retail channels for price comparison and convenience. MOHAP guidelines for commercial kitchen installations mandate ultraviolet or reverse osmosis pre-treatment in hospitality operations. Sharjah's manufacturing free zones host regional assembly operations for temperature-calibrated systems.
Qatar
Indian expatriate communities in Doha sustain demand for familiar RO technology brands with established service networks. The Ministry of Municipality enforces water quality standards that redirect food-service procurement toward chemical-free ultraviolet systems. Lusail City's new residential towers specify integrated filtration at the construction phase.
Kuwait
Evolving building codes for new residential developments in Hawalli and Al Asimah Governorates create captive specification channels for pre-installation filtration systems. The Public Authority for Industry administers conformity assessment timelines that delay market entry for suppliers without established representation. Jahra Governorate's underserved peripheral areas present distributor expansion opportunities.
Bahrain
Lower penetration rates in the Northern Governorate and Muharraq offer white space for channel expansion before competitors establish lock-in. The Electricity and Water Authority maintains potable standards that accelerate residential upgrades from basic carbon filters to multi-stage systems. Manama's retail corridors sustain offline store dominance for tactile evaluation and immediate availability.
GCC Water Purifier Market Key Industry Players
Global majors compete with regional champions across certification capabilities and distributor network density. The vendor base fragments across three tiers: multinational appliance conglomerates with captive Gulf assembly, water treatment specialists with membrane technology control, and regional distributors serving expatriate community preferences. Two strategic archetypes dominate: compliance-heavy integrated system providers and agile aftermarket service specialists. Competitive moves concentrate on SASO pre-certification investments and technician training network expansion.
Within the multinational conglomerate tier, Panasonic Corporation and LG Electronics exemplify scale-driven positioning through electronics retail channel leverage and climate-adapted product portfolios. A.O. Smith Corporation anchors the water treatment specialist archetype through localized assembly operations and temperature-calibrated engineering for Gulf thermal conditions. Kent RO Systems occupies a position within the regional distributor tier, serving Indian expatriate demand clusters across the UAE and Qatar through dense service networks.
| Leading Market Players |
|---|
| Culligan International Company |
| Panasonic Corporation |
| A.O. Smith Corporation |
| Eureka Forbes |
| 3M Company |
| LG Electronics |
| Kent RO Systems |
| Coway Co., Ltd. |
| Pentair |
| Others |
Cost & Logistics Intelligence
Polyamide thin-film composite membrane feedstock indices cascade through GCC water purifier pricing tiers, compressing margins for assemblers dependent on East Asian material flows while amplifying differentiation power for suppliers with captive membrane sourcing or extended warranty bundling.
Pricing Analysis
Warranty and cartridge-replacement bundling separates premium positioning from unbundled transactional sales across Saudi Arabia and the UAE. Three-tier pricing structure across premium, standard, and economy levels reflects SASO certification grade and membrane origin, with Indian expatriate households in Qatar showing highest price sensitivity for initial equipment purchases. Pricing pressure stems from shipping cost volatility for replacement cartridges, though margins are tightening fastest in the standard tier where membrane efficiency gains have commoditized basic RO performance. Healthcare and commercial food-service buyers exhibit least price sensitivity due to compliance documentation requirements.
Supply Chain Analysis
Reverse-logistics for membrane refurbishment and cartridge collection remains underdeveloped across the GCC, constraining circularity economics and inflating net material costs. Thin-film composite membrane production concentrates in South Korea, Japan, and China, while activated carbon sourcing draws from Sri Lankan and Philippine coconut shell processors. Supply chain risk centers on single-source vulnerability for specialized RO housings and pressure vessels subject to ECAS conformity delays. Distribution runs through electronics souk networks in Saudi Arabia and Oman, with e-commerce platforms capturing fulfillment for replacement cycles in the UAE and Bahrain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's evolving technical regulations for electrical appliances erect a cost-of-compliance barrier that rewards incumbents with pre-certified product lines and in-country testing infrastructure, while extending market entry timelines for unestablished suppliers.
For Market Incumbents: Hedge membrane supply exposure through dual-sourcing arrangements across South Korean and Japanese material suppliers, while consolidating technician training networks to capture aftermarket replacement revenue. Defensive positioning requires deepening backward integration into membrane assembly within Sharjah's free zones to offset shipping cost volatility threatening standard-tier margins. For New Entrants and Emerging Players: Smart monitoring and IoT-enabled filter-life prediction offer a technology-first wedge into Bahrain's underserved Northern Governorate and Kuwait's Jahra Governorate, where distributor lock-in remains incomplete. White-space concentration favors UV system specification for Qatar's commercial food-service expansion, with direct-to-consumer digital channels enabling price-transparent entry before offline network buildout. For Investors and Strategic Acquirers: The window for entry favors regional distributors with dense Indian expatriate service networks and established SASO pre-certification relationships. Long-term viability hinges on consolidation plays that combine compliance infrastructure with captive membrane sourcing. Monitor Saudi Arabia's residential building code evolution for mandatory pre-installation mandates as the primary inflection signal for construction-phase specification capture.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Pre-Certification Investment | Accelerates customs clearance and redirects procurement toward compliant suppliers across Saudi Arabia's Riyadh-Jeddah corridor. |
| Technician Training Network Expansion | Addresses field service scarcity constraining after-sales revenue capture and customer retention in Oman's interior regions. |
| Membrane Assembly Localization | Compresses lead times and buffers East Asian supply concentration exposure for GCC-based system integrators. |
| UV System Specification Push | Captures Qatar's commercial food-service growth where MOHAP guidelines mandate chemical-free disinfection compliance. |
| E-Commerce Channel Development | Aligns with younger demographic purchasing patterns across UAE and Bahrain residential towers prioritizing convenience. |
Research Approach
Multi-period observation of SASO certification timelines, membrane import volumes, and distributor network density anchored the trend analysis, supplemented by interviews with water treatment equipment procurement managers at Saudi industrial zones, regulatory affairs specialists navigating ECAS conformity, commercial kitchen operators in Doha's hospitality sector, and aftermarket service technicians across the UAE. Secondary validation drew from Saudi Standards, Metrology and Quality Organization technical regulations, UAE Ministry of Industry and Advanced Technology product registration databases, Qatar Ministry of Municipality water quality standards, customs trade flow records, and SEC filings of publicly listed water treatment equipment manufacturers. Bottom-up channel checks triangulated against top-down macroeconomic indicators for the six Gulf Cooperation Council states.
Segment-weighting approaches modeled revenue and volume trajectories across purification technology, end-user application, and distribution channel dimensions throughout the forecast period. CAGRs were derived from installed base growth rates, replacement cycle compression, and specification shift assumptions, with cross-validation against desalination capacity expansion plans and municipal water quality tightening schedules across Saudi Arabia, the UAE, and Qatar.
Several conditions sit outside the modeled scope, including abrupt regulatory harmonization across the six GCC states, breakthrough membrane materials displacing thin-film composite architectures, and geopolitical disruptions to East Asian shipping lanes. Forecasts reflect assumptions about continued desalination dependency and incremental rather than step-change regulatory evolution. Practitioners should monitor SASO building code proposals for mandatory pre-installation requirements and Kuwaiti regulatory publication timelines for early signals of specification channel capture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Smart Water Softeners Market