
 Water Purification Tablets Market | 2026-2036
Water Purification Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Water Purification Tablets Market Insights
Humanitarian agencies and military buyers is bifurcating demand away from purely recreational consumers. LifeStraw leverages its filter-tablet hybrid portfolio to serve NGO field operations across conflict zones. Katadyn anchors European defense contracts with NATO-standard purification specifications. Aquatabs dominates bulk institutional procurement through WHO prequalification and competitive tenders.
Water purification tablets are solid-dose chemical treatments, typically containing sodium dichloroisocyanurate or chlorine dioxide, that release measured disinfectant concentrations when dissolved in suspect water to neutralize pathogens. The primary commercial purpose spans emergency preparedness kits, military logistics, and backcountry recreation where boiling or filtration proves impractical. Chlorine dioxide formulations command premium positioning due to broader efficacy against Cryptosporidium and reduced taste complaints versus iodine alternatives. Military operations and humanitarian assistance represent the fastest-growing application clusters, while household recreational use remains mature with thinner margins.
EPA Office of Water sets residual disinfectant limits under the Safe Drinking Water Act, shaping tablet formulation chemistry for US-manufactured products. WHO Guidelines for Drinking-water Quality establish international benchmark protocols that prequalification programs enforce across procurement chains. FDA oversight of iodine-based tablets as regulated articles affects label claims and distribution channels. Stakeholders must monitor evolving pathogen resistance profiles and regulatory shifts toward stricter byproduct limits as product differentiation pivots from basic chlorination to multi-barrier chemistries.
Market Dynamics
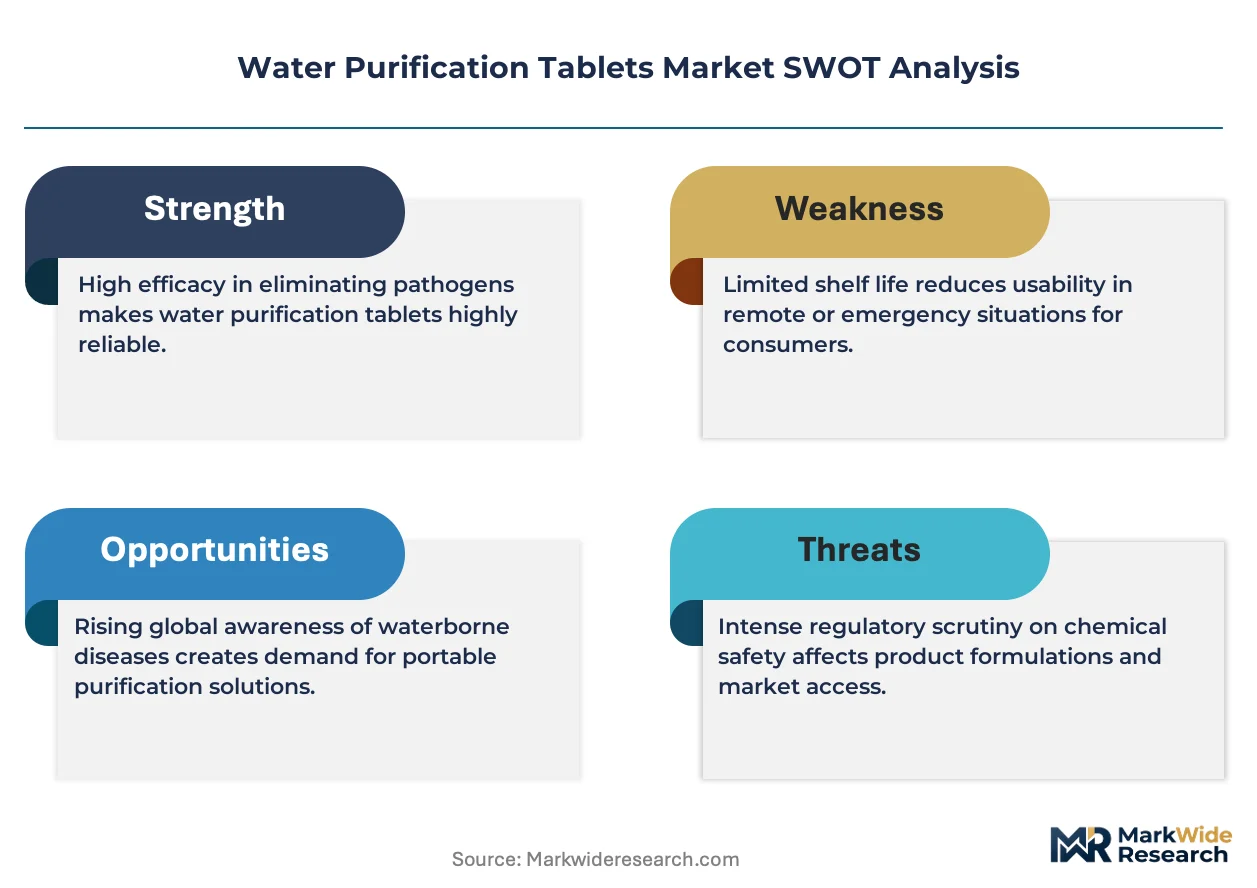
Military procurement standardization is compressing supplier margins while WHO prequalification requirements are elevating chemistry complexity for institutional tenders. Dual-use demand from humanitarian logistics and defense stockpiles is fragmenting product development roadmaps.
Growth Catalysts
- Emergency stockpiling mandates:Federal preparedness directives in the United States require maintained inventories of field-deployable water treatment for disaster response, creating recurring institutional purchase cycles.
- Chlorine dioxide chemistry:Reformulation toward broader-spectrum pathogen neutralization, including Cryptosporidium oocysts, is opening premium positioning in military and medical evacuation applications.
- Conflict zone logistics:Humanitarian agency procurement through UN and Red Cross supply chains is concentrating volume in prequalified manufacturers with rapid-deployment packaging capabilities.
Market Restraints
- Sodium dichloroisocyanurate supply concentration:Active ingredient manufacturing clusters in China create exposure to export licensing volatility and freight cost spikes.
- Residual disinfectant limits:EPA Office of Water thresholds under the Safe Drinking Water Act constrain formulation potency, requiring larger tablet counts per treatment volume.
- Filtration substitute penetration:Gravity-fed ceramic filters and membrane straws are capturing recreational consumer segments where taste sensitivity drives rejection of chemical treatments.
Strategic Opportunities
- Modular packaging formats:Single-dose blister strips and dissolvable film wrappers are penetrating ultralight backpacking and ultramarathon aid station channels.
- Dual-chemistry tablets:Co-formulated chlorine dioxide with flocculating agents is miniaturizing sediment removal and disinfection into one step for turbid source water.
- Defense contractor integration:NATO standardization agreements are creating qualification pathways for European manufacturers into allied military logistics systems.
Industry Challenges
- WHO prequalification timelines:Laboratory validation and field trial documentation for new formulations extends commercialization cycles by 18-24 months.
- Stability testing infrastructure:Accelerated aging protocols for shelf-life claims require climate-controlled facilities that smaller chemistry houses lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Purification Tablets Market |
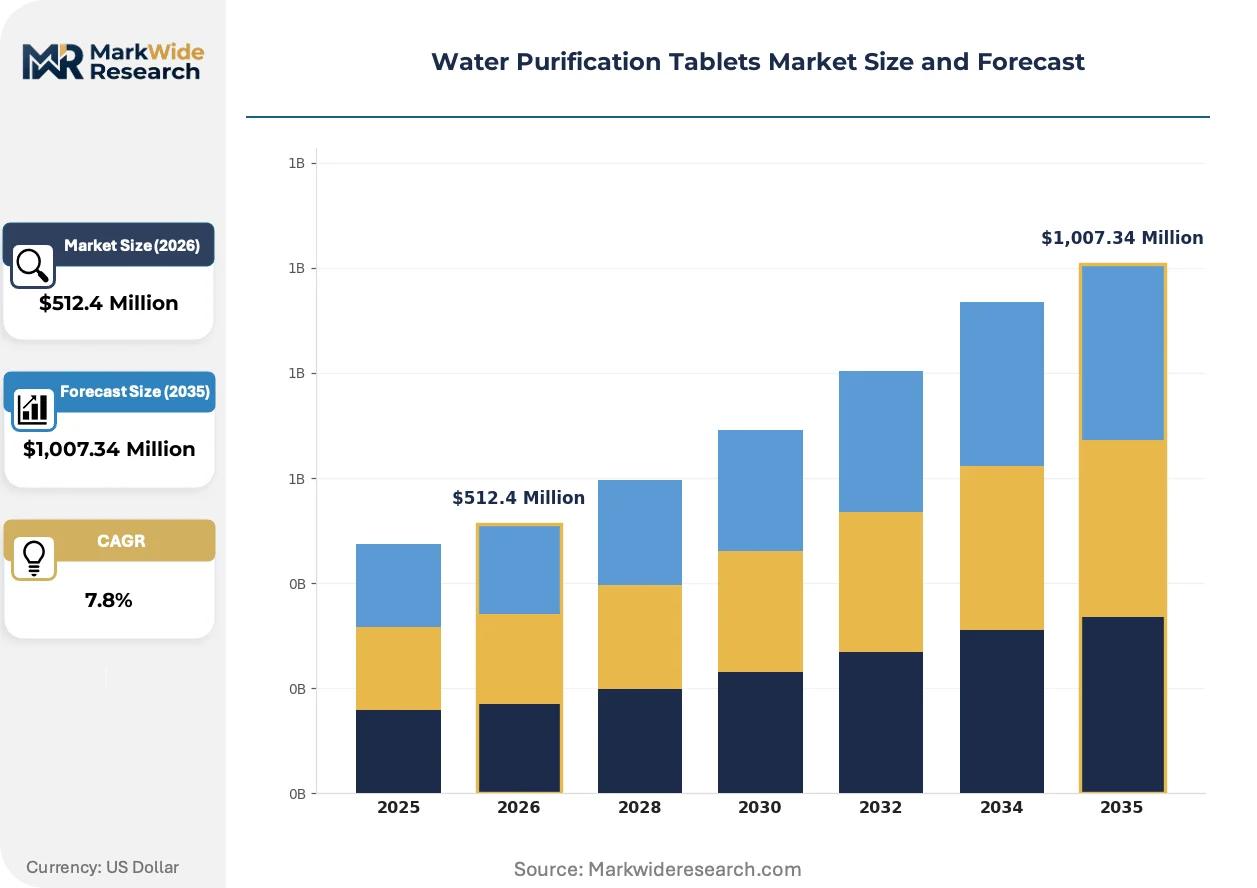
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,007.34 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Dichloroisocyanurate, Calcium Hypochlorite, Chlorine Dioxide, Iodine Tablets Application: Emergency Preparedness, Outdoor Activities, Humanitarian Assistance, Military Operations Delivery Mode: Powder, Tablet, Liquid, Granule End User: Households, NGOs, Military, Recreational |
| Companies Covered | HTH, LifeStraw, Katadyn, Brita, Sawyer, Aquatabs, Dometic, SteriPEN, Ef-Chlor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Purification Tablets Market Trends and Innovations
Formulation chemistry is bifurcating toward military-grade efficacy and consumer-grade palatability. Packaging engineering and supply chain digitization are converging to address last-mile distribution in austere environments.
Effervescent tablet matrices incorporating layered-release chlorine dioxide are miniaturizing dose precision for variable-volume containers. Special forces medical units and alpine rescue teams are adopting these formats for sub-liter treatment flexibility. The technology is compressing inventory variety from multiple tablet sizes toward universal dosing platforms.
REACH authorization requirements for isocyanurate derivatives are forcing reformulation investments among European manufacturers. ECHA substance evaluation timelines are extending registration maintenance costs. German and Swiss suppliers are responding with chlorine dioxide alternatives that bypass restricted substance lists.
Bulk institutional purchasing through centralized humanitarian procurement is displacing fragmented national tender processes. UNHCR and WHO consolidated supply contracts are concentrating volume among prequalified vendors. This pattern is most visible in East African refugee camp operations and Pacific Island disaster preparedness frameworks.
Water Purification Tablets Market Segmentation
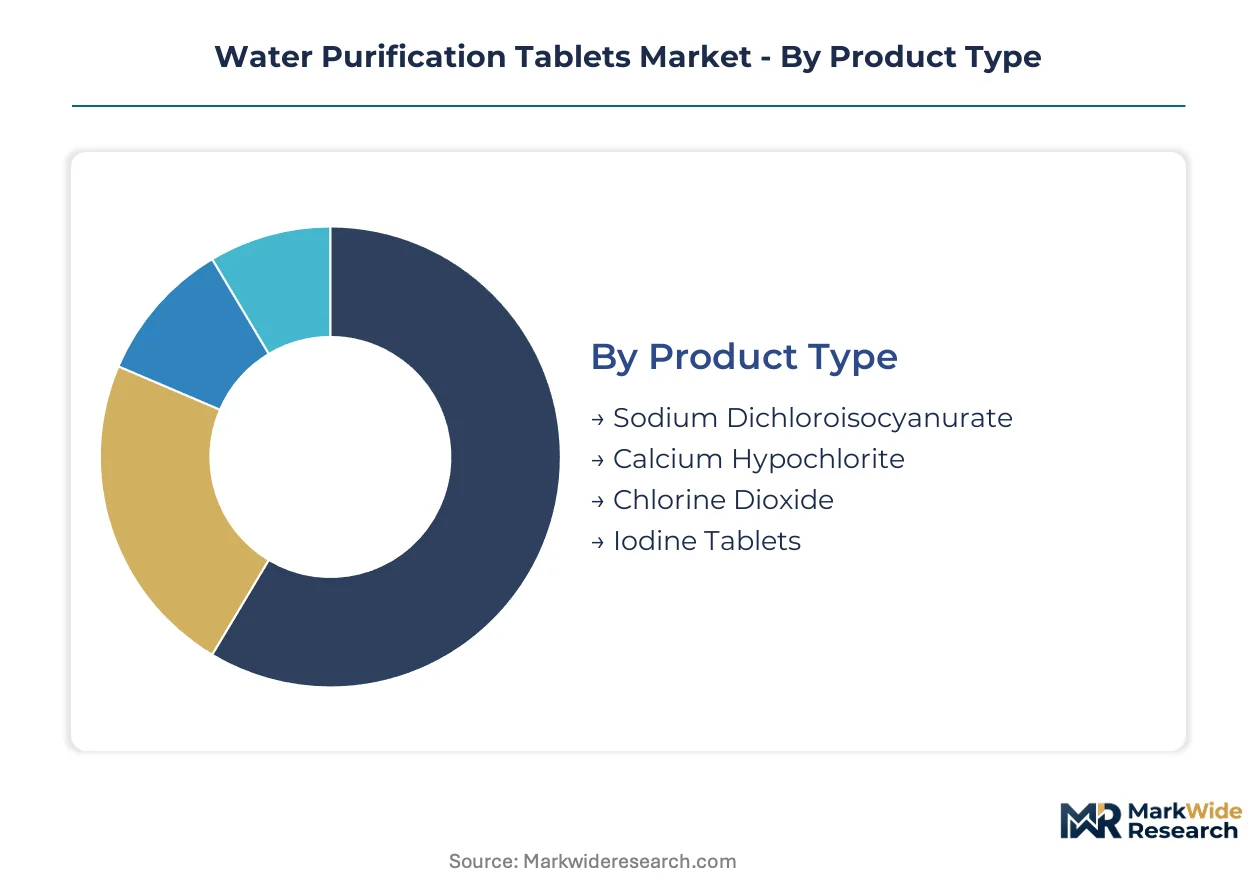
Segmentation in water purification tablets reveals how chemistry choices and packaging formats align with distinct use cases. Procurement patterns diverge sharply between institutional buyers demanding bulk efficacy and recreational consumers prioritizing portability and taste neutrality.
Product Type:
Substitution pressure from filtration technologies hits iodine-based formulations hardest, while chlorine chemistry variants defend share through pathogen spectrum advantages.
- Sodium Dichloroisocyanurate:This stabilized chlorine donor releases hypochlorous acid upon dissolution, achieving rapid bacterial and viral inactivation at neutral pH. Demand concentrates in East African humanitarian logistics and Pacific Island disaster stockpiles where cost-per-liter drives procurement decisions.
- Chlorine Dioxide:Generated through acid-activated sodium chlorite precursors, this chemistry neutralizes Cryptosporidium oocysts and biofilm-resistant pathogens that resist standard chlorination. Military medical evacuation units and alpine rescue teams in Switzerland and Austria specify these formulations for sub-liter treatment flexibility.
- Calcium Hypochlorite:Higher available chlorine content per unit mass supports bulk water treatment applications in refugee camp infrastructure.
- Iodine Tablets:Taste complaints and thyroid interaction concerns limit this chemistry to legacy military kits and ultralight backpacking niches.
Sodium Dichloroisocyanurate anchors the volume base while Chlorine Dioxide gains share at the steepest rate.
Application:
Cost tier stratification separates institutional tenders from retail channels, with pricing power concentrating in defense and humanitarian verticals.
- Military Operations:NATO standardization agreements and national defense stockpiling mandates create multi-year procurement cycles with stringent stability requirements. German and Swiss suppliers anchor European defense contracts through prequalified chemistry platforms.
- Humanitarian Assistance:UNHCR and WHO consolidated supply contracts displace fragmented national tenders, concentrating volume among manufacturers with rapid-deployment packaging and climate-zone stability documentation.
- Emergency Preparedness:Federal directives in the United States require maintained inventories at state and municipal levels, generating recurring institutional purchase cycles.
- Outdoor Activities:Gravity-fed ceramic filters and membrane straws capture recreational consumers where taste sensitivity drives rejection of chemical treatments.
Humanitarian Assistance anchors the volume base while Military Operations climbs the fastest.
Delivery Mode:
Volume economics favor solid-dose formats, with liquid and powder alternatives relegated to bulk treatment scenarios.
- Tablet:Precise dosing, extended shelf stability, and compact logistics make this the default format for military field kits and NGO air-dropped supplies. Effervescent matrices with layered-release chlorine dioxide are miniaturizing dose precision for variable-volume containers.
- Powder:Scoop-dosed bulk containers serve refugee camp water points and institutional treatment stations where volume throughput exceeds portability requirements.
- Liquid:Concentrated solutions require dilution measurement, limiting adoption to trained operator environments.
- Granule:Rapid-dissolve crystals target turbid source water applications where sediment binding complicates tablet dissolution.
Tablet anchors the volume base while Powder expands most quickly in camp infrastructure deployments.
End User:
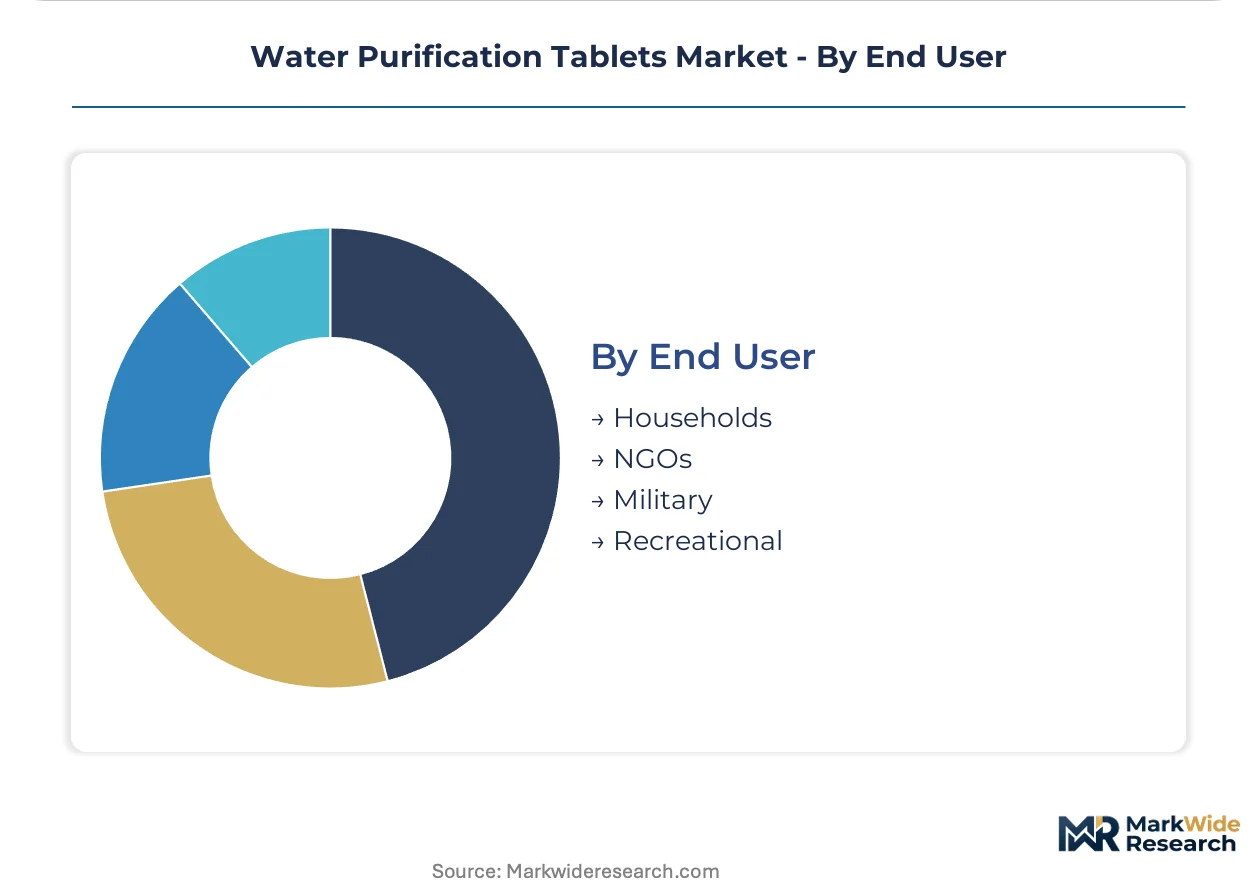
Customer type determines specification intensity, with NGOs and military buyers driving chemistry complexity while households prioritize convenience.
- NGOs:WHO prequalification requirements and UN consolidated procurement frameworks elevate documentation burdens, favoring established manufacturers with stability testing infrastructure.
- Military:National defense logistics systems demand NATO-standard specifications and climate-extremes validation, compressing supplier margins while locking in volume.
- Households:Retail channel distribution through outdoor recreation retailers and emergency preparedness outlets emphasizes single-dose blister packaging and palatability claims.
- Recreational:Ultralight backpacking and ultramarathon aid station channels are penetrating modular packaging formats including dissolvable film wrappers.
NGOs anchor the volume base while Military shows the steepest specification-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient manufacturing clusters in China create exposure to export licensing volatility, while procurement concentrates in defense and humanitarian corridors across North America and Europe. Federal stockpiling mandates in the United States and NATO standardization agreements in Germany shape demand specifications.
United States
Federal emergency preparedness directives require maintained inventories at state and municipal levels, generating recurring institutional purchase cycles. EPA Office of Water residual disinfectant limits under the Safe Drinking Water Act constrain formulation chemistry. Outdoor recreation spending concentrates in Colorado and Utah, where ultralight backpacking demand drives modular packaging adoption.
Germany
NATO standardization agreements create qualification pathways for European manufacturers into allied military logistics systems. REACH authorization requirements for isocyanurate derivatives force reformulation investments among domestic chemistry houses. Bavarian and Swiss-border suppliers anchor European defense contracts through prequalified chlorine dioxide platforms.
Switzerland
Alpine rescue teams and special forces medical units specify premium chlorine dioxide formulations for sub-liter treatment flexibility. Swissmedic oversight shapes stability documentation requirements for military-grade shelf-life claims. Basel-area chemical specialists concentrate on effervescent matrices with layered-release precision.
China
Sodium dichloroisocyanurate manufacturing clusters supply bulk active ingredients to global tablet formulators. Export licensing volatility and freight cost spikes create supply chain exposure for downstream producers. Zhejiang and Jiangsu province chemical parks dominate precursor chemical output.
Australia
Pacific Island disaster preparedness frameworks channel WHO prequalified procurement through consolidated supply contracts. TGA alignment with international stability protocols facilitates rapid registration for emergency stockpile tenders. Queensland and New South Wales serve as distribution hubs for regional humanitarian logistics.
Water Purification Tablets Market Competitive Landscape
Concentration sits with prequalified institutional suppliers who have navigated WHO validation timelines and NATO specification compliance. The vendor base separates into three tiers: established chemistry houses with stability testing infrastructure, defense-focused specialists with climate-extremes validation, and recreational brands competing on packaging innovation. Strategic moves center on dual-chemistry formulation patents and modular packaging format licensing.
Among European defense contractors, Katadyn anchors NATO-standard positioning, while LifeStraw represents the filter-tablet hybrid archetype serving NGO field operations. Aquatabs occupies the bulk institutional procurement tier through WHO prequalification concentration. These three exemplify how chemistry complexity and documentation burden filter competitive participation.
| Leading Market Players |
|---|
| HTH |
| LifeStraw |
| Katadyn |
| Brita |
| Sawyer |
| Aquatabs |
| Dometic |
| SteriPEN |
| Ef-Chlor |
| Others |
Pricing and Supply Chain Analysis
Active ingredient scale economies in Zhejiang and Jiangsu province chemical parks compress unit costs for sodium dichloroisocyanurate formulators while simultaneously concentrating pricing power among bulk manufacturers serving institutional procurement channels.
Pricing Analysis
Volume-discount tiering structures stratify across NATO-standard defense contracts, WHO prequalified humanitarian tenders, and retail recreational channels. Three-tier pricing separates premium chlorine dioxide formulations with Cryptosporidium efficacy from standard sodium dichloroisocyanurate tablets and economy-grade calcium hypochlorite bulk containers. Price differentiation hinges on certification tier and geographic delivery cost. Cost compression in recreational segments is intensifying because gravity-fed ceramic filters capture taste-sensitive consumers. Humanitarian agencies exhibit highest price sensitivity; military medical units show lowest.
Supply Chain Analysis
China and India anchor sodium dichloroisocyanurate precursor manufacturing, while Germany and Switzerland concentrate chlorine dioxide formulation expertise. Tablet production draws from sodium chlorite precursors, acid-activated matrices, and effervescent binding agents. Single-source vulnerability concentrates in Zhejiang province export licensing. Distribution runs through UN consolidated procurement frameworks, NATO logistics systems, and outdoor recreation retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal emergency stockpiling mandates in the United States are driving a cyclical recovery in institutional procurement volumes, with recurring purchase cycles resetting inventory baselines across state and municipal preparedness frameworks.
For Market Incumbents: Consolidate backward integration into sodium chlorite precursor supply to offset Chinese export licensing volatility. Lock in NATO standardization compliance ahead of REACH authorization deadlines for isocyanurate derivatives. Capacity addition in Bavarian chemical parks strengthens European defense contract positioning against margin compression from bulk institutional tenders. For New Entrants and Emerging Players: WHO prequalification fast-tracks open entry pathways for manufacturers with stability testing infrastructure. Target Pacific Island disaster preparedness frameworks where consolidated supply contracts displace fragmented national tenders. Alpine rescue team specifications for sub-liter treatment flexibility represent the most penetrable premium niche. Go-to-market through UNHCR framework agreements bypasses retail channel establishment costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among prequalified institutional suppliers with multi-year defense stockpiling contracts. Long-term viability over a 5-10 year window favors manufacturers with dual-chemistry patent portfolios and climate-extremes validation documentation. Acquisition targets should show established WHO prequalification status and NATO specification compliance. Monitor EPA Office of Water residual disinfectant limit revisions as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive sodium chlorite production insulates margins from Chinese export licensing volatility. |
| WHO Prequalification Investment | UNHCR consolidated procurement frameworks concentrate volume among validated manufacturers exclusively. |
| Dual-Chemistry Formulation Patent | Co-formulated chlorine dioxide with flocculating agents commands premium positioning in turbid water applications. |
| Modular Packaging Format Development | Dissolvable film wrappers penetrate ultramarathon aid stations and ultralight backpacking channels. |
| NATO Standardization Compliance | Allied military logistics systems create multi-year procurement cycles with stringent stability requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with military procurement officers, humanitarian logistics coordinators, and outdoor recreation retail buyers; and secondary validation through EPA Office of Water regulatory filings, WHO prequalification databases, and NATO standardization agreement documentation. Bottom-up tablet volume estimates triangulated against top-down institutional procurement budget allocations across federal preparedness directives.
Across the modeling period, forecasts incorporated chemistry type, application vertical, packaging format, and end-user procurement channel as core segmentation dimensions. CAGRs derived from historical institutional purchase cycle patterns, projected defense stockpiling mandates, and recreational consumer substitution dynamics. Chlorine dioxide efficacy expansion against Cryptosporidium and REACH authorization timelines for isocyanurate derivatives served as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained federal emergency preparedness funding and stable Chinese precursor export licensing; material deviation in either would warrant model refresh. Specific risks include filtration technology substitution acceleration, EPA residual disinfectant threshold tightening, and humanitarian procurement consolidation shifts. Recalibration cycles align with material shifts in defense stockpiling appropriations and regulatory chemistry authorization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market