
 Closed-Loop Recycling Programs for Automotive Hoses Market | 2026-2036
Closed-Loop Recycling Programs for Automotive Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Closed-Loop Recycling Programs for Automotive Hoses Market Insights
Thermoplastic elastomers is expanding its share in automotive hose construction as manufacturers seek mono-material designs that simplify mechanical recycling without separation stages. Continental AG leverages its integrated tire and rubber operations to secure feedstock streams for reprocessed hose compounds. Gates Corporation anchors its program through captive collection networks serving North American heavy-duty vehicle fleets. Nichirin Co. Ltd. specializes in small-diameter fuel and vapor recovery hoses where material purity standards remain stringent.
Closed-loop recycling programs for automotive hoses are systematic recovery systems that collect post-use elastomeric tubing—typically operating within temperature ranges from minus forty to one hundred fifty degrees Celsius—and reprocess them into virgin-equivalent compounds through devulcanization or melt recompounding, primarily serving OEM cost reduction and regulatory compliance objectives. Manufacturer-led programs currently dominate operational scale because they control design specifications and can mandate return protocols through supplier contracts, while incentive-based models represent the fastest-growing segment as third-party platforms reward independent garages for segregated collection. EPDM recovery occupies the largest material volume given its prevalence in coolant and heater hoses, though thermoplastic elastomer streams command margin premiums due to lower reprocessing energy requirements and broader reapplication potential.
The EPA oversees hazardous waste classifications affecting spent hose disposal in the United States, while REACH restricts candidate substance concentrations in recycled elastomers entering European supply chains, and Japan's METI promotes resource circulation through specified recycling targets under its Automobile Recycling Law. These frameworks collectively elevate compliance costs for open-loop disposal while accrediting closed-loop pathways as preferred regulatory outcomes. Stakeholders must now evaluate whether to build captive reprocessing capacity or secure long-term offtake agreements with specialized compounders before feedstock competition intensifies.
Market Dynamics
The EU Green Deal's end-of-life vehicle directives are tightening material recovery quotas across member states, forcing OEMs to redesign supplier contracts around mandatory return protocols rather than optional collection incentives.
Growth Catalysts
- REACH candidate substance restrictions:Recycled elastomers entering European supply chains face stricter concentration limits, accrediting closed-loop pathways as the compliant disposal route.
- Heavy-duty fleet concentration:North American commercial vehicle operators generate predictable hose replacement volumes that anchor captive collection network economics.
- Devulcanization process maturation:Chemical reprocessing of sulfur-cured rubbers now yields virgin-equivalent compounds suitable for under-hood applications.
Market Restraints
- EPDM feedstock volatility:Coolant and heater hose recovery dominates volume but requires energy-intensive devulcanization, compressing margins against thermoplastic alternatives.
- German compounder concentration:Specialized reprocessing capacity clusters in Central Europe, creating geographic supply risk for North American and Asian OEMs.
- Material separation complexity:Multi-layer hose constructions with embedded reinforcement fibers demand manual disassembly, limiting automation scale.
Strategic Opportunities
- Japan's Automobile Recycling Law targets:METI-specified resource circulation mandates create guaranteed offtake volumes for reprocessed hose compounds.
- Mono-material thermoplastic designs:Simplified mechanical recycling without separation stages opens margin premiums in electric vehicle thermal management systems.
- Independent garage incentive platforms:Third-party collection networks reward segregated sorting, expanding feedstock access beyond manufacturer-controlled channels.
Industry Challenges
- Devulcanization chemist scarcity:Specialized expertise in sulfur bond cleavage and compound reformulation concentrates among aging technical workforces in Germany and Japan.
- ISO 14021 environmental claims verification:Recycled content certifications require chain-of-custody documentation that many legacy collection networks cannot provide.
- Legacy ERP integration:Reverse logistics tracking systems must interface with established forward supply chain software, creating IT implementation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closed-Loop Recycling Programs for Automotive Hoses Market |
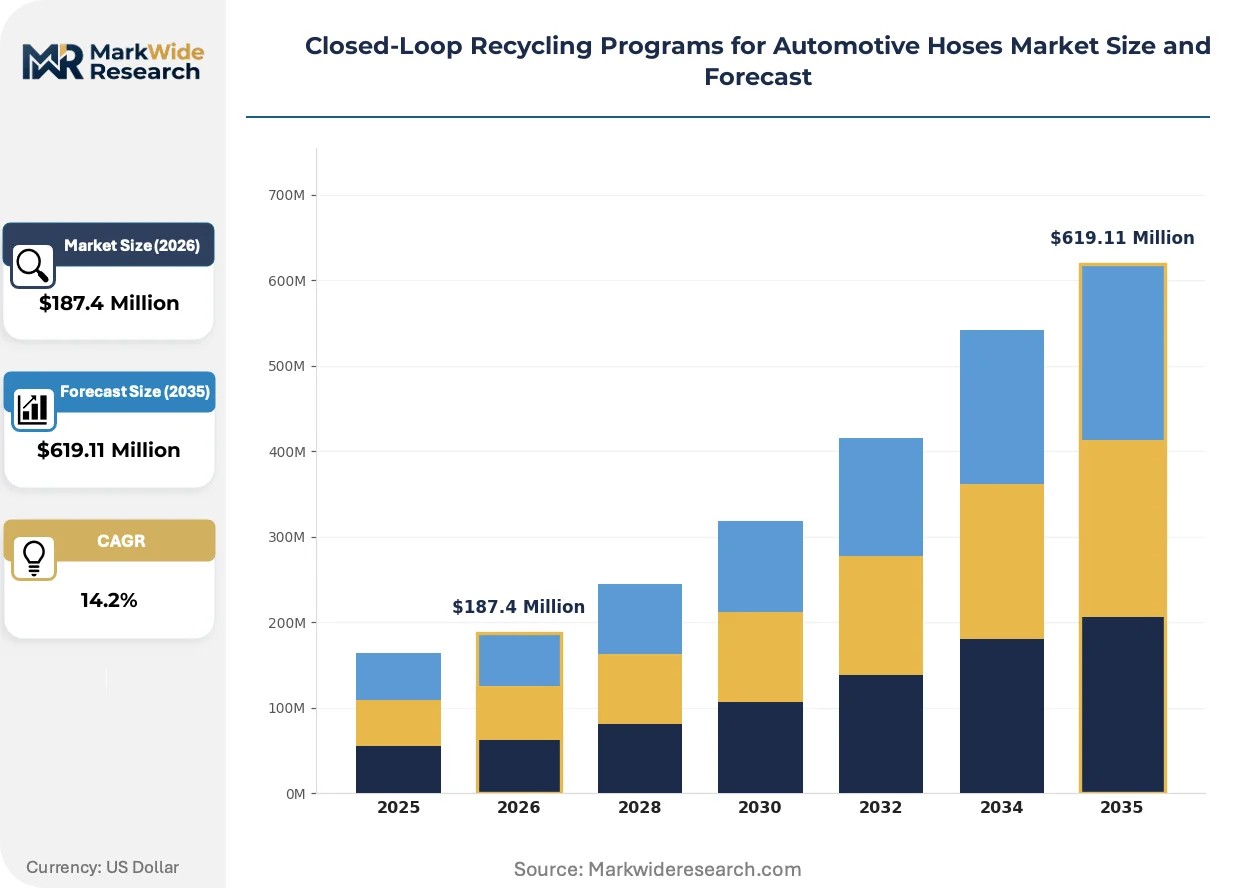
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Post-Consumer, Manufacturer-Led, Multi-Component, Single-Material, Incentive-Based Material Type: EPDM, Nitrile, Neoprene, Silicone, Thermoplastic Elastomers End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Collection Method: Drop-Off Centers, Curbside Pickup, Trade-In Programs, Reverse Logistics |
| Companies Covered | Continental AG, Gates Corporation, Hutchinson SA, Nichirin Co. Ltd., Toyoda Gosei Co. Ltd., Sumitomo Riko Company Limited, Cooper Standard Holdings Inc., Yokohama Rubber Co., Trelleborg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closed-Loop Recycling Programs for Automotive Hoses Market Trends and Innovations
Active chemistry breakthroughs and procurement recalibrations are compressing traditional recycling timelines while regulatory frameworks harden around material provenance documentation.
Thermoplastic elastomer mono-material construction is rewriting hose design specifications across electric vehicle thermal systems. OEMs specify these compounds for battery cooling circuits where temperature cycling demands formerly required cross-linked rubber. The shift enables direct melt recompounding without devulcanization stages, collapsing reprocessing energy requirements and expanding reapplication potential into non-automotive industrial tubing.
REACH authorization list expansions are tightening candidate substance thresholds in recycled elastomers entering European supply chains. ECHA's evolving restrictions on phthalate plasticizers and heavy metal catalyst residues force compounders to invest in purification stages or risk market exclusion. German and French OEMs now mandate batch-level testing documentation that was previously waived for post-industrial scrap.
Fleet operators are consolidating hose replacement procurement under long-term service contracts that bundle collection obligations with supply agreements. North American heavy-duty vehicle lessors now specify reprocessed compound minimums in their maintenance tenders, displacing spot-market purchasing. This concentration shifts bargaining power toward large fleet managers and away from traditional aftermarket distributors.
Closed-Loop Recycling Programs for Automotive Hoses Market Segmentation
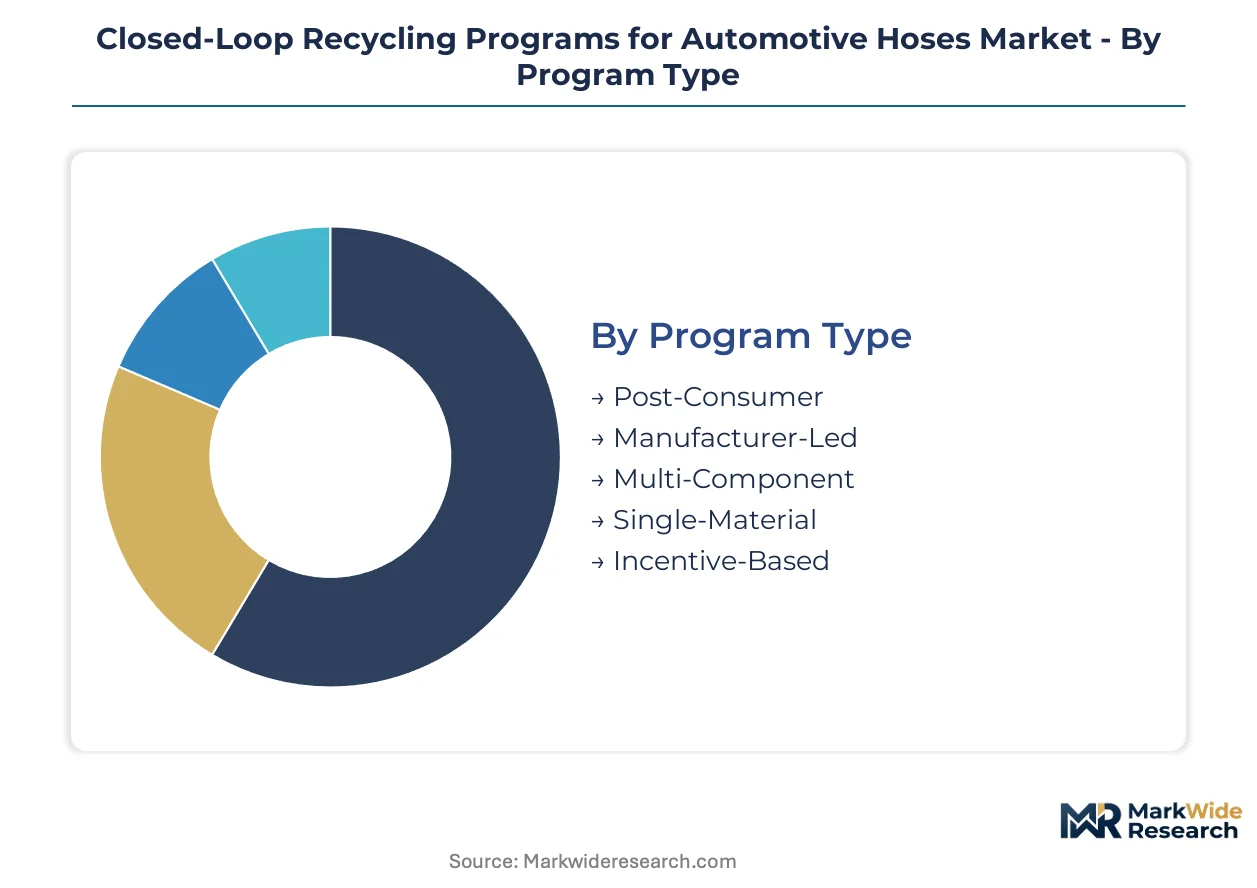
Program design choices determine reprocessing economics and regulatory compliance pathways for automotive hose recovery. Material specifications and collection infrastructure investments lock in margin structures that resist short-term adjustment. Segmentation reveals where capital deployment concentrates and which technical approaches command pricing premiums.
Program Type:
Cost tier stratification separates capital-intensive captive systems from asset-light third-party platforms.
- Post-Consumer:Collection networks target end-of-life vehicle dismantlers and independent repair facilities for hose segregation. European Union member states with mandatory producer responsibility schemes generate predictable feedstock volumes that anchor regional reprocessing capacity.
- Manufacturer-Led:OEM-controlled return protocols leverage supplier contract terms to mandate reverse logistics participation. Germany's automotive clusters concentrate these programs due to integrated compounder proximity and REACH compliance documentation requirements.
- Multi-Component:Recovery of layered hose constructions with embedded reinforcement demands manual disassembly stages that limit automation scale.
- Single-Material:Mono-material designs enable direct mechanical reprocessing without separation chemistry.
- Incentive-Based:Third-party platforms reward independent garages for segregated collection, expanding feedstock access beyond manufacturer channels.
Manufacturer-Led programs lead on scale; Incentive-Based programs lead on momentum.
Material Type:
Reprocessing energy requirements create margin stratification across sulfur-cured and thermoplastic streams.
- EPDM:Ethylene-propylene-diene monomer dominates coolant and heater hose applications across internal combustion engine vehicles. Devulcanization demands specialized sulfur bond cleavage chemistry that concentrates among German and Japanese technical workforces.
- Thermoplastic Elastomers:Melt-reprocessable compounds enable direct recompounding without chemical transformation stages. Electric vehicle battery cooling circuits specify these materials for temperature cycling performance formerly requiring cross-linked rubber.
- Nitrile:Acrylonitrile-butadiene rubber serves fuel system applications where permeation resistance remains critical.
- Neoprene:Chloroprene-based compounds persist in air conditioning and refrigerant hose segments.
- Silicone:High-temperature stability supports turbocharger and exhaust gas recirculation tubing.
EPDM leads on scale; Thermoplastic Elastomers lead on momentum.
End User:
Procurement authority determines contract structure and collection obligation allocation.
- OEMs:Original equipment manufacturers mandate return protocols through supplier agreements and control design specifications that enable or complicate recycling. European Green Deal directives force redesign of these contracts around mandatory recovery quotas.
- Tier-1 Suppliers:Hose fabricators face dual pressure from upstream material costs and downstream OEM compliance requirements.
- Vehicle Assemblers:Final production facilities generate post-industrial scrap streams with chain-of-custody documentation advantages.
- Aftermarket Providers:Independent distributors and service chains participate through incentive-based collection platforms.
OEMs lead on scale; Aftermarket Providers lead on momentum.
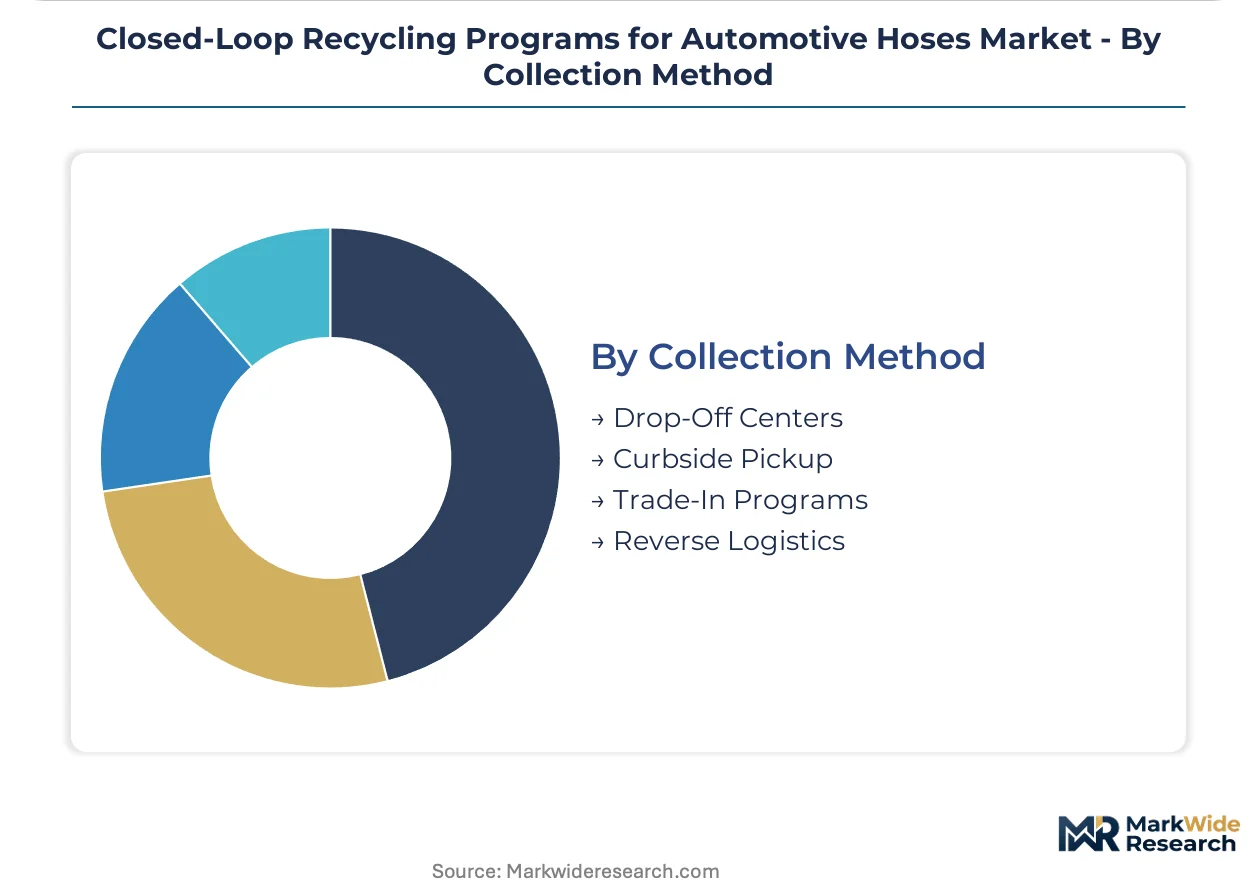
Collection Method:
Reverse logistics integration requirements separate established supply chain participants from new network builders.
- Drop-Off Centers:Designated collection points at dismantling facilities concentrate feedstock geographically. North American heavy-duty fleet operators anchor these networks through predictable replacement volumes.
- Curbside Pickup:Municipal waste streams capture dispersed post-consumer material with contamination risks that complicate reprocessing.
- Trade-In Programs:Transaction-linked collection ties recovery to new product sales, common in premium aftermarket segments.
- Reverse Logistics:Dedicated return systems integrated with forward supply chain software require ERP implementation investment.
Drop-Off Centers lead on scale; Reverse Logistics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive clusters concentrate the bulk of closed-loop recycling infrastructure investment, with compounder proximity and REACH compliance documentation requirements creating self-reinforcing geographic advantages for hose recovery programs.
Germany
EPDM devulcanization capacity clusters around industrial rubber processing centers serving coolant and heater hose streams. REACH candidate substance restrictions on phthalate plasticizers force batch-level testing documentation that was previously waived for post-industrial scrap. The KBA enforces end-of-life vehicle material recovery quotas that tighten supplier contract terms around mandatory return protocols.
United States
Heavy-duty fleet operators generate predictable hose replacement volumes that anchor captive collection network economics across North American commercial vehicle markets. The EPA oversees hazardous waste classifications affecting spent hose disposal, elevating compliance costs for open-loop disposal pathways. Michigan and Ohio automotive corridors host integrated compounder operations that reprocess sulfur-cured rubber streams for under-hood applications.
Japan
METI-specified resource circulation mandates under the Automobile Recycling Law create guaranteed offtake volumes for reprocessed hose compounds. Devulcanization expertise concentrates among aging technical workforces in Nagoya and Osaka industrial zones. Toyota City and surrounding Aichi Prefecture facilities specialize in small-diameter fuel and vapor recovery hoses where material purity standards remain stringent.
China
Electric vehicle manufacturers scale collection partnerships faster than conventional OEMs, driving thermoplastic elastomer adoption in battery cooling circuits. The MIIT promotes resource circulation through specified recycling targets that align with dual carbon goals. Yangtze River Delta manufacturing hubs integrate reverse logistics tracking with forward supply chain software to manage post-industrial scrap documentation.
France
EU Green Deal directives force redesign of supplier contracts around mandatory recovery quotas rather than optional collection incentives. ECHA's evolving restrictions on heavy metal catalyst residues require compounders to invest in purification stages or risk market exclusion. The Auvergne-Rhône-Alpes region hosts specialized reprocessing capacity serving layered hose constructions with embedded reinforcement fibers.
Closed-Loop Recycling Programs for Automotive Hoses Market Competitive Landscape
Global majors compete with regional champions across reprocessing technology and captive feedstock access, with market structure tiering between integrated rubber conglomerates and specialized hose fabricators. Manufacturer-led programs dominate operational scale because participants control design specifications and mandate return protocols through supplier contracts. Two archetypes prevail: vertically integrated tire-and-rubber operators leveraging shared compounder infrastructure, and captive collection network builders serving concentrated fleet segments. Dominant competitive moves include backward integration into devulcanization capacity and long-term offtake agreements with specialized compounders before feedstock competition intensifies.
Within the integrated rubber conglomerate tier, Continental AG exemplifies backward integration into reprocessed compound production through shared tire and rubber operations. Among specialized hose fabricators, Nichirin Co. Ltd. and Gates Corporation occupy positions defined by feedstock stream control—Nichirin through precision small-diameter applications requiring material purity, Gates through captive networks serving predictable replacement cycles. These three anchors illustrate how design specification authority and collection infrastructure ownership determine competitive positioning in closed-loop recovery economics.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Hutchinson SA |
| Nichirin Co. Ltd. |
| Toyoda Gosei Co. Ltd. |
| Sumitomo Riko Company Limited |
| Cooper Standard Holdings Inc. |
| Yokohama Rubber Co. |
| Trelleborg |
| Others |
Pricing and Supply Chain Analysis
OEM mandates for mono-material thermoplastic designs in electric vehicle battery cooling circuits are forcing compounders to retool purification stages, compressing margins on EPDM streams while elevating pricing power for TPE specialists with certified reprocessing chains.
Pricing Analysis
Input-cost pass-through from sulfur-cured rubber devulcanization dominates pricing structures, with energy-intensive EPDM reprocessing commanding contract-based long-term offtake agreements to hedge feedstock volatility. Price differentiation separates ISO 14021-certified premium tiers from undocumented economy streams, while REACH batch-testing requirements add certification-driven cost layers. Pricing pressure stems from thermoplastic elastomer substitution in under-hood applications, eroding EPDM volume premiums. Fleet operators show highest price sensitivity on spot-market purchases, whereas OEMs with mandated recovery quotas accept premium pricing for chain-of-custody documentation.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States form a hub-and-spoke pattern anchoring reprocessed compound flows, with German compounder concentration creating geographic chokepoints for North American OEMs. Raw material dependencies center on post-consumer EPDM feedstock from coolant hose replacement cycles, devulcanization chemical inputs, and virgin-equivalent compound certification services. Supply chain risk concentrates in single-source vulnerability for specialized sulfur bond cleavage expertise among aging technical workforces in Central Europe. Distribution runs through captive collection networks serving heavy-duty fleet operators and third-party incentive platforms targeting independent garages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Japanese and European regulatory mandates create guaranteed offtake premiums unavailable in less structured North American jurisdictions, rewarding early positioning in METI-specified or EU Green Deal-compliant supply corridors.
For Market Incumbents: Deploy backward integration into devulcanization capacity to secure feedstock streams before specialized compounder competition intensifies. Consolidate supplier contract terms around mandatory return protocols as EU member states tighten material recovery quotas. Invest in ISO 14021 certification infrastructure to defend margin position against uncertified economy-tier entrants.
For New Entrants and Emerging Players: Capture incentive-based collection platform white space serving independent garages outside manufacturer-controlled channels, where segregation rewards expand feedstock access. Target thermoplastic elastomer reprocessing for electric vehicle thermal management systems, the fastest-growing material segment. Pursue joint-venture structures with established compounders to bypass devulcanization expertise scarcity.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized reprocessing facilities holding REACH-compliant purification capabilities and long-term OEM offtake agreements. Long-term viability favors compounders with geographic diversification beyond German concentration risk. Watch Japan's Automobile Recycling Law enforcement intensity as the signal indicating guaranteed volume expansion versus discretionary program growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Devulcanization Capacity | Captive sulfur-cured rubber reprocessing secures EPDM feedstock streams against compounder competition. |
| Long-term Supply Agreement with Fleet Operators | Predictable heavy-duty vehicle replacement volumes anchor collection network economics across North America. |
| Green Certification Program | ISO 14021 environmental claims verification unlocks OEM premium pricing and regulatory compliance pathways. |
| Joint Venture with Thermoplastic Elastomer Compounders | Shared battery cooling circuit expertise accelerates electric vehicle thermal management system penetration. |
| Geographic Manufacturing Footprint Expansion | Regional reprocessing capacity in Asia-Pacific reduces dependency on German devulcanization concentration. |
Research Methodology
Coverage spans Germany, Japan, the United States, China, and France, with primary inputs from each market through structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, devulcanization technical specialists, and fleet maintenance operators. Secondary validation draws from EPA hazardous waste classifications, REACH candidate substance restriction updates, METI Automobile Recycling Law enforcement notices, EU Green Deal directive implementations, and customs trade data on elastomer compound flows. Bottom-up feedstock volume estimates triangulate against top-down OEM recovery quota mandates.
Granularity-level modeling disaggregates the analysis window across program type, material specification, end-user procurement authority, and collection method dimensions, with vehicle propulsion architecture and regional regulatory framework as cross-cutting stratifiers. CAGRs derive from logistic curve penetration assumptions for thermoplastic elastomer substitution and mandated recovery quota phase-in schedules. Industry-specific forecast inputs include electric vehicle production ramp rates and devulcanization process energy efficiency improvement trajectories.
Feedstock competition intensity, regulatory enforcement variance across member states, and devulcanization chemist workforce attrition are the dominant revision risks that could compress or extend modeled growth trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Asia Pacific Green Cement Market
Environment & Sustainability
Global Habitat Restoration Market
Environment & Sustainability
Solar Frames Market
Environment & Sustainability
Artificial Green Wall Market
Environment & Sustainability
Qatar Solid Waste Management Market
Environment & Sustainability
North America Waste Management Market
Environment & Sustainability
China Cloud Seeding Market
Environment & Sustainability
E-Scrap Recycling Market
Environment & Sustainability
Sludge Management Equipment Market
Environment & Sustainability
Waste Paper Recycling Market
Environment & Sustainability
Global Cloud Seeding Equipment Market
Environment & Sustainability
Indoor Air Purification Market
Environment & Sustainability
Waste Recycling Services Market
Environment & Sustainability
Carbon Capture and Utilization Market
Environment & Sustainability
Global Biological Wastewater Treatment Market
Environment & Sustainability
Carbon Credit Market