
 Global Residential Water Treatment Devices Market | 2026-2036
Global Residential Water Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Residential Water Treatment Devices Market Foresight
Health-conscious homeowners is bifurcating from price-sensitive renters as the dominant buyer archetype in residential water treatment. Pentair leverages its captive supply of membrane components to dominate North American whole-house installations. A. O. Smith Corporation anchors the Asian market through localized manufacturing of reverse osmosis systems. Kent RO Systems specializes in compact countertop units that navigate India's space-constrained urban apartments.
Residential water treatment devices encompass point-of-entry and point-of-use systems engineered to reduce contaminants through physical filtration, chemical adsorption, or electromagnetic radiation, typically operating at household flow rates between two and fifteen gallons per minute. These devices serve the essential commercial purpose of delivering potable water compliant with local health standards where municipal infrastructure proves insufficient. Reverse osmosis systems occupy the premium tier due to their ability to strip dissolved solids, while activated carbon filters sustain volume leadership in replacement cartridge sales. Ultraviolet purifiers represent the fastest-growing technology segment as consumers prioritize chemical-free disinfection methods.
The EPA regulates contaminant limits under the Safe Drinking Water Act, while the EU Drinking Water Directive and China's MEE groundwater quality standards collectively force manufacturers to certify multi-country compliance. ISO 9001 and NSF/ANSI 42, 53, and 401 protocols shape product testing regimes and market access thresholds. Stakeholders must monitor evolving PFAS maximum contaminant levels across jurisdictions to anticipate filter replacement cycles and certification investments.
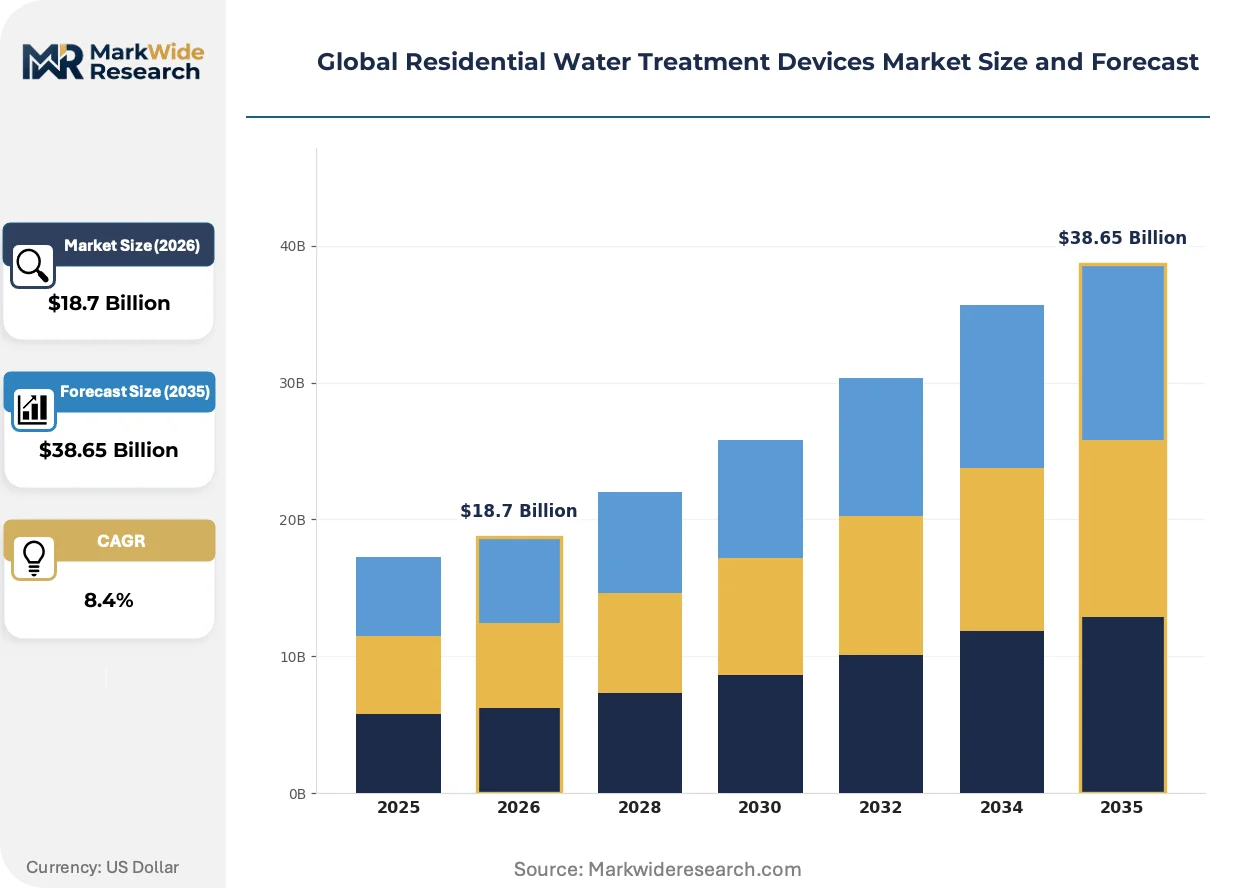
Market Dynamics
The EPA's tightened PFAS and lead standards are compressing replacement cycles across municipal-connected households, while membrane supply concentration in East Asia reshapes equipment availability timelines for North American installers.
Growth Catalysts
- PFAS Maximum Contaminant Levels:The EPA's revised enforceable limits for per- and polyfluoroalkyl substances in drinking water are compelling homeowners in suburban developments to upgrade from pitcher filters to whole-house systems.
- Groundwater contamination clusters:Industrial legacy sites in Germany's Ruhr Valley and China's North China Plain are driving point-of-entry system penetration among single-family households dependent on private wells.
- Ultraviolet disinfection:Chemical-free purification methods are gaining preference among health-conscious buyers seeking alternatives to chlorine-based treatment, particularly in residential applications with immunocompromised occupants.
Market Restraints
- Membrane supply concentration:Reverse osmosis membrane production concentrates in South Korea and Japan, exposing North American and European assemblers to shipping cost volatility and extended lead times.
- Activated carbon raw material costs:Coconut shell charcoal supply from Southeast Asian processors faces agricultural yield fluctuations that compress margins for replacement cartridge manufacturers.
- Installation skill scarcity:Whole-house system deployment requires certified plumbing integration, and qualified technician pools in the United States and Germany lag demand growth by approximately eighteen months.
Strategic Opportunities
- India's urban apartment segment:Compact countertop reverse osmosis units remain underpenetrated in Mumbai and Bangalore high-rises where kitchen space constraints exclude under-sink alternatives.
- EU Drinking Water Directive recast:The 2021 revised directive's tightened microbiological parameters create compliance-driven replacement demand across Italy and Spain's aging municipal networks.
- Smart monitoring convergence:IoT-enabled filter life tracking combined with automated reorder platforms is opening recurring revenue streams for original equipment manufacturers previously dependent on hardware margins alone.
Industry Challenges
- Multi-jurisdiction certification timelines:NSF/ANSI 401 certification for emerging contaminants requires eighteen-to-twenty-four-month validation cycles that delay product launches in California and Massachusetts.
- Legacy infrastructure integration:Pre-1980 residential plumbing in the United Kingdom and northeastern United States contains lead service lines that complicate point-of-entry system specification and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Residential Water Treatment Devices Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis Systems, Ultrafiltration Units, Ultraviolet Purifiers, Activated Carbon Filters, Ion Exchange Softeners Technology: Membrane Filtration, UV Radiation, Adsorption, Ion Exchange, Electrochemical Oxidation Use Case: Drinking Water Treatment, Laundry Water Purification, Cooking Water Filtration, Bathing Water Enhancement, Irrigation Water Quality End User: Homeowners, Property Managers, Rental Housing Operators, Vacation Property Custodians, Domestic Facilities |
| Companies Covered | Pentair, A. O. Smith Corporation, Culligan International Company, 3M Company, Kent RO Systems, LG Electronics, Eureka Forbes, Whirlpool Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Residential Water Treatment Devices Market Shifts & Advancements
Connected diagnostics and modular filtration architectures are displacing static equipment sales with service-layer monetization, while regulatory fragmentation across the United States, European Union, and China forces manufacturers toward flexible certification platforms.
Electrochemical advanced oxidation is decomposing dissolved organic contaminants at residential flow rates without chemical dosing. Wealthy homeowners in Scottsdale, Arizona and Perth, Australia are piloting these systems for agricultural runoff protection. This technology is decomposing the traditional activated carbon replacement cycle by eliminating consumable media entirely.
REACH restrictions on perfluorinated membrane precursors are compelling European manufacturers to reformulate thin-film composite chemistries. The ECHA's 2023 proposal to classify certain fluoropolymers as substances of very high concern is accelerating research into ceramic and graphene oxide alternatives. German and Dutch system integrators are stockpiling legacy membranes while qualifying substitute materials.
Subscription-based filter replacement programs are displacing retail cartridge purchases among millennial homeowners in Toronto and Sydney. D2C platforms with predictive shipping algorithms are capturing loyalty from installers who previously sourced through wholesale distributors. This shift is most visible in Australia's southeastern states where municipal water quality variability drives higher replacement frequency than manufacturer-standard intervals assume.
Global Residential Water Treatment Devices Market Segmentation
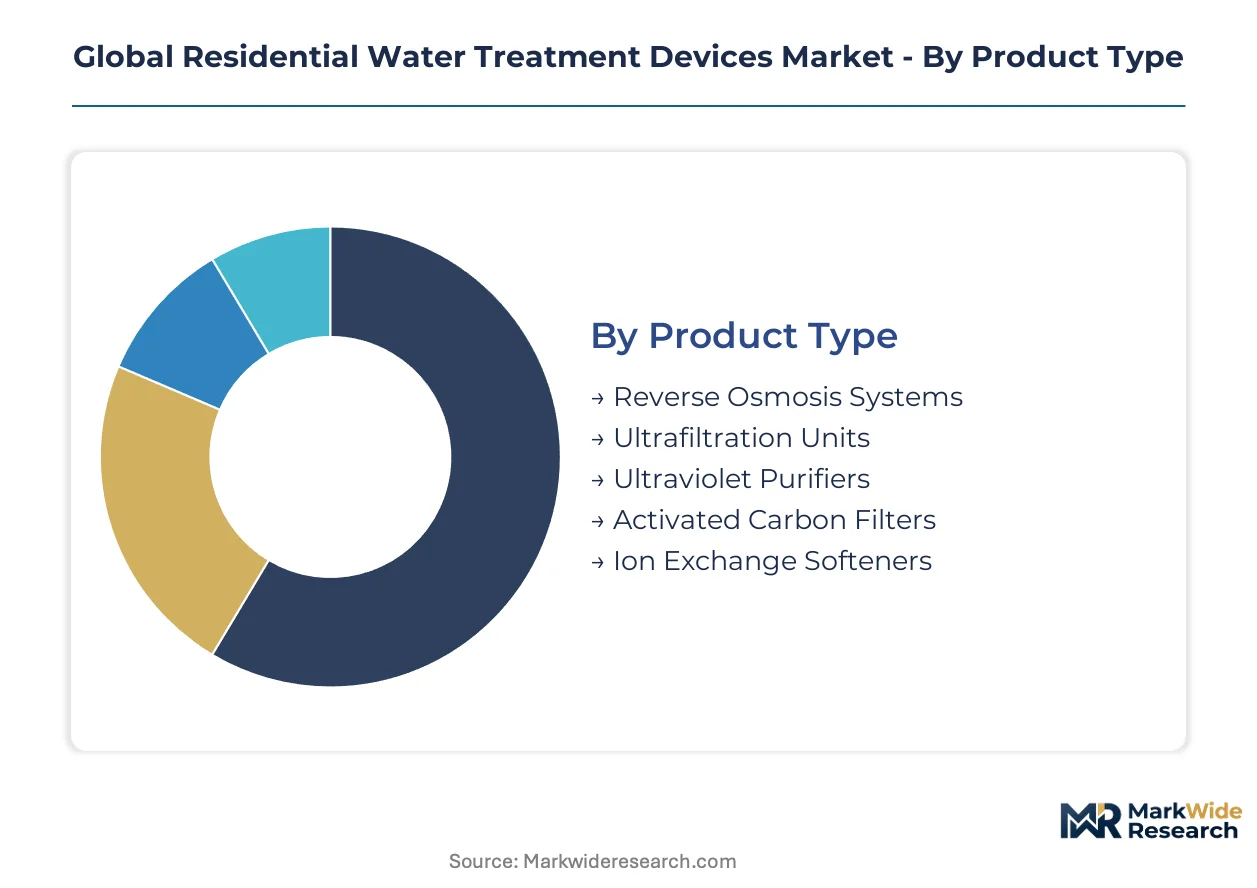
Residential water treatment devices fragment across five distinct product architectures, each commanding divergent channel strategies. Reverse osmosis systems move through certified installer networks, while activated carbon filters dominate retail and e-commerce replenishment cycles. Understanding these flow patterns reveals where margin pools concentrate and which segments sustain recurring revenue versus one-time hardware transactions.
Product Type:
Channel configuration varies sharply by installation complexity and replacement frequency. Whole-house systems require plumbing contractor relationships, whereas countertop units bypass professional installation entirely.
- Reverse Osmosis Systems:These multi-stage units force water through semi-permeable membranes rated at 0.0001 micron pore size, stripping dissolved solids including arsenic and fluoride. Pentair and A. O. Smith Corporation dominate North American whole-house installations through captive membrane supply and localized manufacturing. Demand concentrates among suburban homeowners facing EPA-mandated PFAS compliance deadlines.
- Ultraviolet Purifiers:Mercury-vapor or LED-based UV-C emitters deliver 40 millijoules per square centimeter dosage to neutralize microbiological contaminants without chemical residuals. Scottsdale, Arizona and Perth, Australia pilot these systems for agricultural runoff protection, with health-conscious buyers prioritizing chemical-free disinfection for immunocompromised household members.
- Ultrafiltration Units:Hollow-fiber membranes rated at 0.01 micron retain bacteria and viruses while preserving mineral content, popular in Germany's Ruhr Valley private well applications.
- Activated Carbon Filters:Coconut shell or bituminous coal substrates adsorb chlorine, VOCs, and organic compounds through Van der Waals forces, sustaining the highest replacement cartridge volumes.
- Ion Exchange Softeners:Cation resin beads swap calcium and magnesium ions for sodium or potassium, addressing hardness in Midwestern United States and North China Plain groundwater.
By volume, Activated Carbon Filters leads through replacement cartridge replenishment. By growth pace, Ultraviolet Purifiers is climbing the fastest on chemical-free preference tailwinds.
Technology:
Cost tier stratification separates capital-intensive membrane platforms from low-barrier adsorption methods, with electrochemical systems emerging at the premium frontier.
- Membrane Filtration:Thin-film composite polyamide layers on polysulfone supports achieve 98-99% salt rejection at residential flow rates. Production concentrates in South Korea and Japan, exposing assemblers to shipping volatility.
- UV Radiation:Low-pressure amalgam lamps or UV-C LEDs provide instant microbiological kill without consumable media, gaining preference among millennial homeowners seeking maintenance minimization.
- Adsorption:Activated carbon and catalytic carbon substrates remove chlorine taste, odor, and organic precursors through surface binding, dominating entry-level pitcher and faucet-mount segments.
- Ion Exchange:Synthetic resin beads regenerated with brine solution address water hardness, with demand clustering in single-family homes dependent on private wells.
- Electrochemical Oxidation:Boron-doped diamond electrodes generate hydroxyl radicals that mineralize dissolved organics without chemical dosing, piloting in wealthy Scottsdale and Perth households.
By installed base, Membrane Filtration leads. By technology substitution momentum, Electrochemical Oxidation is gaining share fastest as it eliminates replacement media entirely.
Use Case:
Application maturity separates potable water compliance-driven demand from discretionary quality-of-life upgrades, with irrigation representing the most price-sensitive frontier.
- Drinking Water Treatment:Point-of-use reverse osmosis and ultrafiltration systems deliver EPA, EU Drinking Water Directive, and China's MEE groundwater quality compliance, commanding the highest per-unit spending and certification requirements.
- Cooking Water Filtration:Dedicated faucet-mount or under-sink units address chlorine taste and heavy metals for food preparation, popular in India's space-constrained Mumbai and Bangalore apartments.
- Laundry Water Purification:Whole-house softening and filtration protects appliance longevity and fabric quality, with demand from suburban United States homeowners in hard-water regions.
- Bathing Water Enhancement:Showerhead filters and whole-house dechlorination target dermal absorption concerns, a discretionary segment sensitive to wellness marketing.
- Irrigation Water Quality:Sediment and chlorine reduction for landscaping applications, price-elastic and dependent on drought severity in Australia and southwestern United States.
By revenue concentration, Drinking Water Treatment leads. By penetration gap, Cooking Water Filtration is expanding most quickly in dense Asian urban housing.
End User:
Customer type determines procurement authority and replacement discipline, with institutional buyers sustaining contract-based volume against fragmented homeowner decision-making.
- Homeowners:Individual purchasers with full installation autonomy and upgrade discretion, bifurcating between health-conscious upgraders and price-sensitive maintenance deferrers.
- Property Managers:Multi-unit residential operators in Germany and the United States specifying point-of-entry systems for tenant retention and liability reduction.
- Rental Housing Operators:Institutional landlords balancing capital expenditure constraints against regulatory compliance, favoring portable point-of-use units over permanent installation.
- Vacation Property Custodians:Seasonal occupancy patterns drive intermittent-use system selection and winterization requirements.
- Domestic Facilities:Estate and household staff managing complex water quality for specialized applications including aquariums, pools, and specialty appliances.
By absolute unit volume, Homeowners leads. By contract value stability, Property Managers is gaining share fastest through specification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes Water Authority's regional filtration infrastructure underwrites Michigan's outsized role in North American point-of-entry system demand. Municipal pipeline networks in the Ruhr Valley and North China Plain similarly concentrate replacement cycles where aging distribution meets tightened contaminant standards.
United States
Suburban homeowners in Phoenix and Scottsdale upgrade to whole-house reverse osmosis as the EPA enforces PFAS maximum contaminant levels. The Safe Drinking Water Act's emerging contaminant protocols compress replacement cycles across municipal-connected households. Installers in Maricopa County face eighteen-month backlogs for certified plumbing integration.
Germany
Ruhr Valley private well owners deploy ultrafiltration units against industrial legacy groundwater contamination. The EU Drinking Water Directive recast tightens microbiological parameters for aging municipal networks. System integrators in Düsseldorf and Essen stockpile thin-film composite membranes ahead of REACH fluoropolymer restrictions.
China
North China Plain households dependent on contaminated groundwater drive point-of-entry penetration in suburban Beijing developments. The MEE's groundwater quality standards force multi-province certification compliance from domestic manufacturers. Compact reverse osmosis units dominate kitchen retrofit demand in Shanghai and Shenzhen high-rises.
India
Mumbai and Bangalore apartment dwellers navigate space constraints through countertop ultrafiltration units. The Bureau of Indian Standards certifies domestic membrane assemblies for arsenic and fluoride removal. Kent RO Systems anchors supply to urban clusters where municipal infrastructure fails potable standards.
Australia
Perth households pilot electrochemical oxidation systems for agricultural runoff protection. The Therapeutic Goods Administration's parallel jurisdiction with state water regulators creates dual certification pathways. Subscription-based filter replacement platforms capture millennial homeowners in Melbourne and Sydney southeastern corridors.
Global Residential Water Treatment Devices Market Competitive Landscape
Listed leaders compete with private specialists across membrane supply and installation service networks. The market structures around three tiers: diversified industrial conglomerates with captive component supply, regional water specialists with installer channel control, and appliance manufacturers leveraging retail distribution. Consolidation pressures concentrate in North American whole-house segments where plumbing certification creates barriers. Strategic moves favor backward integration into membrane production and predictive service platform acquisition.
Among diversified industrial players, Pentair and A. O. Smith Corporation exemplify scale-driven positioning through captive supply chains and localized manufacturing footprints. Kent RO Systems occupies a specialist tier focused on compact system architectures for space-constrained Asian urban housing. These three anchors represent divergent competitive vectors: membrane supply concentration, geographic manufacturing proximity, and product form factor specialization.
| Leading Market Players |
|---|
| Pentair |
| A. O. Smith Corporation |
| Culligan International Company |
| 3M Company |
| Kent RO Systems |
| LG Electronics |
| Eureka Forbes |
| Whirlpool Corporation |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
NSF/ANSI 401 certification for emerging contaminants gates both membrane supplier qualification and price differentiation across California and Massachusetts markets simultaneously. Equipment assemblers face eighteen-to-twenty-four-month validation cycles that compress margin recovery timelines while locking out uncertified competitors from premium tier positioning.
Pricing Analysis
Volume-discount tiering separates certified installer networks from retail replenishment channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in replacement cartridges is intensifying because coconut shell charcoal supply from Southeast Asian processors faces agricultural yield fluctuations. Rental housing operators exhibit highest price sensitivity while health-conscious suburban homeowners demonstrate lowest elasticity.
Supply Chain Analysis
Inventory lead times for thin-film composite membranes now stretch eighteen months for North American assemblers. Production concentrates in South Korea and Japan, drawing from polyamide precursor chemicals and polysulfone support substrates. Single-source vulnerability in fluoropolymer supply chains is accelerating as ECHA REACH restrictions compound procurement risk. Distribution runs through certified plumbing contractor networks for whole-house systems and retail e-commerce for countertop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential water treatment sits in early-cycle expansion as EPA PFAS enforcement deadlines accelerate replacement cycles across suburban municipal connections. Penetration gaps in India's space-constrained apartments and Australia's subscription-ready millennial segments sustain runway ahead of saturation.
For Market Incumbents: Shield membrane supply positions through captive production or long-term offtake agreements with South Korean and Japanese substrate manufacturers. Electrochemical oxidation systems threaten to displace activated carbon replacement cycles entirely; accelerate R&D into ceramic and graphene oxide membrane alternatives ahead of REACH fluoropolymer restrictions.
For New Entrants and Emerging Players: Differentiate on smart monitoring convergence with IoT-enabled filter life tracking and automated reorder platforms. India's Mumbai and Bangalore high-rise apartments represent the most penetrable white-space for compact countertop ultrafiltration units. Pursue direct-to-consumer launch with predictive shipping algorithms to bypass wholesale distributor incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming water treatment divisions lacking installer channel control. Long-term viability hinges on recurring revenue transition from hardware margins to subscription-based service layers. Watch smart monitoring adoption rates in Australia's southeastern states as the inflection indicator for platform monetization maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Captive polyamide supply shields Pentair and A. O. Smith from East Asian shipping volatility. |
| Smart Monitoring Platform Acquisition | IoT filter tracking enables recurring revenue streams beyond one-time hardware transactions. |
| REACH-Compliant Membrane Reformulation | Ceramic and graphene oxide alternatives future-proof European manufacturing against fluoropolymer restrictions. |
| Direct-to-Consumer Channel Expansion | Predictive shipping algorithms capture millennial loyalty from wholesale distributors in Australia. |
| Certified Installer Network Consolidation | Plumbing integration scarcity in Maricopa County and Germany creates channel control premiums. |
Research Methodology
A standing panel of membrane manufacturing executives, certified plumbing contractors, municipal water quality officers, and retail category managers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from EPA enforcement announcements, EU Drinking Water Directive recast documentation, customs records for membrane substrate trade flows, and NSF certification databases. Bottom-up unit shipment modeling triangulated against top-down household penetration estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, technology tier, use case application, and end-user procurement authority. CAGRs derived from fitted growth curves applied to replacement cycle compression data and regulatory compliance deadline schedules. Industry-specific inputs incorporated membrane supply lead times and certification timeline distributions.
Material uncertainties — tariff escalation on East Asian substrate imports, ECHA fluoropolymer restriction finalization, municipal infrastructure replacement funding volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement pacing and household upgrade propensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Home Water Softener System Market