
 Africa Zero Liquid Discharge System Market | 2026-2036
Africa Zero Liquid Discharge System Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Zero Liquid Discharge System Market Outlook
Mining houses are redrawing the buyer landscape for zero liquid discharge infrastructure across Africa, displacing municipal utilities as the primary procurement anchor. Veolia Water Technologies leverages its crystallizer expertise to anchor contracts in South Africa's platinum belt. SUEZ Water Technologies & Solutions competes through membrane distillation integration that cuts thermal energy loads for remote mine sites. Thermax Limited dominates India's export channel into African power and chemical installations.
Africa zero liquid discharge systems combine evaporators, crystallizers, and membrane trains to recover dissolved solids from industrial wastewater, achieving total dissolved solids below measurable thresholds. The technology targets water-stressed jurisdictions where surface discharge permits carry strict salinity caps. Reverse osmosis pre-treatment leads technology adoption due to lower capital thresholds, though crystallization commands margin pools where complete salt recovery justifies premium engineering. Mining and oil & gas end users drive application growth, with modular installations gaining traction against centralized builds for remote extraction sites.
South Africa's Department of Water and Sanitation enforces effluent quality standards that prohibit saline discharge to receiving waters, while Botswana's Department of Environmental Affairs mandates closed-loop systems for new mining licenses. Compliance deadlines compress procurement cycles and favor vendors with local service networks. Stakeholders must monitor regulatory harmonization across the Southern African Development Community, as cross-border water treaty obligations extend discharge accountability to upstream industrial zones.
Market Dynamics
Membrane distillation integration is compressing crystallizer energy loads across Africa's mining belt, enabling remote site deployment where thermal evaporation previously failed on power economics. This technology shift is redrawing procurement criteria toward modular, containerized systems.
Growth Catalysts
- Saline Discharge Prohibitions:South Africa's Department of Water and Sanitation enforces effluent quality standards that bar saline release to receiving waters, compelling mining houses to install closed-loop recovery infrastructure.
- Platinum Belt Water Stress:Concentrated processing demand in South Africa's Bushveld Complex intersects with aquifer depletion, forcing operators to recover dissolved solids rather than extract fresh groundwater.
- Membrane Distillation Maturation:Advances in hydrophobic membrane durability reduce thermal energy requirements by half, making ZLD economically viable for mid-scale remote extraction sites.
Market Restraints
- Capital Intensity Barrier:Crystallizer trains require stainless steel alloys and precision welding that concentrate supply with European and East Asian fabricators, extending lead times.
- Power Infrastructure Gap:Remote Botswana mine sites lack grid stability for continuous thermal evaporation, forcing diesel generator dependence that inflates operating expenditure.
- Specialized Technician Scarcity:Membrane cleaning protocols and crystallizer maintenance demand trained operators, a skill set concentrated in South Africa's urban centers.
Strategic Opportunities
- Copperbelt Expansion:Zambia and the Democratic Republic of Congo hold underpenetrated mining jurisdictions where new license conditions are beginning to mirror Botswana's closed-loop mandates.
- Photovoltaic Thermal Hybridization:Solar thermal arrays paired with membrane distillation units enable off-grid ZLD deployment, opening arid extraction zones previously excluded on power economics.
- Brine Mining Integration:Lithium and potash developers in Namibia and Botswana can repurpose ZLD crystallizers as primary recovery equipment, converting wastewater infrastructure into revenue-generating assets.
Industry Challenges
- Commissioning Timeline Compression:Mining license compliance deadlines often allow less than eighteen months from contract award to operational acceptance, straining vendor project management capacity.
- Legacy Water Network Integration:Existing mine water circuits use open evaporation ponds or partial treatment trains, requiring complete re-piping and control system replacement for true zero liquid discharge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Zero Liquid Discharge System Market |
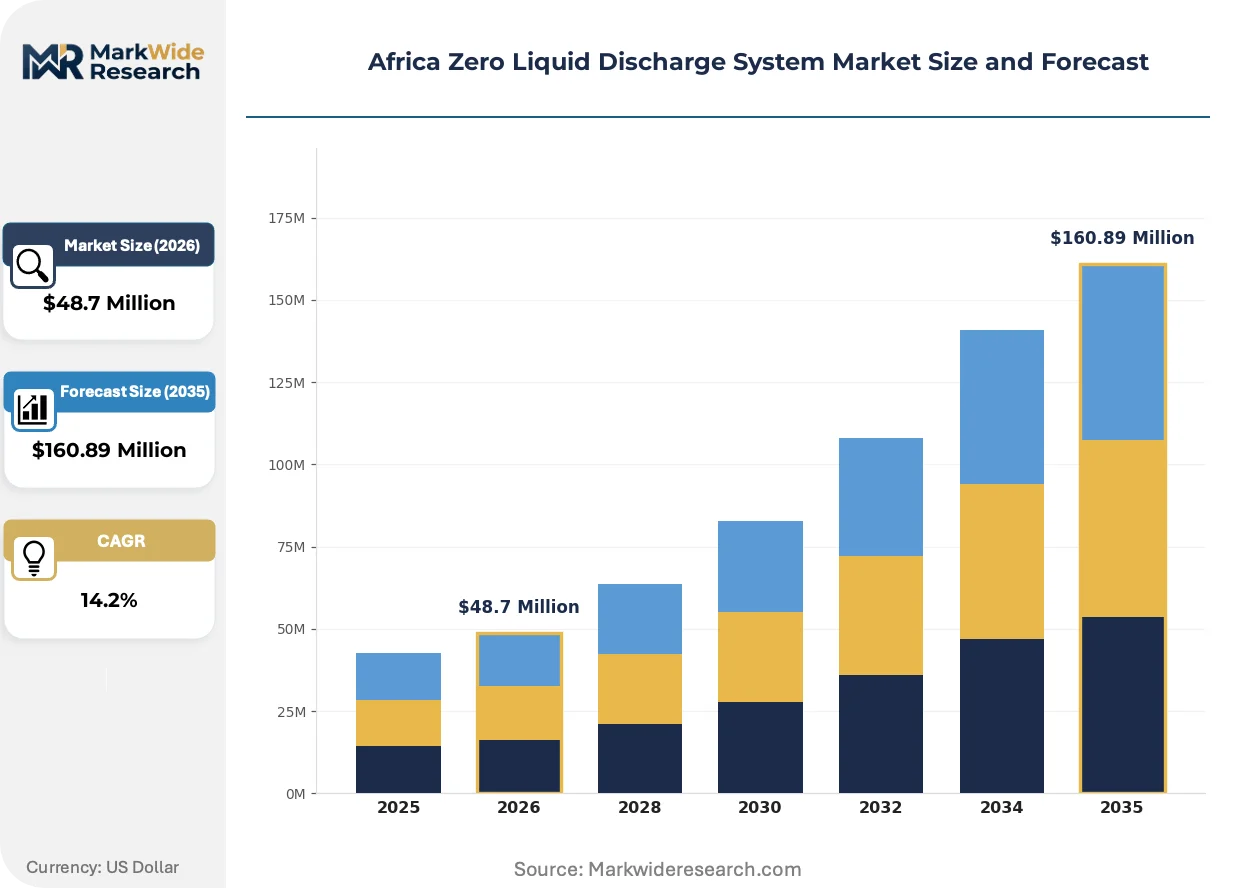
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $160.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial, Municipal, Agricultural, Mining Technology: Reverse Osmosis, Membrane Distillation, Crystallization, Electrodialysis End User: Power Generation, Oil & Gas, Chemical Processing, Food & Beverage Installation: Onsite, Centralized, Decentralized, Modular |
| Companies Covered | Veolia Water Technologies, SUEZ Water Technologies & Solutions, Aquatech International, Thermax Limited, GEA Group, IDE Technologies, ALFA Laval, H2O GmbH, Amanzi Resource Management, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Zero Liquid Discharge System Market Strategic Shifts
Containerized membrane-thermal hybrid systems are displacing permanent civil works across Africa's remote extraction footprint. This architectural shift is compressing deployment timelines and altering vendor competitive criteria toward modular engineering competence.
Membrane distillation crystallizer hybrids are miniaturizing thermal brine concentration into skid-mounted units that fit standard shipping containers. Platinum and coal operators in South Africa's Waterberg and Mpumalanga provinces are specifying these systems for greenfield sites. The format is enabling rapid relocation between mine phases, treating ZLD infrastructure as mobile assets rather than fixed capital.
Botswana's Department of Environmental Affairs mandates closed-loop water systems for all new mining licenses issued after recent regulatory amendments. This policy compresses procurement cycles and disqualifies vendors lacking local service presence. Junior miners are responding by leasing modular ZLD units under operating contracts rather than purchasing capital equipment.
Engineering-procurement-construction contracts are fragmenting into separate equipment supply and operating service agreements. Mining houses in South Africa's Northern Cape prefer to own crystallizer hardware while outsourcing membrane replacement and chemical optimization to specialists. This unbundling is visible most acutely at manganese and iron ore operations where water chemistry variability demands continuous technical attention.
Africa Zero Liquid Discharge System Market Segmentation
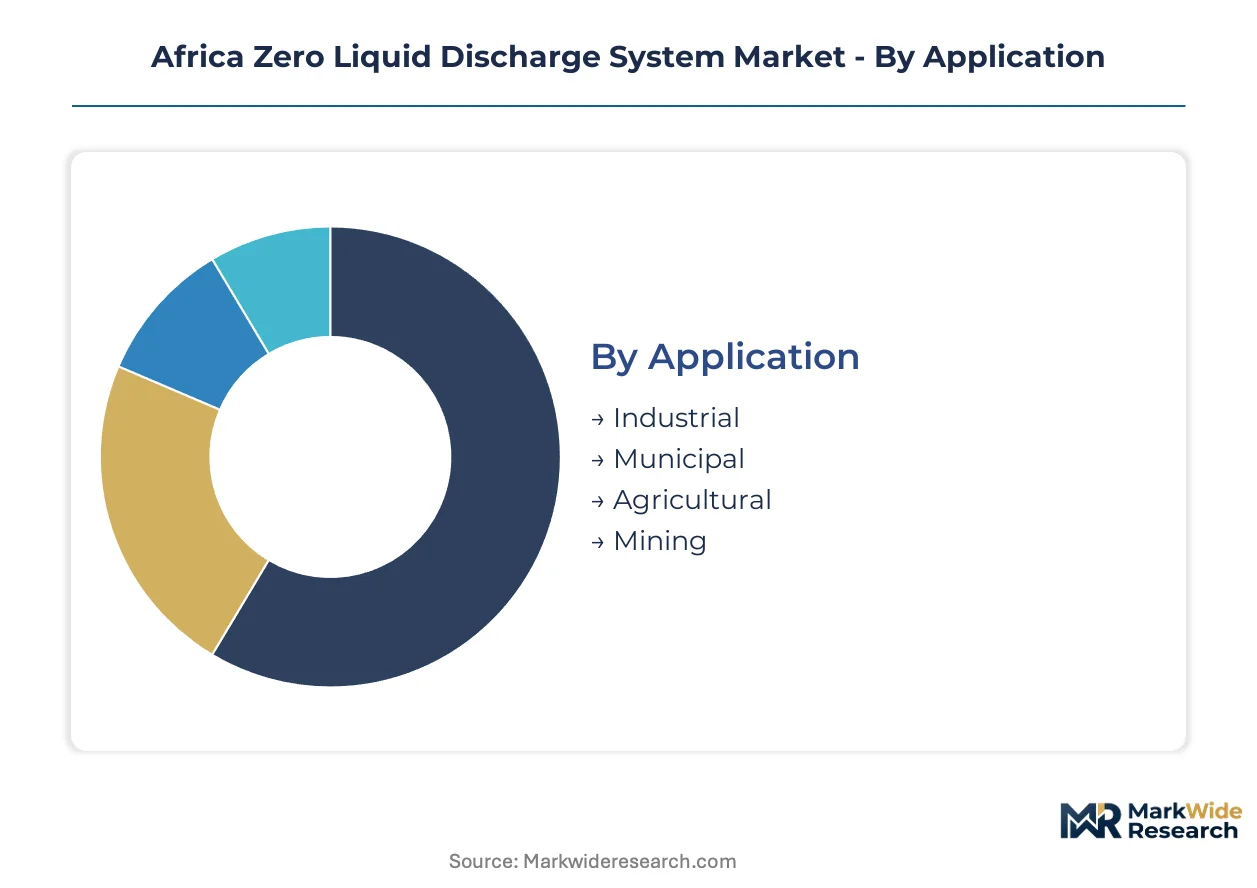
Zero liquid discharge procurement patterns diverge sharply across application contexts and technology choices in Africa. Mining operators prioritize modular thermal-membrane hybrids for remote deployment, while municipal buyers favor centralized crystallizers for urban wastewater recovery.
Application:
Substitution pressure from alternative water management approaches reshapes competitive intensity across end-use contexts, with open evaporation ponds and partial treatment trains threatening segments where regulatory enforcement remains uneven.
- Mining:Closed-loop recovery systems process saline effluent from platinum, coal, and copper extraction across South Africa's Bushveld Complex and Botswana's Kalahari copper belt. South Africa's Department of Water and Sanitation enforces total dissolved solids limits that prohibit surface discharge, compelling capital deployment.
- Industrial:Manufacturing facilities in Gauteng and KwaZulu-Natal deploy reverse osmosis pre-treatment trains ahead of crystallization for process water recycling. Chemical and petrochemical plants drive specification complexity due to variable feedwater chemistry.
- Municipal:Urban utilities in Cape Town and Johannesburg pilot ZLD for landfill leachate and brackish groundwater desalination concentrate. Budget constraints limit adoption to demonstration scale.
- Agricultural:Irrigation drainage recovery operates at pilot scale in Namibia's Orange River valley, constrained by dispersed demand and low salinity tolerance for crop reuse.
Mining anchors the volume base while municipal applications gain share at the steepest rate as drought resilience funding expands.
Technology:
Cost tier stratification separates capital-intensive thermal processes from membrane-based alternatives, with hybrid configurations capturing mid-market positioning.
- Reverse Osmosis:Spiral-wound polyamide membranes concentrate brine ahead of thermal finishing stages, achieving 40-45% recovery in single-pass configurations. South African power plants and Namibian desalination facilities specify these trains for lower capital thresholds.
- Crystallization:Forced-circulation evaporators and spray dryers recover solid salts for disposal or resale, commanding premium engineering margins. Botswana's new mining license mandates require complete dissolved solids removal achievable only through thermal crystallization.
- Membrane Distillation:Hydrophobic membrane contactors enable low-grade heat utilization for brine concentration, cutting thermal energy demand by half compared to conventional evaporation.
- Electrodialysis:Ion-exchange membrane stacks selectively transport dissolved ions under electrical potential, suited to high-value metal recovery in copper and cobalt processing circuits.
Crystallization captures the highest margin tier while membrane distillation expands most quickly as energy economics improve for remote sites.
End User:
Customer type determines specification complexity, with resource extraction industries tolerating higher technical risk than regulated utilities.
- Oil & Gas:Produced water management at Mozambique's offshore gas developments and South Africa's onshore shale exploration requires mobile treatment trains. Salinity variability and hydrocarbon contamination demand robust pre-treatment design.
- Chemical Processing:Fertilizer and chlor-alkali plants in Richards Bay and Sasolburg generate high-TDS effluent requiring complete salt recovery. Process integration opportunities reduce net operating expenditure.
- Power Generation:Coal-fired stations in Mpumalanga and nuclear facilities in the Western Cape treat cooling tower blowdown and boiler feedwater waste. Eskom's water stress exposure drives procurement urgency.
- Food & Beverage:Winery and dairy processors in the Western Cape recover water from cleaning-in-place operations and evaporator condensate. Organic loading complicates membrane selection.
Oil & Gas anchors the volume base while chemical processing gains share at the steepest rate as fertilizer capacity expands.
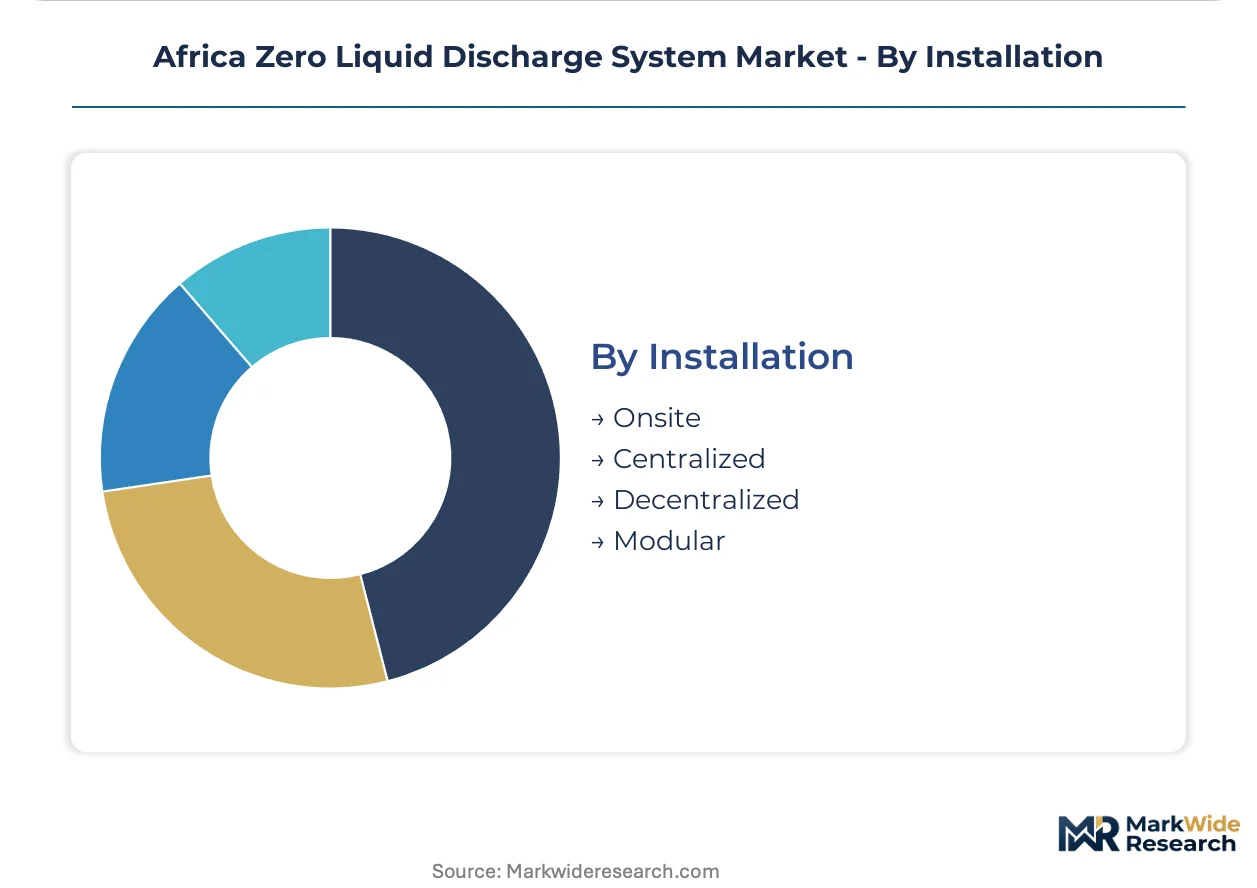
Installation:
Supply concentration in container fabrication and skid-mounted system engineering favors vendors with modular manufacturing competence over civil construction capabilities.
- Modular:Containerized membrane-thermal hybrid units ship to remote Botswana and Namibian mine sites, enabling rapid relocation between extraction phases. Standard shipping dimensions constrain equipment sizing.
- Onsite:Permanent civil works with embedded evaporators and crystallizers serve South African platinum and coal operations with 20-year asset horizons. Commissioning timelines extend to 18 months.
- Centralized:Single-plant ZLD infrastructure treats combined effluent from multiple industrial tenants in special economic zones, achieving economies of scale.
- Decentralized:Distributed treatment nodes at individual process units reduce piping costs for large integrated mining complexes.
Onsite installations anchor the volume base while modular configurations gain share at the steepest rate as junior miners favor leasing over ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates with European and South Asian specialists serving remote African mining sites. Crystallizer trains and membrane skids ship to South Africa's platinum belt and Botswana's copper deposits, where water scarcity enforcement tightens procurement timelines.
South Africa
Platinum and coal operators in the Bushveld Complex and Waterberg region drive crystallizer demand as aquifer depletion accelerates. The Department of Water and Sanitation enforces total dissolved solids limits that prohibit saline discharge to receiving waters, compelling closed-loop infrastructure. Mpumalanga's coal belt hosts the continent's densest ZLD deployment, with Eskom power stations treating cooling tower blowdown.
Botswana
Kalahari copper and diamond extraction generates concentrated brine requiring complete dissolved solids recovery. The Department of Environmental Affairs mandates closed-loop water systems for all new mining licenses, compressing vendor selection cycles. Remote sites in the Central District favor containerized membrane-thermal hybrids over permanent civil works due to power infrastructure gaps.
Namibia
Lithium and potash developers in the Erongo Region repurpose ZLD crystallizers as primary recovery equipment, converting wastewater infrastructure into revenue-generating assets. The country's National Water Policy prioritizes zero discharge for mining in water-stressed catchments. Arid extraction zones previously excluded on power economics now attract photovoltaic-thermal hybrid proposals.
Zambia
Copperbelt mining jurisdictions face emerging license conditions mirroring Botswana's closed-loop mandates. The Zambia Environmental Management Agency extends discharge accountability to upstream industrial zones under revised water quality regulations. Kitwe and Ndola processing hubs lack established ZLD service networks, creating entry opportunities for modular leasing models.
Mozambique
Offshore gas developments require mobile treatment trains for produced water management with salinity variability challenges. The National Petroleum Institute coordinates environmental compliance for extraction concessions in the Rovuma Basin. Pemba and Palma logistics corridors strain to deliver crystallizer components within compressed commissioning windows.
Africa Zero Liquid Discharge System Market Competitive Environment
Concentration sits with European water technology conglomerates and South Asian engineering exporters serving African mining procurement. The vendor base splits between full-service crystallizer specialists and membrane-thermal hybrid integrators. Three archetypes dominate: integrated water technology platforms, regional engineering exporters, and modular system fabricators. Strategic moves center on local service network expansion and technology licensing partnerships to compress commissioning timelines.
Among European integrated platforms, Veolia Water Technologies and SUEZ Water Technologies & Solutions exemplify the full-service archetype with crystallizer expertise and membrane distillation integration capabilities. Thermax Limited occupies a position representing South Asian engineering exporters channeling equipment into African power and chemical installations. These three anchors illustrate how vendor selection increasingly favors established service presence over equipment-only supply as regulatory compliance deadlines tighten.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| SUEZ Water Technologies & Solutions |
| Aquatech International |
| Thermax Limited |
| GEA Group |
| IDE Technologies |
| ALFA Laval |
| H2O GmbH |
| Amanzi Resource Management |
| Others |
Value Chain & Pricing Dynamics
Crystallizer fabrication scale economies in European and East Asian specialist shops anchor price floors across Africa's ZLD procurement landscape, concentrating supply with stainless steel alloy processors whose capacity utilization directly shapes vendor quoting power for South African platinum and Botswana copper operators.
Pricing Analysis
Volume-discount tiering structures separate full crystallizer trains from membrane-thermal skids and containerized lease units across the procurement spectrum. Price differentiation hinges on certification grade (ASME pressure vessel stamping versus non-certified fabrication) and after-sales service bundling (spare parts availability versus pure equipment supply). Cost compression in economy-tier containerized systems is intensifying because junior miners favor operating leases over capital purchases. Municipal utilities in South Africa exhibit the highest price sensitivity due to budget cycle constraints, while oil and gas majors in Mozambique tolerate premium engineering margins for mobile treatment reliability.
Supply Chain Analysis
Strategic stockpile preferences dominate crystallizer component procurement, with European fabricators maintaining stainless steel alloy inventories against eighteen-month project timelines while membrane suppliers favor just-in-time polymer delivery. Geographic supply concentration centers on Germany, Italy, and South Korea for forced-circulation evaporator fabrication, with India anchoring spiral-wound membrane cartridge production. Raw material dependencies include duplex stainless steel alloys, hydrophobic membrane polymers, and precision instrumentation. Single-source vulnerability runs through specialized welding consumables for high-salinity crystallizer construction. Distribution runs through Durban and Cape Town port corridors into South Africa's Bushveld Complex, with overland trucking to Botswana's Central District adding logistics cost layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against open evaporation ponds and partial treatment trains that threaten ZLD adoption where regulatory enforcement remains uneven across African mining jurisdictions.
For Market Incumbents: Fortify local service network density in Botswana's Central District and Namibia's Erongo Region before regulatory deadlines compress vendor qualification windows. Backward integration into membrane cartridge refurbishment capabilities reduces spare parts lead times that currently strain remote site uptime. Prioritize crystallizer alloy inventory positioning in Durban to preempt logistics chokepoints.
For New Entrants and Emerging Players: Anchor in Zambia's Copperbelt processing hubs where established ZLD service networks remain absent and emerging license conditions mirror Botswana's closed-loop mandates. Target junior manganese and iron ore operators in South Africa's Northern Cape with modular lease-to-own structures that bypass capital expenditure approval cycles. Lead with photovoltaic-thermal hybrid system integration as a differentiated power economics pitch.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular system fabricators with demonstrated crystallizer-membrane integration competence over pure equipment traders. Five-to-ten year viability hinges on regulatory harmonization momentum across the Southern African Development Community. Acquisition targets should demonstrate installed base density in at least two of South Africa, Botswana, or Namibia. The signal to watch is lithium and potash developer procurement shifts that repurpose ZLD crystallizers as primary recovery equipment rather than wastewater treatment.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Service Network Expansion | Compresses commissioning timelines for Botswana's Department of Environmental Affairs compliance deadlines. |
| Photovoltaic-Thermal Hybrid Integration | Enables off-grid ZLD deployment in Namibia's arid extraction zones previously excluded on power economics. |
| Membrane Cartridge Refurbishment Capability | Reduces operating expenditure for South African platinum belt operators facing skilled technician scarcity. |
| Modular Lease-to-Own Structure | Aligns procurement with junior miner capital constraints in South Africa's Northern Cape manganese operations. |
| Crystallizer-Membrane Integration Competence | Captures premium engineering margins where complete salt recovery justifies thermal finishing stages. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mining house water managers, crystallizer fabrication engineers, membrane technology specialists, and Department of Water and Sanitation regulatory officers. Secondary validation drew from Eskom water stress disclosures, Botswana Department of Environmental Affairs license condition databases, Southern African Development Community water treaty documentation, and customs records of crystallizer equipment imports. Bottom-up installation counts across South Africa's Bushveld Complex and Botswana's Kalahari copper belt were triangulated against top-down vendor revenue estimates.
Across the analysis window, the forecasting framework modeled technology adoption curves by application (mining, industrial, municipal, agricultural), installation format (modular versus onsite), and end-user water stress exposure. Segmentation dimensions included membrane-thermal hybrid penetration rates, crystallizer energy load configurations, and regional regulatory enforcement intensity. CAGRs were derived from equipment shipment trajectories and license issuance patterns. Industry-specific inputs comprised aquifer depletion indices for South Africa's platinum belt and photovoltaic cost curves for remote site power economics.
Decision-makers should treat outputs as directional under base assumptions of sustained saline discharge prohibitions and membrane distillation cost reduction; material deviation would warrant model refresh. Forecasts reflect assumptions of regulatory harmonization momentum and crystallizer energy efficiency gains. Specific risks that could revise projections include power infrastructure gaps in remote Botswana sites and technician training pipeline failures. Revision becomes warranted when open evaporation pond substitution rates cross regulatory enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
India Desalination Systems Market