
 Waste Heat Boiler Market | 2026-2036
Waste Heat Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Heat Boiler Market Intelligence
The capability gap between custom-engineered, large-scale systems and standardized modular units is rotating the market towards more accessible solutions. Large-scale project specialists like Nooter/Eriksen compete on bespoke designs for power generation and heavy industry. In contrast, Thermax leverages its expertise in packaged boiler systems to serve a broader range of manufacturing clients. Siemens positions itself with integrated digital twin and control solutions for optimizing asset performance.
A waste heat boiler is a heat exchanger that recovers thermal energy from hot gas streams, typically flue gas from industrial processes or engines. These systems utilize this captured energy to generate steam or hot water, often operating at pressures exceeding 50 bar. Water-tube designs dominate large-scale applications in the power generation sector due to their higher efficiency and pressure capabilities. Conversely, fire-tube boilers see significant use in smaller chemical processing and manufacturing facilities for their simpler construction and lower cost.
Industrial energy efficiency mandates, such as the EU's Industrial Emissions Directive and emissions standards from the US EPA, are primary demand drivers. In parallel, China's dual carbon goals accelerate investment in heat recovery systems across its heavy industries. These regulations directly link operational permits and carbon costs to the deployment of efficient boiler technology. Future investment decisions will hinge on balancing upfront capital expenditure against long-term energy savings and carbon compliance.
Market Dynamics
The convergence of stringent emissions regulations and volatile energy costs forms the central dynamic shaping the waste heat boiler market. This dual pressure compels industrial operators to view heat recovery not just as an efficiency measure but as a critical tool for regulatory compliance and cost control.
Growth Catalysts
- Industrial Decarbonization Mandates:China's dual carbon goals and the EU's Industrial Emissions Directive are forcing heavy industries like steel, cement, and chemicals to integrate waste heat recovery systems to meet emissions targets and secure operational permits.
- Advancements in Modular Design:The development of smaller, standardized modular boilers is expanding access to waste heat recovery for medium-sized manufacturing facilities that were previously excluded by the high cost and complexity of custom-engineered systems.
- Energy Price Volatility:Fluctuating natural gas and electricity prices enhance the economic case for investing in waste heat boilers, as the long-term energy savings provide a hedge against market instability and improve operational cost predictability.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment required for large-scale, custom-designed water-tube boilers remains a primary barrier, particularly for companies in capital-intensive industries with competing investment priorities.
- Process Integration Complexity:Retrofitting waste heat boilers into existing industrial plants presents substantial technical challenges, including spatial constraints, process interruptions, and compatibility issues with variable flue gas compositions.
- Alternative Efficiency Technologies:Competition from other energy-saving technologies, such as process optimization software, variable frequency drives, and direct electrification of heat, can divert investment away from boiler-based heat recovery projects.
Strategic Opportunities
- Data Center Heat Recovery:The exponential growth of data centers creates a significant opportunity for deploying waste heat boilers to capture low-grade heat for district heating networks or onsite power generation, addressing a major source of energy consumption.
- Hydrogen Production Integration:As green hydrogen production scales up, waste heat boilers can be integrated with electrolyzers and steam methane reformers to improve the overall process efficiency, creating a new industrial application. *Digital Service Wrappers: Offering integrated digital twin and predictive maintenance services using IoT sensors provides a new revenue stream, shifting the business model from a one-time equipment sale to a long-term performance partnership.
Industry Challenges
- Skilled Engineering Shortage:A scarcity of specialized thermodynamic and process engineers capable of designing and commissioning complex, high-pressure heat recovery systems for diverse industrial applications constrains project execution capacity.
- Material Corrosion and Fouling:Managing corrosion and fouling from aggressive chemical compounds in flue gas streams, especially in industries like glass and non-ferrous metals, requires advanced materials and sophisticated maintenance protocols, increasing operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Heat Boiler Market |
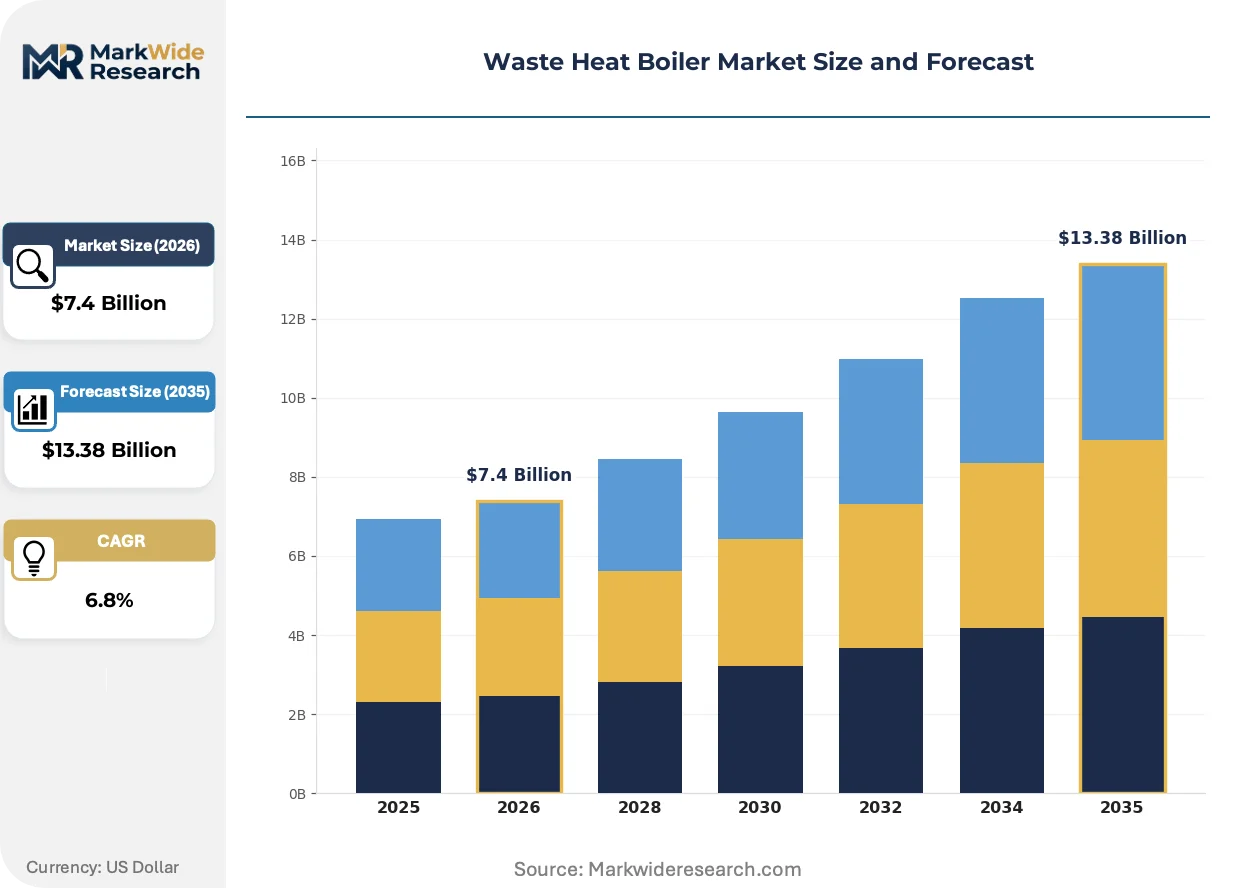
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Economizer, Heat Recovery Steam Generator End User: Power Generation, Oil & Gas, Manufacturing, Chemical Processing Technology: Conventional, Modulating Control, Pressure-Relief, High-Efficiency Application: Industrial Processes, District Heating, Combined Heat and Power, Marine |
| Companies Covered | General Electric, Siemens, Thermax, CMI Group, Nooter/Eriksen, VKK Standardkessel GmbH, Forbes Marshall, JFE Engineering Corporation, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Heat Boiler Market Strategic Shifts & Innovations
The market is shifting from large, bespoke projects toward more standardized and digitally integrated solutions. This evolution is democratizing access to waste heat recovery technology, extending its reach beyond traditional heavy industry into a broader range of manufacturing and energy applications.
Compact and modular waste heat boiler designs are a key product evolution. These packaged systems are pre-engineered for specific flow rates and temperatures, simplifying installation. Small and medium-sized enterprises in sectors like food processing and textiles are adopting these units at a rapid pace. This technology is miniaturizing the physical footprint and capital investment required for heat recovery, making it viable for facilities with limited space and budgets.
Regulatory frameworks are creating powerful financial incentives for adoption. The US Inflation Reduction Act (IRA) provides substantial tax credits for industrial energy efficiency and heat recovery projects. This policy directly lowers the financial barrier for US-based manufacturers to invest in new boiler systems or retrofit existing plants. The cement, chemicals, and refining sectors are the most impacted, using these incentives to fast-track decarbonization investments.
A notable shift in purchasing behavior is the move toward energy-as-a-service (EaaS) models. This disrupts the traditional capital equipment sale by allowing industrial clients to pay for verified energy savings or steam output rather than owning the boiler asset. This trend is most visible in Germany's chemical sector, where operators prioritize predictable operational expenses and guaranteed uptime over direct asset management.
Waste Heat Boiler Market Segmentation
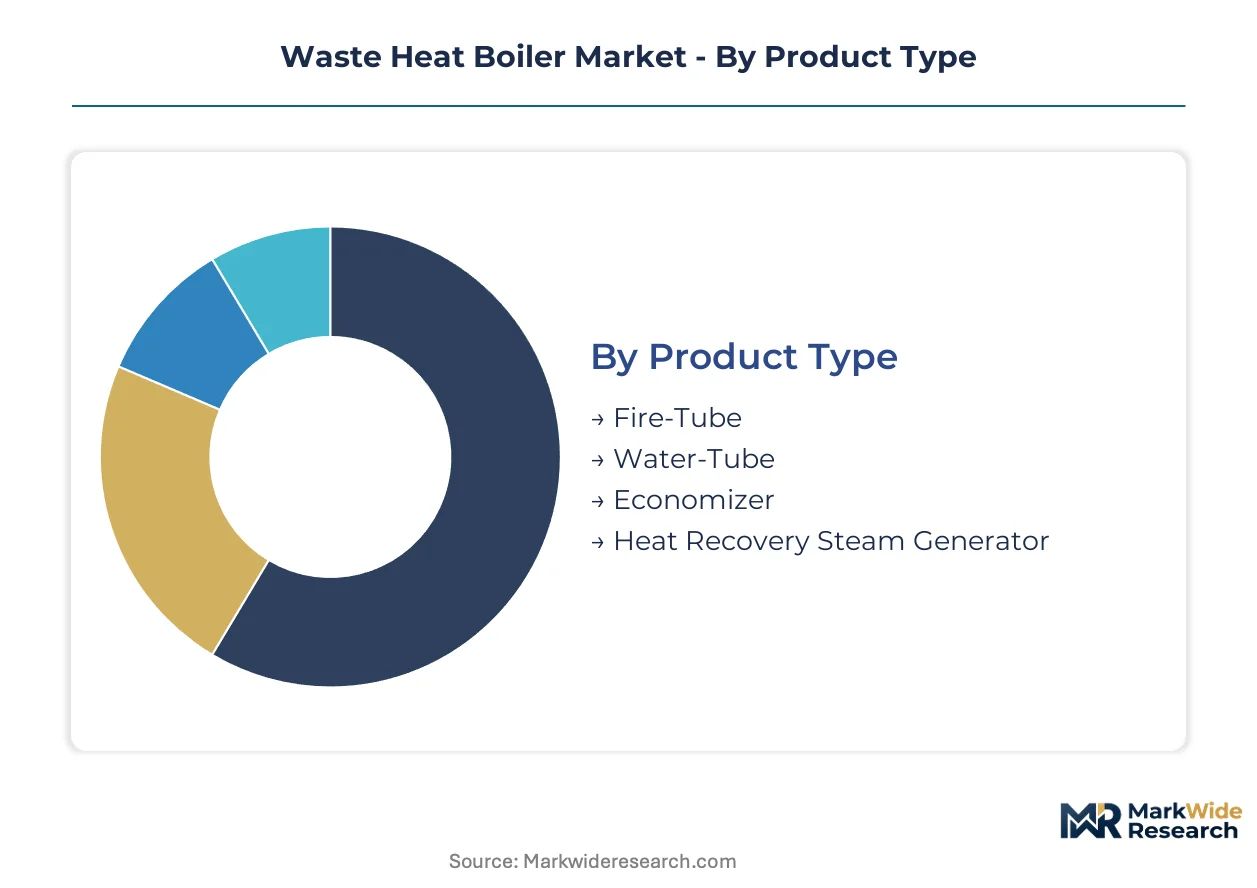
The Waste Heat Boiler Market's segmentation reveals critical distinctions in product design, end-use applications, and technological sophistication. Understanding these categories helps stakeholders navigate the diverse requirements of industrial processes and energy recovery initiatives. This granular analysis illuminates where investment flows and innovation is concentrating across the market.
Product Type:
Global demand for specific product types often reflects regional industrial maturity and regulatory landscapes.
- Water-Tube:These boilers feature water flowing inside tubes, surrounded by hot flue gas, enabling high-pressure steam generation for large-scale power plants. Demand concentrates in Germany and the United States, driven by the need for efficient, high-capacity energy recovery in heavy industries.
- Heat Recovery Steam Generator:These complex systems integrate multiple heat exchange sections to maximize energy capture from gas turbine exhaust or industrial furnaces. Adoption is accelerating in India's emerging manufacturing hubs, spurred by a focus on comprehensive energy efficiency and emissions reduction.
- Fire-Tube:Characterized by hot gases passing through tubes surrounded by water, these boilers offer simpler construction and lower costs for smaller industrial applications.
- Economizer:These heat exchangers preheat boiler feedwater using exhaust gases, enhancing overall system efficiency and reducing fuel consumption in various industrial settings.
Water-Tube holds the largest share; momentum sits with Heat Recovery Steam Generator.
End User:
The functional requirements and operational scale of various industrial sectors dictate their specific waste heat boiler needs.
- Power Generation:This sector utilizes waste heat boilers extensively to recover energy from gas turbine exhaust, converting it into steam for electricity production. Investment in this segment is significant across Europe, driven by decarbonization targets and the expansion of combined cycle power plants.
- Chemical Processing:Facilities in this segment employ waste heat boilers to recover thermal energy from exothermic reactions and flue gases, reducing energy costs and improving process stability. Demand is particularly strong in the European Union, compelled by the Industrial Emissions Directive.
- Oil & Gas:Operations in this industry deploy waste heat boilers to capture heat from refining processes and compressor stations, optimizing energy use and reducing flare gas.
- Manufacturing:Diverse manufacturing plants, from textiles to automotive, integrate waste heat recovery systems to lower utility expenses and meet sustainability goals.
Power Generation accounts for the largest volume; Chemical Processing is expanding most quickly.
Technology:
The adoption of specific waste heat boiler technologies often reflects a plant's age, capital expenditure budget, and desired level of operational control.
- High-Efficiency:These advanced systems minimize heat losses and maximize energy recovery through optimized design, advanced materials, and precise control mechanisms. Demand for high-efficiency solutions is robust in China, driven by national dual carbon goals and stringent industrial emissions standards.
- Modulating Control:This technology adjusts boiler output to precisely match variable heat demand, improving fuel efficiency and reducing wear on components. Facilities in the United States are increasingly adopting these systems, supported by incentives like the Inflation Reduction Act.
- Conventional:Basic waste heat boiler designs provide reliable heat recovery with standard components, suitable for less complex industrial processes.
- Pressure-Relief:These systems incorporate safety mechanisms to manage steam pressure, ensuring safe operation in high-pressure industrial environments.
High-Efficiency solutions currently command the largest share, while Modulating Control technologies are gaining share fastest.
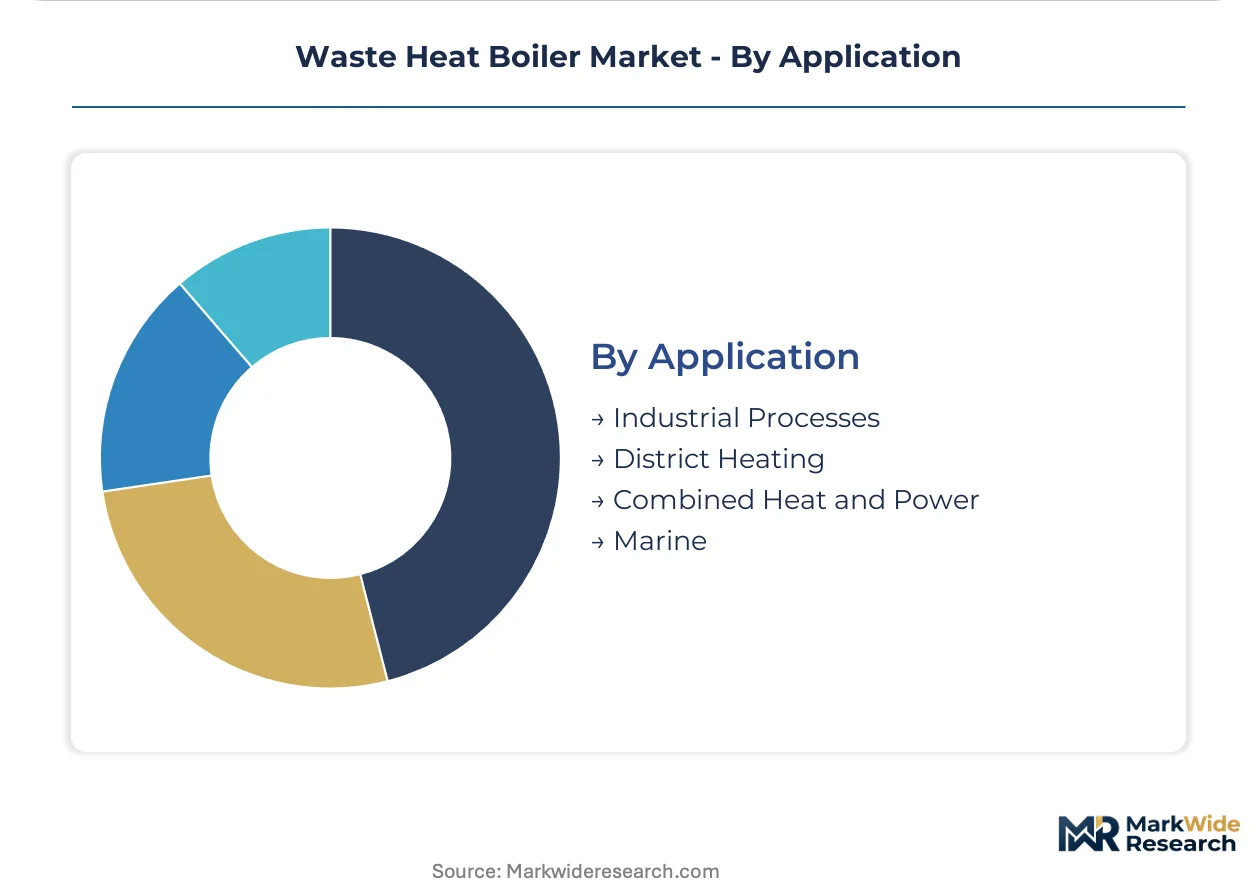
Application:
Diverse industrial and urban energy needs define the varied applications for waste heat boiler systems.
- Industrial Processes:This broad application encompasses various manufacturing and chemical operations where waste heat is recovered from flue gases, furnaces, or exothermic reactions. Demand is widespread, particularly in Germany's heavy industry, focusing on operational cost reduction and compliance.
- Combined Heat and Power:CHP systems integrate waste heat boilers to capture exhaust heat from prime movers (like gas turbines), producing both electricity and useful thermal energy. Investment is significant across the European Union, driven by energy efficiency mandates and grid stability concerns.
- District Heating:Waste heat boilers supply hot water or steam to centralized networks, providing heating for multiple buildings in urban areas.
- Marine:Specific waste heat recovery units are installed on ships to utilize exhaust gas heat for onboard power generation or heating, improving fuel economy.
Industrial Processes represents the largest application segment; Combined Heat and Power shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global waste heat boiler market exhibits varied consumption patterns influenced by industrial maturity and regulatory frameworks. Germany and the United States prioritize high-capacity water-tube systems for heavy industry, while India's emerging manufacturing sector drives demand for Heat Recovery Steam Generators. China's focus on decarbonization also shapes its technology adoption.
Germany
Germany's industrial sector prioritizes waste heat boiler adoption for energy efficiency and high-capacity energy recovery. The EU's Industrial Emissions Directive compels facilities to upgrade their waste heat recovery systems. Established industrial zones, such as the Ruhr region, focus on integrating these systems for operational cost reduction and regulatory compliance. This region sees significant investment in advanced water-tube designs.
India
India's expanding manufacturing base drives demand for comprehensive energy efficiency and emissions reduction solutions. The nation's industrial policies support the adoption of advanced heat recovery systems in new facilities. Emerging manufacturing hubs in states like Gujarat and Maharashtra are rapidly integrating Heat Recovery Steam Generators to maximize energy capture. This investment supports sustainable industrial growth.
China
China's industrial landscape sees strong demand for high-efficiency waste heat boilers driven by national dual carbon goals. Stringent industrial emissions standards accelerate investment in heat recovery systems across heavy industries. Facilities in provinces like Hebei and Shandong are upgrading their operations to meet these ambitious environmental targets. This commitment includes optimizing asset performance through advanced boiler technology.
United States
The United States market for waste heat boilers is influenced by industrial energy efficiency and long-term energy savings goals. The US Inflation Reduction Act (IRA) provides substantial tax credits, lowering financial barriers for manufacturers. Industries like cement, chemicals, and refining in states such as Texas and Louisiana leverage these incentives. This supports the adoption of modulating control technologies.
Waste Heat Boiler Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the waste heat boiler market. The market structure features a core of large-scale project specialists alongside focused providers of standardized modular units. Strategic archetypes include bespoke system engineers, packaged boiler manufacturers, and digital solution integrators. Companies frequently engage in strategic partnerships to expand their service offerings and pursue portfolio diversification to address diverse industrial needs.
Large-scale project specialists like Nooter/Eriksen exemplify providers of bespoke designs for power generation and heavy industry applications. Siemens AG, a German-based technology company, occupies a position focused on integrated digital twin and control solutions for optimizing asset performance. India-based Thermax Limited represents a manufacturer leveraging expertise in packaged boiler systems to serve a broader range of manufacturing clients. These companies anchor different segments of the market by offering specialized solutions tailored to distinct customer requirements.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| Thermax |
| CMI Group |
| Nooter/Eriksen |
| VKK Standardkessel GmbH |
| Forbes Marshall |
| JFE Engineering Corporation |
| Alfa Laval |
| Others |
Cost & Logistics Intelligence
The increasing substitution of custom-engineered systems with standardized modular units simultaneously reshapes supply geography and the pricing economics for waste heat boilers. This shift favors manufacturing hubs with efficient production capabilities, influencing overall market cost structures.
Pricing Analysis
After-sales service and digital integration drive significant lifetime value in the waste heat boiler market. The dominant pricing model remains project-based for large-scale installations, while energy-as-a-service (EaaS) models offer value-based pricing. Price differentiation stems from the customization level required for bespoke solutions and the extent of integrated digital services. Pricing softness stems from intense competition in the standardized modular segment, driven by manufacturers optimizing production. Medium-sized manufacturing facilities are the most price-sensitive buyers, prioritizing lower upfront capital expenditure.
Supply Chain Analysis
Extended lead times for specialized high-pressure components impact project timelines for waste heat boiler installations. Geographic supply concentration for critical components rests in countries like Germany, known for precision engineering, and China, for cost-effective manufacturing. The supply chain draws from specialized heat exchange tubes and high-grade steel alloys. Commodity price volatility for steel represents a structural risk, affecting manufacturing costs. Distribution for large, custom systems typically runs through direct sales teams and EPC contractors, while modular units leverage regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story for incumbents, primarily due to regulatory entrenchment from stringent industrial emissions directives and decarbonization mandates.
For Market Incumbents: Fortify core market share by investing in advanced digital twin and control solutions, enhancing predictive maintenance capabilities. This directly addresses the threat from alternative efficiency technologies that offer integrated process optimization. Expand R&D efforts into advanced materials to manage corrosion and fouling risks in diverse industrial flue gas streams, improving asset longevity and performance.
For New Entrants and Emerging Players: Anchor in underserved market niches with standardized, compact modular designs. Target medium-sized manufacturing facilities in emerging industrial hubs, particularly in regions like India, where energy efficiency mandates are accelerating. A compelling go-to-market angle involves offering bundled solutions that simplify installation and guarantee performance, leveraging lower upfront costs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with vertically integrated mid-cap specialists offering proven modular solutions or digital service wrappers. The long-term viability of this market is strong over the next decade, driven by global decarbonization efforts and energy security concerns. Acquire firms with strong intellectual property in advanced heat exchange materials or integrated IoT platforms. Watch for policy shifts in major industrial economies, particularly around carbon pricing and energy efficiency incentives, as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Siemens' approach to optimizing asset performance ensures higher operational efficiency for end-users. |
| Modular Product Line Expansion | Thermax can broaden its client base in manufacturing by offering more accessible heat recovery units. |
| Advanced Materials R&D | Mitigating corrosion and fouling in aggressive flue gas streams enhances boiler lifespan and reduces maintenance for operators. |
| Energy-as-a-Service (EaaS) Model | Germany's chemical sector benefits from predictable operational expenses and guaranteed uptime, shifting capital expenditure. |
| Green Hydrogen Project Partnerships | Integrating waste heat boilers into electrolyzer and SMR processes creates new industrial applications and improves overall efficiency. |
Research Approach
Operator-level perspectives from plant engineers, procurement managers, R&D directors, and sustainability officers anchored the qualitative base of this analysis. Primary interviews with these industry stakeholders provided crucial insights, which were then validated against secondary data sources. This included industry association reports, government energy agency data, company annual reports, and academic research, triangulated through both bottom-up and top-down approaches.
Sensitivity analysis framed the quantitative modeling across the analysis window, evaluating various market scenarios. The analytical framework modeled segmentation dimensions including product type, end user, technology, application, and regional industrial output. Compound Annual Growth Rate calculations were performed based on historical trends and projected market drivers. Key forecast inputs included industrial energy consumption trends and regulatory compliance deadlines across major economies.
Decision-makers should treat outputs as directional under the named base assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological advancements and stable regulatory environments. Unforeseen policy shifts, energy market shocks, or rapid technological breakthroughs represent specific risk factors that could revise these projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Europe Power Plant Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
Field Erected Boiler Market
Boilers
Utility Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Biomass Boiler Market
Boilers
Boiler Control Market
Boilers
Global Domestic Boilers Market
Boilers
Oil-Fired Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Residential Boiler Market
Boilers
Electric Boiler Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Advanced Utility Boilers Market