
 Global Domestic Boilers Market | 2026-2036
Global Domestic Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Domestic Boilers Market Foresight
The installer and wholesaler channel is rewriting how domestic boilers reach end users across Europe and North America. Bosch Thermotechnology leverages its captive distribution network to control specification decisions at the contractor level. Vaillant Group anchors its competitive position through deep vertical integration into heat exchanger manufacturing. Viessmann competes by dominating the premium hydronic system segment with proprietary control platforms.
Domestic boilers are pressurized vessels designed to heat water for space heating and potable hot water supply, typically operating at outputs between 15 kW and 40 kW for single-family applications and employing cast aluminum or stainless-steel heat exchangers for thermal transfer efficiency. The natural gas fuel type still occupies the largest installed base across mature markets, though biomass and electricity are gaining specification share in new construction subject to zero-carbon building codes. Combi boilers lead volume in urban retrofit markets where space constraints eliminate separate cylinder requirements, while system boilers sustain margin pools in larger properties with high simultaneous hot water demand.
The EU F-Gas Regulation, ErP Directive, and CE marking framework collectively mandate minimum seasonal efficiency thresholds and restrict refrigerant-based auxiliary systems in integrated products. The US EPA and DOE furnace standards shape product eligibility for federal tax credits and utility rebate programs. Stakeholders must monitor how national implementation timelines for fossil-fuel phaseouts alter replacement demand curves and inventory positioning across channel tiers.
Market Dynamics
The EU F-Gas Regulation and ErP Directive are compressing replacement cycles across Northern European housing stock, forcing manufacturers to reconfigure product portfolios around hydrogen-ready combustion architectures and smart control integration before fossil-fuel phaseout deadlines.
Growth Catalysts
- Building retrofit mandates:Germany's Building Energy Act and France's RE2020 regulations are accelerating replacement demand in aging single-family housing stock.
- CE marking efficiency thresholds:Tightened seasonal efficiency requirements under the ErP Directive are disqualifying legacy atmospheric boilers from new installations.
- Hydrogen blending infrastructure:Pilot programs in the United Kingdom and Netherlands are creating specification pull for H2-ready heat exchangers.
Market Restraints
- Stainless steel price volatility:Heat exchanger input costs fluctuate with nickel and chromium spot markets, compressing margin pools for mid-tier manufacturers.
- Cast aluminum supply concentration:Italian and German foundries control critical die-casting capacity for condensing boiler blocks.
- Heat pump substitution:Air-source electric systems are capturing new-build specifications in jurisdictions with zero-carbon building codes.
Strategic Opportunities
- Polish and Romanian housing stock:Underpenetrated markets with aging coal-fired systems present replacement volume as EU cohesion funds flow.
- Utility-managed installation programs:British Gas and E.ON are bundling boiler replacement with financing, bypassing traditional wholesaler channels.
- Hybrid system convergence:Integration of gas condensing units with thermal batteries and solar thermal is opening premium retrofit segments.
Industry Challenges
- Gas-safe certification bottlenecks:Installer training programs cannot scale to meet accelerated replacement timelines in the United Kingdom.
- Legacy control protocol fragmentation:Proprietary bus systems from Viessmann, Bosch, and Vaillant complicate third-party smart thermostat integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Domestic Boilers Market |
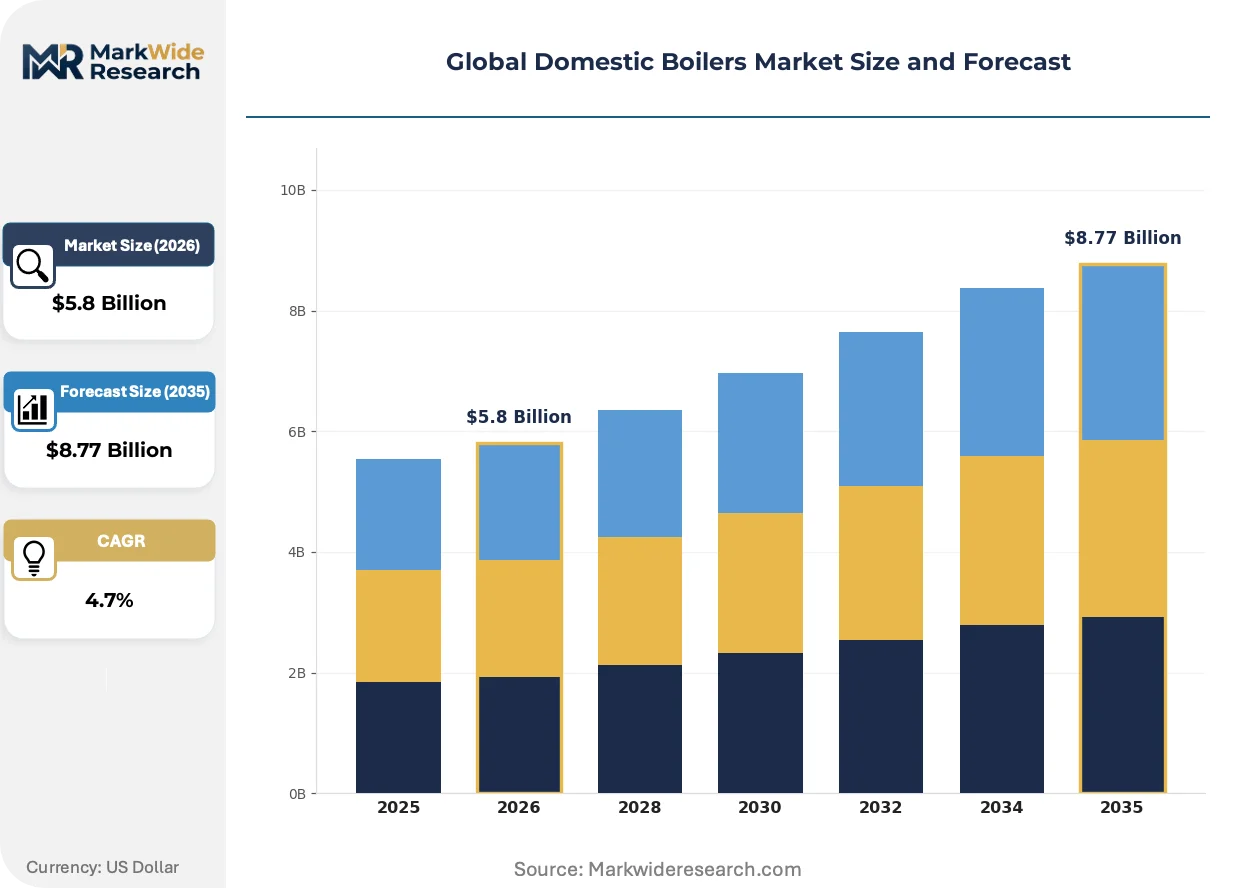
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boiler Type: Combi, System, Conventional, Electric Fuel Type: Natural Gas, LPG, Oil, Biomass, Electricity Installation Type: Wall-Mounted, Floor-Standing, Compact, Modular End User Segment: Residential Buildings, Commercial Establishments, Rental Properties, Vacation Homes |
| Companies Covered | Bosch Thermotechnology, Vaillant Group, A.O. Smith, Viessmann, Ideal Heating, BDR Thermea Group, Ariston Holding, Suntec Energy Systems, Alpha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Domestic Boilers Market Shifts & Advancements
Digital control architectures and low-carbon combustion systems are restructuring how domestic boilers are specified, installed, and serviced across European and North American markets.
Modulating burner control via cloud-connected thermostats is virtualizing traditional hydronic system management. Multi-family housing operators in Germany and the Netherlands are adopting these platforms to optimize district-level thermal load balancing. The technology is virtualizing legacy BMS functions into edge-computing devices embedded at the appliance level.
The US DOE furnace efficiency standards and EPA refrigerant phase-down rules are reshaping product eligibility for federal tax credits. Manufacturers must now certify dual-fuel compatibility and low-NOx combustion to access utility rebate programs. The residential retrofit segment in cold-climate US states is responding by prioritizing condensing units with sealed combustion chambers.
Specification authority is migrating from installers to energy auditors and mortgage lenders. French banks are tying green loan rates to ErP-labeled boiler selections, displacing contractor brand preferences. This shift concentrates volume in certified product tiers and compresses specification diversity in new-build housing developments.
Global Domestic Boilers Market Segmentation
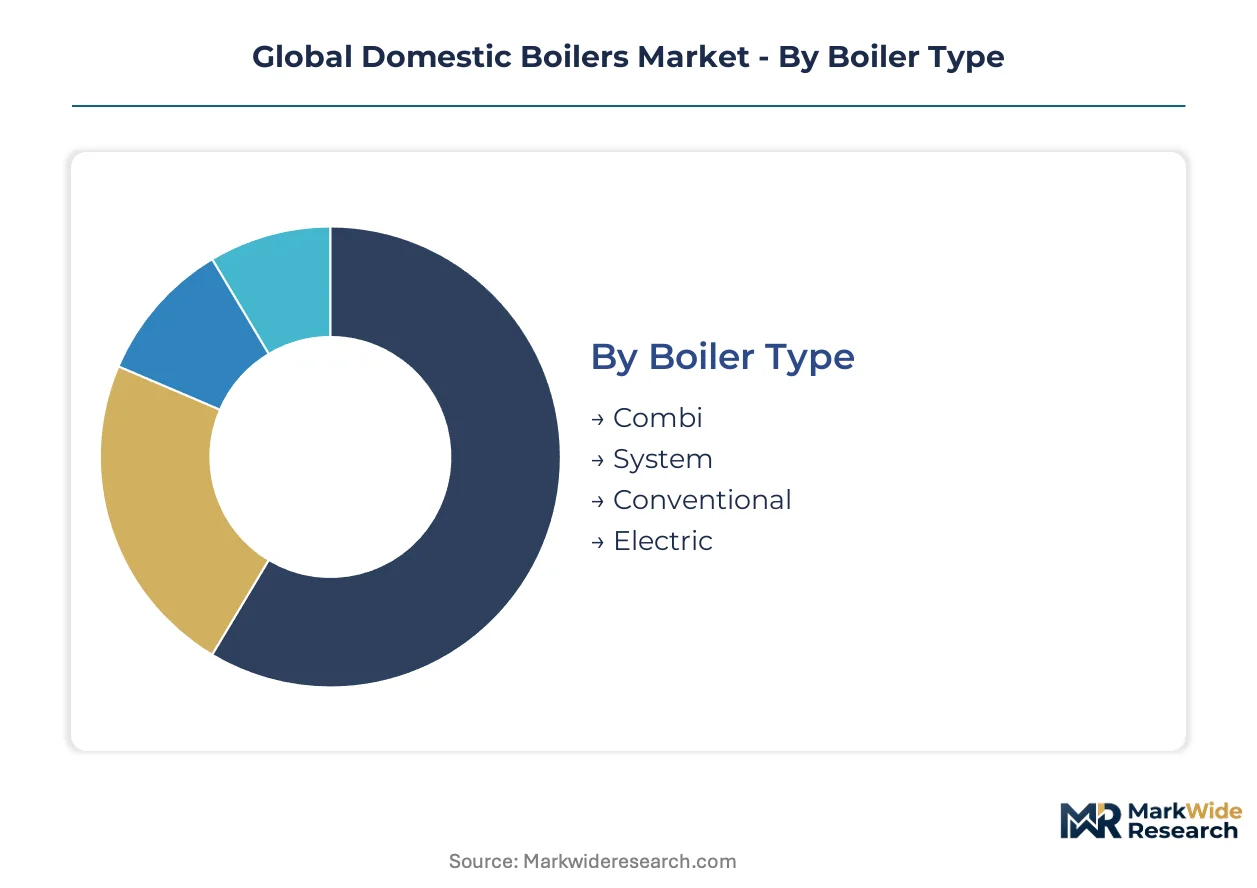
Domestic boiler segmentation tracks how specification authority migrates across installer, wholesaler, and utility channels. After-sales service intensity varies sharply by boiler type and fuel architecture, reshaping margin capture for manufacturers and distributors.
Boiler Type:
After-sales service intensity peaks with system and conventional boilers requiring separate cylinder maintenance and annual safety inspections across Germany, the United Kingdom, and France.
- Combi:Single-unit design integrates space heating and instantaneous hot water generation through plate heat exchangers. Demand concentrates in urban retrofit markets across London, Berlin, and Paris where space constraints eliminate separate cylinder requirements and installation timelines compress replacement decisions.
- System:Requires separate unvented cylinder for stored hot water, creating higher lifetime service touchpoints. Specification pull strengthens in larger detached properties across suburban Munich and Vienna where simultaneous multi-outlet demand exceeds combi output limits.
- Conventional:Open-vented gravity-fed design retains installed base in pre-1980 housing stock. Legacy replacement cycles persist in rural France and northern England where existing pipework retrofit costs deter combi conversions.
- Electric:Resistance or heat pump-based units bypass combustion certification requirements. Emerging specifications in Netherlands zero-carbon pilot districts and new-build Swedish multifamily housing.
By volume, combi leads. By growth pace, electric is climbing the fastest.
Fuel Type:
Cost tier stratification separates premium hydrogen-ready natural gas systems from economy electric resistance units across European replacement markets.
- Natural Gas:Condensing combustion with modulating premix burners dominates replacement volume. Network infrastructure in Germany, the Netherlands, and the United Kingdom sustains specification share despite building code phaseout timelines.
- LPG:Bottled or tanked propane/butane serves off-grid rural properties. Demand persists in southwestern France, rural Wales, and Scottish Highlands where mains gas extension remains uneconomic.
- Oil:Pressure-atomized or vaporizing burners retain installed base in isolated single-family housing. Replacement cycles accelerate in Ireland and northern Germany under building energy act mandates.
- Biomass:Wood pellet or chip combustion with automated feed systems. Niche specification in Austrian alpine regions and Bavarian forest zones with local fuel supply chains.
- Electricity:Direct resistance or heat pump integration. Steepest expansion trajectory in French new-build RE2020 compliance zones and Dutch gas-free district pilots.
Natural gas retains the largest installed base. Electricity is gaining share fastest in zero-carbon building codes.
Installation Type:
Application context drives specification between retrofit wall-hung replacements and new-build floor-standing plant room configurations.
- Wall-Mounted:Compact heat exchanger and burner assemblies reduce footprint for kitchen or utility room installation. Standard specification across German and British single-family retrofits.
- Floor-Standing:Larger water content and service access for high-output or multi-boiler cascade arrangements. Preferred in Belgian apartment blocks and Dutch commercial-residential mixed use.
- Compact:Reduced depth dimensions for cupboard or closet integration. Urban London and Paris apartment retrofits where space constraints override output optimization.
- Modular:Multiple unit synchronization for phased capacity expansion. Emerging in Polish and Romanian multifamily developments with EU cohesion fund backing.
Wall-mounted units dominate replacement volume. Modular configurations show the steepest expansion trajectory in emerging European markets.
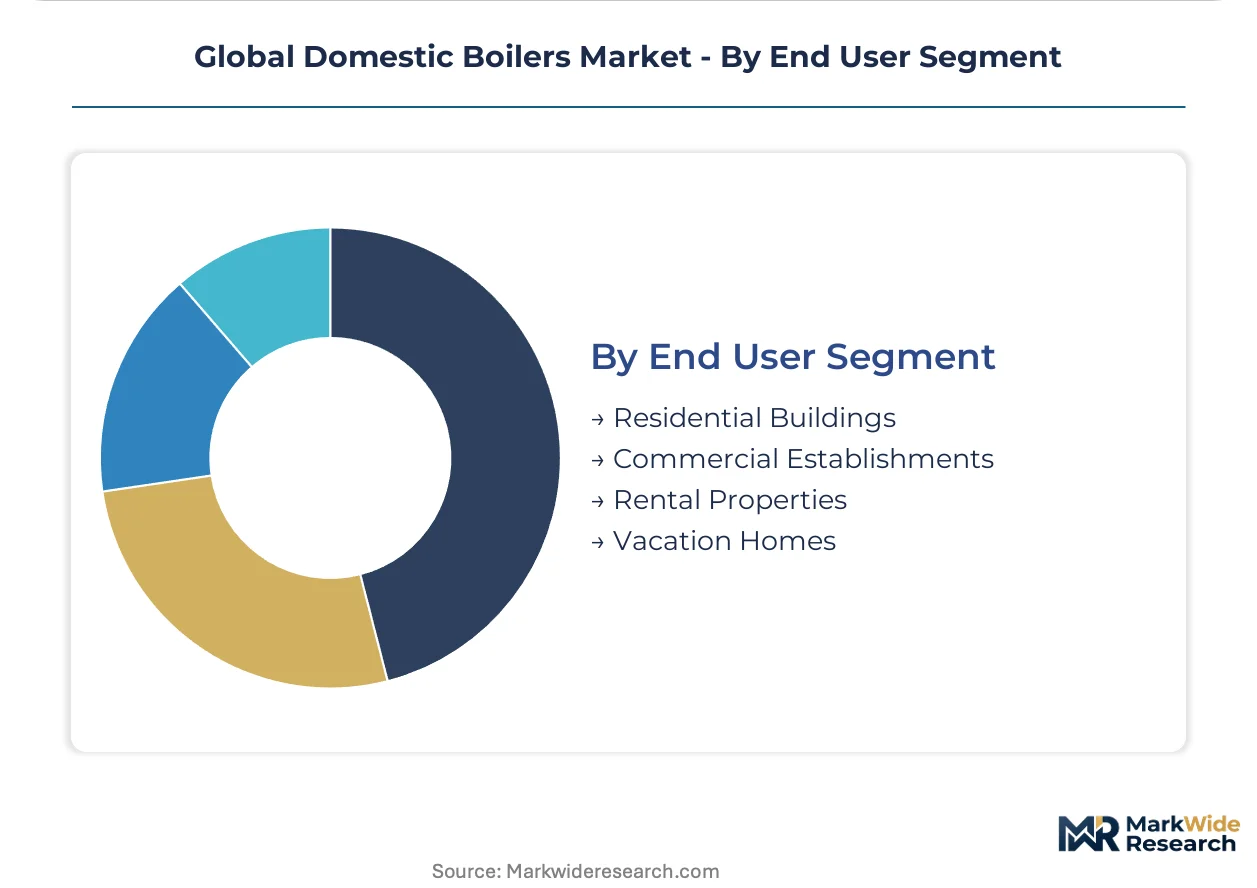
End User Segment:
Customer type determines procurement channel, with rental property portfolios centralizing specification through housing association frameworks distinct from homeowner discretionary replacement.
- Residential Buildings:Owner-occupied single-family and multifamily dwellings. Decision authority splits between installer recommendation and energy auditor certification in France and Germany.
- Commercial Establishments:Small hotels, restaurants, and retail premises with combined heating and process hot water loads. British Gas and E.ON utility programs target this segment with financed replacement bundles.
- Rental Properties:Social and private landlord portfolios with regulatory compliance obligations. UK MEES regulations and German heating ordinance drive centralized procurement through housing associations.
- Vacation Homes:Seasonal occupancy properties with frost-protection and low-standby-loss priorities. Alpine Austria and Mediterranean Spanish coastal markets specify compact electric or LPG solutions.
Residential buildings account for the largest volume base. Rental properties are expanding most quickly under regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Building Energy Act and the United Kingdom's gas boiler phaseout timeline are compressing replacement cycles across Northern European housing stock. National implementation schedules for fossil-fuel restrictions are diverging, creating asynchronous demand pulses that manufacturers must navigate through 2035.
Germany
Retrofit mandates in single-family housing are accelerating condensing boiler replacements under the Building Energy Act. The Federal Office for Economic Affairs and Export Control administers subsidy programs for hydrogen-ready heating systems. Industrial clusters around North Rhine-Westphalia and Bavaria concentrate manufacturing capacity for heat exchanger components.
United Kingdom
Gas-safe certification bottlenecks are constraining installer capacity despite accelerated replacement timelines. The Future Homes Standard and Clean Heat Grant shape specification decisions for new-build and retrofit segments. Greater London and the Midlands dominate wholesale distribution channels for combi boiler volume.
France
Green loan rate differentiation tied to ErP labeling is displacing contractor brand preferences in residential finance. The RE2020 environmental regulations mandate performance thresholds for new construction heating systems. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate housing association procurement for rental property compliance.
Netherlands
Gas-free district pilot programs are creating specification demand for electric and hybrid alternatives in new residential developments. The national climate agreement targets 1.5 million natural gas disconnections by 2030. Eindhoven and Randstad urban clusters lead technical validation for hydrogen blending infrastructure.
Poland
EU cohesion fund flows are unlocking replacement volume in aging coal-fired heating systems across multifamily housing. The National Fund for Environmental Protection and Water Management administers subsidy windows for efficiency upgrades. Silesian and Mazovian industrial zones concentrate foundry capacity for cast aluminum heat exchanger production.
Global Domestic Boilers Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated European specialists and diversified industrial conglomerates with captive distribution networks. Three strategic archetypes dominate: heat exchanger manufacturers with backward integration into metallurgy, controls specialists with proprietary digital platforms, and diversified building technology groups with installer channel capture. Competitive moves concentrate on hydrogen-ready product certification races and utility partnership structures that bypass traditional wholesale tiers.
Among German-based heating technology groups, Bosch Thermotechnology, Vaillant Group, and Viessmann exemplify the vertically integrated archetype with in-house production of critical combustion components. These entities anchor the premium specification tier through proprietary control ecosystems and direct contractor specification relationships. Mid-tier positioning is occupied by diversified water heating specialists including A.O. Smith and Ideal Heating, while Italian and Dutch holding structures such as Ariston Holding and BDR Thermea Group represent regional consolidation plays with broad fuel-type coverage.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Vaillant Group |
| A.O. Smith |
| Viessmann |
| Ideal Heating |
| BDR Thermea Group |
| Ariston Holding |
| Suntec Energy Systems |
| Alpha |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rates directly transmit stainless steel and aluminum ingot cost volatility into final boiler pricing, compressing margins for mid-tier manufacturers while enabling premium players to capture price differentiation through captive metallurgy and certified component sourcing.
Pricing Analysis
Certification level under the EU ErP Directive and CE marking framework creates the primary spread between premium hydrogen-ready systems and economy atmospheric replacements. Three-tier pricing structure across premium, standard, and economy levels stratifies by seasonal efficiency thresholds, with hydrogen-ready heat exchangers commanding material premiums over legacy condensing units. Cost compression in the standard tier is intensifying because nickel price volatility feeds directly into stainless steel heat exchanger inputs. Social housing associations and rental property portfolios exhibit highest price sensitivity, while owner-occupiers in suburban Munich and Vienna prioritize performance over first cost.
Supply Chain Analysis
Italian foundries in Lombardy and German die-casters in North Rhine-Westphalia hold captive capacity for cast aluminum condensing boiler blocks, with Polish and Romanian facilities expanding secondary sourcing. Critical inputs draw from nickel-chromium alloy suppliers, electronic control module fabricators, and precision burner component specialists. Single-source vulnerability concentrates in hydrogen-ready heat exchanger certification, where only three European metallurgy houses qualify for H2-blend compatibility testing. Distribution runs through installer-wholesaler networks in Germany and the United Kingdom, with utility-managed programs in France and the Netherlands bypassing traditional channel tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The domestic boilers market is entering a cyclical recovery phase driven by Northern European building retrofit mandates compressing replacement timelines. Installers and manufacturers must position for asynchronous demand pulses as national fossil-fuel phaseout schedules diverge through the projection horizon.
For Market Incumbents: Insulate specification authority against heat pump substitution by accelerating hydrogen-ready certification races and embedding proprietary control platforms into utility-managed installation programs. Bosch Thermotechnology and Vaillant Group should deepen captive metallurgy capacity to offset nickel price volatility. Channel control through direct contractor relationships remains the priority lever against emerging electric heating specialists.
For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian multifamily retrofit segments where EU cohesion fund flows are unlocking replacement volume in aging coal-fired systems. Electric and hybrid boiler architectures offer the most penetrable specification path in Dutch gas-free districts and French RE2020 new-build zones. A utility partnership go-to-market model bypasses entrenched wholesaler relationships dominated by incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core heating technology assets amid portfolio rebalancing toward electrification. Long-term viability hinges on hydrogen infrastructure deployment pace and hybrid system convergence with thermal storage. The signal to monitor is British Gas and E.ON program expansion rates as indicators of utility channel capture momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Certification Investment | ErP Directive compliance secures specification eligibility in German and UK replacement markets. |
| Foundry Capacity Expansion | Captive cast aluminum production insulates margin pools from Italian supply concentration. |
| Utility Partnership Structuring | E.ON and British Gas program integration bypasses traditional wholesaler channel capture. |
| Control Platform Proliferation | Proprietary digital ecosystems lock in contractor specification authority against third-party thermostats. |
| Polish-Romanian Market Entry | EU cohesion fund flows unlock multifamily replacement volume in underpenetrated housing stock. |
Research Methodology
Initial hypotheses were tested against primary input from heating technology product managers, gas-safe certified installers, housing association procurement officers, and foundry operations directors, and refined through secondary validation against EU F-Gas Regulation implementation timelines, ErP Directive efficiency databases, national building energy act filings, and customs trade data for heat exchanger alloy inputs. Bottom-up volume estimates from installer channel interviews were triangulated against top-down replacement cycle modeling.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled by boiler type, fuel architecture, installation configuration, and end-user procurement channel. CAGRs were derived from replacement cycle compression rates under national fossil-fuel phaseout schedules, hydrogen blending infrastructure deployment assumptions, and heat pump substitution elasticity in new-build specifications. Forecast inputs incorporated housing stock age profiles, subsidy program budget allocations, and foundry capacity utilization rates.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, stainless steel spot markets, and eurozone construction investment would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation pace and technology cost curves. Quarterly review of hydrogen pilot program expansion, CE marking threshold revisions, and utility program enrollment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Europe Residential Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Marine Boiler Burner Market
Boilers
Industrial and Residential Heating Market
Boilers
Boiler Combustion Chamber Market
Boilers
Power Plant Boiler Market
Boilers
North America Industrial Boiler Market
Boilers
US Commercial Boiler Market
Boilers
Europe Combined Heat and Power Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Superheater Tubes Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Biomass Boiler Market
Boilers
Superheater Market