
 Electric Boiler Market | 2026-2036
Electric Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Boiler Market Analysis
Market Context
Data center thermal management is repositioning electric boilers from seasonal heating equipment to year-round industrial assets. Bosch Thermotechnology leverages its European service network to dominate replacement cycles in commercial buildings. PARAT Halvorsen anchors its competitiveness through electrode boiler specialization for marine and offshore process steam. Viessmann Climate Solutions extends its residential heat pump integration into hybrid electric boiler systems for multi-family housing.
Technical Definition and Segment Structure
An electric boiler converts electrical energy into thermal energy through resistance heating elements, electrode immersion, or induction coils, producing hot water or saturated steam at pressures up to critical ranges for industrial process applications. Modular product types are capturing the fastest growth as facilities scale capacity in incremental megawatt blocks rather than committing to single large installations. The industrial end user segment sustains the deepest margin pools where electrode technology displaces fuel oil in food processing and pharmaceutical sterilization. Low capacity units face commoditization pressure from Asian manufacturers while ultra high capacity systems concentrate among European specialists with ASME and PED certification depth.
Regulatory Frame
The EU Ecodesign Directive and F-Gas Regulation tighten permissible emissions from competing gas-fired systems, directly expanding the addressable base for electric alternatives in member states. EPA emissions standards under the Clean Air Act and state-level building performance standards in California and New York mandate electrification pathways that elevate electric boiler specifications in commercial construction. Stakeholders must monitor grid interconnection queue delays and capacity market reforms that determine whether electrified heat can deliver promised carbon reductions at dispatchable reliability.
Market Dynamics
Grid-interconnection queue delays and capacity market reforms are forcing district heating operators to reconsider electrification timelines, creating a structural tension between decarbonization mandates and dispatchable reliability requirements.
Growth Catalysts
- EU F-Gas Regulation:Tightening permissible emissions from competing gas-fired systems expands the addressable base for electrode and resistance boiler alternatives across member states with building decarbonization codes.
- Industrial process-heat retrofits:Food processing and pharmaceutical sterilization facilities in Germany, Norway, and Finland are accelerating fuel oil displacement through modular electric unit procurement.
- Data center thermal management:Hyperscale operators are repositioning electric boilers from seasonal heating equipment to year-round industrial assets for server cooling integration.
Market Restraints
- Electricity price volatility:Industrial buyers face input cost exposure from spot market fluctuations that erode operating cost advantages over gas-fired alternatives.
- Asian manufacturer commoditization:Low capacity units face margin compression from offshore suppliers lacking ASME and PED certification depth.
- Grid capacity constraints:Distribution infrastructure limitations in Nordic municipalities delay interconnection approvals for multi-megawatt installations.
Strategic Opportunities
- Marine and offshore process steam:Electrode boiler specialization for vessel propulsion and platform heating represents underpenetrated demand outside district heating.
- Hybrid heat pump integration:Multi-family housing developers are specifying combined electric boiler and heat pump systems for peak-load management.
- State-level building performance standards:California and New York mandates are elevating electric boiler specifications in commercial construction procurement.
Industry Challenges
- ASME and PED certification timelines:Ultra high capacity system manufacturers face extended approval cycles that compress project delivery windows.
- Electrode boiler engineering talent:Specialized design and commissioning expertise concentrates among European specialists, constraining scaling capacity.
- Legacy control system integration:Industrial facilities require complex retrofitting to connect modular electric units to existing SCADA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Boiler Market |
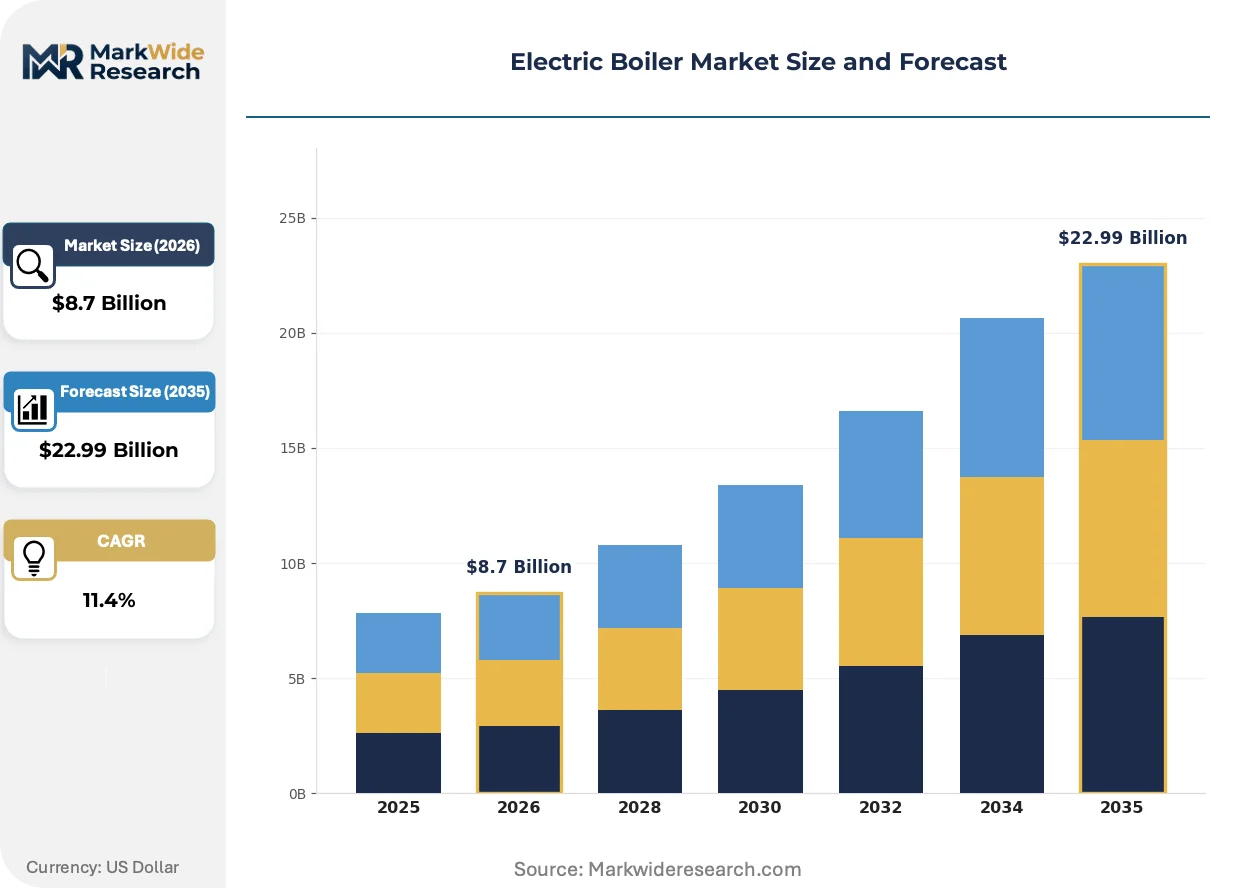
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instantaneous, Storage, Combination, Modular End User: Residential, Commercial, Industrial, Institutional Technology: Thermal, Electric Resistance, Induction, Heat Pump Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Chromalox, PARAT Halvorsen, Bosch Thermotechnology, Danstoker, Fulton Boiler Works, Viessmann Climate Solutions, Babcock & Wilcox, U.S. Boiler Company, Cleaver-Brooks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Boiler Market Emerging Trajectories
Electrification mandates are colliding with grid reliability constraints, forcing technology suppliers to innovate around dispatchability and modular scaling rather than pure capacity expansion.
Electrode immersion systems are automating load-following capabilities that match steam output to real-time renewable generation profiles. District heating operators in Denmark and Sweden are deploying these units to avoid curtailment penalties during wind power oversupply periods. The technology is automating revenue stacking opportunities that were previously unavailable to thermal assets.
EPA emissions standards under the Clean Air Act are tightening NOx and particulate thresholds for commercial boiler installations. Industrial facilities in Texas and Pennsylvania are pre-emptively specifying electric alternatives to avoid compliance retrofit costs. The regulation is accelerating specification changes in process industries where fuel switching had previously been deferred.
Service contract unbundling is fragmenting the traditional bundled maintenance model that dominated commercial heating. Facility managers in German municipal buildings are separating equipment procurement from long-term service agreements, forcing OEMs to compete on discrete performance metrics. The shift is most visible in replacement cycles where incumbent suppliers face re-bidding pressure.
Electric Boiler Market Segmentation
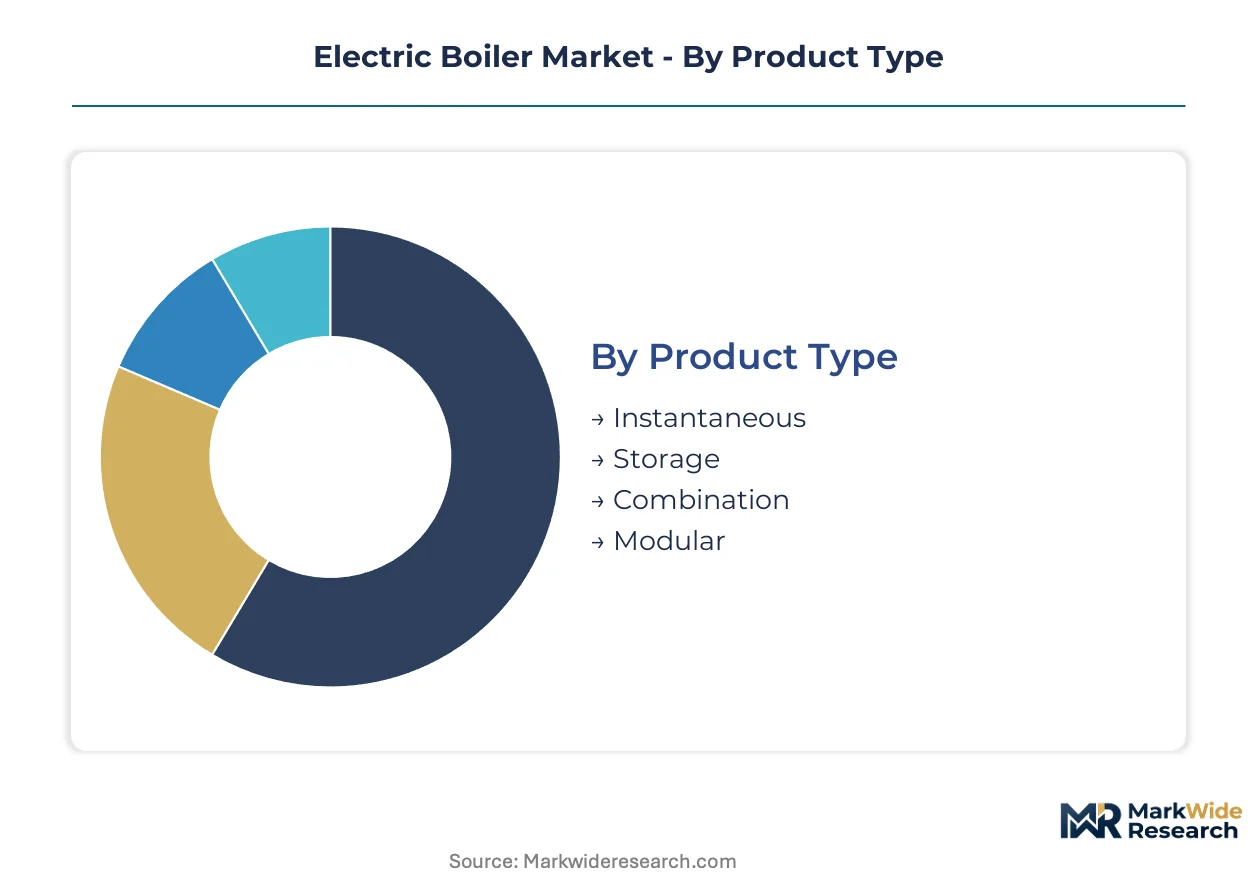
Electric boiler procurement patterns diverge sharply across building types and thermal loads, forcing manufacturers to maintain parallel product architectures. The report examines four critical dimensions—product configuration, end-use application, heating technology, and unit scale—that determine specification requirements and margin structures.
Product Type:
Standardization pressure intensifies at the low-capacity end while industrial buyers demand bespoke engineering for integrated thermal systems.
- Instantaneous:Compact wall-mounted units deliver hot water on demand without storage vessels, eliminating standby losses. German municipal housing authorities specify these for retrofit programs where space constraints dominate.
- Storage:Tank-integrated systems buffer thermal energy for peak-shaving and demand response participation. District heating operators in Finland deploy electrode-equipped storage boilers to arbitrage hourly electricity price spreads.
- Combination:Dual-function units merge space heating and domestic hot water production in single enclosures. Norwegian multi-family developers favor these for reduced mechanical room footprints.
- Modular:Incremental megawatt blocks enable capacity scaling without full-system replacement. Data center operators in Sweden specify modular arrays for phased load growth alignment.
Most installed capacity flows through Storage configurations. Expansion is steepest in Modular systems.
End User:
Margin concentration shifts toward process-heat applications where technical complexity erects competitive barriers.
- Residential:Single-family and multi-family dwellings drive volume through replacement cycles. Building decarbonization codes in California and New York mandate electric heating in new construction.
- Commercial:Office buildings, retail, and hospitality facilities prioritize compact footprints and smart grid integration. German facility managers unbundle service contracts to pressure OEM pricing.
- Industrial:Food processing, pharmaceutical sterilization, and chemical process-heat applications sustain premium pricing. Electrode technology displaces fuel oil in Nordic manufacturing retrofits.
- Institutional:Hospitals, universities, and government buildings require redundant thermal capacity with 99.9% uptime guarantees. EPA emissions standards accelerate fuel switching in US public sector procurement.
Industrial buyers command the deepest margin pools. Residential volume expands most rapidly under electrification mandates.
Technology:
Heat transfer mechanisms determine efficiency ceilings and grid-interaction capabilities across the installed base.
- Thermal:Direct element-to-fluid heat transfer dominates residential and light commercial applications. Asian manufacturers compress margins through standardized production.
- Electric Resistance:Nickel-chromium or iron-chromium-aluminum elements convert electricity to heat with near-unity efficiency. US commercial buildings specify these for compliance with state-level building performance standards.
- Induction:Electromagnetic field generation heats ferrous materials without direct element contact. Marine applications in Norway exploit induction's rapid thermal response for vessel propulsion systems.
- Heat Pump:Refrigerant-cycle systems amplify thermal output above electrical input, though classification overlaps with hybrid configurations. German residential developers integrate heat pumps with electric resistance backup for peak-load coverage.
Electric Resistance retains the largest installed base. Induction systems are climbing the fastest on marine and offshore demand.
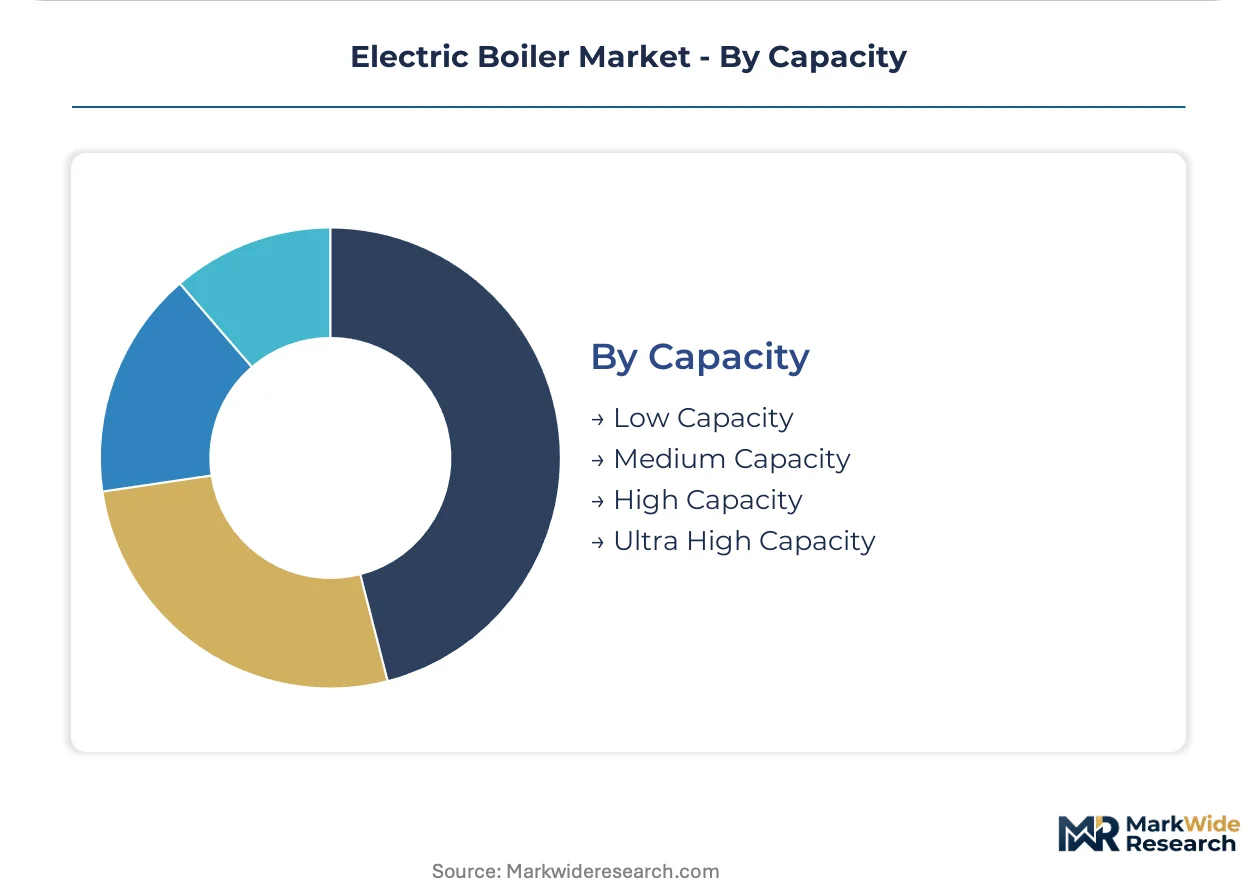
Capacity:
Certification requirements and engineering talent scarcity stratify competitive dynamics across the scale spectrum.
- Low Capacity:Units below 50 kW serve single-family dwellings and small commercial tenants. Offshore suppliers without ASME or PED certification erode pricing power.
- Medium Capacity:50-500 kW systems address multi-family housing and light industrial process loads. Nordic district heating procurement concentrates in this band for distributed generation nodes.
- High Capacity:500 kW-5 MW installations supply centralized heating plants and manufacturing facilities. Extended ASME and PED approval timelines compress project delivery windows.
- Ultra High Capacity:Systems exceeding 5 MW require specialized electrode engineering and custom control integration. European specialists with marine certification anchor competitiveness in this tier.
Medium Capacity units dominate procurement volumes. Ultra High Capacity systems exhibit the steepest expansion trajectory on industrial retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate electrode boiler assembly to jurisdictions with streamlined PED certification timelines and subsidized industrial electrification programs.
Germany
Industrial process-heat retrofits in food processing and chemical manufacturing drive procurement volumes. The EU Ecodesign Directive and national building decarbonization codes mandate electrification pathways in commercial construction. The Rhine-Ruhr industrial cluster hosts concentrated demand for ultra high capacity electrode systems in steel and pharmaceutical sterilization applications.
United States
Data center thermal management and district heating electrification create dual demand channels for modular electric units. EPA emissions standards under the Clean Air Act tighten NOx thresholds for commercial boiler installations. Texas and Pennsylvania industrial facilities are pre-emptively specifying electric alternatives to avoid compliance retrofit costs in process industries.
Norway
Marine and offshore process steam applications anchor demand for rapid-response induction systems in vessel propulsion. Grid-electrification mandates coincide with industrial process-heat retrofits in coastal manufacturing zones. Stavanger and Bergen harbor districts concentrate procurement of electrode-equipped storage boilers for offshore platform heating.
Sweden
Hyperscale data center operators specify modular arrays for phased load growth alignment with renewable generation profiles. The EU F-Gas Regulation redirects capital from gas infrastructure toward resistance boiler installations. Stockholm and Malmö municipal districts deploy automated load-following units to arbitrage hourly electricity price spreads during wind power oversupply.
Finland
District heating operators accelerate procurement of modular electric units for distributed generation nodes. National building decarbonization codes elevate electric boiler specifications in multi-family housing development. Helsinki metropolitan procurement concentrates in medium-capacity systems for peak-shaving and demand response participation.
Electric Boiler Market Vendor Landscape
Technology licensing dominates the current landscape as European specialists monetize electrode engineering expertise through regional partnership structures. The vendor base stratifies across three tiers: diversified HVAC conglomerates with integrated service networks, marine-certified electrode specialists with ASME depth, and Asian fabricators compressing margins in standardized low-capacity segments. Competitive positioning hinges on certification velocity, control system integration capabilities, and unbundled service contract penetration.
Among diversified European HVAC conglomerates, Bosch Thermotechnology and Viessmann Climate Solutions exemplify the service-network archetype, leveraging established maintenance infrastructures to defend replacement cycle positions. PARAT Halvorsen occupies the marine-specialist tier, anchoring competitiveness through offshore certification depth and vessel propulsion applications. These three entities represent contrasting strategic postures: scale-driven portfolio breadth, vertical integration into hybrid system architecture, and technical specialization in demanding process environments.
| Leading Market Players |
|---|
| Chromalox |
| PARAT Halvorsen |
| Bosch Thermotechnology |
| Danstoker |
| Fulton Boiler Works |
| Viessmann Climate Solutions |
| Babcock & Wilcox |
| U.S. Boiler Company |
| Cleaver-Brooks |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Norway maintain pricing discipline through captive electrode engineering expertise and selective PED certification investments. Their ownership structure insulates margin pools from quarterly earnings pressure while reinforcing long-term supply commitments to district heating operators and marine propulsion integrators.
Pricing Analysis
Distributor margins in the 15-25% range separate certified European fabricators from Asian commodity suppliers lacking ASME depth. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and control-system integration complexity. Cost compression in low-capacity residential units is intensifying because offshore manufacturers are flooding replacement cycles with unbundled hardware. Industrial process-heat buyers exhibit the lowest price sensitivity due to uptime guarantees and sterilization compliance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore anchor hub-and-spoke patterns for electrode boiler components and resistance element assemblies. Manufacturing concentrates in Germany, Norway, and China, with European specialists retaining ultra high capacity electrode production while Chinese fabricators dominate standardized thermal units below 50 kW. Nickel-chromium heating elements, pressure vessel steel, and SCADA control modules constitute critical input dependencies. Single-source vulnerability around marine-grade induction coil winding creates chokepoint exposure for Norwegian offshore suppliers. Distribution runs through OEM-direct channels for industrial projects and HVAC wholesale networks for commercial replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in electric boilers rests on electrode automation reducing commissioning labor intensity and hybrid heat pump integration commanding premium positioning in multi-family housing procurement.
For Market Incumbents: Acquire specialized electrode engineering boutiques in Denmark and Sweden to consolidate load-following automation IP before district heating operators internalize design capabilities. Incumbents must defend installed base positions by embedding predictive maintenance software into legacy SCADA architectures, countering unbundled service contract fragmentation that German municipal facility managers are accelerating. For New Entrants and Emerging Players: Launch via direct-to-industrial EPC partnerships in Texas and Pennsylvania data center thermal management, bypassing saturated HVAC distribution channels. Marine and offshore process steam in Norwegian coastal zones offers the most penetrable white space, with vessel propulsion retrofits underserved by incumbent land-focused specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among electrode automation software layers and marine certification holders with ASME-PED dual accreditation. Long-term viability favors platforms integrating dispatchable thermal assets with renewable generation arbitrage. Watch for F-Gas Regulation enforcement intensity in German industrial clusters as the inflection signal for accelerated fuel-switching capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Electrode Automation Investment | Load-following capabilities capture wind power oversupply revenue in Danish district heating networks. |
| Marine Certification Expansion | ASME-PED dual accreditation unlocks Norwegian offshore platform and vessel propulsion procurement. |
| Hybrid System Integration | Combined heat pump and resistance boiler configurations penetrate German multi-family housing mandates. |
| Service Contract Unbundling | Discrete performance metrics respond to German municipal facility manager procurement restructuring. |
| Data Center Thermal Partnership | Year-round industrial asset positioning captures hyperscale operator cooling integration specifications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with district heating procurement officers, marine engineering directors, industrial plant managers, and EPC contractors with secondary validation from EU Ecodesign Directive filings, F-Gas Regulation implementation reports, EPA Clean Air Act enforcement databases, and Nordic customs trade records. Bottom-up installation tracking and top-down energy demand modeling provided triangulation across the analysis window.
Historical reference periods anchored the projection horizon through capacity deployment velocity and electrification mandate implementation curves. Segmentation dimensions modeled include product configuration, end-use application, heating technology mechanism, and unit capacity tier alongside regional regulatory framework clustering. CAGRs derived from unit shipment trajectories and average selling price movements across certified and uncertified supply tiers. Forecast inputs incorporated grid interconnection queue dynamics and capacity market reform timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under electricity price volatility spikes and extended PED certification delays. Outputs reflect documented assumptions regarding mandate enforcement intensity and industrial retrofit capital availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Superheater Tubes Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Combi Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
GCC Electric Water Heater Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Commercial Boiler Market
Boilers
Boiler System Market
Boilers
Reformer Unit Market
Boilers
Europe Residential Boiler Market
Boilers
Gas Fired Boilers Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
US Boiler Market