
 Asia-Pacific Combined Heat and Power Market | 2026-2036
Asia-Pacific Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Combined Heat and Power Market Outlook
Aftermarket service revenue is narrowing toward turnkey performance contracts as owners outsource operational risk. Siemens Energy AG leverages its digital turbine monitoring platforms to sustain long-term service agreements across Southeast Asian industrial parks. Mitsubishi Heavy Industries Ltd anchors its position through in-house production of gas turbine components, controlling spare parts availability for regional utilities. Wärtsilä Corporation competes on fuel flexibility, positioning its reciprocating engine systems for biogas and synthetic fuel conversions in Pacific island grids.
Combined heat and power denotes integrated energy systems that simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving total system efficiencies of 75-90% through waste heat recovery. The technology serves industrial facilities, district heating networks, and critical infrastructure requiring reliable baseload power with thermal output for process steam or space conditioning. Natural gas-fired installations dominate current deployment, though biomass systems are gaining traction in Indonesia and Thailand where agricultural residues provide low-cost feedstock. Distributed installation models are expanding fastest among commercial campuses and manufacturing clusters seeking resilience against grid volatility, while centralized utility-scale plants remain the margin pool in South Korea and Japan where district heating infrastructure is mature.
Japan's METI enforces efficiency benchmarks under its Top Runner program, compelling equipment upgrades in existing cogeneration fleets. China's MEE implements emission intensity rules that favor gas-fired CHP over coal-only plants in the Beijing-Tianjin-Hebei airshed. Australia's CEFC and state-level clean energy agencies channel concessional finance toward biogas and hydrogen-ready systems. Stakeholders must weigh fuel price hedging strategies against evolving carbon border mechanisms and local content requirements that reshape equipment procurement decisions.
Market Dynamics
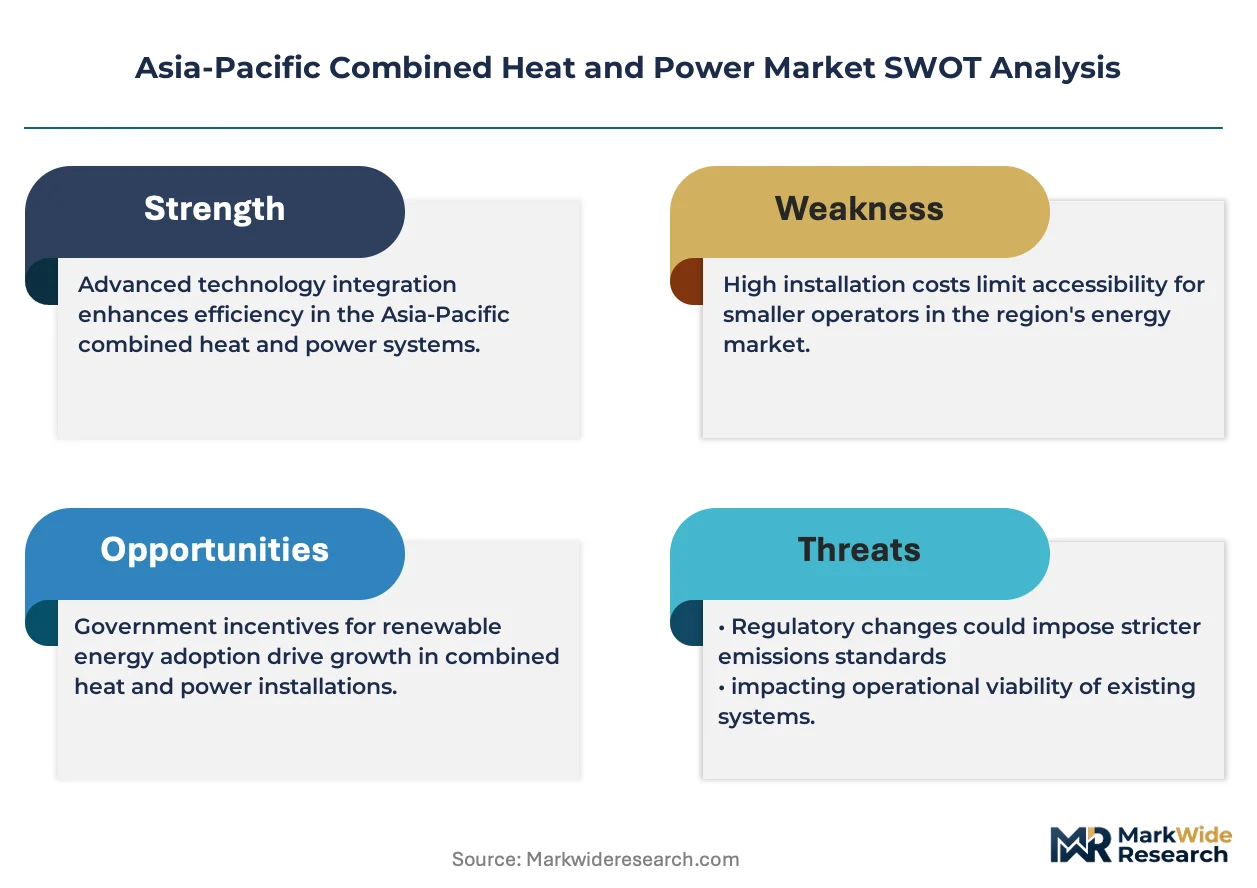
Japan's METI efficiency mandates are compressing replacement cycles for aging gas turbine fleets while China's MEE emission intensity rules accelerate fuel switching across the Beijing-Tianjin-Hebei industrial corridor. Equipment suppliers now face parallel pressure to deliver higher thermal efficiency and lower NOx profiles under tightening multi-jurisdictional standards.
Growth Catalysts
- Data center load growth:Southeast Asian operators are expanding on-site generation capacity to manage grid instability and secure baseload power for hyperscale facilities.
- Top Runner program mandates:Japan's METI compels commercial cogeneration upgrades through binding efficiency benchmarks that trigger fleet modernization.
- Biomass feedstock availability:Agricultural residues in Indonesia and Thailand enable low-cost thermal input for industrial process steam applications.
Market Restraints
- Natural gas price volatility:Import-dependent economies face margin compression when LNG spot markets spike, eroding CHP payback periods.
- Core component supply concentration:Precision turbine blade casting capacity concentrates in a handful of specialized foundries, creating procurement bottlenecks.
- Grid parity pressure:Utility-scale solar plus battery configurations in Australia threaten distributed gas-fired generation economics.
Strategic Opportunities
- Hydrogen-ready system deployment:Australia's CEFC concessional finance supports turbine retrofits capable of burning hydrogen blends, positioning assets for fuel transition.
- District heating network expansion:South Korea's mature infrastructure creates aftermarket service expansion potential for performance-based O&M contracts.
- Synthetic fuel convergence:Reciprocating engine systems capable of biogas and e-fuel flexibility capture Pacific island grid modernization projects.
Industry Challenges
- Turbine specialist workforce scarcity:Southeast Asian markets lack sufficient field service engineers trained on advanced gas turbine diagnostics and hot-path inspections.
- Legacy control system integration:Brownfield industrial sites struggle to retrofit digital monitoring platforms onto 1990s-era distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Combined Heat and Power Market |
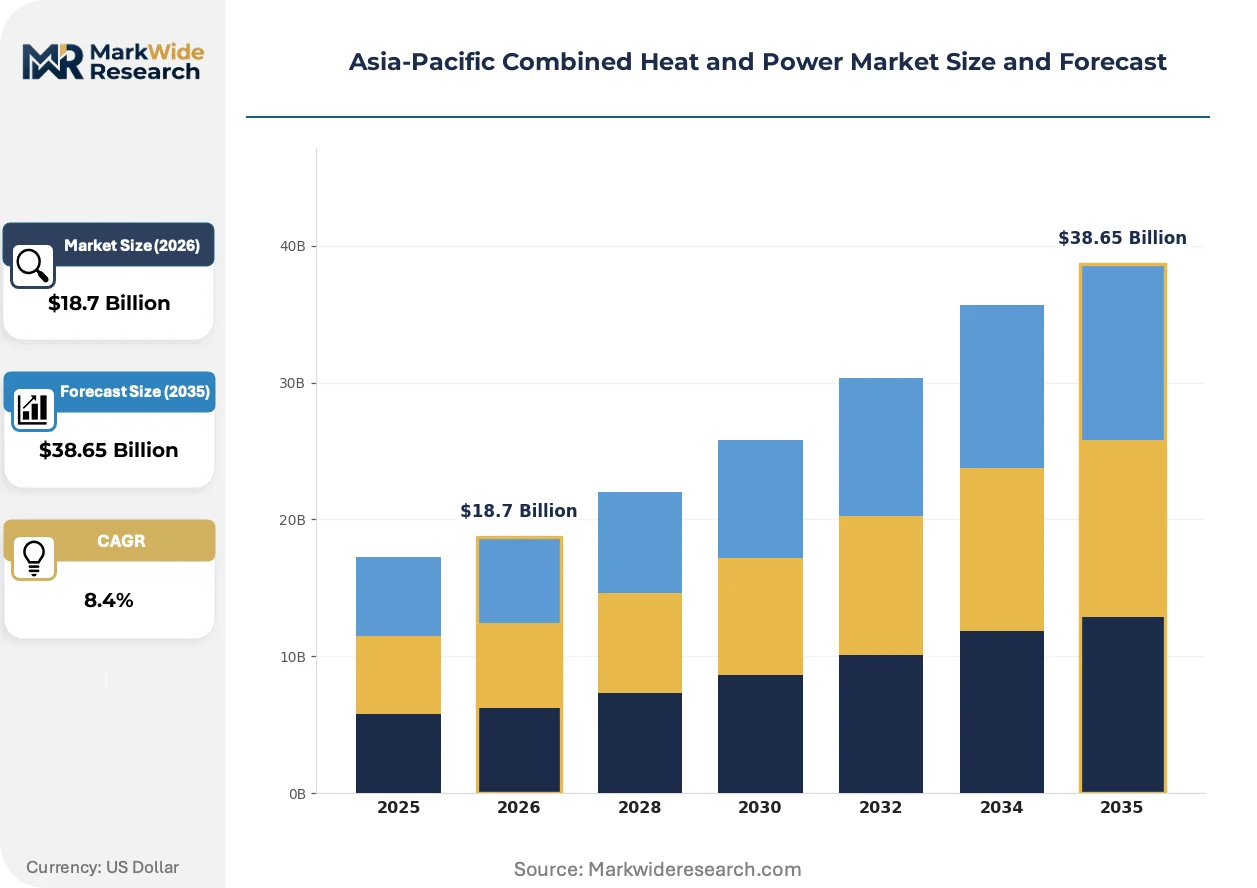
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: On-Site, Distributed, Centralized, Remote Fuel Type: Natural Gas, Biomass, Coal, Oil Technology: Steam Turbines, Gas Engines, Reciprocating Engines, Microturbines Application: Industrial, Residential, Commercial, Utility |
| Companies Covered | Siemens Energy AG, Mitsubishi Heavy Industries Ltd, General Electric Company, Wärtsilä Corporation, Kawasaki Heavy Industries Ltd, MAN Energy Solutions SE, Caterpillar Inc., Veolia Environnement SA, Mitsubishi Electric Asia Pte Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Combined Heat and Power Market Strategic Shifts
Digital twin architectures and predictive maintenance algorithms are restructuring how asset owners manage operational risk across dispersed generation portfolios. Equipment suppliers now bundle hardware with long-term performance guarantees rather than transactional spare parts sales.
Advanced turbine inlet cooling systems are rendering obsolete fixed-capacity peaking plants in tropical climates. Thai and Vietnamese independent power producers are retrofitting existing gas turbines with fogging and absorption chiller packages to recover lost output during high ambient temperature periods. This thermal augmentation technology is rendering obsolete simple-cycle peakers that cannot match the efficiency gains of upgraded CHP configurations.
China's MEE emission intensity rules favor gas-fired CHP over coal-only generation in the Beijing-Tianjin-Hebei airshed. Steel and chemical producers must demonstrate lower carbon intensity per unit of output or face production curtailments. Eastern China's industrial corridor is responding by accelerating captive power plant fuel switching and installing waste heat recovery boilers to capture thermal output.
Aftermarket service unbundling is disrupting traditional OEM service monopolies. Industrial park operators in Malaysia and Indonesia now tender O&M contracts separately from equipment procurement, opening entry points for specialized third-party service providers. This procurement fragmentation is most visible in textile and food processing clusters where multi-tenant facilities aggregate sufficient installed base to justify dedicated maintenance teams.
Asia-Pacific Combined Heat and Power Market Segmentation
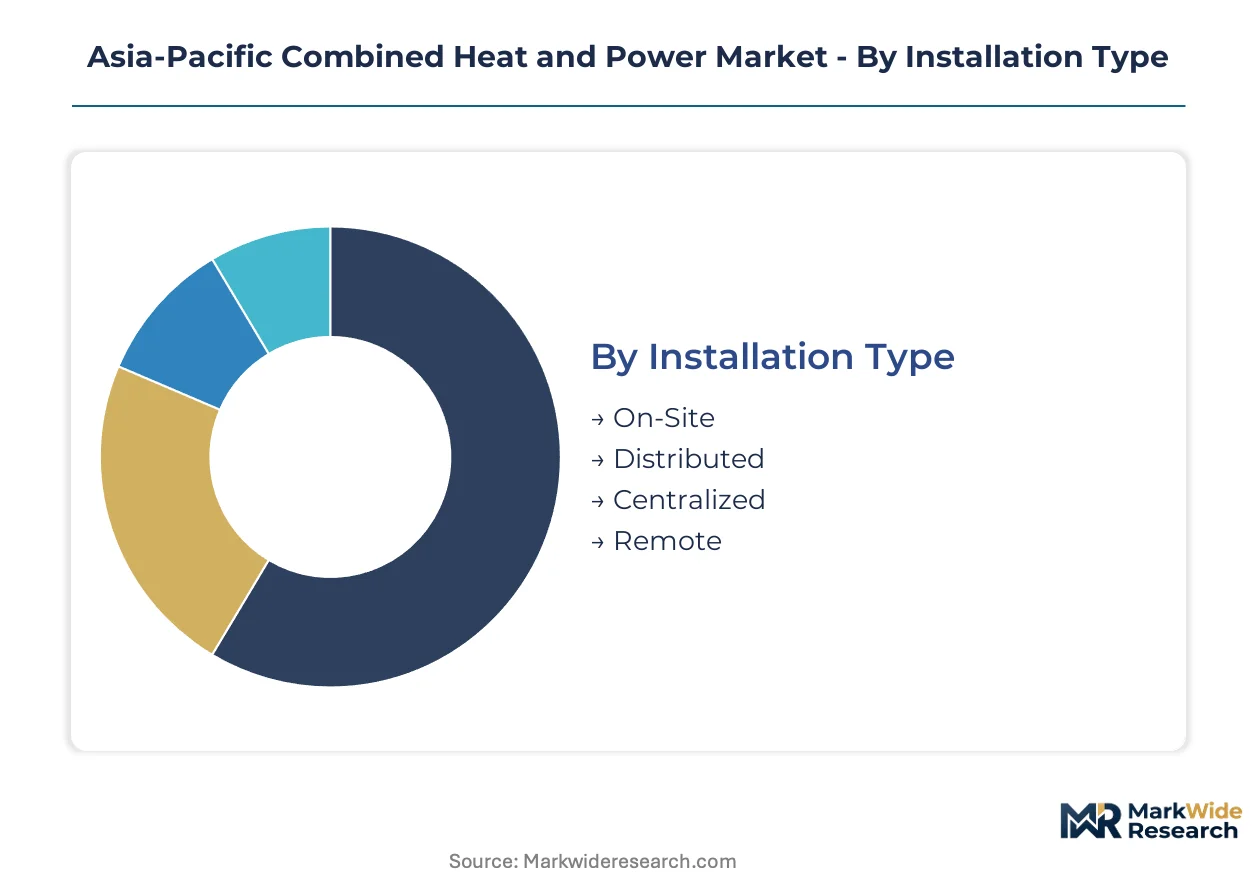
Segmentation in Asia-Pacific combined heat and power markets reveals divergent capital deployment patterns across installation scales, fuel portfolios, and technology vintages. Equipment suppliers and project developers must align product configurations with distinct risk-return profiles governing each segment's procurement behavior.
Installation Type:
Mature centralized utilities anchor established revenue streams while distributed models emerge as the primary expansion frontier across Southeast Asian industrial zones.
- On-Site:Captive generation systems installed within facility boundaries serve steel mills, chemical complexes, and data centers requiring thermal-electric integration with grid independence. Japanese automotive manufacturers and Thai petrochemical operators favor this configuration to isolate operations from transmission instability.
- Distributed:Multi-tenant generation assets serving industrial parks and commercial campuses aggregate thermal loads across multiple off-takers. Vietnam's northern manufacturing corridors and Indonesia's Batam free trade zone host the densest concentrations of distributed CHP infrastructure.
- Centralized:Large-scale district heating plants with co-located power generation dominate South Korean urban heating networks and legacy Japanese city gas systems. These assets face replacement pressure under METI efficiency mandates.
- Remote:Standalone systems powering mining camps, island grids, and offshore platforms prioritize fuel flexibility over thermal efficiency. Australian LNG extraction facilities and Pacific island utilities specify remote configurations with multi-fuel engine capabilities.
Centralized installations retain volume leadership; distributed configurations hold the steepest expansion curve.
Fuel Type:
Cost tiers stratify procurement decisions between pipeline-accessible feedstocks and residue-based alternatives with localized supply economics.
- Natural Gas:Pipeline and LNG-delivered methane dominates new capacity additions across Japan, South Korea, and eastern China's industrial corridor. METI emission intensity rules and China's MEE airshed regulations explicitly favor gas-fired CHP over coal alternatives in designated zones.
- Biomass:Agricultural residues including rice husks, palm kernel shells, and bagasse enable low-cost thermal input for Indonesian pulp mills and Thai food processing clusters. Feedstock seasonality constrains year-round dispatch reliability.
- Coal:Existing captive power plants at Chinese steel and chemical facilities face accelerated fuel switching requirements under Beijing-Tianjin-Hebei emission intensity caps. Greenfield coal CHP encounters effective prohibition in coastal provinces.
- Oil:Diesel and heavy fuel oil systems persist in Pacific island grids and remote Australian mining operations where gas infrastructure remains uneconomic. High operating costs limit expansion to backup and peaking applications.
Natural gas commands the dominant share of new investment; biomass feedstocks are climbing fastest in ASEAN manufacturing zones.
Technology:
Application requirements dictate technology selection across baseload, peaking, and process-integrated operating regimes.
- Steam Turbines:Large-scale extraction-condensing configurations serve industrial process steam applications at chemical and paper facilities. Chinese steel mills retrofit waste heat recovery boilers to existing steam cycles for compliance with MEE carbon intensity benchmarks.
- Gas Engines:Spark-ignited and dual-fuel reciprocating engines deliver modular capacity additions with rapid ramp rates for grid-following duty. Australian independent power producers specify gas engines for hybrid renewable firming applications.
- Reciprocating Engines:Compression-ignition systems burn diesel, heavy fuel oil, and biogas blends across Pacific island utilities and remote industrial sites. Wärtsilä Corporation positions these assets for synthetic fuel conversion readiness.
- Microturbines:Compact sub-megawatt systems target commercial building thermal loads and small-scale district heating networks. South Korean apartment complexes and Japanese hospital campuses deploy microturbines for on-site resilience.
Steam turbines anchor utility-scale deployment; gas engines are expanding most quickly behind meter at industrial facilities.
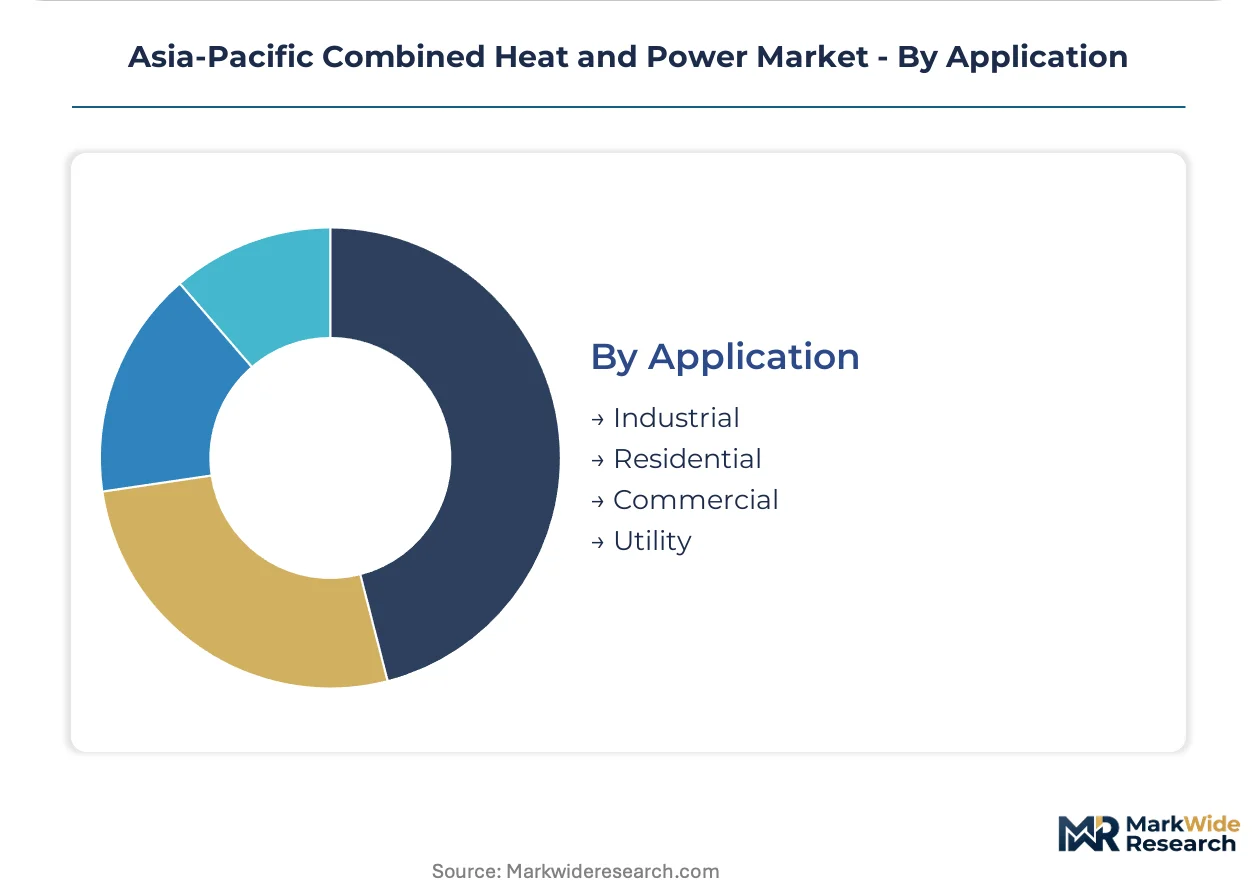
Application:
Customer type determines thermal load profiles, dispatch requirements, and contracting structures governing equipment procurement.
- Industrial:Continuous process industries including chemicals, pulp and paper, and food processing constitute the core thermal demand base. Eastern China's steel corridor and Indonesia's pulp mill clusters drive the largest project pipelines.
- Residential:District heating connections in South Korean apartment complexes and legacy Japanese city gas networks sustain established service territories. New residential CHP penetration remains limited by competing heat pump economics.
- Commercial:Hotels, hospitals, and shopping centers deploy sub-megawatt systems for baseload power with absorption cooling. Singapore's integrated resort developments and Bangkok hospital campuses specify commercial-scale configurations.
- Utility:Grid-connected cogeneration plants sell electricity under power purchase agreements while supplying thermal output to district heating networks. South Korea's KOSPO and Japan's JERA operate the largest utility-owned fleets.
Industrial applications retain volume leadership; commercial installations are gaining share fastest among distributed generation portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in import-dependent Southeast Asian economies exhibit acute price sensitivity to LNG spot volatility, while Japanese and South Korean utilities absorb efficiency premiums with greater elasticity under mandatory upgrade programs.
China
Steel and chemical producers across the Beijing-Tianjin-Hebei airshed face MEE emission intensity caps that compel fuel switching from coal to gas-fired CHP configurations. The ministry's carbon intensity benchmarks per unit of output trigger production curtailments for non-compliant facilities. Eastern China's industrial corridor is accelerating captive power plant retrofits with waste heat recovery boilers to capture thermal output while meeting regulatory thresholds.
Japan
Commercial cogeneration fleet operators confront compressed replacement cycles under METI's Top Runner efficiency mandates that bind equipment upgrades to published benchmarks. The program compels modernization of aging gas turbine installations across manufacturing and district heating applications. Kanto and Kansai metropolitan areas concentrate the heaviest upgrade activity where city gas infrastructure supports distributed thermal networks.
South Korea
KOSPO and other utility operators manage established district heating networks that sustain centralized CHP revenue streams while facing aftermarket service expansion opportunities. The country's mature urban heating infrastructure creates demand for performance-based O&M contracts as assets age. Seoul Capital Area and Busan-Ulsan corridor host the densest concentrations of utility-scale cogeneration capacity requiring operational support.
Australia
Independent power producers specify gas engine systems for hybrid renewable firming applications where grid stability requirements intersect with variable solar output. The CEFC channels concessional finance toward biogas and hydrogen-ready turbine retrofits that position assets for fuel transition. Queensland and Western Australian mining operations deploy remote multi-fuel configurations where gas pipeline economics remain unfavorable.
Vietnam
Northern manufacturing corridors host dense concentrations of distributed CHP infrastructure serving multi-tenant industrial parks with aggregated thermal loads. Textile and electronics manufacturers favor distributed configurations to isolate operations from transmission instability affecting the national grid. Bac Ninh and Hai Phong industrial zones drive capacity additions as foreign direct investment flows into export-oriented manufacturing.
Asia-Pacific Combined Heat and Power Market Competitive Environment
Capability concentration sits with specialized turbine component fabricators controlling precision casting capacity; scale advantage sits with integrated energy conglomerates bundling hardware with long-term service agreements. The market structures around three archetypes: European-origin engineering groups with digital monitoring platforms, Japanese industrial conglomerates with captive component supply chains, and Nordic specialists competing on fuel flexibility. Dominant competitive moves include strategic partnerships for aftermarket service unbundling and technology licensing for hydrogen-ready system retrofits.
Among European-origin engineering groups, Siemens Energy AG and MAN Energy Solutions SE represent the digital-and-service bundled archetype, anchoring positions through turbine monitoring platforms and long-term performance contracts. Mitsubishi Heavy Industries Ltd exemplifies the integrated industrial conglomerate model with in-house gas turbine component production. Wärtsilä Corporation occupies the fuel-flexibility specialist tier, positioning reciprocating engine systems for biogas and synthetic fuel conversions across Pacific island grid applications.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Mitsubishi Heavy Industries Ltd |
| General Electric Company |
| Wärtsilä Corporation |
| Kawasaki Heavy Industries Ltd |
| MAN Energy Solutions SE |
| Caterpillar Inc. |
| Veolia Environnement SA |
| Mitsubishi Electric Asia Pte Ltd |
| Others |
Value Chain & Pricing Dynamics
The Singapore-Jakarta maritime corridor's freight cost dynamics transmit directly into landed equipment pricing across Southeast Asian industrial zones, amplifying the margin compression that suppliers face when precision turbine components concentrate in Japanese and German foundries while buyers in Vietnam and Indonesia demand standardized-economy configurations.
Pricing Analysis
Long-term service agreements now capture the dominant share of lifetime value, displacing transactional spare parts sales as the primary revenue tier. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement decisions, with METI-certified efficiency grades and bundled digital monitoring platforms commanding premiums. Cost compression in the economy tier is intensifying because Indonesian textile clusters and Vietnamese electronics parks aggregate sufficient volume to negotiate fleet-wide discounts. State-owned utilities in South Korea and Thailand exhibit the lowest price sensitivity, while private industrial park operators in Malaysia and Indonesia prioritize capital expenditure minimization over efficiency specifications.
Supply Chain Analysis
Export control regimes limiting advanced gas turbine blade casting technology constrain component flows from German and Japanese specialized foundries to Southeast Asian assembly facilities. Precision casting capacity concentrates in Germany, Japan, and the United States, while final system integration draws from China, South Korea, and Singapore. Nickel-based superalloys, ceramic thermal barrier coatings, and precision control electronics feed from concentrated upstream suppliers. Single-source vulnerability in hot-path component fabrication creates procurement bottlenecks when METI-mandated upgrade cycles synchronize across Japanese utilities. Distribution runs through authorized OEM service networks and emerging third-party aftermarket providers competing for unbundled O&M contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field service engineer scarcity across Southeast Asian markets constrains expansion velocity, with specialized turbine diagnostic expertise concentrated in aging Japanese and European workforces while demand accelerates in Vietnamese and Indonesian industrial corridors.
For Market Incumbents: Build captive spare parts availability as the defensive moat by anchoring regional inventory hubs in Singapore and Busan, insulating against supply chain disruption while METI efficiency mandates compress replacement cycles. Deepen backward integration into precision casting partnerships to secure hot-path component supply against export control friction. Expand performance-based O&M contract penetration in South Korea's aging district heating networks before third-party service providers capture aftermarket share. For New Entrants and Emerging Players: Pursue aftermarket service unbundling as the primary white-space target, tendering dedicated maintenance teams to Malaysian and Indonesian multi-tenant industrial parks where procurement fragmentation has already separated equipment from operational contracts. Biogas-ready reciprocating engine configurations in Thailand's food processing clusters and Pacific island grids represent the most penetrable segment. Position synthetic fuel conversion capabilities as the differentiated go-to-market angle against OEM incumbents locked into gas turbine architectures. For Investors and Strategic Acquirers: Specialized third-party service providers with established technician training pipelines and existing industrial park relationships represent the priority acquisition archetype for exposure to recurring revenue streams. Long-term viability hinges on fuel transition readiness across installed fleets, with hydrogen-blend capability and biogas flexibility determining asset stranding risk. Watch METI's expansion of binding efficiency benchmarks to district heating assets as the signal indicating accelerated replacement demand and aftermarket service expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | Australia's CEFC concessional finance accelerates fuel transition positioning for gas-fired assets. |
| Digital Twin Platform Deployment | Siemens Energy AG leverages predictive maintenance algorithms to secure long-term performance contracts. |
| Biogas Engine System Specification | Wärtsilä Corporation captures Pacific island grid modernization through synthetic fuel conversion readiness. |
| Precision Casting Capacity Expansion | Mitsubishi Heavy Industries Ltd controls hot-path component supply for METI-mandated upgrade cycles. |
| Third-Party O&M Contract Aggregation | Industrial park operators in Batam and Bac Ninh tender separated maintenance agreements from equipment procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads across Japan, South Korea, China, and Southeast Asia; and secondary validation against IEA deployment databases, FERC-style regulatory filings from METI and China's MEE, customs trade records for turbine component flows, and project finance documentation from Australia's CEFC. Bottom-up capacity addition tracking and top-down regulatory impact assessment were triangulated to constrain forecast variance.
Forecast inputs include fuel switching timelines under Beijing-Tianjin-Hebei emission intensity caps, METI Top Runner program expansion scope, and data center load growth trajectories across Singapore, Johor, and Batam. Segmentation dimensions span installation scale, fuel portfolio, technology vintage, and application type across the projection horizon. CAGRs were derived from regression-weighted scenario blending rather than single-point extrapolation. Grid parity pressure from utility-scale solar-plus-battery configurations and LNG spot price volatility curves fed sensitivity testing.
Macroeconomic conditions sit as an overlay; deviation in regional LNG contract pricing, yen-won-yuan exchange rate movements, or carbon border mechanism implementation timing would shift the trajectory. Material shifts in hydrogen infrastructure deployment pace or METI regulatory stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Boiler Control Solutions Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Residential Boiler Market
Boilers
Superheater Tubes Market
Boilers
Industrial Biomass Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Superheater Market
Boilers
Germany Combined Heat and Power Market
Boilers
Europe Power Plant Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Boiler Control Market
Boilers
GCC Electric Water Heater Market
Boilers
Reformer Unit Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Power Plant Boiler Market