
 Europe Power Plant Boiler Market | 2026-2036
Europe Power Plant Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power Plant Boiler Market Foresight
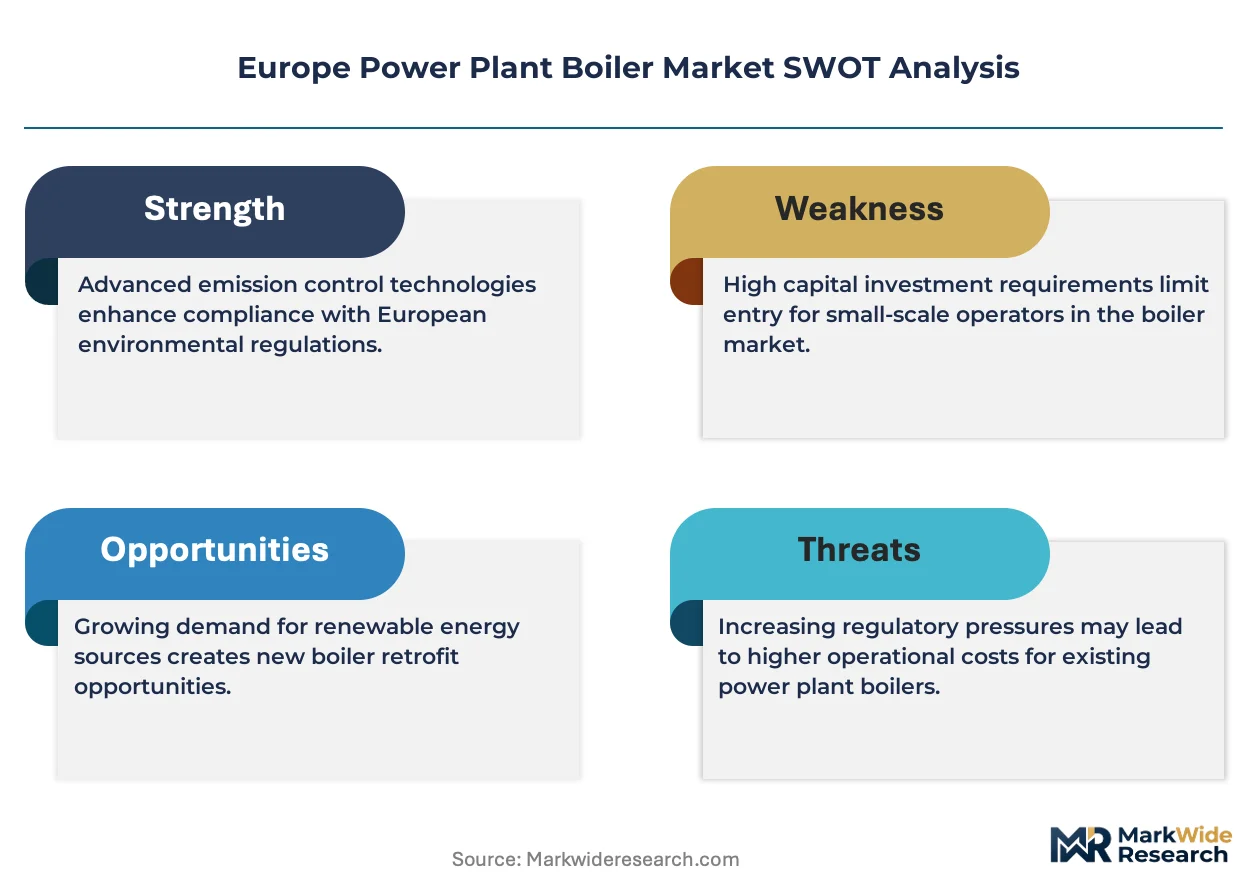
CE marking under the EU Pressure Equipment Directive is collapsing the vendor landscape for high-pressure steam generators above 0.5 bar. Siemens AG leverages its digital twin platform to sustain engineering margins on supercritical retrofit projects. John Cockerill anchors its position through specialized HRSG supply for combined cycle plants across Belgium and France.
Europe power plant boilers are pressurized vessels designed to convert chemical energy from fuel combustion into thermal energy for steam-driven turbines, typically operating at pressures exceeding 150 bar and temperatures above 540°C for supercritical applications. Pulverized coal technology still occupies the largest installed base but faces accelerated retirement schedules under EU ETS carbon pricing. Circulating fluidized bed systems compete aggressively for biomass and waste-to-energy conversions where fuel flexibility commands premium positioning. Combined heat and power applications concentrate margin pools in Nordic and Baltic markets where district heating infrastructure remains state-subsidized.
EU Green Deal emission benchmarks and the F-Gas Regulation constrain refrigerant choices in auxiliary cooling systems, while ECHA REACH compliance adds material certification burdens for alloy suppliers. National regulators in Germany and Poland enforce divergent coal phase-out timelines, fragmenting procurement standardization across member states. Stakeholders must monitor carbon border adjustment mechanism developments to anticipate import cost shifts on boiler-grade steel and specialty tubing.
Market Dynamics
EU ETS carbon pricing is accelerating coal-to-biomass retrofits across Central European utilities, forcing boiler vendors to reengineer combustion systems for variable feedstock quality while maintaining steam parameters.
Growth Catalysts
- EU Green Deal emission benchmarks:National coal phase-out mandates in Germany and Poland are unlocking public financing for district heating network upgrades, creating captive demand for high-efficiency biomass boilers.
- Biomass co-firing technology:Circulating fluidized bed retrofits allow existing pulverized coal units to burn agricultural residues and forestry waste without full replacement capex.
- Nordic district heating infrastructure:State-subsidized combined heat and power programs in Denmark and Sweden sustain premium pricing for supercritical biomass units with thermal storage integration.
Market Restraints
- Alloy supply concentration:CE marking under the EU Pressure Equipment Directive limits qualified suppliers of creep-resistant steel tubing to German and Austrian specialty mills.
- F-Gas Regulation constraints:Refrigerant restrictions on auxiliary cooling systems force boiler OEMs to redesign heat rejection circuits, adding engineering validation cycles.
- Natural gas price volatility:Dutch TTF hub fluctuations compress project IRRs for combined cycle developers in the Netherlands and UK, freezing some procurement decisions.
Strategic Opportunities
- Waste-to-energy conversions:Italian and Spanish municipalities are tendering refuse-derived fuel boiler installations to meet landfill diversion targets under EU Circular Economy Action Plan.
- Digital twin integration:Predictive maintenance platforms for supercritical steam generators open recurring revenue streams beyond equipment sale margins.
- Baltic district heating expansion:Estonian and Latvian cities are replacing Soviet-era heat-only boilers with biomass CHP systems eligible for EU cohesion fund grants.
Industry Challenges
- Welding certification bottlenecks:ECHA REACH compliance for nickel-based superalloys extends material qualification timelines, delaying project handovers.
- Legacy control system integration:Retrofit projects must synchronize new distributed control systems with existing turbine protection logic, multiplying commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power Plant Boiler Market |
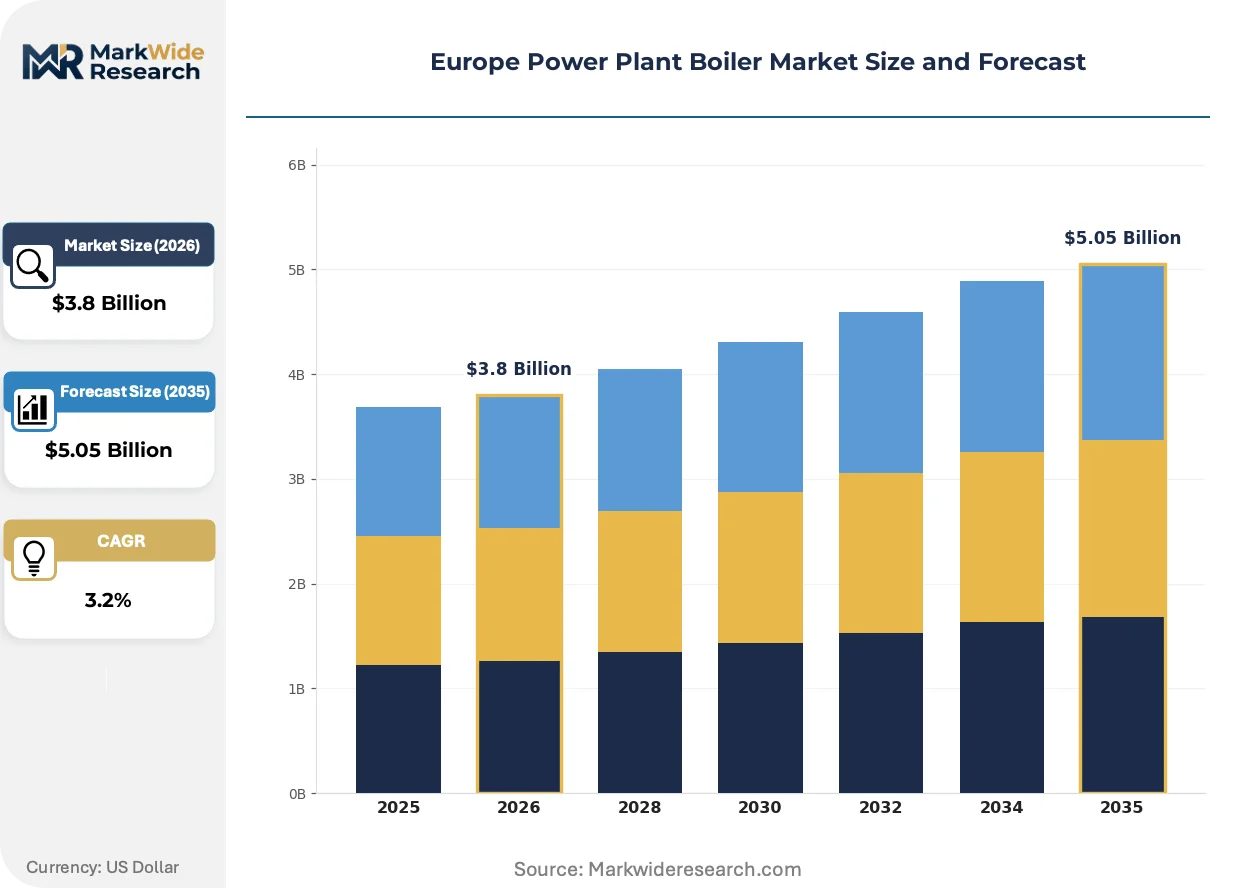
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural Circulation, Forced Circulation, Biomass-fired, Coal-fired Fuel Type: Coal, Biomass, Oil, Natural Gas Application: Industrial Power Generation, Residential Heating, District Heating, Combined Heat and Power Technology: Circulating Fluidized Bed, Pulverized Coal, Watertube, Firetube |
| Companies Covered | BDR Thermea Group, Siemens AG, VIESSMANN, Babcock & Wilcox, Andritz Group, Bosch Limited, A. O. Smith, John Cockerill, Vaillant Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power Plant Boiler Market Shifts & Advancements
Boiler technology trajectories center on fuel flexibility engineering, emissions monitoring digitization, and thermal efficiency optimization under tightening EU carbon accounting rules.
Advanced ultra-supercritical steam conditions—operating above 620°C and 300 bar—are supplanting subcritical drum boilers in new-build projects. Finnish and Polish utilities are specifying these units for biomass and waste-to-energy applications where higher efficiency offsets feedstock cost volatility. The technology is compressing the economic viability window for conventional pulverized coal retrofits that cannot achieve comparable heat rates.
CE marking enforcement under the EU Pressure Equipment Directive is hardening compliance thresholds for high-pressure steam generators above 0.5 bar. Notified bodies in Germany and France are demanding extended fatigue testing for welded joints in cyclic service. Boiler OEMs serving combined cycle plants are responding by pre-certifying modular heat recovery steam generator designs to accelerate site assembly.
Long-term service agreements are displacing transactional spare parts sales as the dominant commercial model. Nordic district heating operators in Sweden and Denmark are bundling twenty-year maintenance contracts with initial equipment procurement, transferring operational risk to vendors. This pattern concentrates margin pools with OEMs capable of remote monitoring and predictive parts logistics.
Europe Power Plant Boiler Market Segmentation
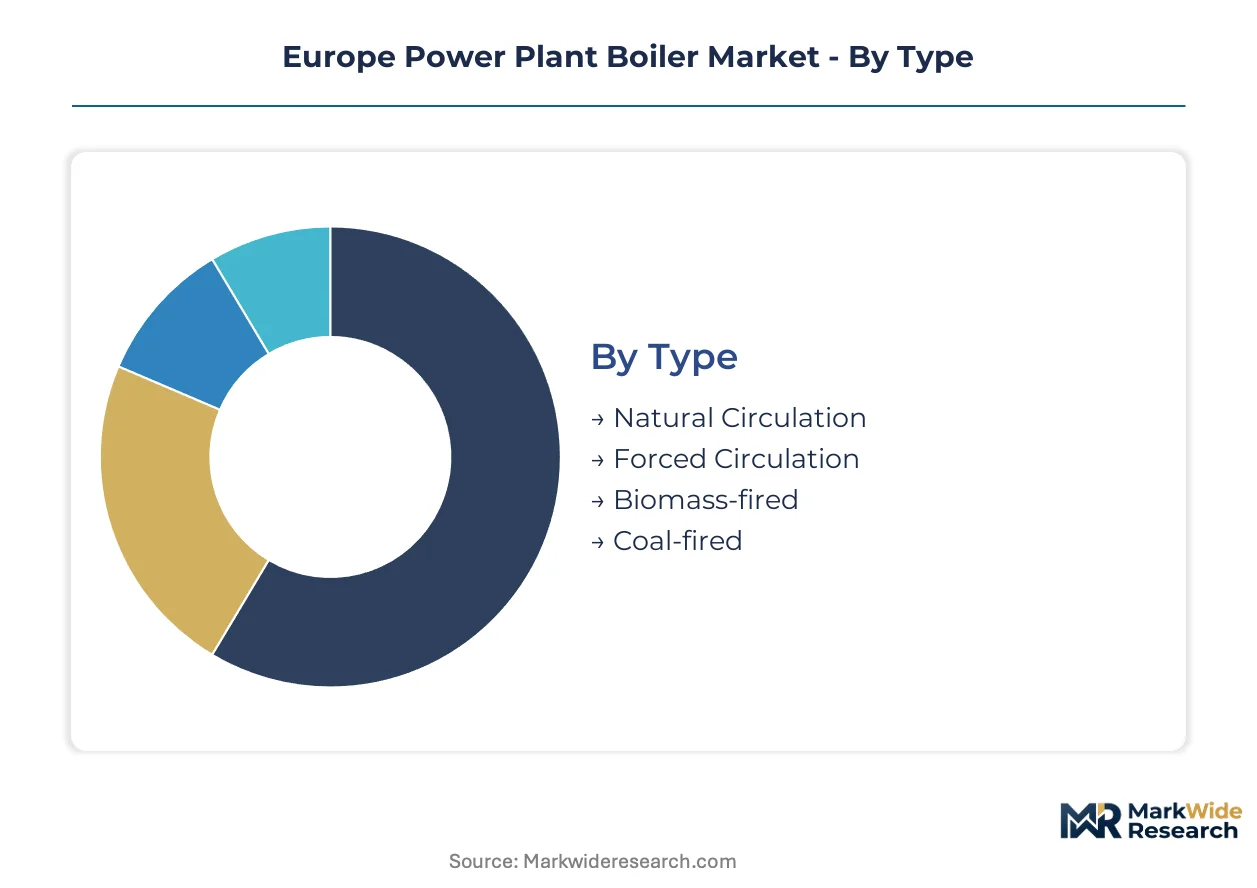
Segmentation in the Europe power plant boiler market reveals how technology choices, fuel switching mandates, and end-use applications fragment procurement patterns across utilities, municipalities, and industrial operators. Understanding these divisions exposes where engineering margins concentrate and which regulatory pressures reshape equipment specifications.
Type:
Channel flows diverge sharply: biomass-fired and coal-fired units move through EPC contractors on utility retrofit contracts, while natural circulation and forced circulation systems reach industrial buyers via specialized boiler distributors.
- Biomass-fired:These systems combust processed agricultural residues, forestry waste, and energy crops in grate-fired or fluidized bed configurations. Danish and Swedish district heating utilities drive premium demand for units with thermal storage integration and automated fuel handling systems.
- Coal-fired:Pulverized coal and circulating fluidized bed designs still occupy the largest installed base across Poland and Germany. Polish utilities under EU ETS pressure are accelerating retrofit schedules or mothballing subcritical units ahead of national phase-out deadlines.
- Natural Circulation:Drum-type boilers rely on density differentials to move water through evaporator circuits without pumps. These dominate legacy industrial installations where operators prioritize operational familiarity over efficiency gains.
- Forced Circulation:Pump-assisted designs enable once-through operation at supercritical pressures above 221 bar. German and French combined cycle developers specify these for heat recovery steam generator applications where compact footprint matters.
Coal-fired units dominate installed base. Biomass-fired systems are where expansion concentrates.
Fuel Type:
Cost tier stratification separates segments: natural gas commands premium pricing in Dutch and UK combined cycle projects, while biomass sits in mid-tier municipal tenders and coal retreats to distressed-asset maintenance contracts.
- Natural Gas:Combined cycle gas turbine plants in the Netherlands and UK specify high-pressure heat recovery steam generators with fast-start capabilities. Dutch TTF hub volatility has frozen some procurement decisions as developers recalculate project IRRs.
- Biomass:Wood pellets, agricultural residues, and refuse-derived fuel feed systems require specialized fuel handling and combustion controls. Finnish utilities lead in specifying advanced ultra-supercritical biomass units operating above 620°C.
- Coal:Bituminous and lignite combustion systems face accelerated retirement under EU Green Deal benchmarks. German hard coal phase-out by 2038 and earlier lignite closures in North Rhine-Westphalia compress remaining service contract windows.
- Oil:Heavy fuel oil and light distillate systems persist as peaking and backup units on Mediterranean islands and remote industrial sites. Greek and Italian island utilities maintain these for grid stability where gas infrastructure remains absent.
Coal retains legacy installed base dominance. Natural gas and biomass are climbing the fastest as new-build and retrofit priorities.
Application:
Customer type fragmentation shapes procurement: utilities run competitive tenders for industrial power generation, while municipalities negotiate long-term service agreements for district heating and combined heat and power.
- Combined Heat and Power:Cogeneration systems simultaneously produce electricity and useful thermal energy for industrial processes or district heating networks. Nordic operators in Denmark and Sweden bundle twenty-year maintenance contracts with initial equipment procurement.
- District Heating:Centralized heat distribution systems supply residential, commercial, and institutional buildings through insulated pipe networks. Estonian and Latvian cities are replacing Soviet-era heat-only boilers with biomass CHP systems eligible for EU cohesion fund grants.
- Industrial Power Generation:Captive power plants serve energy-intensive manufacturing facilities in chemicals, pulp and paper, and cement sectors. German industrial operators face dual pressure from EU ETS compliance and volatile electricity import prices.
- Residential Heating:Small-scale boilers serve individual buildings or small clusters outside district heating coverage. This segment concentrates in rural Central European markets where network extension remains uneconomical.
District heating anchors premium pricing pools. Combined heat and power is gaining share fastest as efficiency regulations tighten.
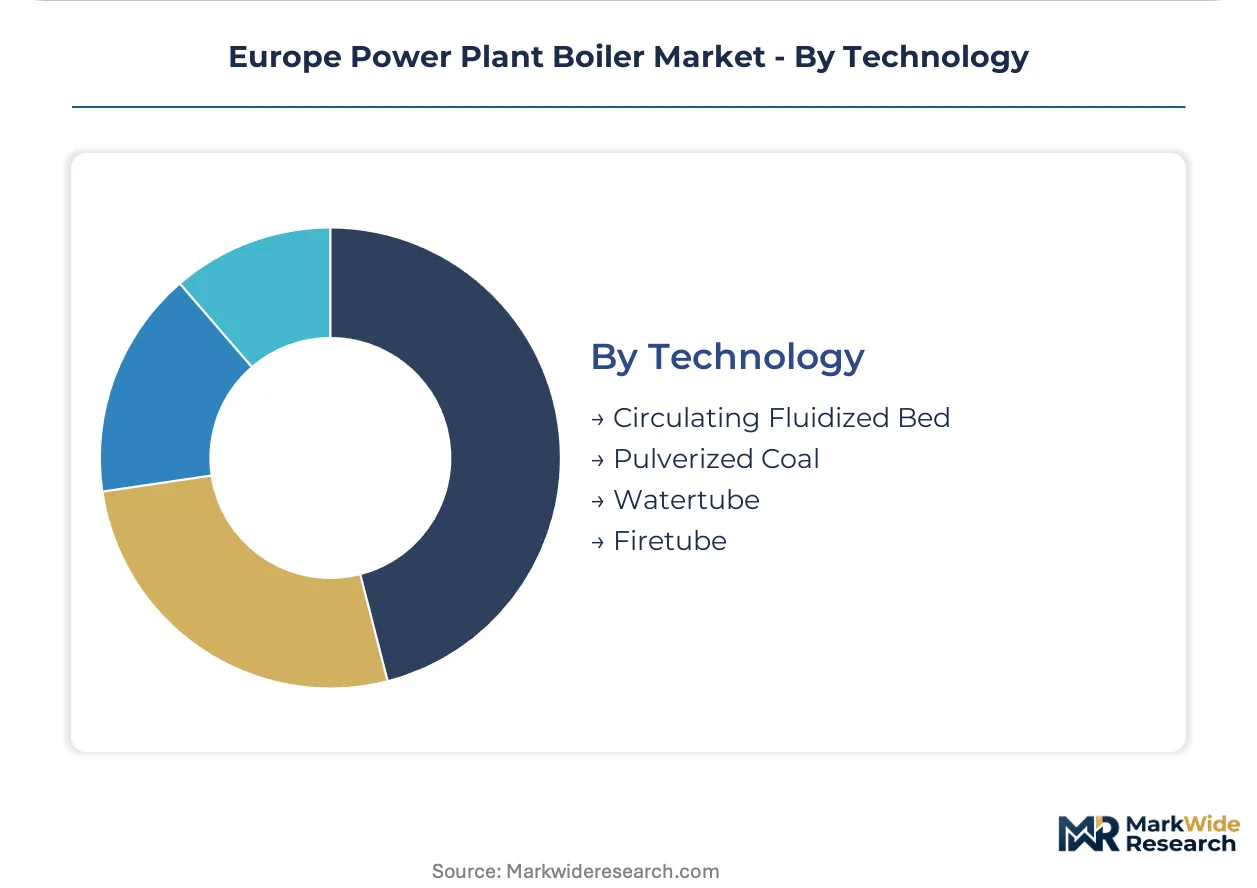
Technology:
Supply concentration determines competitive dynamics: watertube and pulverized coal technologies flow through consolidated EPC channels, while circulating fluidized bed and firetube designs reach buyers through more fragmented engineering procurement routes.
- Circulating Fluidized Bed:These systems suspend fuel particles in upward-flowing air streams, enabling combustion of variable-quality biomass and waste fuels. Polish and Italian utilities specify CFB retrofits to convert aging coal units without full replacement capex.
- Pulverized Coal:Fine coal powder combustion in suspension-fired furnaces still dominates legacy installed capacity. CE marking enforcement under the EU Pressure Equipment Directive is hardening compliance thresholds for high-pressure retrofits.
- Watertube:Water circulates through tubes surrounded by combustion gases, enabling operation at supercritical pressures and temperatures. Advanced ultra-supercritical designs above 300 bar and 620°C are supplanting subcritical drum boilers in new-build projects.
- Firetube:Hot combustion gases pass through tubes immersed in a water shell, limiting pressure capability but simplifying maintenance. These concentrate in small industrial and commercial applications where operational simplicity outweighs efficiency.
Pulverized coal dominates installed base. Circulating fluidized bed is where expansion concentrates as fuel flexibility commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion funds and national coal phase-out schedules are redistributing boiler procurement across member states, with Nordic district heating networks and Central European biomass retrofits capturing the largest public financing allocations.
Germany
Hard coal phase-out by 2038 and earlier lignite closures in North Rhine-Westphalia are compressing service contract windows for legacy pulverized coal units. The Federal Network Agency enforces divergent regional timelines that fragment procurement standardization. Industrial clusters in the Ruhr and Lusatia regions are pivoting toward hydrogen-ready gas turbines and biomass CHP systems.
Poland
Utilities under EU ETS carbon pricing are accelerating retrofit schedules or mothballing subcritical coal units ahead of national deadlines. The Energy Regulatory Office manages concession processes for biomass conversion projects. Silesian power districts are specifying circulating fluidized bed retrofits to burn agricultural residues without full replacement capex.
Netherlands
Combined cycle gas turbine developers face frozen procurement decisions as Dutch TTF hub volatility compresses project IRRs. The Ministry of Economic Affairs and Climate Policy governs renewable energy transition subsidies. Rotterdam and Eindhoven industrial zones are prioritizing hydrogen-compatible heat recovery steam generators for future fuel flexibility.
Sweden
State-subsidized district heating programs sustain premium pricing for supercritical biomass units with thermal storage integration. The Swedish Energy Agency administers investment grants for CHP modernization. Stockholm and Gothenburg municipal utilities are bundling twenty-year maintenance contracts with initial equipment procurement.
Italy
Municipalities are tendering refuse-derived fuel boiler installations to meet landfill diversion targets under the EU Circular Economy Action Plan. The Ministry of Ecological Transition oversees waste-to-energy permitting. Northern industrial cities in Lombardy and Emilia-Romagna are replacing aging oil-fired backup units with biomass-compatible systems.
Europe Power Plant Boiler Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with energy sector divisions, creating a tiered structure where engineering-heavy OEMs with digital service capabilities command premium positioning alongside specialized boiler fabricators. Two strategic archetypes dominate: full-scope energy technology providers bundling hardware with long-term service agreements, and niche specialists focused on high-pressure component supply for retrofit projects. Competitive moves center on pre-certification of modular designs to accelerate CE marking compliance and vertical integration into creep-resistant alloy sourcing to bypass material qualification bottlenecks.
Among European-based industrial groups, Siemens AG and John Cockerill occupy positions exemplifying the full-scope archetype, while Andritz Group represents the specialized processing equipment tier. Siemens AG leverages digital twin capabilities across supercritical retrofit engagements. John Cockerill anchors its presence through heat recovery steam generator supply for combined cycle installations. Andritz Group sits within the biomass and waste-to-energy conversion specialist category, reflecting Austrian engineering concentration in circulating fluidized bed technology.
| Leading Market Players |
|---|
| BDR Thermea Group |
| Siemens AG |
| VIESSMANN |
| Babcock & Wilcox |
| Andritz Group |
| Bosch Limited |
| A. O. Smith |
| John Cockerill |
| Vaillant Group |
| Others |
Supply & Pricing Matrix
CE marking under the EU Pressure Equipment Directive gates both supplier qualification and price differentiation simultaneously, compressing vendor margins on high-pressure steam generators while concentrating premium pricing power with German and Austrian specialty mills holding extended fatigue-test certifications.
Pricing Analysis
Cost-plus contracts with steel indexation dominate utility procurement, linking final equipment pricing to German and Austrian alloy mill surcharges. Price differentiation separates CE-certified supercritical units from standard-pressure alternatives, with after-sales bundling widening spreads further. Pricing pressure stems from Dutch TTF hub volatility freezing combined cycle developer commitments. Municipal district heating operators show lowest price sensitivity due to EU cohesion fund coverage, while industrial captive power buyers negotiate hardest on unit economics.
Supply Chain Analysis
Strategic stockpiling of creep-resistant tubing prevails over just-in-time approaches given 18-month material qualification cycles under ECHA REACH. Supply concentrates in Germany, Austria, and Japan for nickel-based superalloys and specialty welded components. Raw material dependencies center on chromium-molybdenum steel, Inconel tubing, and high-purity weld consumables. Single-source vulnerability runs through German specialty mills holding exclusive CE marking approvals. Distribution runs through EPC contractors for utility retrofits and specialized boiler distributors for industrial replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as heat pumps and thermal storage systems displace boiler-based district heating in Nordic municipal planning. Incumbents must navigate this technology pivot while defending retrofit service contracts.
For Market Incumbents: Shield installed base relationships through twenty-year maintenance contract bundling that transfers operational risk from municipal utilities. Deepen backward integration into creep-resistant alloy sourcing to bypass German mill qualification bottlenecks. Accelerate digital twin deployment to sustain engineering margins on supercritical retrofit engagements as coal phase-out compresses project windows.
For New Entrants and Emerging Players: Anchor in Baltic district heating modernization where EU cohesion funds cover 40-60 percent of biomass CHP capital costs and established vendor presence remains thin. Target Estonian and Latvian cities replacing Soviet-era heat-only boilers. Pursue refuse-derived fuel specialization for Italian and Spanish municipal tenders under landfill diversion mandates.
For Investors and Strategic Acquirers: The EU Green Deal coal phase-out timeline reshapes the acquisition landscape, concentrating viable targets among CFB technology specialists with proven biomass conversion track records. Long-term viability favors OEMs with digital service platforms capable of recurring revenue beyond equipment sales. Watch carbon border adjustment mechanism developments as the signal for import cost shifts on boiler-grade steel.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Conversion Retrofit | Polish and Italian utilities specify CFB retrofits to avoid full replacement capex under EU ETS pressure. |
| Digital Twin Platform Deployment | Siemens AG leverages predictive maintenance capabilities to sustain margins on supercritical projects. |
| Modular HRSG Pre-Certification | John Cockerill accelerates site assembly through CE marking compliance for combined cycle plants. |
| Long-Term Service Agreement Bundling | Nordic operators transfer operational risk to vendors through twenty-year maintenance contracts. |
| Creep-Resistant Alloy Backward Integration | Specialty mills in Germany and Austria control material qualification timelines under ECHA REACH. |
Research Methodology
A standing panel of utility planning officers, EPC procurement directors, district heating network managers, and aftermarket service heads provided ongoing calibration across primary fieldwork and secondary validation. Bottom-up equipment shipment data triangulated against top-down utility capex disclosures from ENTSO-E and national regulatory filings. Secondary sources included EU ETS carbon price registries, CE marking notified body certifications, and national energy agency investment grant databases.
Consistency checks validated volume and value outputs against external benchmarks including IEA power plant investment trackers and Euroheat district heating statistics across the analysis window. Segmentation modeling spanned fuel source, pressure rating tier, application type, and regional regulatory framework. CAGRs derived from unit shipment trajectories and average selling price movements, with fuel switching velocity and coal phase-out schedule adherence as key forecast sensitivity inputs.
Material uncertainties — national coal phase-out timeline revisions, Dutch TTF hub volatility extremes, and carbon border adjustment mechanism implementation scope — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Green Deal benchmark enforcement and ECHA REACH compliance continuity. Revision becomes warranted when biomass feedstock cost inflation crosses thresholds that erode retrofit project IRRs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Commercial Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Boiler Control Solutions Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Global Marine Boilers Market
Boilers
Global Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Europe Residential Boiler Market
Boilers
US Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Power Plant Boiler Market
Boilers
Residential Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
Gas Fired Boilers Market
Boilers
Power Boiler Market