
 Biomass Boiler Market | 2026-2036
Biomass Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Biomass Boiler Market Analysis
Scandinavian capacity expansion is tilting European supply dynamics toward high-efficiency combustion systems. ANDRITZ leverages its Austrian engineering base to dominate large-scale industrial boiler installations across Northern Europe. Babcock & Wilcox sustains its position through extensive reference lists in utility-scale power generation retrofits. Hurst Boiler specializes in smaller-capacity stoker systems that anchor its presence in North American lumber and food processing facilities.
A biomass boiler converts solid organic fuel—typically wood pellets, agricultural residues, sawdust, or chips—into thermal energy through controlled combustion, gasification, or pyrolysis at temperatures exceeding 850°C, producing steam or hot water for industrial processes or space heating. The equipment serves primary purposes in district heating networks, manufacturing plants, and institutional facilities seeking to displace fossil-derived thermal loads. Combustion technology occupies the mature core of the installed base, while gasification systems represent the fastest-expanding segment as operators pursue higher electrical efficiencies and syngas co-production. Wood pellets command the largest product type volume, though agricultural residues gain traction where localized supply chains reduce feedstock procurement costs.
The EU Green Deal and F-Gas Regulation shape equipment efficiency mandates and emission thresholds for new installations across member states. EPA standards under the US Clean Air Act impose particulate and nitrogen oxide limits that filter market access for non-compliant boiler designs. India's BIS certification requirements and PLI scheme incentives for renewable thermal equipment create parallel compliance pathways for technology suppliers. Stakeholders must monitor feedstock price volatility and evolving carbon accounting rules to align capacity investments with long-term offtake contracts.
Market Dynamics
The EU Green Deal's coal phase-out mandates are redirecting utility capital toward biomass combustion retrofits, compressing project timelines as operators race to secure feedstock contracts before carbon border adjustments take full effect.
Growth Catalysts
- EU Green Deal mandates:Germany, Poland, and the Netherlands enforce coal phase-out deadlines that force utilities to accelerate biomass boiler procurement for baseload thermal generation.
- District heating expansion:Nordic municipalities in Sweden and Finland are expanding wood pellet procurement for municipal heat networks, creating predictable offtake volumes for equipment suppliers.
- Industrial decarbonization pressure:Chemical and paper plants in Germany's Rhine-Ruhr corridor seek steam system retrofits to displace natural gas and meet Scope 1 emission targets.
Market Restraints
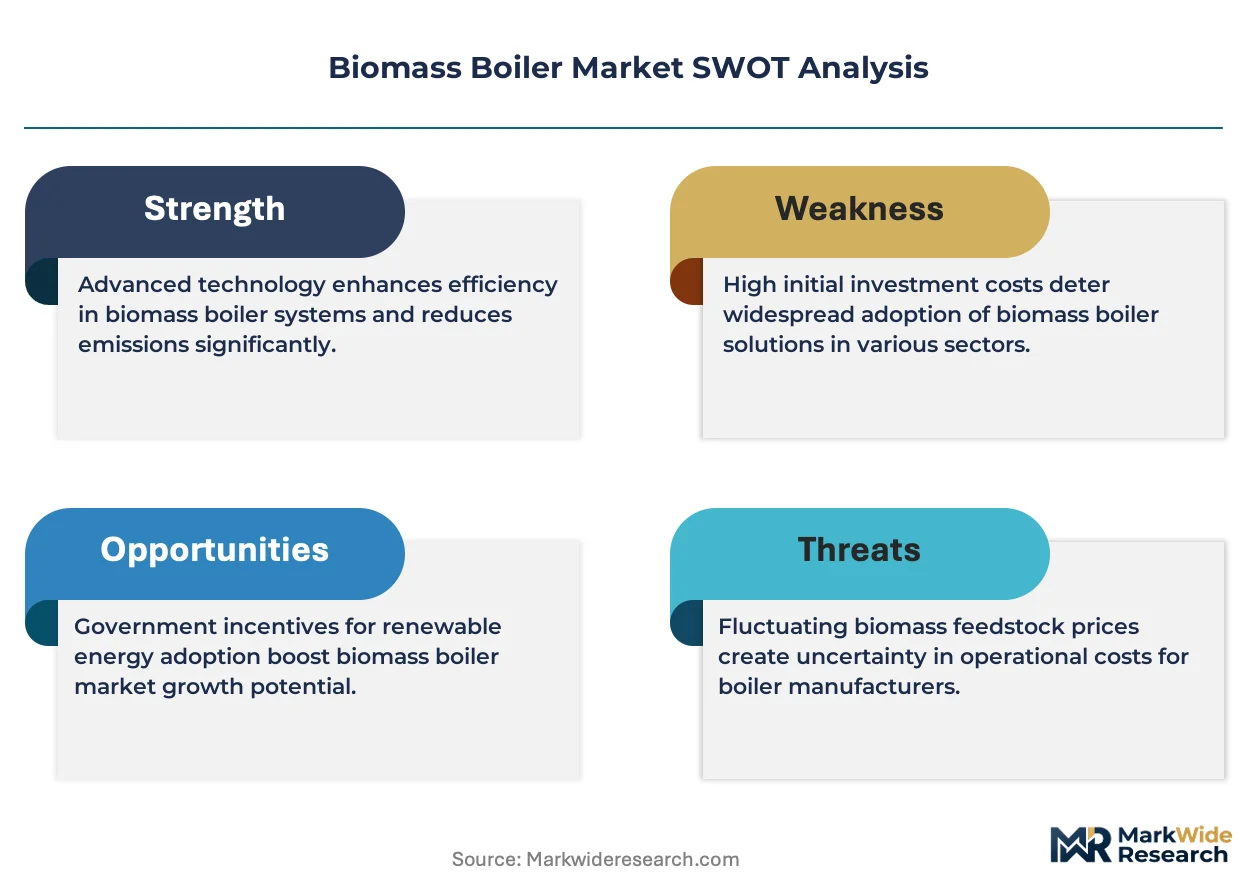
- Feedstock price volatility:Wood pellet and agricultural residue costs fluctuate with harvest yields and competing demand from pellet export markets, squeezing project IRRs.
- Supply concentration in combustion technology:Austrian and German engineering bases dominate large-scale system design, limiting buyer leverage and extending lead times for specialized components.
- EPA particulate limits:US Clean Air Act standards for nitrogen oxides and particulate matter filter out non-compliant boiler designs, raising engineering costs for market entry.
Strategic Opportunities
- Gasification technology convergence:Operators are combining biomass gasification with combined heat and power systems to capture higher electrical efficiencies and syngas co-production revenue streams.
- India's PLI scheme incentives:The Production Linked Incentive scheme for renewable thermal equipment creates subsidized demand pathways for suppliers willing to localize manufacturing.
- Agricultural residue feedstock localization:Supply chain development around straw, rice husks, and bagasse in South Asia and Southeast Asia reduces procurement costs for distributed industrial heat users.
Industry Challenges
- Combustion system integration complexity:Retrofitting biomass boilers into legacy steam infrastructure in older paper and chemical plants requires extensive civil works and control system upgrades.
- BIS certification timelines:India's Bureau of Indian Standards approval processes for pressure vessels and emission control systems extend commercialization cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomass Boiler Market |
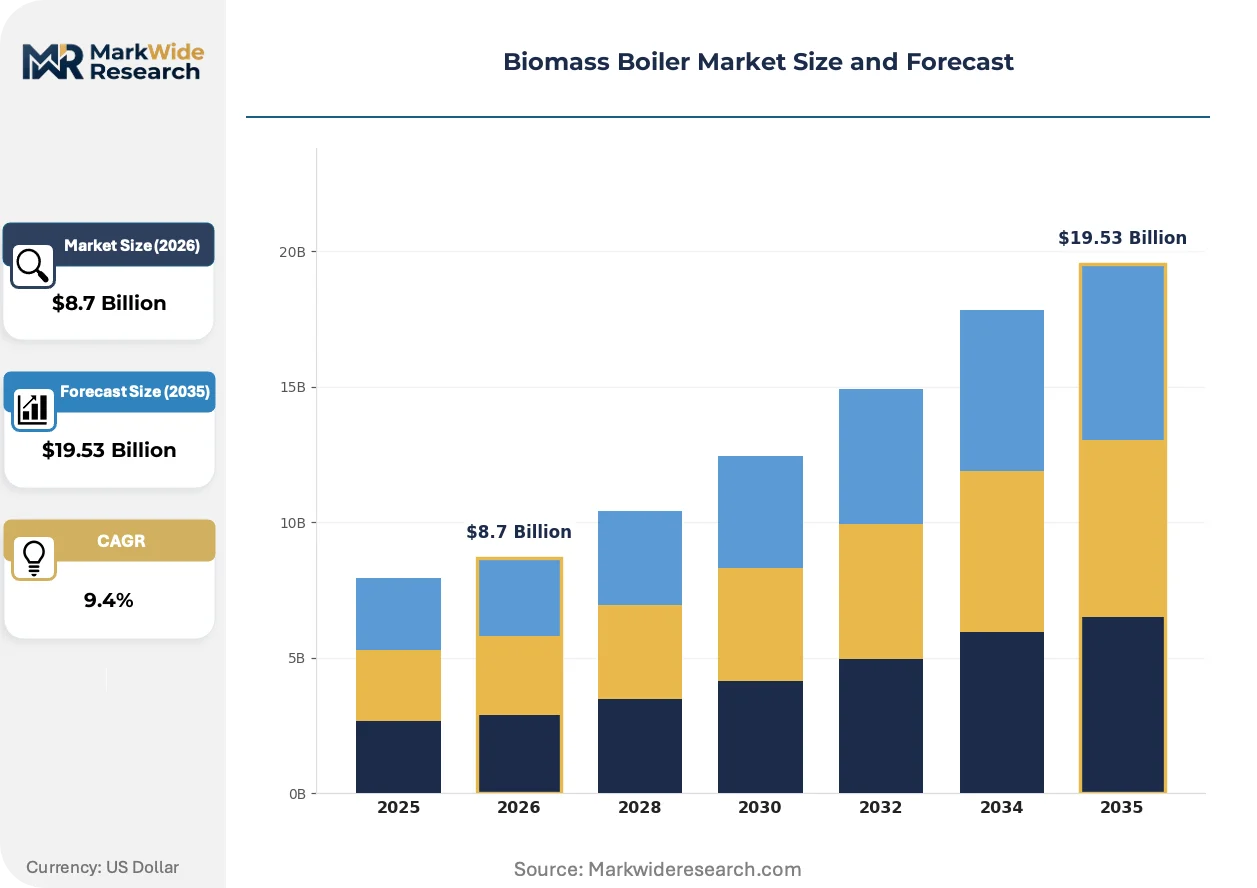
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Pellets, Agricultural Residues, Sawdust, Chips Technology: Combustion, Gasification, Anaerobic Digestion, Pyrolysis End User: Industrial, Residential, Commercial, Institutional Application: Heating, Power Generation, Combined Heat and Power, District Heating |
| Companies Covered | Hurst Boiler, Thermax, Babcock & Wilcox, ANDRITZ, Innasol, Amec Foster Wheeler, Dongfang Electric, Hargassner, Justsen Energiteknik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomass Boiler Market Emerging Trajectories
Equipment suppliers are converging on higher-efficiency combustion architectures as carbon accounting rules tighten and industrial buyers demand verifiable emission reductions in thermal supply contracts.
Fluidized bed combustion technology is collapsing the efficiency gap between biomass and natural gas boilers in large-scale industrial applications. Chemical plants in the Netherlands and Germany are adopting circulating fluidized bed systems at accelerating pace. This technology is collapsing project payback periods below five years for high-load operations.
The EU F-Gas Regulation is tightening emission thresholds for auxiliary refrigeration and heat pump components integrated with biomass thermal systems. Boiler manufacturers must redesign auxiliary circuits or source alternative working fluids to maintain CE marking eligibility. District heating operators in Denmark and Austria are prioritizing equipment packages that preempt anticipated 2027 F-Gas phase-down schedules.
Industrial buyers are consolidating procurement through long-term energy service contracts rather than capital purchase models. Equipment vendors in Northern Europe are responding by unbundling hardware supply from fuel procurement and O&M services. This pattern is most visible in Sweden's pulp and paper sector, where mill operators prefer heat-rate guarantees over asset ownership.
Biomass Boiler Market Segmentation
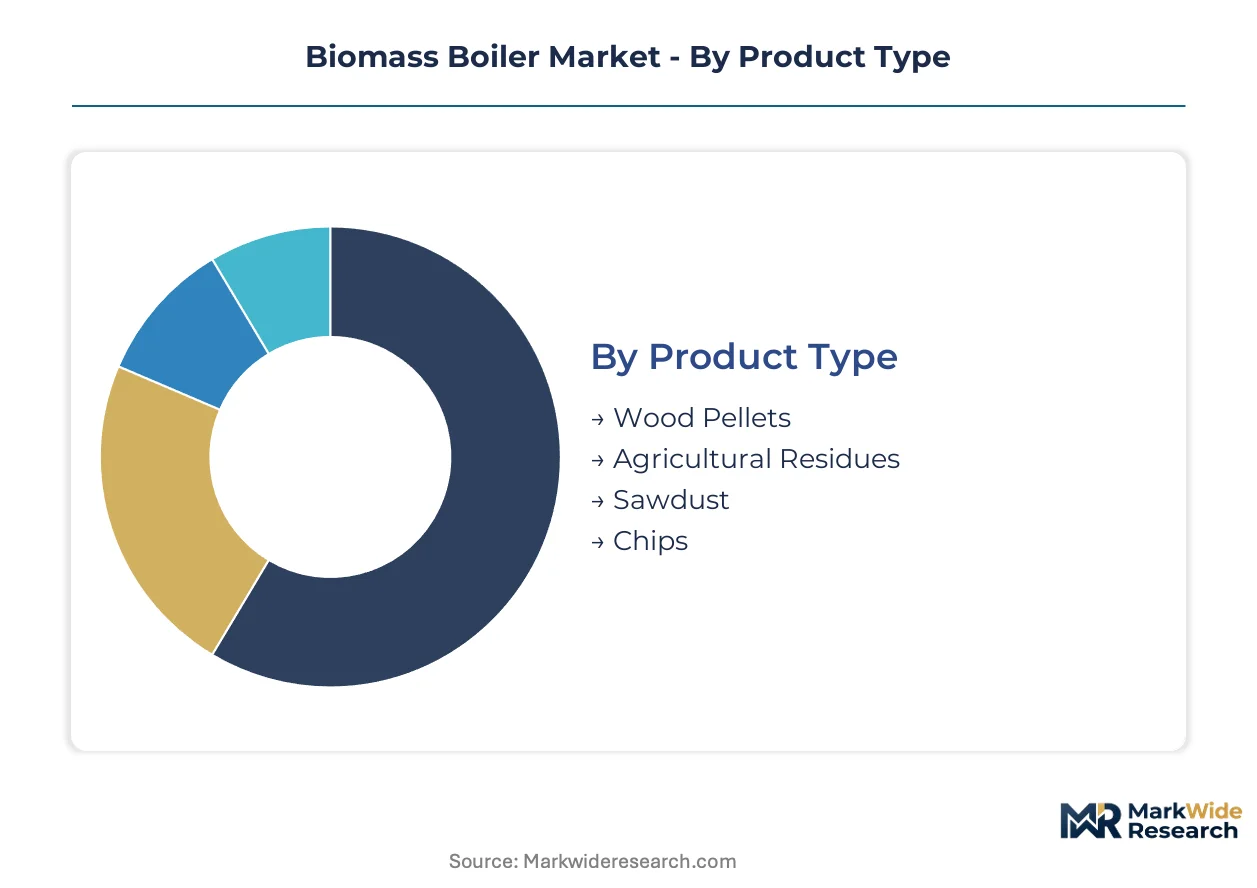
Segmentation in the biomass boiler market reveals how feedstock chemistry, combustion architecture, and thermal load profiles determine equipment specification and procurement patterns. Buyers select across these dimensions to align capital deployment with fuel availability, emission targets, and baseload requirements.
Product Type:
Cost tiers in feedstock procurement separate premium pellet supply from localized residue streams that trade at volume discounts but carry handling complexity.
- Wood Pellets:Densified biomass with standardized moisture content below 10% and calorific value exceeding 16.5 MJ/kg enables automated handling systems. District heating operators in Sweden and Finland prioritize pellet-fired systems for supply predictability and automated feed mechanisms that reduce labor intensity.
- Agricultural Residues:Straw, rice husks, and bagasse exhibit variable ash content and require staged combustion chambers with enhanced slag removal. Paper mills in Germany's Rhine-Ruhr corridor are retrofitting residue-capable stoker systems to exploit localized supply chains and reduce feedstock procurement costs.
- Sawdust:Fine particulate waste from sawmilling demands pneumatic injection systems and cyclone separators to manage dust explosion risks.
- Chips:Hog fuel from forest operations requires larger grate surfaces and longer residence times, limiting application to high-tonnage industrial boilers.
Wood pellets hold installed capacity. Agricultural residues are rotating up the share rankings.
Technology:
Application maturity separates proven combustion architectures from emerging thermochemical conversion platforms that capture higher electrical efficiencies.
- Combustion:Controlled oxidation of solid biomass at 850-1100°C through fixed-bed, moving-grate, or fluidized bed configurations produces steam or hot water. Chemical plants in the Netherlands adopt circulating fluidized bed systems for baseload steam decarbonization and sub-five-year project payback on high-load operations.
- Gasification:Partial oxidation at 700-900°C with restricted oxygen yields syngas for combined cycle power generation or chemical synthesis. Operators in Denmark are integrating biomass gasification with CHP systems to capture electrical efficiencies above 35% and syngas co-production revenue streams.
- Anaerobic Digestion:Microbial decomposition of wet organic feedstocks produces biogas for boiler firing or upgrading to biomethane.
- Pyrolysis:Thermal decomposition in oxygen-starved conditions yields bio-oil, char, and syngas fractions for separate valorization.
Combustion dominates current installations. Gasification is climbing the fastest as efficiency premiums justify capital intensity.
End User:
Customer type determines scale economics, with industrial buyers commanding customized engineering against standardized residential packages.
- Industrial:High-capacity installations exceeding 10 MW thermal output serve continuous process heat demands in pulp and paper, food processing, and chemicals. Germany's industrial Rhine-Ruhr corridor drives procurement of baseload steam systems as Scope 1 emission targets harden.
- Residential:Small-scale automated pellet boilers below 100 kW serve single-family heating loads, primarily in Austrian and German markets with established fuel supply infrastructure.
- Commercial:Hotels, hospitals, and retail complexes deploy mid-range systems with thermal storage to manage intermittent occupancy patterns.
- Institutional:Schools and municipal buildings favor standardized packages with remote monitoring capabilities to reduce facility management burden.
Industrial end users hold installed capacity. Commercial applications are gaining share fastest as ESCO models reduce capital barriers.
Application:
Volume concentration in heating applications is diversifying toward power generation and hybrid thermal-electric configurations.
- Heating:Direct thermal output for space conditioning or industrial process heat represents the foundational application with lowest capital cost per kW. Nordic municipalities in Sweden expand wood pellet procurement for municipal heat networks, creating predictable offtake volumes.
- Combined Heat and Power:Simultaneous electricity and thermal generation captures 80%+ system efficiency through backpressure steam turbines or Organic Rankine Cycle units. Dutch chemical plants prioritize CHP-integrated biomass systems to maximize carbon reduction per fuel unit consumed.
- Power Generation:Dedicated electricity-only configurations compete with other renewables on grid pricing and capacity market revenues.
- District Heating:Centralized thermal distribution networks aggregate multiple heat sources including biomass, waste heat, and seasonal storage.
Heating holds installed capacity. Combined heat and power is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian utilities favor district heating configurations while German industrial buyers prioritize process steam retrofits, revealing how geography shapes equipment specification and procurement timelines.
Germany
Chemical plants in the Rhine-Ruhr corridor drive demand for baseload steam decarbonization as Scope 1 emission targets harden. The national coal phase-out mandate accelerates utility procurement timelines for biomass combustion retrofits. Industrial clusters around Düsseldorf and Cologne are retrofitting legacy steam infrastructure with circulating fluidized bed systems.
Sweden
Municipal heat networks expand wood pellet procurement to displace residual fuel oil in district heating systems. The EU Green Deal's emission thresholds shape equipment efficiency mandates for new installations. Stockholm and Gothenburg anchor procurement volumes as operators seek automated feed mechanisms that reduce labor intensity.
United States
Lumber and food processing facilities in the Pacific Northwest and Southeast deploy smaller-capacity stoker systems for thermal loads. EPA standards under the Clean Air Act impose particulate and nitrogen oxide limits that filter market access for non-compliant designs. Paper mills in Georgia and Oregon are retrofitting biomass boilers into existing steam infrastructure.
India
Paper and textile plants in Maharashtra and Gujarat exploit localized agricultural residue supply chains to reduce feedstock procurement costs. The PLI scheme for renewable thermal equipment creates subsidized demand pathways for technology suppliers. Industrial zones around Ahmedabad and Pune are adopting residue-capable stoker systems with enhanced slag removal.
Netherlands
Chemical plants prioritize CHP-integrated biomass systems to maximize carbon reduction per fuel unit consumed. The EU F-Gas Regulation tightens emission thresholds for auxiliary components integrated with thermal systems. The Rotterdam port cluster is consolidating procurement through long-term energy service contracts rather than capital purchase models.
Biomass Boiler Market Vendor Landscape
Capability concentration sits with Austrian and German engineering specialists; scale advantage sits with diversified industrial conglomerates with cross-border installation footprints. The vendor base separates into three tiers: premium engineering houses with proprietary combustion architectures, mid-market fabricators serving regional industrial clusters, and commodity assemblers competing on delivery speed. Dominant competitive moves include backward integration into feedstock handling equipment and technology licensing partnerships for gasification system deployment.
Within the premium engineering tier, ANDRITZ and Babcock & Wilcox occupy positions anchored by extensive reference lists in utility-scale and industrial installations. Hurst Boiler represents the mid-market specialist archetype, with its naming convention suggesting North American origins and a focus on smaller-capacity system fabrication. Thermax exemplifies the diversified industrial conglomerate model, with its corporate structure indicating Indian base and exposure to PLI scheme incentive flows.
| Leading Market Players |
|---|
| Hurst Boiler |
| Thermax |
| Babcock & Wilcox |
| ANDRITZ |
| Innasol |
| Amec Foster Wheeler |
| Dongfang Electric |
| Hargassner |
| Justsen Energiteknik |
| Others |
Supply Flow & Price Mechanics
The Baltic Sea freight corridor's volatile bunker fuel costs compress margins for wood pellet shipments from Scandinavian ports to German industrial buyers, concentrating pricing power with Austrian and German engineering houses that control combustion system design while forcing smaller fabricators toward spot-market feedstock procurement.
Pricing Analysis
Long-term offtake contracts dominate procurement for district heating operators in Sweden and Finland, insulating buyers from spot-market volatility while premium-mid-economy pricing differentiation separates CE-marked fluidized bed systems from standard stoker configurations. Price differentiation hinges on emission control certification tiers and after-sales service bundling. Cost compression in the mid-market tier is intensifying because feedstock handling complexity demands customized engineering. Municipal buyers exhibit highest price sensitivity; chemical plants in the Rhine-Ruhr corridor prioritize performance guarantees over unit cost.
Supply Chain Analysis
EU dual-use export controls on advanced combustion monitoring systems limit technology flows to non-member manufacturing bases, concentrating high-efficiency system production in Austria, Germany, and Denmark. Component supply draws from Swedish steel for pressure vessels, Italian burner assemblies, and Finnish emission control modules. Single-source vulnerability sits with specialized grate casting foundries in Central Europe. Distribution runs through EPC contractors with utility relationships rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biomass boiler market functions as a service-attach opportunity where fuel procurement and O&M contracts expand faster than hardware sales as Swedish pulp mills and Dutch chemical plants shift toward heat-rate guarantees.
For Market Incumbents: Harden reference list leverage in utility-scale retrofits by embedding combustion system diagnostics into long-term service agreements. Backward integration into feedstock handling equipment manufacturing anchors margin capture against emerging Asian fabricators. Prioritize CE marking pre-emption for anticipated F-Gas Regulation phase-down schedules.
For New Entrants and Emerging Players: Establish a beachhead in India's residue-capable stoker segment where PLI scheme subsidies offset BIS certification timelines. Agricultural residue supply chain development in Maharashtra and Gujarat offers the most penetrable entry path. Lead with localized manufacturing partnerships rather than direct import competition.
For Investors and Strategic Acquirers: Engineering specialists with proprietary gasification architectures and district heating reference lists represent the highest-conviction acquisition archetype. Long-term viability across the analysis window rests on carbon accounting rule convergence rather than feedstock cost advantages. Watch for EU carbon border adjustment implementation pace as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Handling | Austrian engineering houses capture margin from pneumatic injection systems and automated stoker mechanisms. |
| Gasification Technology Licensing | Danish operators deploy CHP-integrated platforms to achieve electrical efficiencies above 35%. |
| Long-term Energy Service Contracting | Swedish pulp mills shift from asset ownership to heat-rate guarantees with unbundled O&M services. |
| CE Marking Pre-emption for F-Gas Compliance | German and Dutch boiler manufacturers redesign auxiliary circuits to maintain eligibility under tightening thresholds. |
| PLI Scheme Manufacturing Localization | Technology suppliers in India exploit subsidized demand pathways for renewable thermal equipment. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, EPC contractors, plant engineers at chemical and paper facilities, and aftermarket service heads, then refined against secondary validation from EIA biomass consumption data, IEA renewable heat reports, EU ETS emissions registries, and national coal phase-out policy documents. Bottom-up equipment shipment tallies and top-down energy demand projections were triangulated to anchor volume estimates.
Demand-supply balance modeling across the projection horizon segmented by feedstock type, combustion technology tier, end-user scale, and application mode, with CAGRs derived from regression against historical capacity additions and policy mandate timelines. Forecast inputs incorporated EU Green Deal implementation pace, carbon border adjustment sequencing, and feedstock harvest yield variability.
Sensitivities concentrate around carbon accounting rule revisions and feedstock price volatility assumptions. Forecasts reflect documented assumptions about policy continuity and technology cost curves. Material shifts in EU ETS pricing or agricultural residue export demand patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fire Tube Industrial Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Boiler Combustion Chamber Market
Boilers
District Heating Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Commercial Boiler Market
Boilers
Europe Combined Heat and Power Market
Boilers
Power Plant Boiler Market
Boilers
Superheater Tubes Market
Boilers
Europe Residential Boiler Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Industrial Biomass Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Field Erected Boiler Market
Boilers
Germany Combined Heat and Power Market