
 Utility Boiler Market | 2026-2036
Utility Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Boiler Market Analysis
Utility boiler procurement through engineering-procurement-construction consortia is tilting toward technology licensors with in-house fabrication depth. Mitsubishi Power leverages its ultra-supercritical turbine-generator integration to anchor large-scale independent power producer contracts across Southeast Asia. Babcock & Wilcox competes through modular circulating fluidized bed designs that reduce field construction labor for industrial cogeneration clients. Harbin Boiler Company sustains cost advantages via captive supply of heavy-pressure vessel forgings and domestic alloy sourcing.
A utility boiler is a large-scale closed vessel engineered to convert feedwater into high-pressure steam through combustion of fossil or renewable fuels, typically operating at pressures exceeding 150 bar and temperatures above 540°C for thermal power generation. Its primary industrial purpose is driving steam turbine generators for electricity production or supplying process heat to refineries, chemical complexes, and district heating networks. Natural gas-fired units lead capacity additions in markets with pipeline infrastructure maturity, while ultra-supercritical technology captures margin pools where efficiency premiums justify alloy metallurgy costs. Biomass co-firing retrofits represent the fastest-growing technology segment as existing coal plants seek fuel diversification without greenfield capital.
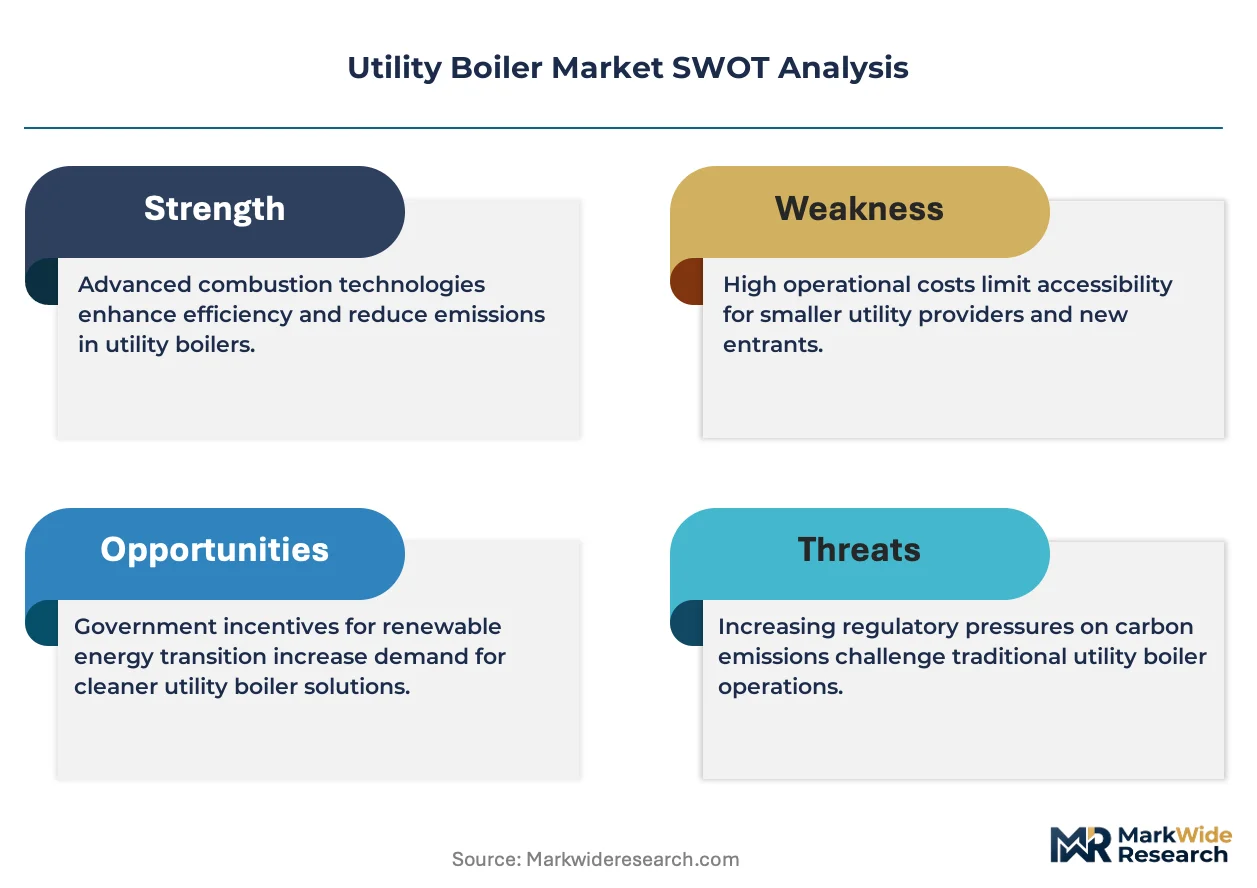
EPA emission standards under the Clean Air Act and EU F-Gas Regulation constrain new coal boiler deployments while accelerating supercritical retrofits in legacy fleets. China's MEE enforces ultra-low emission limits on thermal power stacks, forcing operators toward higher-efficiency combustion systems or retirement. India's CEA mandates minimum thermal efficiency thresholds that favor supercritical and ultra-supercritical new builds over subcritical units. Stakeholders must monitor carbon border adjustment mechanisms and emerging hydrogen co-firing certification standards to preserve asset viability across regulatory jurisdictions.
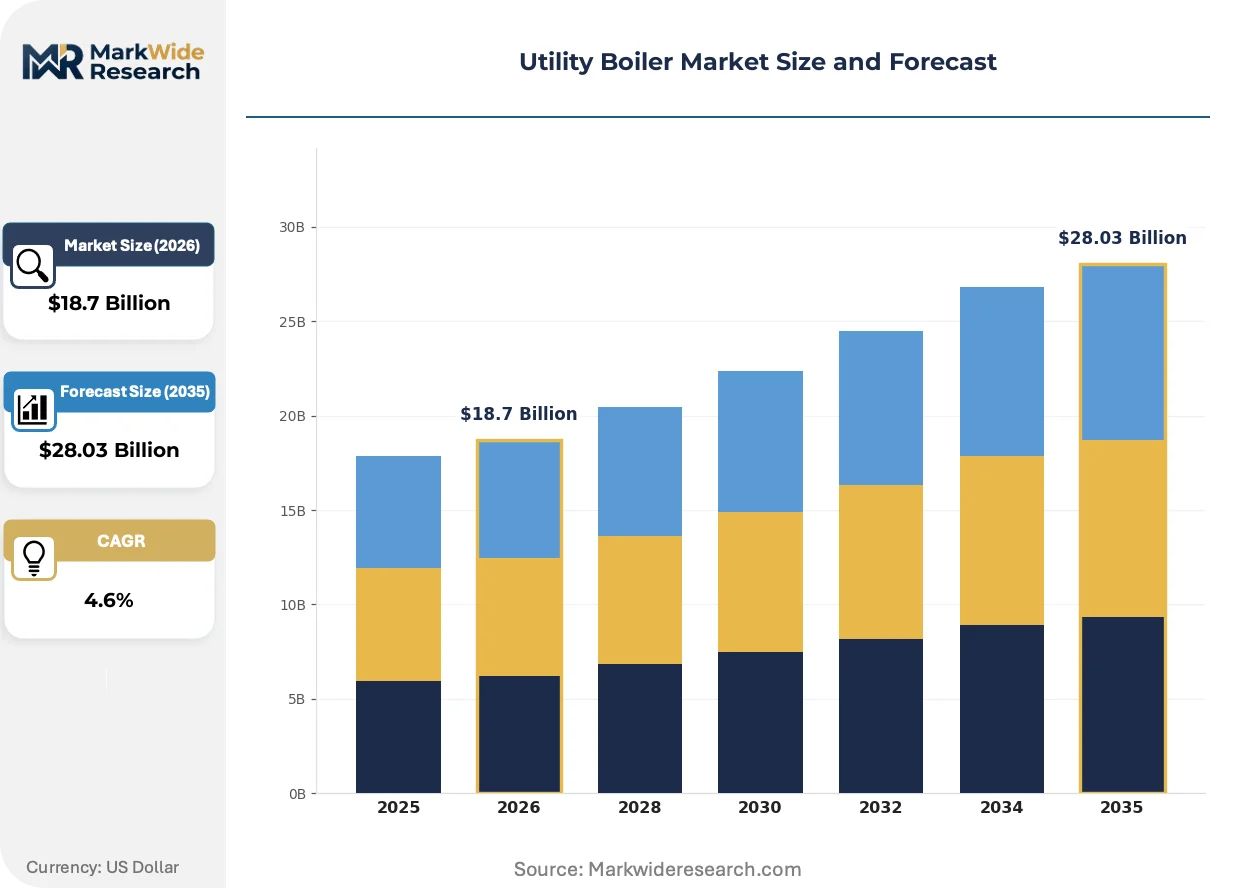
Market Dynamics
Ultra-supercritical steam parameter adoption is compressing subcritical unit economics while tightening alloy supply chains for high-pressure vessel fabrication. Southeast Asian power developers now specify 600°C+ steam conditions as baseline tender requirements, forcing technology licensors to secure nickel-superalloy forging capacity years ahead of delivery.
Growth Catalysts
- Indonesia's 35,000 MW Fast Track Program:State utility PLN continues awarding coal-fired independent power producer contracts with supercritical technology mandates, sustaining order pipelines for domestic and foreign boiler fabricators.
- EU F-Gas Regulation Phase-Down:Refrigerant restrictions on auxiliary cooling systems are accelerating dry-cooling retrofits that require higher-efficiency steam cycles to maintain net output.
- Biomass Co-Firing Retrofits:European coal plant operators under EU ETS carbon price pressure are installing biomass injection systems without greenfield capital, extending asset life cycles.
Market Restraints
- Nickel Superalloy Supply Concentration:Forged pressure vessel components for 620°C steam conditions depend on Japanese and German specialty steel mills with 18-24 month order backlogs.
- China MEE Ultra-Low Emission Enforcement:Retrofit capital requirements for SOx, NOx, and particulate controls are forcing early retirement of subcritical units under 300 MW, eroding secondary market refurbishment demand.
- Renewable Baseload Substitution:Grid-scale battery storage and pumped hydro projects in Vietnam and the Philippines are capturing peak shaving contracts previously served by cycling coal units.
Strategic Opportunities
- India's National Clean Air Programme:State pollution control board enforcement in the Indo-Gangetic Plain is creating retrofit demand for flue gas desulfurization and advanced combustion controls on legacy 500 MW units.
- Hydrogen Co-Firing Certification:Emerging ISO standards for hydrogen injection rates in coal and gas boilers are opening engineering service contracts for burner modification and flame stability modeling.
- Digital Twin Deployment:Predictive maintenance platforms integrating real-time creep monitoring with outage scheduling are penetrating the Middle East independent water and power producer segment.
Industry Challenges
- Welding Inspector Certification Bottlenecks:ASME Section IX and EN ISO 9606 qualification timelines for narrow-gap welding of P92 steel are extending field construction schedules by 4-6 months.
- Legacy Control System Integration:DCS migration from proprietary 1990s-era platforms to open-architecture IEC 61850 standards requires custom protocol gateways that inflate commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Boiler Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Coal, Natural Gas, Oil, Biomass Technology: Conventional, Circulating Fluidized Bed, Supercritical, Ultra Supercritical End User: Power Plants, Industrial Facilities, District Heating, Others Application: Electricity Generation, Process Heat, Combined Heat and Power, Steam Production |
| Companies Covered | Sanrenxing, Cleaver-Brooks, Babcock & Wilcox, Viessmann, Fulton Companies, Mitsubishi Power, Wuxi Huaguang Boiler, Bosch Thermotechnology, Harbin Boiler Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Boiler Market Emerging Trajectories
Boiler technology trajectories are converging on higher thermal efficiency targets while digital instrumentation penetrates remaining analog control architectures. Equipment suppliers are repositioning around lifecycle service contracts rather than turnkey hardware margins.
Advanced ultra-supercritical (A-USC) boiler designs operating at 700°C and 350 bar are hybridizing nickel-based superalloy metallurgy with additive-manufactured cooling channels in high-temperature headers. Japanese power developers under METI efficiency mandates are piloting these units at 600 MW scale. The technology is hybridizing competitive positioning around alloy supply chain capture rather than pure engineering licensure.
EPA's revised Mercury and Air Toxics Standards are tightening particulate matter emission limits for existing coal-fired fleets, forcing activated carbon injection upgrades and fabric filter replacements. US independent power producers with merchant exposure face retrofit capital decisions against shrinking capacity factor forecasts. The regulation is compressing project finance timelines as lenders impose technology risk premiums on subcritical collateral.
Engineering-procurement-construction consortia are unbundling long-term aftermarket service contracts from initial equipment supply, with Middle Eastern independent water and power producers demanding 15-year availability guarantees. Technology licensors are responding with remote monitoring centers and predictive parts replacement programs. This restructuring is most visible in Saudi Arabia's National Water Company privatization wave, where O&M cost escalation clauses now dominate tender evaluation criteria.
Utility Boiler Market Segmentation
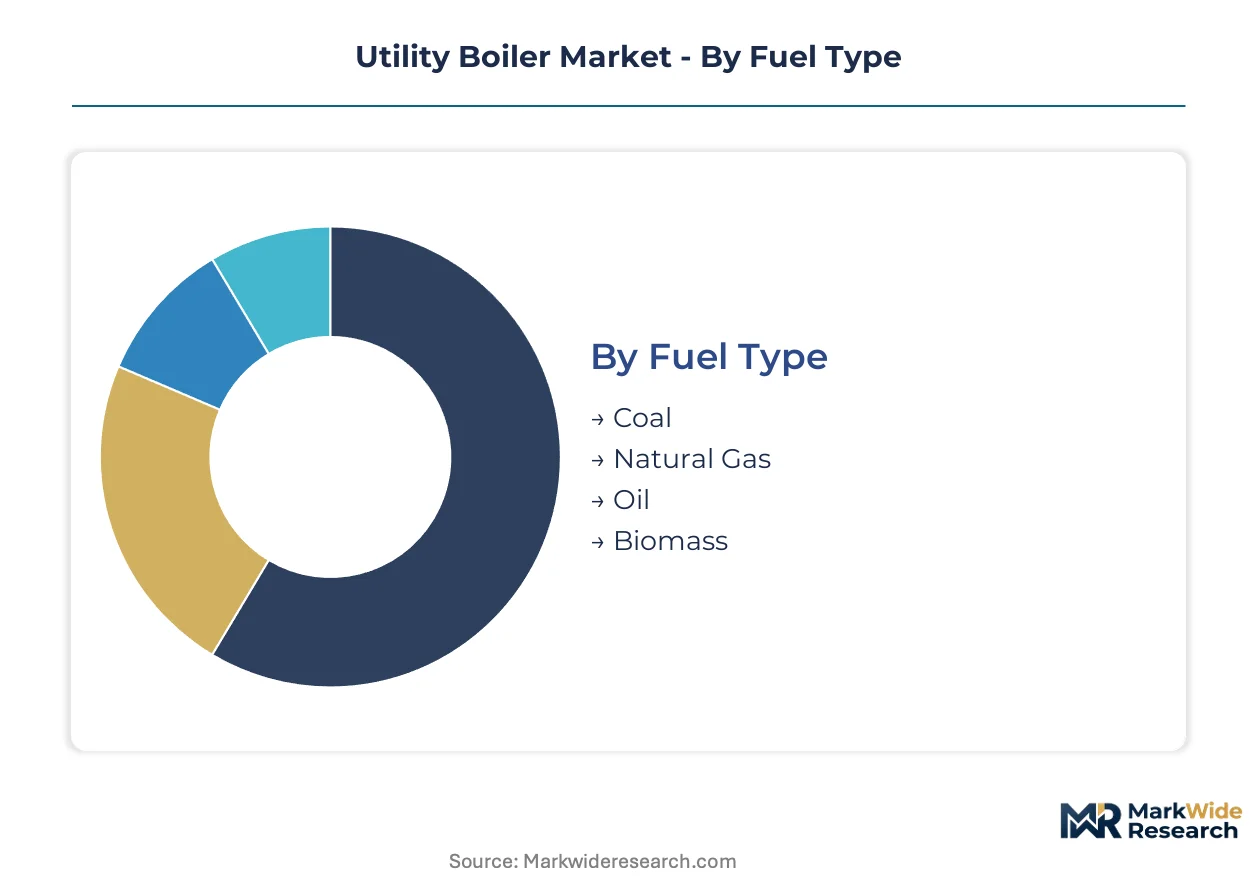
Utility boiler procurement decisions cascade across fuel choices, steam cycle technologies, and end-use configurations that determine capital intensity and operating economics. Segment boundaries are blurring as biomass co-firing retrofits and hydrogen-ready designs create hybrid categories.
Fuel Type:
Coal-to-gas switching and renewable co-firing mandates are fragmenting traditional fuel procurement patterns across power generation portfolios.
- Coal:Subcritical units face accelerated retirement under tightened emission limits, while supercritical and ultra-supercritical designs retain viability in Southeast Asian markets where domestic reserves anchor energy security strategies. Indonesian and Vietnamese independent power producers continue specifying coal-fired baseload capacity despite net-zero commitments.
- Natural Gas:Combined-cycle configurations dominate capacity additions in markets with mature pipeline infrastructure, offering lower capital costs and faster construction timelines than solid-fuel alternatives. Gas-fired units capture peak shaving and mid-merit dispatch roles as renewable penetration rises.
- Oil:Residual fuel oil and distillate units persist in islanded grids and emergency backup applications where fuel flexibility outweighs thermal efficiency premiums.
- Biomass:Agricultural residue and wood pellet co-firing retrofits extend coal plant asset life under carbon pricing pressure, with European operators leading deployment.
The dominant share belongs to coal, while biomass is closing the gap fastest.
Technology:
Steam parameter thresholds determine metallurgical requirements, fabrication complexity, and long-term efficiency premiums that shape procurement evaluation criteria.
- Conventional:Subcritical drum boilers operating below 221 bar and 374°C retain limited greenfield appeal but sustain aftermarket demand in emerging markets with cost-constrained procurement. Legacy fleet operators in India and Indonesia defer replacement decisions against residual book value.
- Circulating Fluidized Bed:Low-grade fuel flexibility and in-situ sulfur capture position CFB designs for industrial cogeneration and high-ash coal applications. Modular shop-fabricated configurations reduce field construction labor exposure for remote site deployments.
- Supercritical:Once-through boilers operating above critical pressure without steam-water separation drums achieve 40-42% net thermal efficiency, meeting baseline mandates in India's CEA efficiency thresholds.
- Ultra Supercritical:Steam conditions exceeding 593°C and 310 bar push nickel-superalloy metallurgy limits, capturing margin pools where carbon pricing justifies alloy cost premiums. Japanese METI efficiency mandates are accelerating 600°C+ tender specifications.
Ultra supercritical designs command premium positioning, though circulating fluidized bed is expanding most quickly in captive power applications.
End User:
Customer archetypes diverge around availability requirements, fuel procurement autonomy, and regulatory compliance burdens that dictate technology selection.
- Power Plants:Centralized generation assets face the most stringent efficiency and emission mandates, driving supercritical adoption and flue gas treatment retrofits.
- Industrial Facilities:Refineries, petrochemical complexes, and pulp mills prioritize steam reliability and fuel flexibility over peak efficiency, sustaining CFB and multi-fuel boiler demand.
- District Heating:Combined heat and power configurations in Nordic and Eastern European markets favor backpressure turbines and extraction-condensing cycles.
- Others:Military bases, remote mining operations, and islanded microgrids specify self-contained boiler-turbine packages with fuel oil backup capability.
Power plants absorb the majority of ultra-supercritical capacity additions, while industrial facilities are diversifying fastest into biomass and hydrogen-ready configurations.
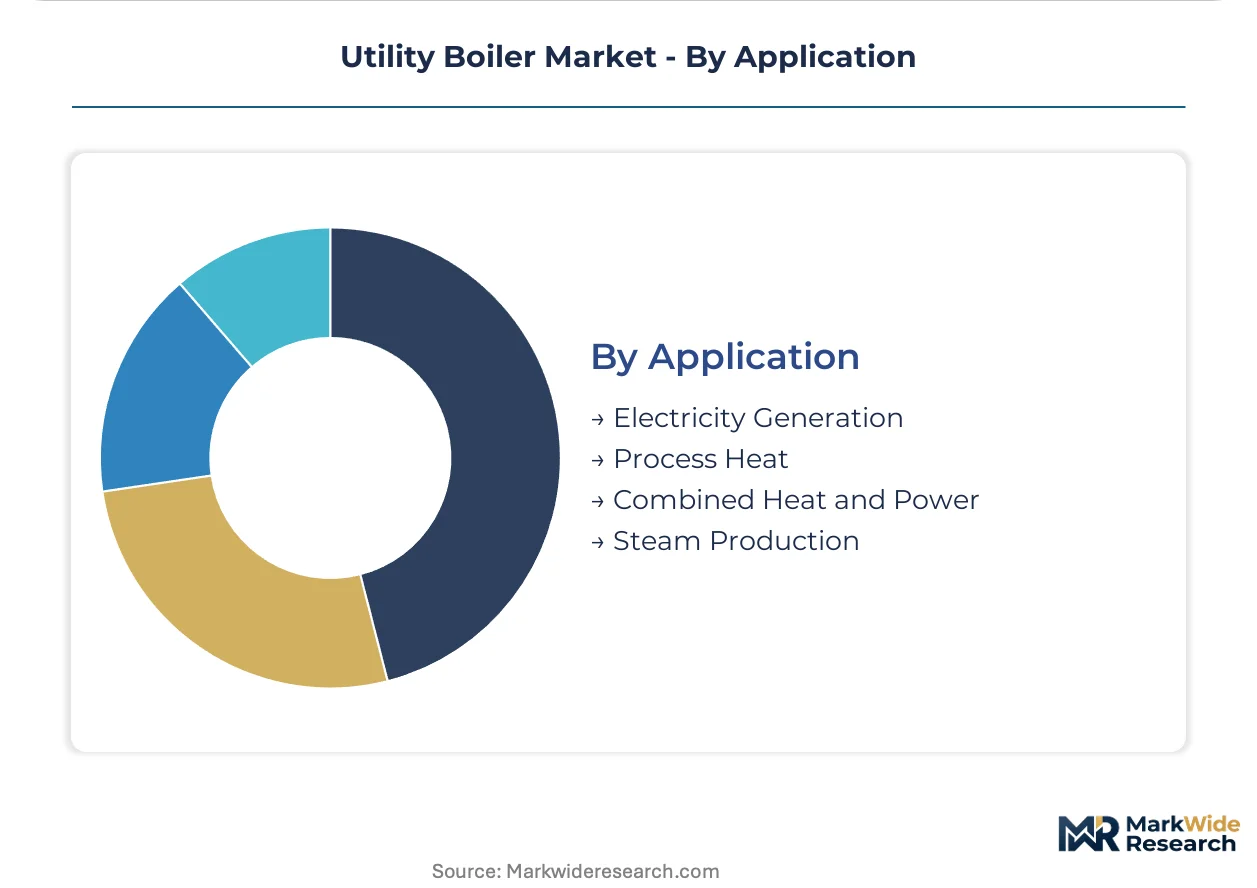
Application:
Output specifications determine steam pressure, temperature, and purity requirements that cascade into metallurgy and control system design choices.
- Electricity Generation:Condensing steam turbines for grid-connected power demand the highest steam parameters and reheat stages to maximize thermal efficiency.
- Process Heat:Saturated steam supply to refineries and chemical plants prioritizes reliability and turndown ratio over superheat temperature.
- Combined Heat and Power:Cogeneration configurations extract maximum fuel utilization through sequential electricity and thermal output, common in paper mills and district heating networks.
- Steam Production:Dedicated industrial steam supply without power extraction serves sterilization, humidification, and reaction vessel heating in pharmaceutical and food processing facilities.
Electricity generation retains the largest installed base, though combined heat and power is gaining share fastest under efficiency-focused policy incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Java-Bali grid interconnection underwrites Indonesia's central role in Southeast Asian capacity expansion, while Vietnam's North-South 500kV transmission backbone enables northern coal clusters to supply southern demand centers.
Indonesia
PLN's 35,000 MW Fast Track Program sustains tender flows for supercritical units across Java and Sumatra. The Ministry of Energy and Mineral Resources mandates efficiency thresholds that disqualify subcritical designs from state-backed independent power producer contracts. Surabaya's manufacturing corridor hosts domestic fabricators supplying pressure vessel components to Batang and Cilacap project sites.
Vietnam
EVN's capacity additions in Quang Ninh and Thai Binh provinces target baseload gaps as hydropower output fluctuates seasonally. The Prime Minister's Decision 28/2014/QD-TTg imposes emission standards that accelerate flue gas desulfurization retrofits on legacy 300 MW units. The Vinh Tan power center anchors ultra-supercritical deployment with 600°C steam parameters specified in recent international competitive bidding rounds.
China
Provincial grid companies in Shandong and Inner Mongolia retire subcritical fleets under MEE ultra-low emission enforcement. The National Energy Administration's 14th Five-Year Plan caps new coal builds but incentivizes A-USC pilots at 700°C steam conditions. Shanghai Electric and Harbin equipment clusters supply domestic projects while capturing Southeast Asian export orders.
India
NTPC and state gencos tender supercritical units for Uttar Pradesh and Madhya Pradesh capacity expansion. CEA technical standards mandate 40% minimum thermal efficiency that excludes drum boiler designs from new build eligibility. The Mundra and Krishnapatnam ultra-mega power project zones concentrate 800 MW unit deployments with indigenous boiler-turbine-generator packaging.
Japan
Utilities under METI efficiency mandates pilot 600°C+ ultra-supercritical retrofits at existing thermal sites. The Feed-in Tariff scheme for biomass co-firing extends operational licenses for legacy coal units in Chubu and Kansai regions. Yokohama's heavy industrial zone hosts specialist alloy forging capacity for high-temperature header components.
Utility Boiler Market Vendor Landscape
On the supply side, the industry is consolidating around technology licensors with captive metallurgy capabilities and fabrication depth. Boiler procurement through engineering-procurement-construction consortia favors vendors offering integrated turbine-generator packages. Two strategic archetypes dominate: integrated power plant solution providers and modular industrial boiler specialists. Capacity expansion in Southeast Asian markets and strategic partnerships for aftermarket service contracts represent the prevailing competitive moves.
Within the integrated solution tier, Mitsubishi Power and Babcock & Wilcox exemplify contrasting positioning strategies. Mitsubishi Power anchors large-scale independent power producer contracts through ultra-supercritical turbine-generator integration. Babcock & Wilcox occupies a position emphasizing modular circulating fluidized bed configurations. Harbin Boiler Company represents the state-affiliated fabricator archetype with backward integration into heavy-pressure vessel supply chains. These three entities collectively illustrate the geographic and technological segmentation governing competitive dynamics.
| Leading Market Players |
|---|
| Sanrenxing |
| Cleaver-Brooks |
| Babcock & Wilcox |
| Viessmann |
| Fulton Companies |
| Mitsubishi Power |
| Wuxi Huaguang Boiler |
| Bosch Thermotechnology |
| Harbin Boiler Company |
| Others |
Supply Flow & Price Mechanics
Surabaya's manufacturing corridor concentrates domestic pressure vessel fabrication capacity, translating upstream nickel-superalloy scarcity into tiered quotation premiums for Southeast Asian independent power producers. Contract bundling of turbine-generator packages amplifies pricing power for integrated licensors against modular competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs utility boiler procurement, with ultra-supercritical designs commanding alloy-grade premiums and subcritical units competing on capital cost alone. Price differentiation hinges on ASME certification tier and captive forging capability, with Japanese and German specialty mills extracting scarcity rents for 620°C steam conditions. Cost compression in the standard tier is intensifying as Chinese fabricators expand Southeast Asian export quotas. State utilities in Indonesia and Vietnam exhibit highest price sensitivity, while Middle Eastern independent water and power producers prioritize availability guarantees over upfront capital.
Supply Chain Analysis
Contract manufacturing concentration rests with Harbin Boiler Company, Mitsubishi Power, and Babcock & Wilcox, each anchoring distinct regional procurement channels. Geographic supply concentration centers on China, Japan, and Germany for high-pressure vessel forgings, with Indonesia and India hosting downstream assembly clusters. Raw material dependencies draw from nickel-superalloy feedstock, creep-resistant steel plate, and specialized welding consumables. Single-source vulnerability around Japanese and German specialty mills for A-USC components exposes project timelines to 18-24 month order backlogs. Distribution runs through engineering-procurement-construction consortia that unbundle long-term service contracts from initial equipment supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as ultra-supercritical technology penetration accelerates under tightened thermal efficiency mandates across Southeast Asian baseload procurement.
For Market Incumbents: Pre-empt alloy supply chain capture through offtake agreements with Japanese and German specialty mills before competitor tendering locks capacity. Secure captive forging capabilities or joint venture structures in Surabaya and Harbin to defend margin position against Chinese cost aggression. Reinforce digital twin service bundling to anchor 15-year availability guarantees demanded by Middle Eastern independent water and power producers.
For New Entrants and Emerging Players: Build out biomass co-firing retrofit specialization targeting European coal operators under EU ETS carbon price pressure, where incumbent boiler OEMs underinvest in combustion modification engineering. Target India's National Clean Air Programme enforcement zones for flue gas desulfurization aftermarket contracts on legacy 500 MW units. Lead with hydrogen co-firing certification advisory services as ISO standards emerge, avoiding head-to-head tender competition against integrated turbine-generator packages.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors alloy supply chain specialists over pure engineering licensure, as 700°C A-USC pilots shift competitive advantage toward metallurgy control. Long-term viability over the next decade rests on nickel-superalloy forging capacity and regional fabrication depth rather than brand equity. Acquisition target archetype: captive forging assets with Southeast Asian or Middle Eastern geographic adjacency. The signal to watch is nickel price volatility and Japanese mill order backlog duration as inflection indicators for project finance risk premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Alloy Supply Chain Capture | Secures nickel-superalloy forging capacity ahead of Southeast Asian ultra-supercritical tender waves. |
| Biomass Co-Firing Retrofit | Extends European coal plant asset life under EU ETS carbon pricing without greenfield capital deployment. |
| Digital Twin Deployment | Enables 15-year availability guarantees for Middle Eastern independent water and power producer contracts. |
| Hydrogen Co-Firing Certification | Positions engineering services for emerging ISO standards on hydrogen injection rates in coal and gas boilers. |
| Regional Fabrication Expansion | Reduces field construction labor exposure and tariff vulnerability for Indonesian and Vietnamese project sites. |
Methodological Framework
A standing panel of utility planning officers, independent power producer project developers, EPC contractors, and aftermarket service heads provided ongoing calibration across the study period. Primary interviews with boiler procurement managers at PLN, EVN, and NTPC combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition tracking and top-down regulatory impact assessment were triangulated against alloy supply chain lead times and tender pipeline monitoring.
Scenario-bracketing framed demand projections across the analysis window, modeling fuel type, steam cycle technology, end-user configuration, and regional regulatory framework as core segmentation dimensions. CAGRs were derived from installed base turnover rates and efficiency mandate implementation timelines. Forecast inputs incorporated nickel-superalloy order backlog duration, welding inspector certification bottlenecks, and grid-scale battery storage substitution rates for cycling coal units.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-affiliated Chinese fabricators or unexpected EU carbon border adjustment mechanism acceleration would shift outcomes. Forecasts reflect assumptions around MEE ultra-low emission enforcement continuity, PLN Fast Track Program tender flow stability, and nickel price mean reversion. Quarterly review of specialty mill order backlogs, Southeast Asian IPP financial closure rates, and hydrogen co-firing pilot announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Europe Combined Heat and Power Market
Boilers
Global Package Boilers Market
Boilers
Power Plant Boiler Market
Boilers
Gas Condensing Boiler Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Steam Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Global Marine Boilers Market
Boilers
Boiler System Market
Boilers
Watertube Boilers Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Power Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Waste Heat Boiler Market
Boilers
Global Boiler Market