
 Field Erected Boiler Market | 2026-2036
Field Erected Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Field Erected Boiler Market Foresight
Ultra-supercritical steam conditions is unwinding legacy subcritical specifications across the field erected boiler landscape. Alfa Laval Corporate AB leverages its heat transfer engineering heritage to compete in high-efficiency heat recovery installations. Indeck Power Equipment Co anchors its position through specialized rental and permanent boiler solutions for industrial clients. Ware Inc differentiates via comprehensive service capabilities and geographic coverage across North American manufacturing corridors.
A field erected boiler is a large-capacity steam generator assembled at the final installation site rather than factory-built, typically producing steam pressures exceeding 150 psi and temperatures above 1,000°F for industrial process heat or power generation. These units employ welded membrane wall construction, drum internals, and customized burner configurations to match specific fuel profiles and emission constraints. Water-tube designs dominate heavy industrial applications where high pressure and rapid steam response are essential, while heat recovery configurations capture waste heat from gas turbines and process streams. Modular field erected approaches are gaining traction for reducing on-site construction duration and labor risk in remote locations.
ASME Boiler and Pressure Vessel Code compliance, EPA Maximum Achievable Control Technology standards, and state-level renewable portfolio obligations collectively determine product specifications and project economics for field erected boiler deployments. The National Board of Boiler and Pressure Vessel Inspectors registration requirements create barriers for non-certified manufacturers seeking utility-scale contracts. Stakeholders must track evolving carbon border adjustment mechanisms and hydrogen-ready burner technology maturation to align capital planning with decarbonization pathways.
Market Dynamics
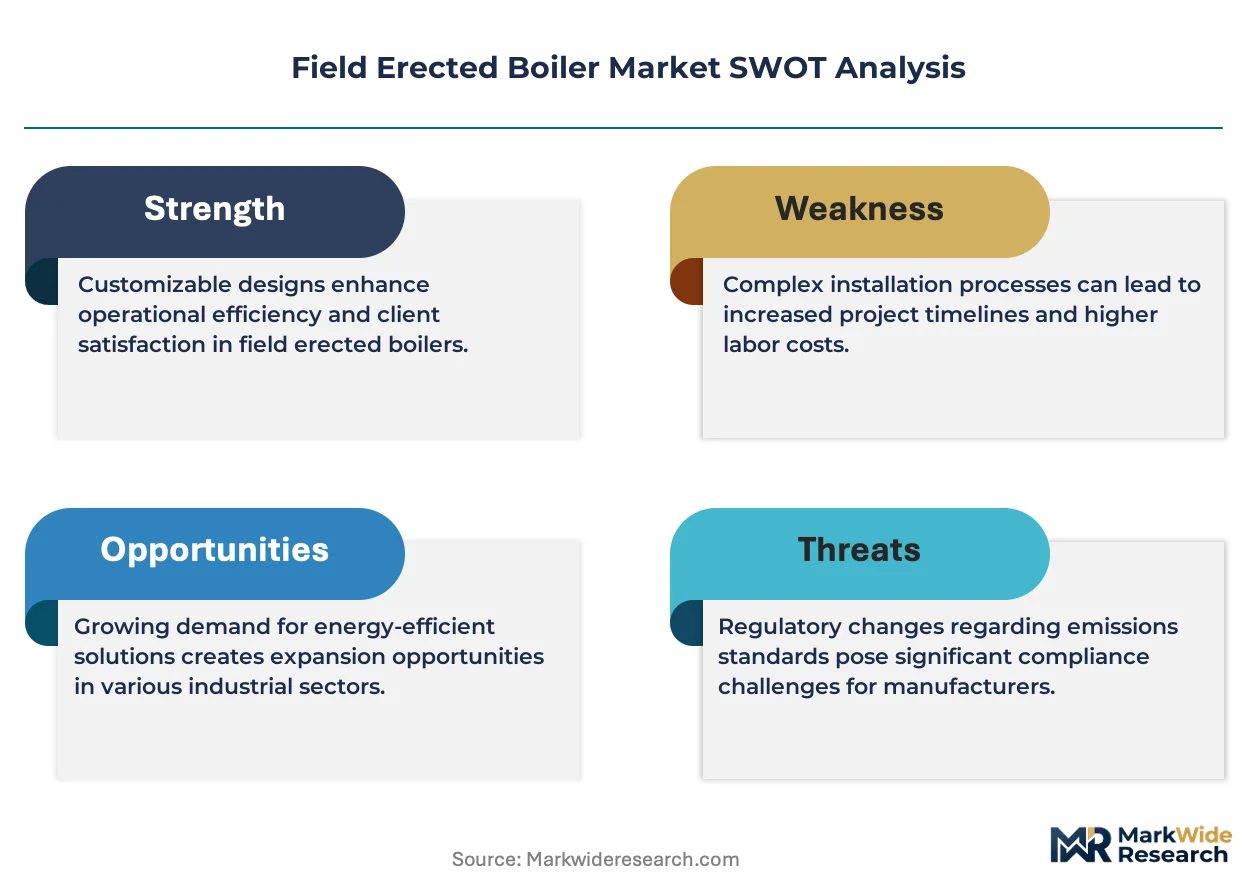
Ultra-supercritical steam technology is decomposing legacy subcritical specifications across utility procurement cycles, forcing boiler fabricators to reengineer membrane wall designs and burner architectures for 1,100°F-plus operating conditions.
Growth Catalysts
- Coal-to-gas conversion mandates:Indonesia's Ministry of Energy and Mineral Resources directives accelerate retirement of aging subcritical units across Java-Bali grid infrastructure, requiring custom field erected replacements.
- Industrial zone expansion:Vietnam's processing manufacturing clusters in Binh Duong and Dong Nai provinces drive demand for high-pressure process steam systems in textiles and food processing.
- EPA Maximum Achievable Control Technology:Stringent NOx emission ceilings force existing power generators to upgrade combustion systems and heat recovery configurations.
Market Restraints
- Specialized alloy supply concentration:Superalloy procurement for ultra-supercritical pressure parts depends on concentrated European and Japanese specialty steel producers.
- ASME certification timeline:National Board of Boiler and Pressure Vessel Inspectors registration requirements extend project qualification cycles by 8-14 months for non-certified entrants.
- Modular prefabrication substitution:Factory-built modular boiler systems capture mid-scale industrial applications below 200 MW thermal output.
Strategic Opportunities
- Hydrogen-ready burner development:Dual-fuel combustion architectures position existing fabricators for EU Green Deal hydrogen blending mandates in power generation.
- Philippines geothermal expansion:Leyte and Mindanao island projects require custom heat recovery steam generators for combined-cycle geothermal hybrid plants.
- Performance-based service contracts:Output-guaranteed maintenance agreements transform aftermarket revenue from parts replacement to availability-based fees.
Industry Challenges
- Welding specialist scarcity:Certified pressure vessel welders for membrane wall construction face 18-24 month training pipelines amid competing infrastructure demands.
- Legacy control system integration:Digital burner management retrofits onto 1990s-era distributed control architectures create commissioning complexity and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Erected Boiler Market |
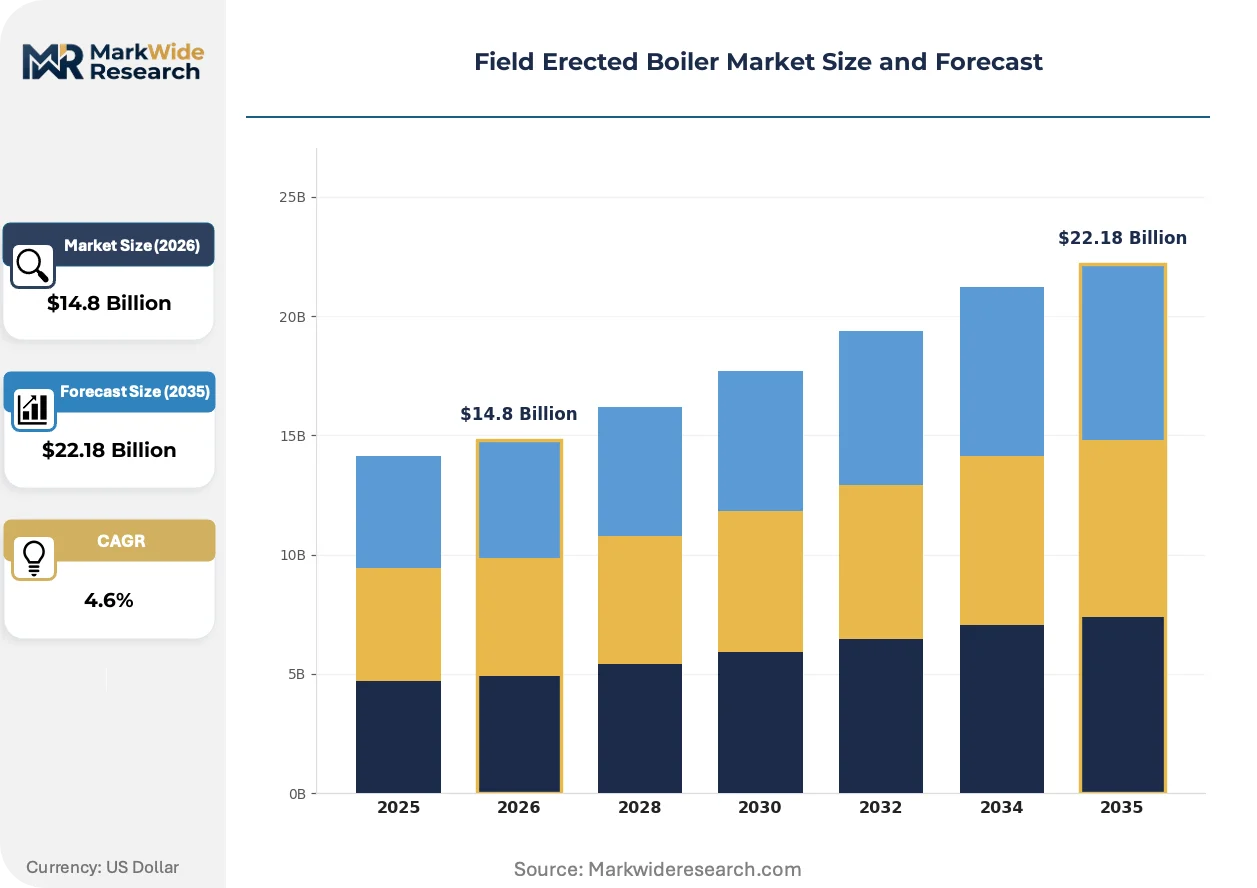
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Heat Recovery, Modular End User: Power Generation, Oil & Gas, Manufacturing, Chemical Processing Technology: Combustion, Gasification, Biomass, Solar Thermal Installation: On-Site, Off-Site, Turnkey, Customized |
| Companies Covered | Zeeco Connecticut, Alfa Laval Corporate AB, Applied Control Engineering Inc, Indeck Power Equipment Co, Ware Inc, Allied General Services, Industrial Boiler & Mechanical Co Inc, Miller & Chitty Co Inc, HydroTherm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Erected Boiler Market Shifts & Advancements
Digital twin deployment and additive manufacturing are reshaping how field erected boilers are designed, fabricated, and commissioned across remote industrial sites.
Membrane wall panel additive manufacturing is decomposing traditional rolled-tube and welded-fin construction sequences. Boiler fabricators in Germany and Japan are adopting wire-arc directed energy deposition for complex header connections, compressing on-site welding hours by 30-40 percent while enabling geometries impractical with conventional bending equipment.
EPA's revised New Source Performance Standards for greenhouse gas emissions from fossil fuel-fired electric generating units impose efficiency floors that exclude subcritical steam cycles from new construction permits. Combined-cycle gas turbine developers in Texas and Louisiana are specifying heat recovery steam generators with triple-pressure reheat configurations to maximize thermal efficiency.
Buyers are consolidating procurement authority into centralized engineering-procurement-construction management firms, stripping traditional equipment distributors from large utility transactions. This concentration shifts negotiation leverage toward lump-sum turnkey pricing and extended performance guarantees, most visible in Indonesian IPP tenders where Mitsubishi and Doosan affiliates now compete directly for full-plant contracts rather than component supply.
Field Erected Boiler Market Segmentation
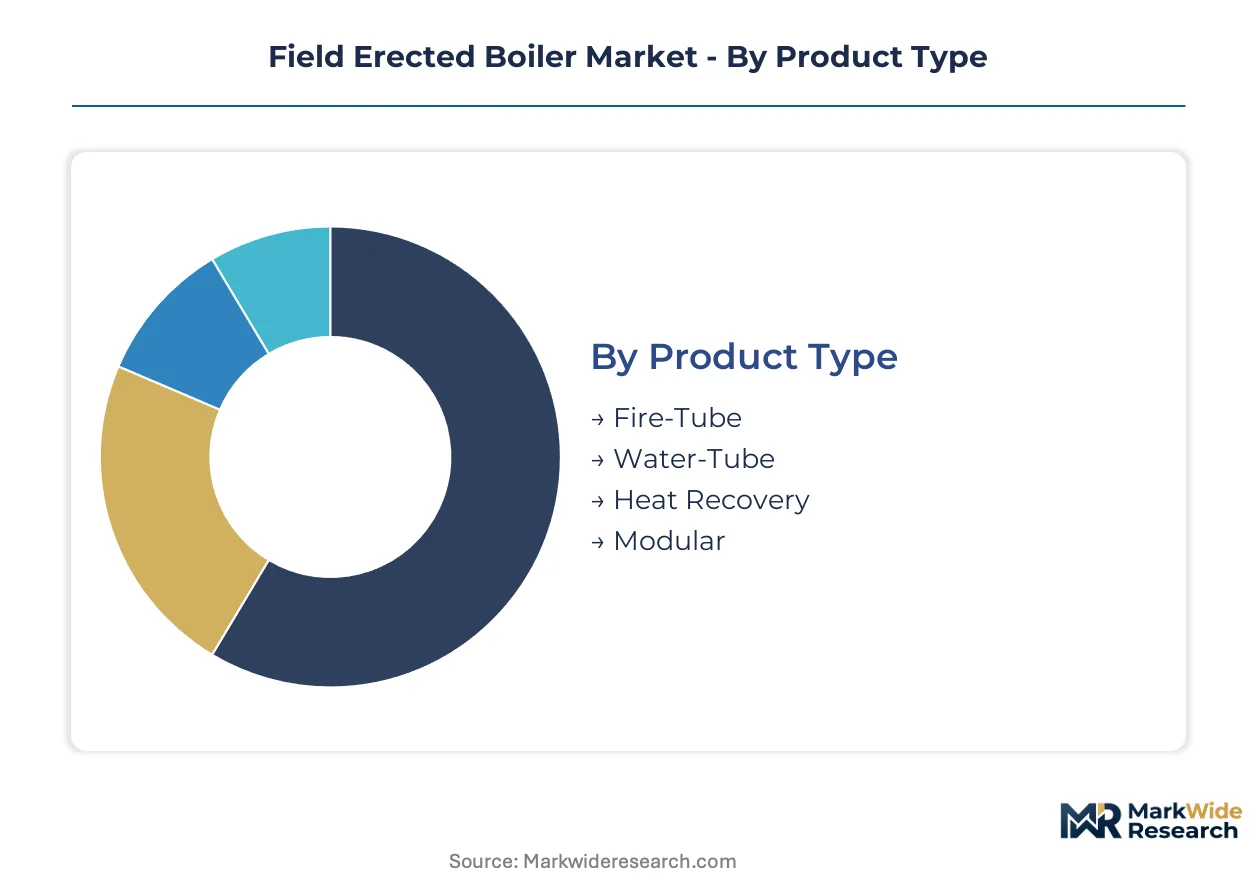
Field erected boiler procurement channels diverge sharply by project scale and technical complexity. Utility-scale power generators engage directly with original equipment manufacturers for custom specifications, while industrial processors route mid-size orders through engineering-procurement-construction integrators.
Product Type:
Channel mix varies by product architecture. Water-tube designs flow through direct OEM relationships for utility contracts. Fire-tube and modular configurations distribute more heavily through regional industrial distributors.
- Water-Tube:These configurations employ welded membrane wall construction with separated steam and water circuits to achieve pressures above 3,000 psi. Demand concentrates in Indonesian and Vietnamese utility expansions where ultra-supercritical specifications now dominate new-build tenders. ASME Section I compliance requirements lock in specialized fabricator relationships.
- Heat Recovery:Heat recovery steam generators capture exhaust energy from gas turbines and industrial process streams. Combined-cycle developers in Texas and Louisiana specify triple-pressure reheat configurations to maximize thermal efficiency under EPA greenhouse gas performance standards.
- Fire-Tube:Shell-and-tube designs with combustion gases passing through submerged tubes serve lower-pressure industrial process applications.
- Modular:Pre-fabricated sub-assemblies reduce on-site construction duration for remote installations.
By volume, water-tube leads. By growth pace, heat recovery is expanding most quickly.
End User:
Cost tier segmentation separates premium utility-grade specifications from standard industrial process configurations. Power generation commands engineering premiums; manufacturing and chemical processing compete on total installed cost.
- Power Generation:Independent power producers and regulated utilities deploy field erected units for baseload and peaking capacity. Indonesia's coal-to-gas conversion mandates and Vietnam's grid expansion drive procurement cycles with 25-30 year asset lifecycles.
- Chemical Processing:Petrochemical complexes and fertilizer plants require high-pressure steam for process heat and feedstock conversion. Gulf Coast facilities in Texas and Louisiana specify hydrogen-ready burner architectures to align with IRA clean hydrogen production tax credits.
- Oil & Gas:Refinery and upstream operations utilize field erected boilers for process steam and enhanced oil recovery.
- Manufacturing:Textile, pulp and paper, and food processing facilities deploy medium-pressure systems for drying and sterilization operations.
Power generation captures the largest revenue pool. Chemical processing shows the steepest expansion trajectory.
Technology:
Application context determines technology selection. Combustion dominates established infrastructure; gasification and biomass gain share in decarbonization-focused jurisdictions.
- Combustion:Conventional burner configurations firing natural gas, coal, or fuel oil remain the installed base majority. EPA Maximum Achievable Control Technology standards force continuous burner management system upgrades to meet tightening NOx ceilings.
- Biomass:Agricultural residue and dedicated energy crop combustion systems address renewable portfolio obligations in European and Southeast Asian markets. Specialized grate and fluidized bed designs handle variable fuel moisture and ash content.
- Gasification:Partial oxidation processes convert solid fuels to syngas for cleaner combustion.
- Solar Thermal:Concentrating solar power systems integrate field erected steam generators for thermal energy storage discharge.
Combustion retains volume leadership. Biomass is gaining share fastest in regulated renewable markets.
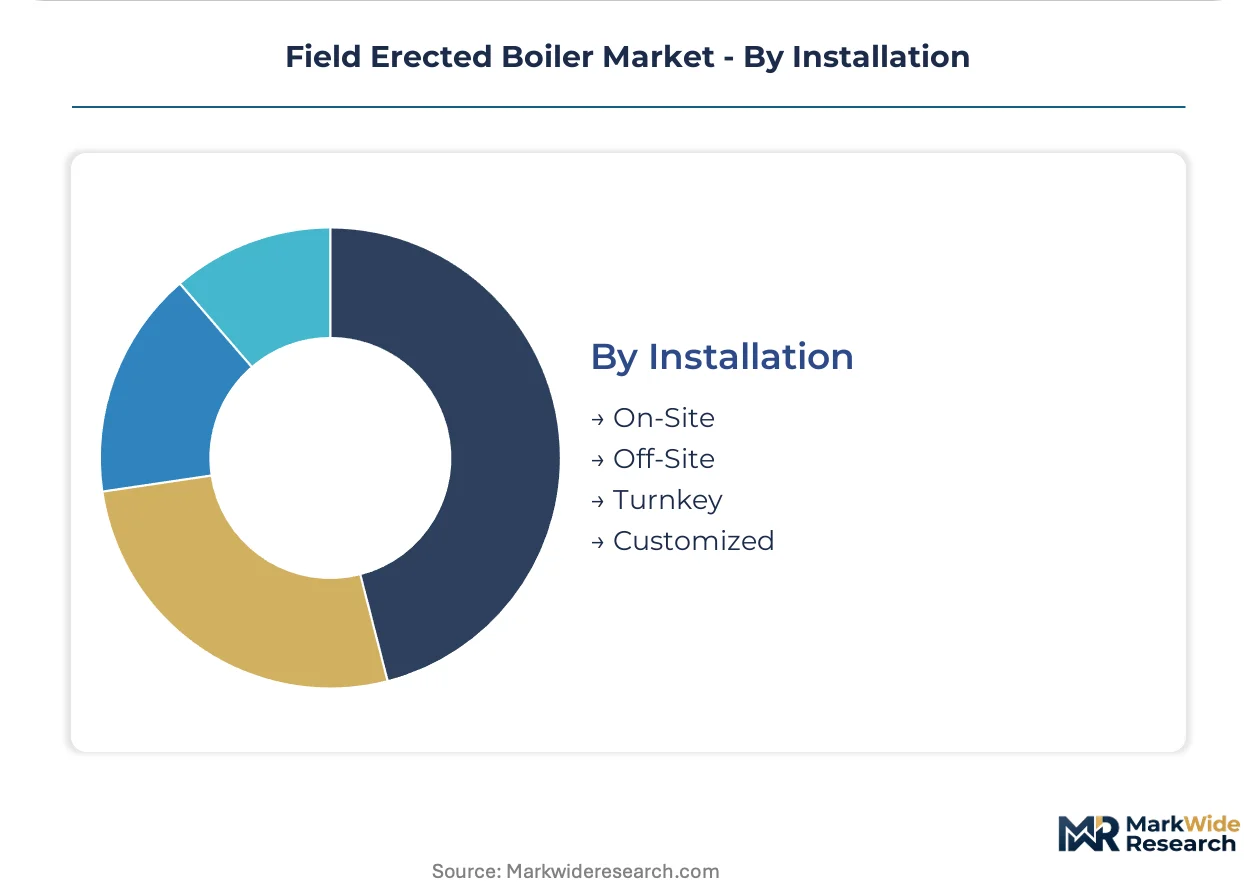
Installation:
Customer type segmentation separates owner-operated project management from third-party construction risk transfer. Utilities with in-house engineering capabilities favor customized arrangements; industrial processors prefer turnkey certainty.
- Turnkey:Single-contractor responsibility for engineering, procurement, construction, and commissioning transfers performance risk to the integrator. Indonesian IPP tenders increasingly specify lump-sum arrangements with extended availability guarantees.
- Customized:Owner-directed specification development with multiple contractor interfaces preserves design control. Philippine geothermal hybrid projects require site-specific heat recovery steam generator configurations for combined-cycle integration.
- On-Site:Traditional field assembly of components shipped to the installation location.
- Off-Site:Modular pre-assembly at remote fabrication yards with final module transport.
Turnkey dominates new utility capacity additions. Customized retains share in complex hybrid plant configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for superalloy pressure parts tilts the trade balance toward specialized steel exporters in Germany and Japan. Southeast Asian utilities absorb the majority of field erected boiler shipments as domestic fabrication capacity remains concentrated in established industrial economies.
Indonesia
Java-Bali grid infrastructure drives coal-to-gas conversion procurement cycles. The Ministry of Energy and Mineral Resources mandates retirement schedules for aging subcritical units. Industrial zones in Banten and East Java host independent power producer tenders specifying ultra-supercritical steam conditions.
Vietnam
Binh Duong and Dong Nai provinces anchor textile and food processing demand for high-pressure process steam. The national power development plan prioritizes combined-cycle capacity additions. Northern coal clusters in Quang Ninh province require custom field erected replacements for environmental compliance.
United States
Gulf Coast petrochemical complexes in Texas and Louisiana specify hydrogen-ready burner architectures. EPA Maximum Achievable Control Technology standards force combustion system upgrades across existing fleets. Permian Basin enhanced oil recovery operations utilize field erected steam generators for thermal extraction.
Germany
Ruhr industrial heritage supports specialized membrane wall fabrication for export markets. EU Green Deal hydrogen blending mandates accelerate dual-fuel burner development. Wire-arc directed energy deposition adoption in Bavarian fabrication yards compresses on-site welding hours for complex header geometries.
Philippines
Leyte and Mindanao island geothermal expansion requires custom heat recovery steam generators for hybrid plant configurations. The Department of Energy prioritizes renewable baseload capacity. Batangas and Quezon provinces host combined-cycle tenders specifying triple-pressure reheat configurations.
Field Erected Boiler Market Competitive Landscape
Listed leaders compete with private specialists across engineering-procurement-construction contract structures. The vendor base organizes around fabrication scale and service intensity rather than pure manufacturing volume. Three archetypes dominate: integrated boiler fabricators with captive alloy supply, regional service specialists with rental fleet assets, and engineering houses focused on heat recovery configurations. Competitive moves concentrate on lump-sum turnkey pricing and extended availability guarantees rather than component supply margins.
Among Swedish- and American-anchored fabricators, Alfa Laval Corporate AB, Indeck Power Equipment Co, and Ware Inc exemplify distinct positioning vectors. Alfa Laval occupies the heat transfer engineering tier with heritage in thermal system design. Indeck sits within the equipment supply and rental specialist category serving industrial process clients. Ware anchors the comprehensive service coverage archetype across North American manufacturing corridors. Each represents a viable competitive model without claiming exclusive segment dominance.
| Leading Market Players |
|---|
| Zeeco Connecticut |
| Alfa Laval Corporate AB |
| Applied Control Engineering Inc |
| Indeck Power Equipment Co |
| Ware Inc |
| Allied General Services |
| Industrial Boiler & Mechanical Co Inc |
| Miller & Chitty Co Inc |
| HydroTherm |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month lead times for certified pressure vessel welders compress pricing power toward established fabricators with captive training pipelines, while ASME certification backlogs force industrial buyers into premium long-term contracts. This supply-side rigidity amplifies cost pass-through capacity for membrane wall specialists serving Indonesian and Vietnamese utility tenders.
Pricing Analysis
Industrial OEM buyers anchor contract structures around lump-sum turnkey arrangements with extended availability guarantees. Pricing stratifies across ASME-certified premium fabricators, National Board-registered standard-tier suppliers, and non-certified economy entrants facing 8-14 month qualification delays. Price differentiation hinges on certification tier and geographic delivery cost, with remote Southeast Asian sites commanding engineering premiums. Cost compression in mid-scale modular segments intensifies as factory-built systems capture applications below 200 MW thermal output. Chemical processing buyers exhibit highest price sensitivity due to IRA clean hydrogen tax credit competition, while regulated utilities accept premium pricing for 25-30 year asset lifecycle certainty.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for superalloy pressure parts sourced from German and Japanese specialty steel producers. Membrane wall fabrication concentrates in Germany, Japan, and South Korea, with Ruhr industrial heritage supporting export-oriented production. Raw material dependencies center on nickel-based superalloys, chromium-molybdenum steel plate, and specialized welding consumables. Single-source vulnerability from concentrated European and Japanese alloy supply creates tariff exposure risk under evolving carbon border adjustment mechanisms. Distribution runs through engineering-procurement-construction integrators for utility-scale projects, while regional industrial distributors handle mid-scale manufacturing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based service contracts now expand faster than hardware shipments, transforming aftermarket revenue from parts replacement to availability-based fees. This service-attach dynamic rewards fabricators with installed base visibility and predictive maintenance capabilities.
For Market Incumbents: Compound defensive positioning through captive alloy supply relationships and hydrogen-ready burner R&D investment. Modular prefabrication substitution threatens mid-scale margins; counter via backward integration into membrane wall panel additive manufacturing to compress on-site welding hours. Prioritize ASME certification maintenance to preserve National Board registration barriers against non-certified entrants.
For New Entrants and Emerging Players: Remote site service coverage gaps in Philippine geothermal and Indonesian island installations present white-space entry points. Target customized heat recovery steam generator configurations for combined-cycle hybrid plants where incumbent EPC bundling leaves specification flexibility. Enter through specialized welding subcontractor partnerships to bypass 18-24 month certification pipelines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ASME and EPA compliance creates durable moats around certified fabricator relationships. Acquisition target archetype: regional service specialists with rental fleet assets and established utility maintenance contracts. Watch hydrogen blending mandate implementation timelines in EU and Southeast Asian jurisdictions as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Development | Dual-fuel architectures position fabricators for EU Green Deal blending mandates in power generation. |
| Membrane Wall Additive Manufacturing | Wire-arc directed energy deposition adoption compresses on-site welding hours for complex header geometries. |
| Performance-Based Service Contracts | Output-guaranteed maintenance agreements transform aftermarket revenue toward availability-based fee structures. |
| Backward Integration into Superalloy Supply | Captive procurement relationships mitigate single-source vulnerability from European and Japanese steel producers. |
| Modular Pre-Assembly Expansion | Remote fabrication yard deployment reduces on-site construction duration and labor risk in Southeast Asian installations. |
Research Methodology
A standing panel of utility planning officers, EPC project developers, aftermarket service heads, and membrane wall fabrication engineers provided ongoing calibration throughout primary fieldwork. Boiler OEM procurement teams and industrial plant maintenance directors contributed demand-side validation. Secondary sources included ASME Boiler and Pressure Vessel Code revision filings, EPA Maximum Achievable Control Technology standards documentation, National Board of Boiler and Pressure Vessel Inspectors registration databases, and Indonesian Ministry of Energy and Mineral Resources conversion mandate directives. Bottom-up project pipeline tracking and top-down installed base analysis were cross-referenced for triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product architecture, end-use industry, fuel technology, and installation modality. CAGRs were derived from project commissioning schedules, retirement replacement cycles, and industrial zone expansion timelines. Forecast inputs incorporated ASME certification queue lengths, superalloy price indices, and regional grid interconnection priorities.
Forecasts assume regulatory continuity in EPA emissions enforcement and EU Green Deal implementation; material policy shifts would require re-modeling. Hydrogen infrastructure deployment pace and carbon border adjustment mechanism activation represent primary revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Global Package Boilers Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Industrial and Residential Heating Market
Boilers
Gas Condensing Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Reformer Unit Market
Boilers
US Boiler Market
Boilers
North America Commercial Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Industrial Biomass Boiler Market
Boilers
Europe Residential Boiler Market
Boilers
Gas Fired Boilers Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
US Commercial Boiler Market
Boilers
Advanced Utility Boilers Market