
 Boiler Control Market | 2026-2036
Boiler Control Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler Control Market Analysis
The boiler control industry is pivoting around a widening split between premium IoT-enabled systems and commodity relay-based hardware. Honeywell leverages its building automation ecosystem to dominate integrated heating system deployments across North American commercial real estate. Siemens anchors its position through deep specialization in PLC-based process control architectures for industrial steam applications. Yokogawa competes by sustaining technology leadership in precision combustion monitoring for energy-intensive manufacturing sectors.
Boiler control encompasses the instrumentation, logic controllers, and software interfaces that regulate fuel-air mixture, steam pressure, and thermal output in combustion-based heat generation equipment. Modern systems integrate flame safeguard relays operating at millisecond response thresholds with digital actuators modulating fuel valve positions across 4-20 mA control loops to maintain thermal efficiency and operational safety. PLC-based systems occupy the highest margin tier due to their programmability and diagnostic depth in process control environments. Cloud-based solutions represent the fastest-expanding segment as facility operators remote-monitor boiler fleets through centralized dashboards. Conventional boilers retain volume leadership in residential replacement cycles where upgrade capital remains constrained.
The US Department of Energy and EPA shape product standards through minimum efficiency mandates and emissions thresholds that OEMs must certify against through third-party testing. The EU F-Gas Regulation and Ecodesign Directive progressively restrict greenhouse gas intensity in commercial heating equipment, forcing control suppliers to embed leak detection and modulation logic. Stakeholders must monitor how cybersecurity frameworks for operational technology evolve as cloud-connected boiler controllers expand attack surfaces across critical infrastructure networks.
Market Dynamics
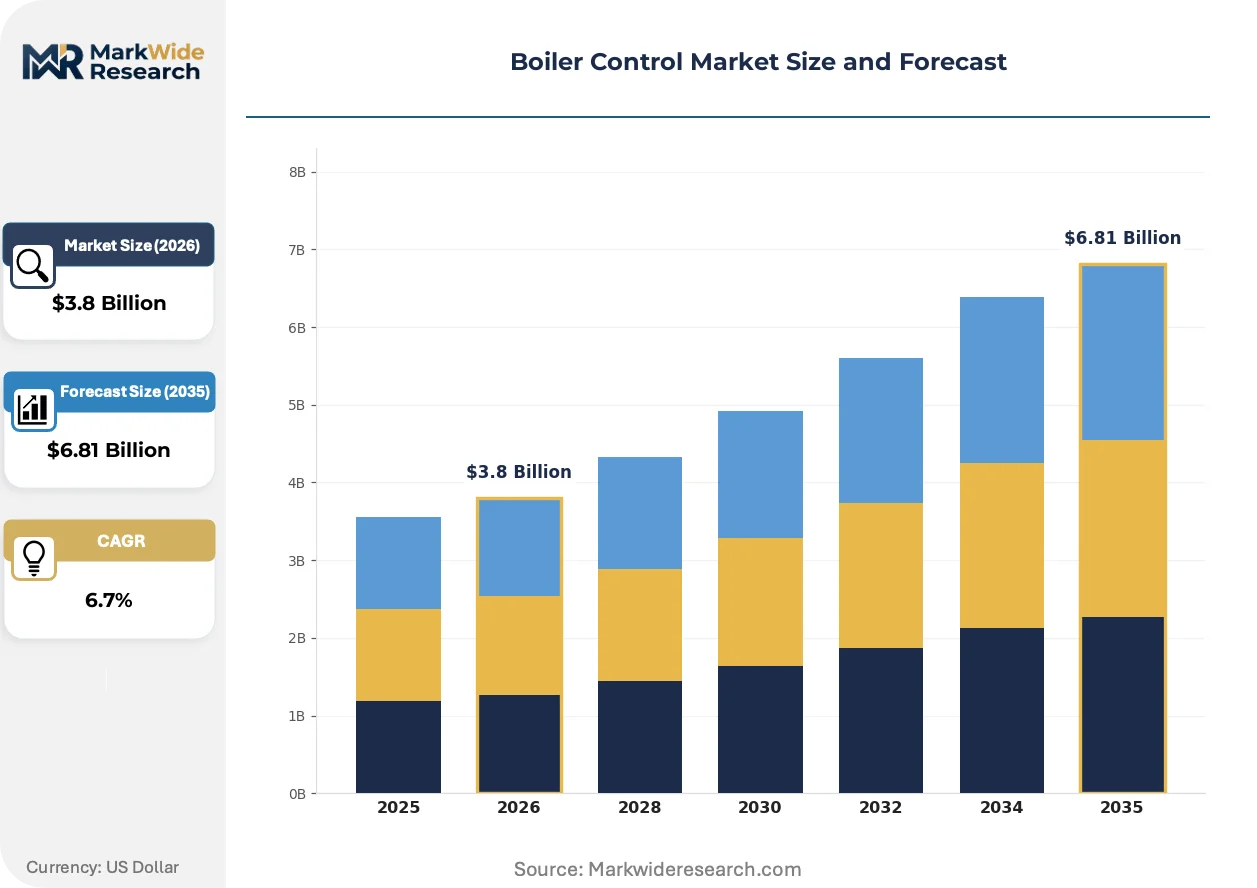
The boiler control market is bifurcating sharply between legacy relay-based hardware and connected digital platforms, with regulatory efficiency mandates accelerating replacement cycles across commercial and industrial installations.
Growth Catalysts
- Industrial facility retrofits:Aging steam infrastructure in Germany's chemical processing corridor is driving PLC-based control upgrades to meet tightening emissions thresholds.
- IoT platform proliferation:Commercial real estate operators are deploying cloud-connected boiler management systems to centralize thermal asset oversight across distributed property portfolios.
- EPA appliance standards:The US Department of Energy's escalating minimum performance thresholds for combustion systems are disqualifying non-modulating legacy controllers from new installations.
Market Restraints
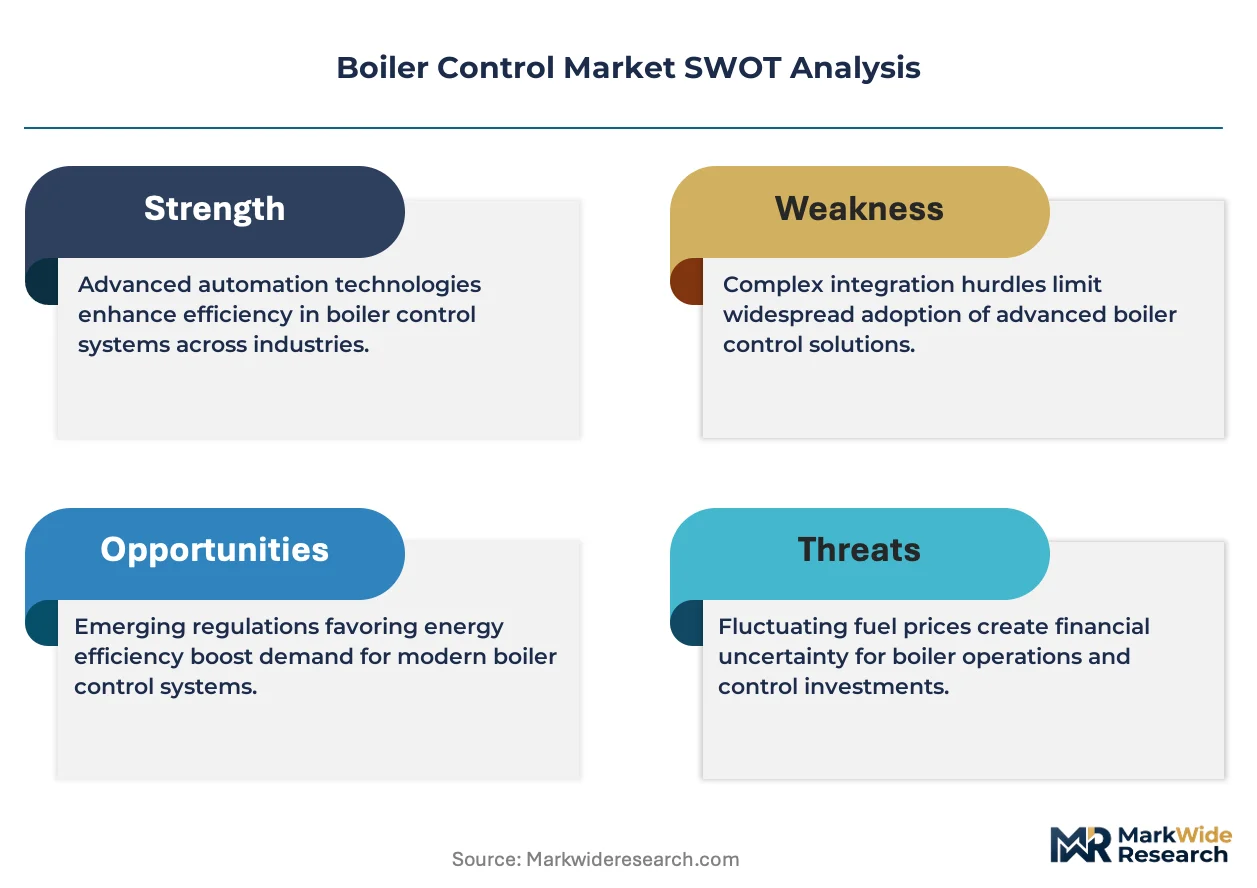
- Semiconductor supply concentration:PLC module production depends on specialized industrial microcontrollers concentrated in East Asian foundries, exposing lead times to geopolitical disruption.
- Copper and rare earth volatility:Control panel wiring and sensor magnet assemblies face input cost swings that compress hardware margins unpredictably.
- Skills gap in combustion tuning:The declining population of certified boiler technicians capable of calibrating fuel-air mixtures limits deployment velocity for advanced modulation systems.
Strategic Opportunities
- Predictive maintenance integration:Vibration and thermal sensor data streams are converging with machine learning platforms to enable failure-anticipation services for industrial steam operators.
- EU F-Gas tailwinds:Leak detection mandates for commercial heating equipment are creating embedded sensor demand that control suppliers can capture through integrated modulation logic.
- Remote monitoring channels:Direct-to-facility dashboard subscriptions are bypassing traditional distributor networks, capturing recurring revenue from multi-site hospital and university campuses.
Industry Challenges
- Cybersecurity certification complexity:Cloud-connected controllers must satisfy evolving OT security frameworks for critical infrastructure, extending product validation timelines.
- Legacy system integration friction:Digital retrofit kits face mechanical incompatibility with decades-old boiler mechanical linkages, requiring custom engineering on each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler Control Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Boilers, Conventional Boilers, Condensing Boilers, Combination Boilers Technology: PLC-based Systems, Relay-based Systems, Cloud-based Solutions, IoT-enabled Devices End User: Industrial Facilities, Residential Buildings, Commercial Establishments, Educational Institutions Application: Heating Systems, Process Control, Hot Water Supply, Energy Management |
| Companies Covered | Honeywell, Yokogawa, Siemens, Spirax Sarco, Cleaver-Brooks, ABB, Schneider Electric, HBX Control Systems, Emerson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler Control Market Emerging Trajectories
Boiler control architecture is pivoting from isolated electromechanical safeguards to networked digital ecosystems, with three parallel developments reshaping how thermal systems are specified, operated, and serviced.
Edge computing platforms are converging with flame safeguard relays to enable millisecond-response combustion monitoring while simultaneously streaming diagnostic telemetry to centralized maintenance dashboards. Food processing and pharmaceutical manufacturers with validated thermal processes are adopting these hybrid architectures fastest. The technology is converging with existing building automation protocols, compressing the addressable market for standalone boiler controllers into narrow replacement niches.
The EU F-Gas Regulation's progressive greenhouse gas intensity restrictions are forcing control suppliers to embed refrigerant leak detection and automated modulation logic into commercial heating equipment certifications. Industrial boiler OEMs must now demonstrate integrated sensor responsiveness through third-party testing before CE marking approval. German and Dutch facility operators are responding by specifying factory-integrated control packages rather than aftermarket retrofits to ensure compliance traceability.
Facility operators are consolidating thermal asset procurement under centralized engineering departments that demand outcome-based performance guarantees from control system vendors. Traditional equipment distributors are losing specification influence to direct manufacturer relationships with multi-site healthcare and education institutions. This concentration is most visible across US university systems and European hospital networks where capital planning has shifted from decentralized plant maintenance to enterprise energy management offices.
Boiler Control Market Segmentation
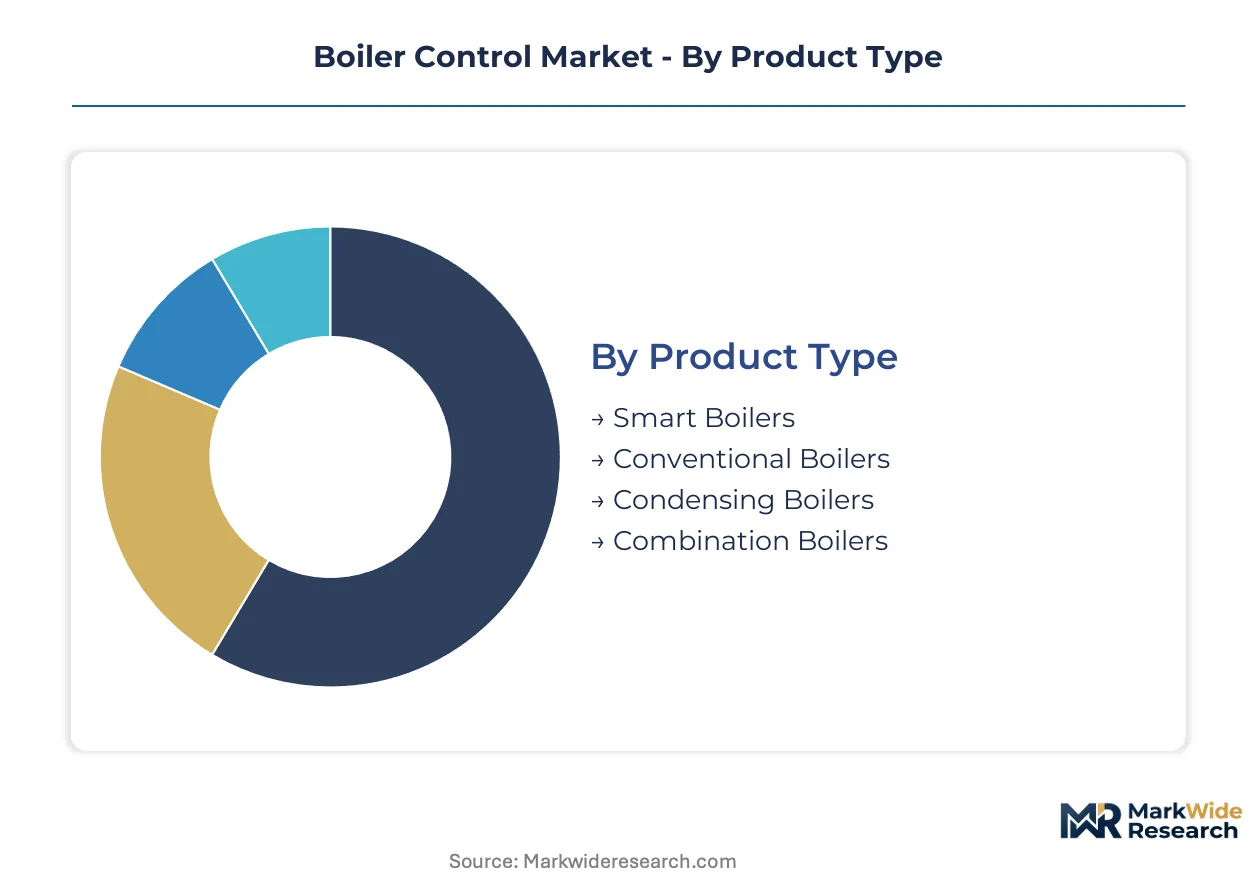
Boiler control procurement splits sharply across technical sophistication tiers, with facility operators weighing integration depth against capital constraints. Specification authority varies dramatically by end-use, from centralized engineering departments in multi-site healthcare networks to decentralized maintenance teams in residential property management.
Product Type:
Capital availability and retrofit complexity drive product selection, with premium digital systems commanding specification in new construction while legacy hardware persists in replacement cycles.
- Smart Boilers:Integrated control architectures embed flame safeguard relays with digital actuators modulating fuel valves across 4-20 mA loops. Demand concentrates in US commercial real estate portfolios where Honeywell's building automation ecosystem enables centralized thermal asset oversight.
- Condensing Boilers:High-efficiency combustion systems recover latent heat from flue gases through precision modulation controls. German chemical processing corridors specify these for facility retrofits meeting tightening EU F-Gas Regulation thresholds.
- Conventional Boilers:Non-modulating electromechanical controls dominate residential replacement markets where upgrade capital remains constrained.
- Combination Boilers:Dual-function heating and hot water units with integrated space-saving controls gain traction in European urban multi-family housing.
Volume sits with Conventional Boilers; growth tilts toward Smart Boilers.
Technology:
Control architecture selection hinges on diagnostic depth requirements, with process environments demanding programmability while simpler applications prioritize reliability over configurability.
- PLC-based Systems:Programmable logic controllers deliver millisecond-response combustion monitoring with extensive diagnostic telemetry. German industrial facility retrofits prioritize these upgrades for validated thermal processes in pharmaceutical manufacturing.
- Cloud-based Solutions:Remote monitoring platforms stream operational data to centralized maintenance dashboards. US university systems and European hospital networks deploy these across distributed campuses to consolidate engineering oversight.
- IoT-enabled Devices:Sensor-integrated controllers with predictive analytics capabilities are expanding most quickly in food processing sectors requiring continuous thermal validation.
- Relay-based Systems:Electromechanical safeguards persist in narrow replacement niches where mechanical simplicity outweighs connectivity requirements.
PLC-based Systems anchor industrial margins; Cloud-based Solutions are climbing the fastest.
End User:
Procurement centralization varies by sector, with enterprise energy management offices displacing traditional distributor influence in institutional settings.
- Industrial Facilities:Energy-intensive manufacturing sectors specify precision combustion monitoring for steam-intensive processes. German chemical processing corridors drive PLC-based control demand through emissions compliance mandates.
- Commercial Establishments:Multi-site property operators deploy IoT-enabled management platforms to centralize oversight. US commercial real estate expansion of cloud-connected systems bypasses traditional distributor networks.
- Educational Institutions:Enterprise energy management offices in US university systems demand outcome-based performance guarantees from control vendors.
- Residential Buildings:Decentralized maintenance teams with constrained capital sustain volume for conventional relay-based hardware in replacement cycles.
Industrial Facilities command premium pricing; Commercial Establishments are gaining share fastest.
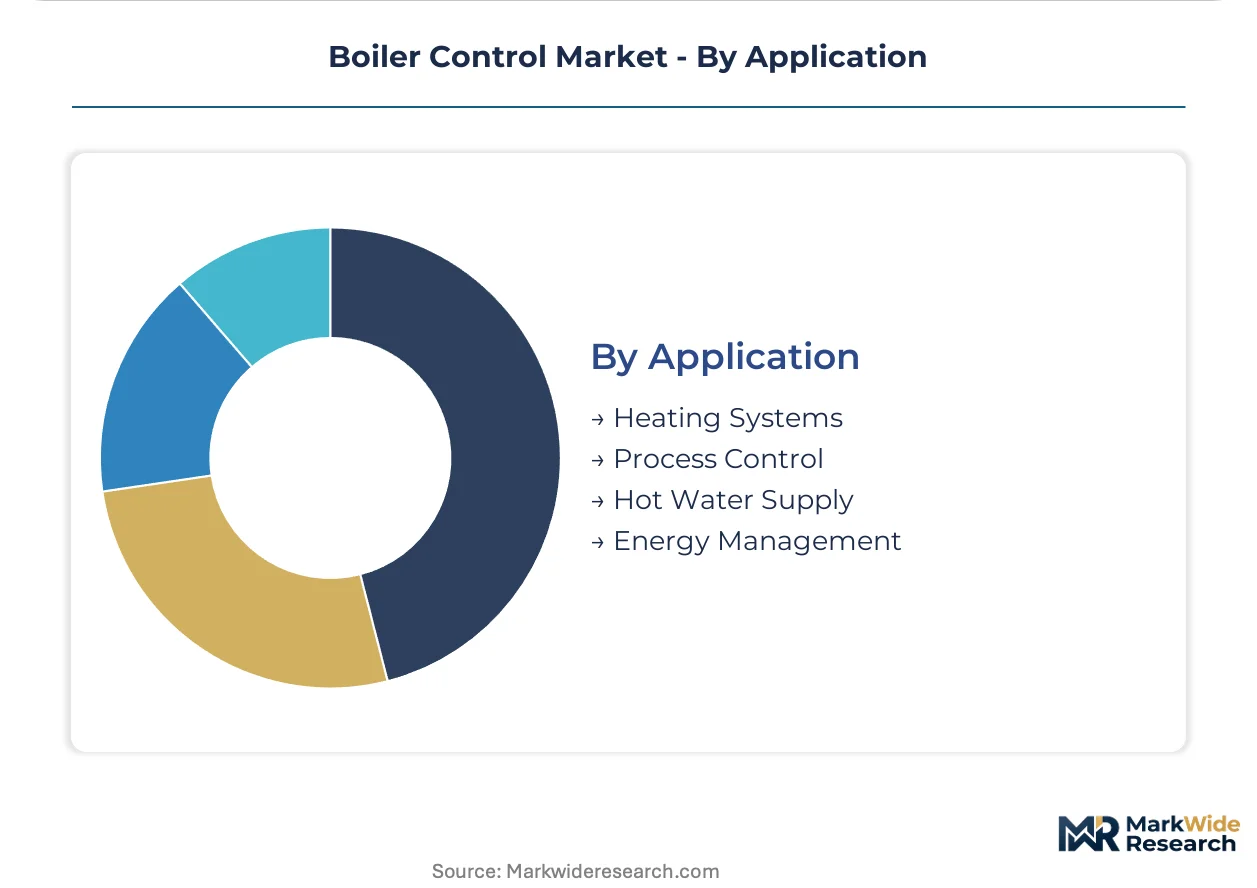
Application:
Functional requirements dictate control sophistication, with safety-critical process environments mandating redundancy while comfort heating permits simpler modulation.
- Process Control:Validated thermal processes in pharmaceutical and food manufacturing demand millisecond-response flame safeguards with comprehensive audit trails. German and Dutch facility operators specify factory-integrated packages for CE marking compliance traceability.
- Energy Management:Outcome-based performance contracts require granular consumption monitoring and automated optimization. Multi-site healthcare and education institutions consolidate procurement under centralized engineering departments.
- Heating Systems:Space heating applications in commercial and residential buildings utilize modulation controls meeting EPA appliance efficiency standards.
- Hot Water Supply:Domestic hot water generation employs simpler temperature control loops with lower diagnostic requirements than process steam applications.
Heating Systems retain volume leadership; Energy Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European boiler control demand through chemical processing facility retrofits. The United States and China follow as distinct demand centers shaped by diverging regulatory frameworks and infrastructure investment cycles.
United States
Commercial real estate portfolios in New York and Chicago drive cloud-connected boiler management deployments. EPA appliance efficiency standards disqualify non-modulating legacy controllers from new installations. University systems across California and Texas consolidate procurement under enterprise energy management offices demanding outcome-based performance guarantees.
Germany
Industrial facility retrofits in the chemical processing corridor prioritize PLC-based control upgrades. EU F-Gas Regulation mandates progressively tighten greenhouse gas intensity thresholds for commercial heating equipment. Facility operators in Ludwigshafen and Leverkusen specify factory-integrated control packages to ensure CE marking compliance traceability.
China
Manufacturing clusters in the Yangtze River Delta expand precision combustion monitoring for energy-intensive production. MIIT industrial efficiency programs accelerate control system modernization in state-owned steam facilities. Cities across Jiangsu and Zhejiang provinces deploy integrated heating solutions in new commercial construction.
Japan
Pharmaceutical manufacturers in the Kansai region adopt millisecond-response flame safeguards for validated thermal processes. METI energy conservation standards push facility operators toward predictive maintenance integration. Osaka-based food processors specify sensor-integrated controllers with continuous thermal validation capabilities.
India
Industrial boiler operators in Maharashtra and Gujarat face CEA efficiency mandates requiring modulation control retrofits. PLI scheme incentives support domestic manufacturing of programmable logic controllers for process industries. Chemical plants in the Mumbai-Pune industrial belt prioritize PLC-based upgrades to meet tightening emissions thresholds.
Boiler Control Market Vendor Landscape
Premium-margin players sit above commodity-margin players across diagnostic depth and integration complexity. The vendor base stratifies into three tiers: building automation ecosystem integrators, industrial process control specialists, and standalone hardware fabricators. Two strategic archetypes dominate — diversified automation conglomerates leveraging cross-selling synergies, and focused combustion control specialists defending niche technical positions. Competitive moves concentrate on technology licensing partnerships and backward integration into sensor manufacturing.
Among diversified automation conglomerates, Honeywell and Siemens exemplify contrasting ecosystem strategies. Honeywell leverages its building automation footprint across North American commercial real estate. Siemens anchors industrial positioning through deep PLC-based process control specialization. Yokogawa occupies a focused specialist position in precision combustion monitoring for energy-intensive manufacturing sectors.
| Leading Market Players |
|---|
| Honeywell |
| Yokogawa |
| Siemens |
| Spirax Sarco |
| Cleaver-Brooks |
| ABB |
| Schneider Electric |
| HBX Control Systems |
| Emerson |
| Others |
Supply Flow & Price Mechanics
Copper wiring and rare earth magnet assemblies feed from East Asian foundries through three distinct pricing tiers before reaching facility operators in Germany's chemical corridor and US commercial real estate portfolios. PLC module costs concentrate in Taiwanese semiconductor fabrication, compressing margins for European system integrators facing EU F-Gas compliance mandates while elevating premium pricing for certified factory-integrated packages.
Pricing Analysis
Outcome-based performance contracts anchor value-based pricing for cloud-connected boiler management platforms serving multi-site healthcare and education institutions. Three-tier pricing structure across premium, standard, and economy levels separates PLC-based process control systems with millisecond-response diagnostics from relay-based hardware and IoT-enabled subscription tiers. Cost compression in relay-based controllers is intensifying because residential replacement markets prioritize mechanical simplicity over connectivity. Commercial real estate operators exhibit lowest price sensitivity, while decentralized residential maintenance teams sustain volume demand for economy-tier electromechanical safeguards.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries supplying industrial microcontrollers for PLC module production. Component sourcing draws from China for sensor assemblies, Germany for precision actuators, and Japan for flame safeguard relays. Tariff exposure on semiconductor imports threatens lead times for North American control system OEMs. Distribution runs through authorized industrial automation distributors serving plant engineering departments, with direct manufacturer relationships gaining share in institutional procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's progressive greenhouse gas intensity restrictions create a cost-of-compliance moat that factory-integrated control suppliers can exploit while aftermarket retrofitters face certification traceability barriers.
For Market Incumbents: Deepen backward integration into sensor manufacturing to capture embedded leak detection demand from EU F-Gas mandates. Fortify channel control through direct relationships with enterprise energy management offices in US university systems, displacing traditional distributor influence. Certification investment in CE marking compliance traceability defends margin position against emerging cloud-native platform entrants. For New Entrants and Emerging Players: Edge computing platforms with millisecond-response combustion monitoring offer a technology-first wedge into food processing and pharmaceutical manufacturing segments requiring validated thermal processes. White-space concentration sits with predictive maintenance integration for industrial steam operators in India's Maharashtra chemical belt. Direct-to-facility dashboard subscriptions bypass entrenched distributor networks in European hospital networks. For Investors and Strategic Acquirers: CEA efficiency mandate enforcement in India's Mumbai-Pune industrial belt is the leading indicator that PLC-based control retrofit demand will accelerate across emerging market manufacturing clusters. Acquisition targets should prioritize industrial process control specialists with deep pharmaceutical and chemical sector certification depth. Watch for cybersecurity framework finalization for operational technology as the signal for cloud-connected controller market consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures EU F-Gas embedded leak detection mandates for CE marking compliance. |
| Predictive Maintenance Platform Launch | Converges vibration and thermal data with machine learning for industrial steam operators. |
| Direct-to-Facility Subscription Model | Bypasses distributor networks to capture recurring revenue from multi-site healthcare campuses. |
| Cybersecurity Certification Investment | Satisfies evolving OT security frameworks for critical infrastructure cloud-connected deployments. |
| Pharmaceutical Sector Specialization | Targets validated thermal process requirements in German and Dutch facility operator specifications. |
Methodological Framework
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews across plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Bottom-up segment sizing triangulated against top-down macro indicators validated volume and value estimates. Primary fieldwork captured specification authority shifts from decentralized maintenance teams to enterprise energy management offices in institutional settings.
Historical trendline analysis established baseline growth patterns across product type, technology architecture, end-user sector, and application function segmentation dimensions. CAGRs were derived through regression analysis of replacement cycle timing, regulatory compliance deadlines, and technology adoption S-curves. Forecast inputs incorporated EPA appliance efficiency standard phase-in schedules and EU F-Gas Regulation implementation timelines without year-specific anchoring.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian semiconductor supply, extreme commodity price volatility in copper and rare earth markets, and unanticipated cybersecurity incidents affecting cloud-connected controller adoption. Deviation in regulatory enforcement intensity or compliance deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Europe Power Plant Boiler Market
Boilers
Electric Boiler Market
Boilers
Field Erected Boiler Market
Boilers
Commercial Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
GCC Electric Water Heater Market
Boilers
Advanced Utility Boilers Market
Boilers
Gas Condensing Boiler Market
Boilers
Global Package Boilers Market
Boilers
US Industrial Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market