
 Advanced Utility Boilers Market | 2026-2036
Advanced Utility Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Utility Boilers Market Outlook
Utility procurement consolidation around independent power producers and large industrial captives is restructuring the competitive landscape for boiler OEMs. General Electric Company leverages its HA gas turbine integration expertise to bundle combined-cycle boiler packages for IPP developers. Siemens AG sustains engineering leadership in supercritical steam conditions through its Benson boiler technology platform. Mitsubishi Hitachi Power Systems anchors Asian coal-utility relationships with ultra-supercritical reference plants across multiple markets.
Advanced utility boilers are high-pressure steam generators engineered to operate above 22.1 MPa and 374°C, converting thermal energy from pulverized coal, natural gas, or biomass combustion into mechanical work for electricity generation. Supercritical units eliminate the steam-water phase boundary, achieving thermal efficiencies exceeding 45% while reducing fuel consumption and CO₂ intensity per megawatt-hour. Circulating Fluidized Bed technology captures growing share in markets with high-ash coal or biomass co-firing mandates due to its fuel flexibility and in-situ sulfur capture. Natural Gas-fired installations lead value contribution where carbon pricing and methane regulation accelerate coal-to-gas switching, though coal retains dominant share in developing Asian power systems.
EPA MATS in the United States, EU F-Gas Regulation, and India's CEA emission norms collectively tighten particulate, SOₓ, NOₓ, and mercury limits, mandating selective catalytic reduction, flue-gas desulfurization, and advanced combustion controls as baseline requirements for new and retrofit installations. Boiler OEMs must certify equipment against diverging regional standards, fragmenting product platforms and raising compliance engineering costs. Stakeholders should monitor carbon border adjustment mechanisms and evolving green hydrogen blending specifications, as these will determine whether gas-fired supercritical designs or biomass-adapted circulating fluidized bed systems command the next wave of utility capital allocation.
Market Dynamics
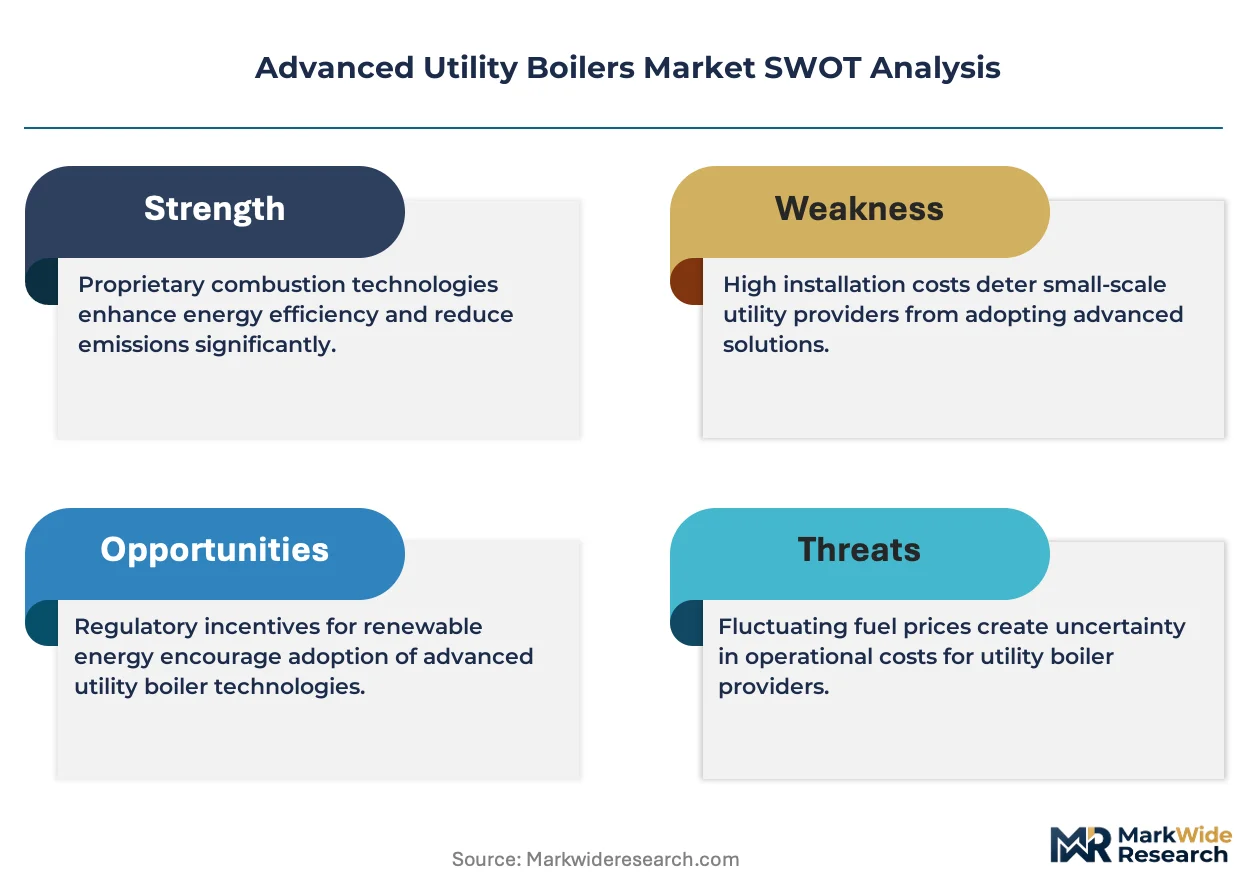
IPP and captive power operators in Southeast Asia are consolidating procurement around supercritical boiler packages, compressing vendor margins while raising technical certification barriers for equipment suppliers.
Growth Catalysts
- EPA MATS compliance deadlines:US coal-fired utilities face mandatory mercury and acid gas emission limits, forcing boiler retrofits and selective catalytic reduction installations across aging generation fleets.
- India's CEA emission norms:Central Electricity Authority mandates tighten particulate and SOₓ thresholds for new thermal capacity, accelerating orders for flue-gas desulfurization-integrated boiler systems.
- Biomass co-firing mandates:EU member states enforce renewable energy quotas for existing coal plants, expanding circulating fluidized bed retrofits capable of handling agricultural residue blends.
Market Restraints
- Specialized alloy supply concentration:Supercritical pressure parts require P91 and P92 creep-resistant steels concentrated among Japanese and European specialty mills, exposing OEMs to input cost volatility.
- Carbon border adjustment exposure:EU CBAM phase-in creates tariff uncertainty for coal-fired boiler exports from Vietnam and Indonesia, complicating long-term project financing.
- Green hydrogen substitution threat:Electrolyzer cost declines and EU hydrogen bank subsidies position H₂-ready gas turbines as eventual replacements for new-build gas-fired boilers.
Strategic Opportunities
- Vietnam power development plan:PDP8 authorizes 14 GW of new supercritical coal capacity through 2030, creating demand concentration for ultra-supercritical reference plant suppliers.
- Green hydrogen blending specifications:EU F-Gas Regulation and national hydrogen strategies open retrofit markets for gas-fired boilers capable of 30% H₂ co-firing.
- Digital twin convergence:Integration of physics-based boiler modeling with AI-driven predictive maintenance creates aftermarket service expansion paths for OEMs with installed base data.
Industry Challenges
- Welding technician scarcity:Thick-walled pressure vessel fabrication requires ASME-certified welders in short supply across Southeast Asian manufacturing hubs.
- Multi-jurisdiction certification timelines:Boiler OEMs must sequence ASME, EN, and BIS approvals for export orders, extending project bid-to-award cycles.
- Legacy control system integration:Supercritical upgrades into 1970s-era subcritical plants face DCS compatibility constraints and operator retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Utility Boilers Market |
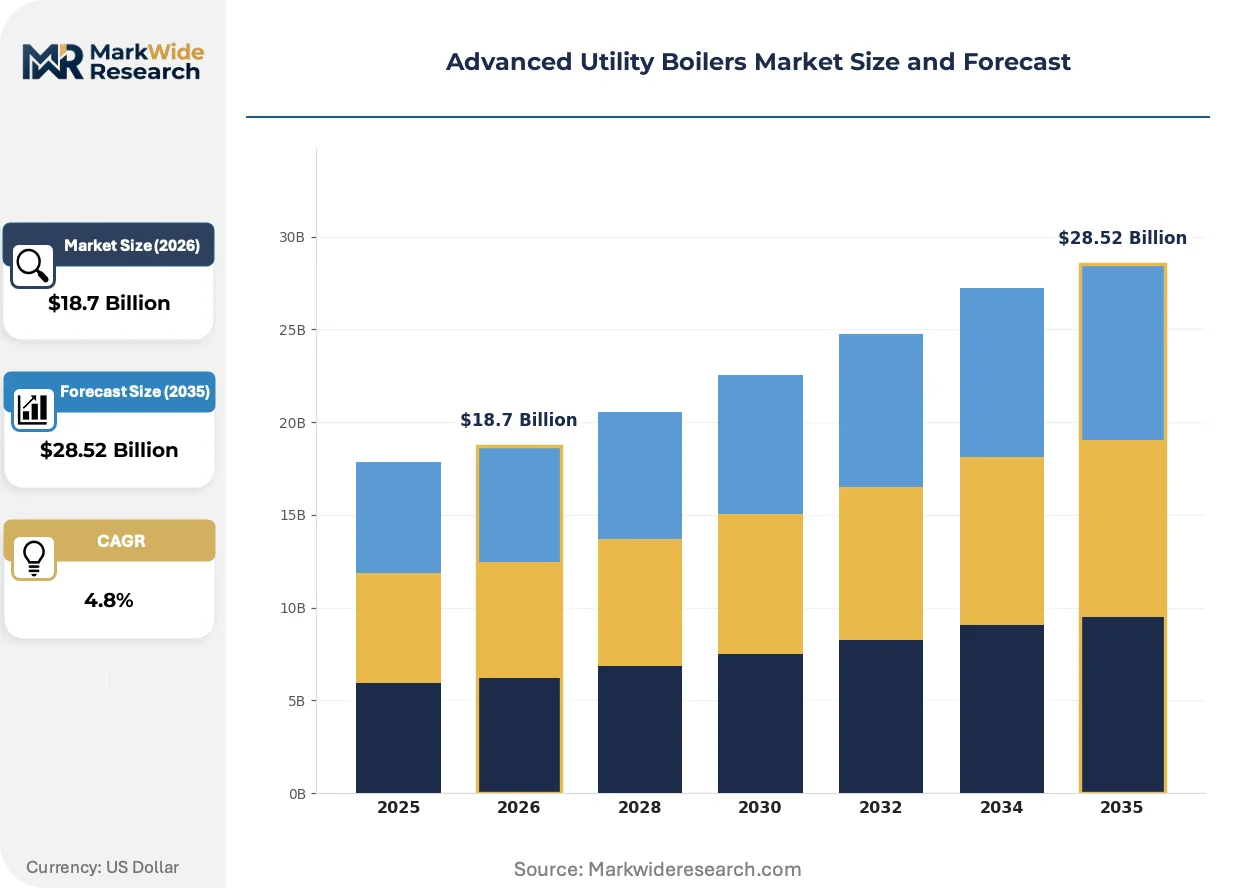
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boiler Type: Circulating Fluidized Bed, Supercritical, Subcritical, Heat Recovery Fuel Type: Coal, Natural Gas, Biomass, Oil End User: Power Generation, Industrial, District Heating, Paper & Pulp Installation Type: New, Retrofit, Modular, Replacement |
| Companies Covered | General Electric Company, Siemens AG, Mitsubishi Hitachi Power Systems, Babcock & Wilcox Enterprises, Doosan Heavy Industries & Construction, Mitsubishi Heavy Industries, Dongfang Electric Corporation, Larsen & Toubro Limited, Thermax Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Utility Boilers Market Strategic Shifts
Equipment manufacturers are repositioning around fuel flexibility and digital integration as coal-gas biomass boundaries blur and utility buyers demand operational data transparency.
Modular once-through steam generator designs are decentralizing project execution models for IPP developers. Standardized Benson boiler skids from Siemens Energy enable 18-month construction schedules versus 36 months for field-erected units. This compression is decentralizing EPC risk allocation toward balance-of-plant contractors while concentrating OEM responsibility on core pressure part performance guarantees.
EU F-Gas Regulation phase-down schedules are accelerating natural gas-fired boiler specifications with lower-GWP refrigerants for auxiliary cooling systems. Industrial consequence falls on OEMs redesigning turbine hall HVAC and stator cooling packages. German and Dutch utilities now specify ammonia-based or water-cooled alternatives in tender documents, forcing engineering changes for export-bound equipment.
IPP procurement teams are unbundling long-term service agreements from initial equipment supply, compressing OEM aftermarket revenue visibility. Independent service providers with AI-driven diagnostics capabilities are capturing boiler tuning and outage management contracts previously held by manufacturers. This unbundling is most advanced in Indian and Indonesian markets where NTPC and PLN subsidiaries actively cultivate third-party maintenance competition.
Advanced Utility Boilers Market Segmentation
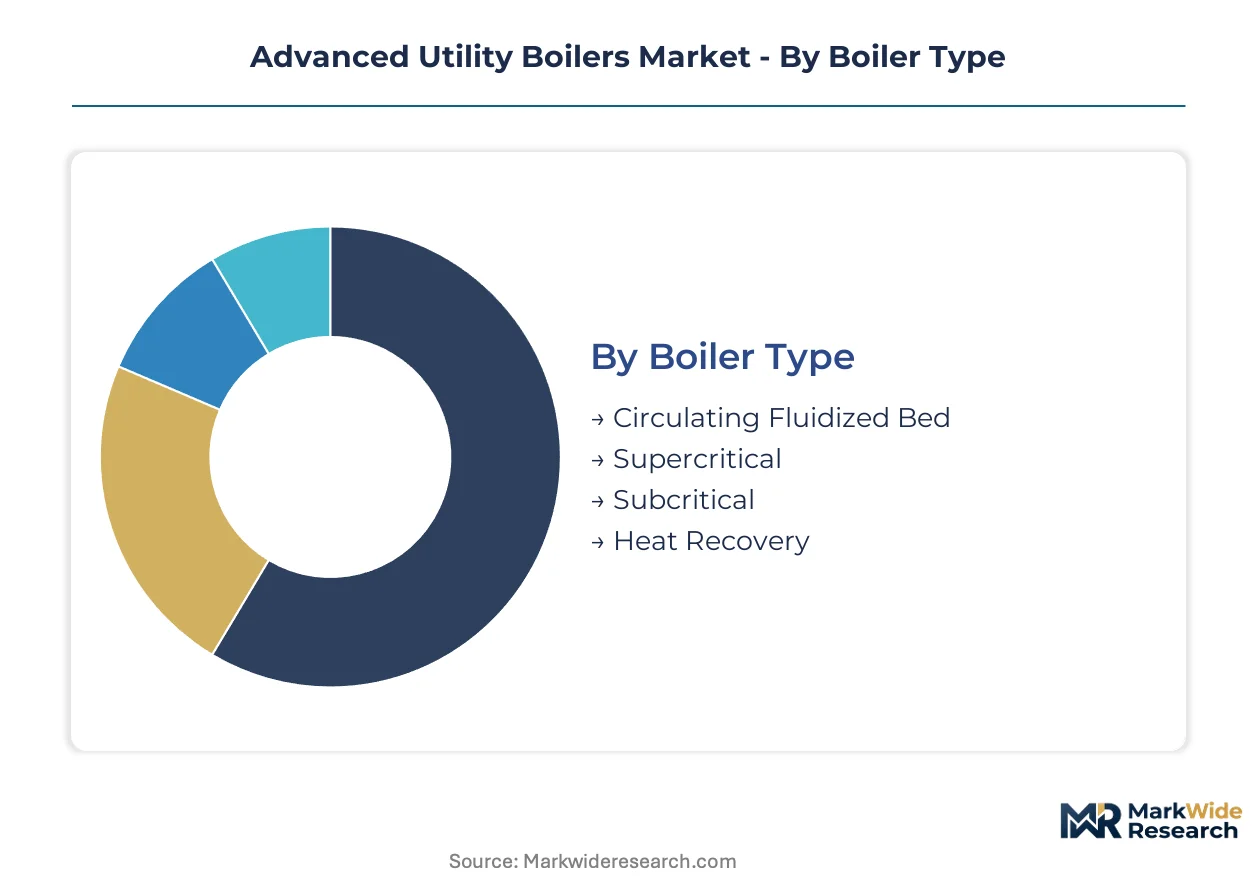
Boiler OEMs configure product platforms around fuel chemistry, steam pressure boundaries, and installation constraints. Segmentation discipline separates volume-driven replacement cycles from technology-led new-build premiums.
Boiler Type:
Upgrade and replacement cycles concentrate procurement around pressure-part specifications that determine retrofit compatibility with existing turbine islands.
- Supercritical:These units operate above 22.1 MPa, eliminating the liquid-vapor phase boundary to achieve thermal efficiencies exceeding 45%. IPP developers in Vietnam and Indonesia anchor procurement around ultra-supercritical reference plants from established Asian suppliers.
- Circulating Fluidized Bed:Fuel-flexible designs suspend solid fuel in upward-flowing air streams, enabling high-ash coal combustion and biomass co-firing without downstream desulfurization. EU utilities retrofit CFB systems to meet renewable energy quotas for existing thermal fleets.
- Subcritical:Conventional drum-type boilers remain entrenched in legacy fleets requiring pressure-part replacement rather than full island upgrades.
- Heat Recovery:HRSG modules capture exhaust energy from gas turbines in combined-cycle configurations.
Supercritical units sit at the top of the volume ranking, with Circulating Fluidized Bed climbing the fastest.
Fuel Type:
Carbon pricing intensity and fuel availability reshape regional procurement patterns across utility portfolios.
- Coal:Pulverized coal combustion dominates developing Asian power systems despite net-zero commitments. India's CEA emission norms force flue-gas desulfurization integration for all new subcritical and supercritical installations.
- Natural Gas:Combined-cycle gas turbine integration drives demand for heat recovery steam generators in markets with carbon border exposure. EU F-Gas Regulation accelerates specifications for lower-GWP auxiliary cooling systems on gas-fired units.
- Biomass:Agricultural residue and energy crop combustion expands in markets with renewable portfolio standards.
- Oil:Distillate and residual fuel oils retain niche applications in island grids and peaking plants.
Coal retains the largest installed base, though Natural Gas gains share fastest where methane regulation tightens.
End User:
Customer archetypes diverge around dispatch priority, fuel procurement scale, and environmental compliance exposure.
- Power Generation:Centralized utilities and IPPs prioritize thermal efficiency and grid stability services. Southeast Asian power development plans anchor equipment demand for supercritical coal and combined-cycle gas configurations.
- Industrial:Captive power operators integrate process steam and electricity production around refinery, petrochemical, and steel plant loads.
- District Heating:Municipal energy systems in Northern Europe and China deploy combined heat and power configurations.
- Paper & Pulp:Black liquor recovery boilers and biomass co-firing systems serve integrated mill energy balances.
Power Generation commands the revenue concentration, with Industrial expanding most quickly on captive capacity additions.
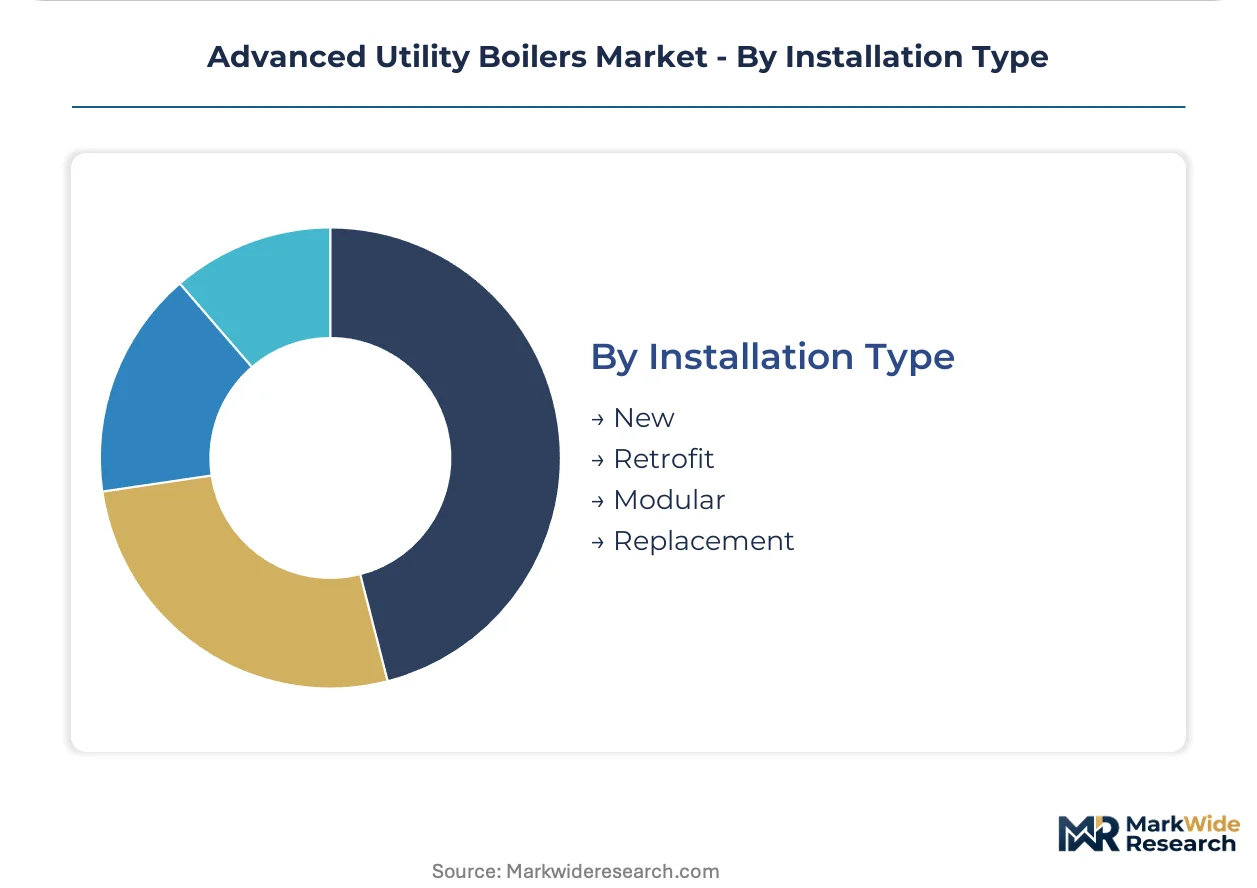
Installation Type:
Project delivery models compress construction schedules and redistribute EPC risk between OEMs and balance-of-plant contractors.
- New:Greenfield supercritical and combined-cycle installations require full island engineering with 36-month typical construction timelines. Modular Benson boiler skids from European suppliers compress this to 18 months for standardized IPP developments.
- Retrofit:Emission control upgrades integrate selective catalytic reduction and flue-gas desulfurization into 1970s-era subcritical plants. EPA MATS compliance deadlines in the United States force mercury and acid gas control retrofits across aging coal fleets.
- Modular:Factory-fabricated pressure part assemblies reduce field welding requirements and accelerate commissioning in markets with ASME-certified welder scarcity.
- Replacement:In-kind pressure part swaps maintain turbine island compatibility while extending plant operating licenses.
New installations lead absolute unit volume, with Retrofit showing the steepest expansion trajectory on regulatory compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's supercritical coal expansion contrasts with Germany's gas turbine integration pivot, while Southeast Asian markets split between emission compliance retrofits and new capacity additions.
United States
EPA MATS compliance deadlines force mercury and acid gas control retrofits across aging coal fleets. Utilities in Ohio, Pennsylvania, and West Virginia accelerate selective catalytic reduction installations. The PJM interconnection anchors demand for boiler emission upgrades as plant operators seek operating license extensions.
Germany
EU F-Gas Regulation phase-down schedules redirect utility procurement toward lower-GWP auxiliary cooling systems. The Rhine-Ruhr industrial corridor hosts combined-cycle gas turbine conversions as coal phase-out accelerates. E.ON and RWE subsidiaries specify ammonia-based alternatives in tender documents for new HRSG modules.
India
CEA emission norms tighten particulate and SOₓ thresholds for all new thermal capacity. Gujarat and Maharashtra states concentrate ultra-supercritical orders as NTPC and Adani Power expand generation fleets. Flue-gas desulfurization integration becomes mandatory for subcritical and supercritical installations alike.
Vietnam
PDP8 authorizes 14 GW of new supercritical coal capacity through 2030. The Red River Delta and Mekong Delta regions host IPP developers sourcing reference plant technology from established Asian suppliers. Carbon border adjustment exposure complicates long-term project financing for export-oriented manufacturing zones.
Indonesia
PLN procurement consolidation around captive power operators compresses vendor margins for boiler OEMs. Java-Bali grid expansion drives supercritical orders despite net-zero pledge tensions. High-ash coal characteristics favor circulating fluidized bed specifications in Sumatra and Kalimantan mine-mouth plants.
Advanced Utility Boilers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base organizes around three strategic archetypes: integrated energy technology conglomerates with turbine-boiler bundling capabilities, pressure-part fabricators with ASME certification depth, and regional EPC contractors with local content compliance expertise. M&A activity concentrates on digital twin and predictive maintenance capabilities, while technology licensing agreements redistribute supercritical design IP across Asian manufacturing hubs.
Among integrated technology conglomerates, General Electric Company and Siemens AG occupy positions spanning gas turbine integration and supercritical steam generator engineering. Mitsubishi Hitachi Power Systems anchors the Asian reference plant tier. Babcock & Wilcox Enterprises and Doosan Heavy Industries & Construction represent the pressure-part fabrication archetype with extensive ASME-certified welding capacity. Dongfang Electric Corporation and Larsen & Toubro Limited exemplify regional EPC contractors with domestic content compliance capabilities in their respective home markets. Thermax Limited sits within the industrial captive power specialization tier.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| Mitsubishi Hitachi Power Systems |
| Babcock & Wilcox Enterprises |
| Doosan Heavy Industries & Construction |
| Mitsubishi Heavy Industries |
| Dongfang Electric Corporation |
| Larsen & Toubro Limited |
| Thermax Limited |
| Others |
Value Chain & Pricing Dynamics
P91 and P92 creep-resistant steels from Japanese and European specialty mills cascade through supercritical pressure part fabrication into tiered OEM pricing structures, with alloy cost volatility compressing margins for fabricators lacking long-term offtake agreements with ASME-certified mills.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for supercritical boiler packages as IPP procurement consolidation intensifies vendor competition. Project-based contract pricing dominates, with differentiation driven by reference plant track record and flue-gas desulfurization integration scope. Cost compression in standardized Benson boiler skids is intensifying because modular designs reduce field welding labor. Captive power operators in Southeast Asia exhibit highest price sensitivity, while central utilities in India prioritize thermal efficiency guarantees over upfront capital.
Supply Chain Analysis
ASME certification requirements for pressure vessel welding gate access to utility procurement channels, concentrating qualified fabrication capacity in Japan, Germany, and South Korea. Supercritical boiler production draws from specialized alloy feedstock, precision forging capabilities, and high-integrity welding consumables. Single-source vulnerability runs through Japanese specialty steel mills supplying P91/P92 grades. Distribution runs through EPC contractors with regional content compliance expertise, particularly in India and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Advanced Utility Boilers Market functions as a stable compounder anchored by regulatory-mandated emission control retrofits across aging coal fleets in the United States and Europe.
For Market Incumbents: Extend aftermarket service reach through digital twin integration to offset unbundling of long-term service agreements by IPP procurement teams. Cement relationships with NTPC and PLN subsidiaries before independent service providers with AI-driven diagnostics capture boiler tuning contracts. Prioritize backward integration into ASME-certified welding capacity to defend against alloy supply concentration risk. For New Entrants and Emerging Players: Balance-of-plant contractors with stator cooling and auxiliary system expertise represent the most penetrable channel for modular HRSG and lower-GWP cooling package insertion. Target green hydrogen blending retrofit specifications in EU member states where ammonia-based alternatives displace conventional refrigerants. Pursue technology licensing arrangements with established Asian manufacturing hubs rather than greenfield certification investment. For Investors and Strategic Acquirers: Consolidation pressure builds where digital twin and predictive maintenance capabilities determine aftermarket revenue capture. The market supports 5-10 year holding periods for pressure-part fabricators with ASME depth and regional EPC contractors with domestic content compliance. Watch carbon border adjustment mechanism implementation as the inflection signal for coal-fired boiler export competitiveness from Vietnam and Indonesia.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Redistributes supercritical design IP to Asian manufacturing hubs seeking reference plant credibility. |
| Backward Integration into Alloy Supply | Captures P91/P92 steel sourcing security for OEMs exposed to Japanese and European mill concentration. |
| Digital Twin Platform Development | Creates aftermarket service expansion paths through physics-based boiler modeling with AI-driven predictive maintenance. |
| Green Hydrogen Co-firing Certification | Opens retrofit markets for gas-fired boilers under EU F-Gas Regulation and national hydrogen strategies. |
| Modular Benson Boiler Skid Standardization | Compresses IPP construction schedules from 36 months to 18 months while decentralizing EPC risk allocation. |
Study Parameters
Coverage spans India, Vietnam, Indonesia, Germany, and the United States, with primary inputs from each market cluster obtained through structured interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Secondary validation draws from EIA data, IEA reports, FERC filings, and project development databases tracking supercritical coal and combined-cycle gas capacity. Bottom-up unit installation counts triangulate against top-down utility capital expenditure disclosures.
Granularity-level modeling operates at boiler type, fuel source, generation capacity tier, and end-user archetype dimensions across the projection horizon. CAGRs derive from regression analysis of historical utility procurement cycles against regulatory compliance deadline clustering. Forecast inputs incorporate EPA MATS implementation timelines, EU F-Gas Regulation phase-down schedules, and India's CEA emission norm enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanism expansion and green hydrogen electrolyzer cost trajectories. Forecasts reflect documented assumptions regarding coal plant retirement schedules and IPP financing availability. A model refresh is warranted upon material change in EU CBAM coverage scope or Vietnamese PDP8 capacity authorization revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fuel Operated Heaters Market
Boilers
US Commercial Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Boiler System Market
Boilers
North America Industrial Boiler Market
Boilers
Power Plant Boiler Market
Boilers
US Industrial Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Watertube Boilers Market
Boilers
Commercial Boiler Market
Boilers
Biomass Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Boiler Control Market
Boilers
Industrial Biomass Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Waste Heat Boiler Market