
 Captive Power Generation Market | 2026-2036
Captive Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Captive Power Generation Market Analysis
India's industrial belt is narrowing the reliability gap between grid supply and manufacturing uptime. Caterpillar Inc. leverages its diesel generator portfolio to serve mining and heavy industry customers across South Asia. Siemens AG anchors its position through turbine technology integration for combined-cycle captive plants. Bharat Heavy Electricals Ltd. dominates domestic coal-based installations with utility-scale engineering adapted for industrial self-generation.
Captive power generation refers to electricity produced by an industrial or commercial entity for its own consumption rather than sale to a public utility, typically employing reciprocating engines, gas turbines, or renewable arrays with capacities ranging from single-digit megawatts to several hundred megawatts. The primary purpose is to ensure supply continuity, manage energy costs, and maintain power quality for processes where grid interruptions cause catastrophic losses. Diesel generators retain the largest installed base among power source categories due to low capital outlay and rapid deployment, though natural gas is gaining share where pipeline infrastructure exists. Solar-biomass hybrid configurations represent the fastest-expanding technology segment as carbon accounting pressures intensify. Peak shaving applications command premium margins by reducing demand charges and grid dependency during tariff spikes.
The EPA enforces emissions limits on diesel and natural gas engines through Tier 4 Final standards, compelling operators toward aftertreatment systems or fuel switching. India's CEA mandates technical standards for grid interconnection and safety protocols at captive plants above threshold capacities. The EU F-Gas Regulation restricts fluorinated greenhouse gases in cooling systems used within combined-cycle installations. Stakeholders must monitor evolving carbon border mechanisms and local air quality mandates to determine whether retrofitting existing assets or greenfield renewable investments offer superior lifecycle economics.
Market Dynamics
Steel mills and chemical clusters across India are accelerating captive installations to escape grid volatility, while EPA Tier 4 Final emissions rules force diesel operators toward aftertreatment retrofits or fuel switching.
Growth Catalysts
- India's PLI scheme for manufacturing:Production-linked incentives accelerate capital deployment into on-site generation capacity across Gujarat's industrial corridor. Textile and chemical processors capture subsidies for baseload self-supply installations.
- Solar-biomass hybrid configurations:Carbon accounting pressures from EU carbon border adjustment mechanisms drive fastest-expanding technology adoption. Industrial facilities integrate dual-fuel arrays to hedge fuel price volatility.
- Peak shaving applications:Demand charge reduction economics command premium margins for reciprocating engine deployments. Mining and heavy industry operators reduce grid dependency during tariff spikes.
Market Restraints
- Natural gas pipeline infrastructure gaps:Pipeline network concentration limits gas turbine adoption to coastal industrial zones. Interior manufacturing clusters remain locked into diesel reciprocating engines.
- Aftertreatment system capex burden:EPA Tier 4 Final compliance adds capital intensity to diesel generator lifecycle economics. Smaller industrial operators defer replacement cycles.
- Grid interconnection technical standards:India's CEA mandates impose compliance costs and timeline delays for captive plants above threshold capacities. Permitting friction constrains rapid deployment.
Strategic Opportunities
- EU carbon border adjustment mechanism:Export-facing Indian steel and aluminum producers face embedded carbon penalties. Captive renewable installations secure green accreditation for EU market access.
- Combined-cycle turbine integration:Siemens AG technology anchors position through waste heat recovery configurations. Efficiency gains from converging gas turbine and steam cycle technologies displace simple-cycle diesel.
- Digital remote monitoring platforms:Predictive maintenance contracts unlock recurring revenue streams. Equipment OEMs capture aftermarket value through sensor-enabled service subscriptions.
Industry Challenges
- Grid synchronization engineering scarcity:Specialized power systems engineers capable of CEA-compliant interconnection design command wage premiums. Talent pipeline constraints delay project commissioning.
- Dual-fuel control system integration:Legacy diesel assets require control architecture overhaul for solar-diesel hybrid operation. Retrofit complexity extends downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Captive Power Generation Market |
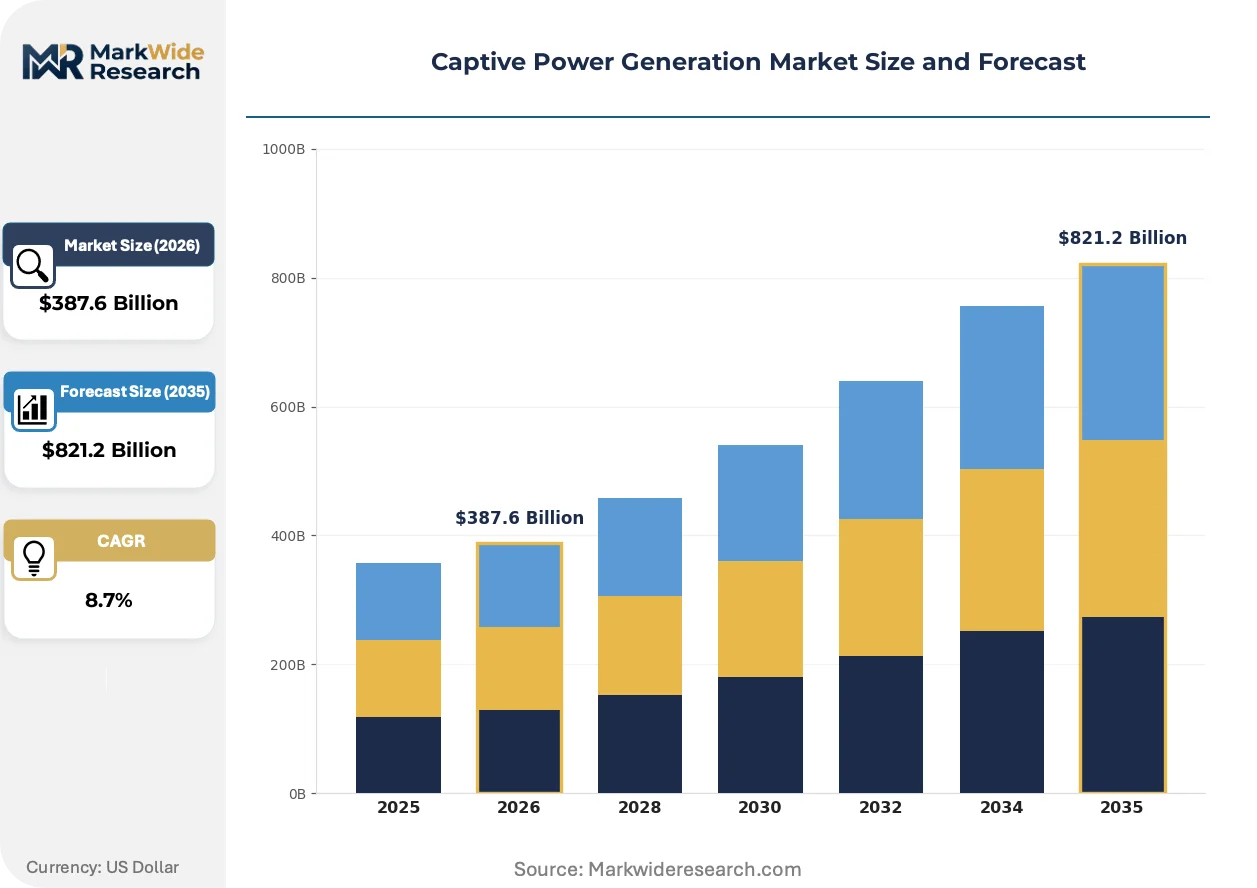
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Diesel Generators, Natural Gas, Coal, Renewable Sources Technology: Combined Cycle, Turbine Technology, Solar Power, Biomass End User: Manufacturing, Mining, Commercial, Industrial Application: Grid Support, Standalone Operations, Backup Power, Peak Shaving |
| Companies Covered | Caterpillar Inc., Cummins Inc., General Electric Company, Bharat Heavy Electricals Ltd., MAN Energy Solutions SE, Siemens AG, Mitsubishi Heavy Industries Ltd., Jindal Steel and Power Ltd., Wärtsilä Oyj Abp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Captive Power Generation Market Emerging Trajectories
Digitization of asset performance management is compressing maintenance cycles and enabling outcome-based service contracts across industrial power fleets.
Advanced sensor arrays and edge computing platforms are digitizing condition monitoring for reciprocating engines and gas turbines. Mining operators in Australia's Pilbara region deploy real-time vibration analysis to shift from calendar-based to predictive maintenance. This capability is digitizing service revenue models toward availability guarantees.
The EU F-Gas Regulation restricts fluorinated greenhouse gases in cooling systems used within combined-cycle installations. Industrial operators face refrigerant retrofit mandates or technology replacement decisions. Combined-cycle plants in Germany and the Netherlands accelerate absorption chiller adoption to maintain cooling capacity.
Steel mills and petrochemical complexes are unbundling equipment procurement from long-term service agreements. Buyers negotiate separate capex and opex contracts to optimize total cost of ownership visibility. This pattern concentrates in India's western industrial corridor where project finance structures favor transparent cost segregation.
Captive Power Generation Market Segmentation
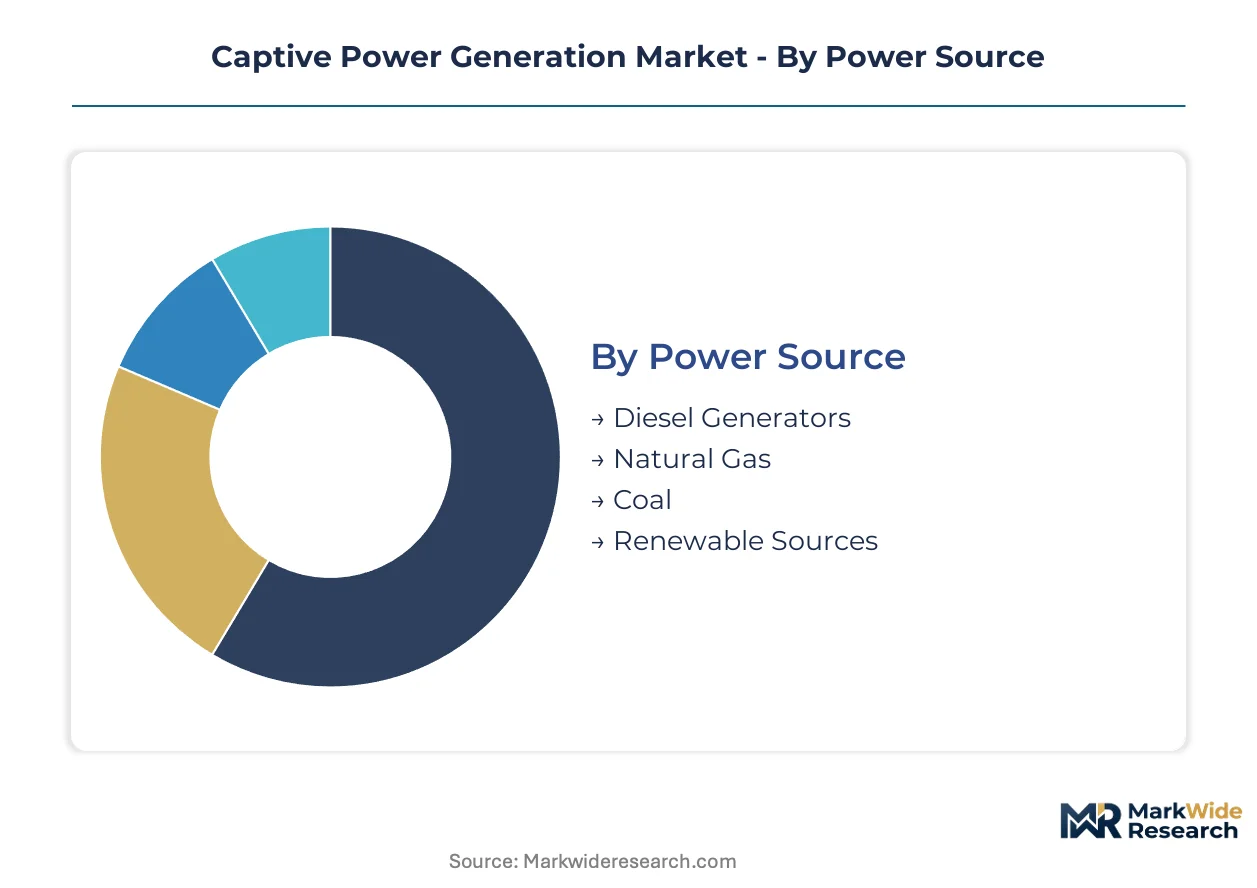
Captive power segmentation reveals divergent capital intensity and operational flexibility across fuel types and technology architectures. Steel mills in Gujarat and mining operators in Australia's Pilbara deploy distinct configurations based on grid proximity and emissions exposure.
Power Source:
Cost tier differentiation separates rapid-deployment options from infrastructure-dependent baseload investments.
- Diesel Generators:Reciprocating engines deliver sub-10 MW modular capacity with minimal site preparation. Mining camps and remote textile clusters in India's interior rely on these assets where pipeline infrastructure remains absent.
- Natural Gas:Gas turbines achieve thermal efficiencies above 40 percent in combined-cycle configurations. Demand concentrates along coastal industrial corridors where pipeline networks terminate, particularly Gujarat's chemical processing belt.
- Coal:Pulverized fuel boilers anchor utility-scale engineering adapted for cement and aluminum smelters. Domestic resource availability in India's eastern states sustains this segment despite carbon accounting pressures.
- Renewable Sources:Solar-biomass hybrid arrays displace fossil backup in export-facing manufacturing. EU carbon border adjustment mechanisms accelerate deployment across European-integrated supply chains.
Diesel Generators holds installed capacity. Renewable Sources is rotating up the share rankings.
Technology:
Application requirements dictate technology selection from simple-cycle backup to integrated heat recovery systems.
- Combined Cycle:Converging gas turbine and steam cycle technologies extract waste heat for process steam or absorption cooling. Siemens AG anchors this segment through turbine integration for petrochemical complexes.
- Turbine Technology:Simple-cycle gas turbines serve peaking and grid support functions with sub-15 minute start capability. Peak shaving applications in South Asian manufacturing clusters favor this architecture for tariff arbitrage.
- Solar Power:Photovoltaic arrays with battery storage displace daytime diesel consumption in remote industrial facilities. Rajasthan's solar irradiance attracts textile processors seeking renewable baseload.
- Biomass:Agricultural residue combustion serves sugar mills and food processing with captive fuel supply. India's bagasse-fired cogeneration dominates this segment with established feedstock logistics.
Combined Cycle commands premium margins. Solar Power is climbing the fastest on capacity additions.
End User:
Customer type determines reliability requirements and fuel switching flexibility across industrial categories.
- Manufacturing:Continuous process industries including steel, cement, and chemicals require uninterrupted baseload supply. Gujarat's industrial corridor concentrates demand for multi-fuel captive plants.
- Mining:Remote extraction operations depend on modular diesel and hybrid renewable configurations. Australia's iron ore producers deploy sensor-enabled predictive maintenance across dispersed power fleets.
- Commercial:Data centers and healthcare facilities prioritize power quality and seamless transfer switching. Urban installations face air quality mandates that restrict diesel runtime.
- Industrial:Heavy fabrication and assembly operations balance capital constraints against uptime requirements. Peak shaving economics attract this segment where demand charges dominate utility bills.
Manufacturing anchors capacity deployment. Mining is rotating up the share rankings.
Application:
Volume requirements and grid interdependency shape architecture selection across operational modes.
- Grid Support:Synchronized captive plants provide frequency regulation and reactive power compensation. India's CEA mandates technical standards for grid interconnection above threshold capacities.
- Standalone Operations:Islanded microgrids serve locations where utility infrastructure remains uneconomic. Remote mining and processing facilities in Australia's interior deploy this architecture exclusively.
- Backup Power:Emergency diesel systems activate within 10 seconds of grid failure for critical processes. Pharmaceutical and semiconductor cleanrooms mandate this redundancy tier.
- Peak Shaving:Reciprocating engines reduce grid dependency during tariff spikes and demand charge assessment windows. Textile processors in Tamil Nadu capture arbitrage value through scheduled engine operation.
Backup Power holds installed capacity. Peak Shaving is expanding most quickly on margin attraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA anchors the regulatory framework for the most active geography. Steel mills and chemical clusters across the subcontinent are accelerating captive installations to escape grid volatility. The analysis spans five countries where industrial self-generation concentrates.
India
Textile processors and aluminum smelters drive capacity additions across Gujarat's industrial corridor. The country's PLI scheme for manufacturing accelerates capital deployment into on-site generation. Mundra and Hazira port zones concentrate multi-fuel captive plants serving export-facing chemical clusters.
China
Cement producers and steel complexes deploy pulverized fuel boilers amid dual carbon goals pressure. The country's MIIT enforces efficiency standards for industrial power systems. Shandong Peninsula hosts the densest concentration of coal-based captive installations with utility-scale engineering.
United States
Data centers and semiconductor fabs prioritize power quality and seamless transfer switching. The EPA enforces Tier 4 Final emissions limits on diesel and natural gas engines. Texas's Permian Basin oilfield operations deploy modular reciprocating engines where pipeline infrastructure remains absent.
Germany
Petrochemical complexes accelerate absorption chiller adoption to maintain cooling capacity under F-Gas Regulation constraints. The EU carbon border adjustment mechanism pressures export-facing manufacturers toward renewable accreditation. Ruhr industrial belt operators integrate combined-cycle waste heat recovery for process steam.
Australia
Iron ore producers in the Pilbara region deploy sensor-enabled predictive maintenance across dispersed power fleets. The country's national energy regulator mandates technical standards for remote microgrid interconnection. Queensland mining camps rely exclusively on islanded diesel and hybrid renewable configurations.
Captive Power Generation Market Vendor Landscape
Engine specialists and turbine integrators split the market into distinct capability tiers. The structure concentrates around OEMs with in-house manufacturing depth and aftermarket service networks. Equipment fabricators and digital service providers represent the dominant archetypes. Capacity expansion and technology licensing constitute the primary competitive moves as participants defend position against renewable disruptors.
Within the engine fabrication tier, Caterpillar Inc. and Cummins Inc. exemplify the reciprocating engine specialists with established mining and heavy industry presence. Siemens AG occupies a position among turbine integrators serving combined-cycle configurations. Bharat Heavy Electricals Ltd. anchors the domestic engineering segment with utility-scale adaptations for industrial self-generation.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| General Electric Company |
| Bharat Heavy Electricals Ltd. |
| MAN Energy Solutions SE |
| Siemens AG |
| Mitsubishi Heavy Industries Ltd. |
| Jindal Steel and Power Ltd. |
| Wärtsilä Oyj Abp |
| Others |
Supply Flow & Price Mechanics
Hazira-Mundra freight corridors carry turbine components and reciprocating engine blocks from Gujarat's port zones to interior manufacturing clusters, with logistics cost differentials of 15-20 percent between coastal and hinterland delivery points concentrating pricing power among suppliers with established distribution networks. This geographic cost wedge feeds into three-tier pricing structures that separate premium combined-cycle integrators from standard diesel generator assemblers and economy-tier refurbished equipment dealers.
Pricing Analysis
Price spreads between coastal Gujarat and interior Maharashtra captive plants reach 12-18 percent for equivalent gas turbine configurations, reflecting pipeline proximity premiums and grid interconnection cost differentials. Contract-based long-term offtake agreements dominate above 50 MW installations, while modular diesel deployments favor per-kW transactional pricing with 90-day delivery windows. Price differentiation hinges on EPA Tier 4 Final certification tier and after-sales service bundling, with carbon-accounting-compliant hybrid arrays commanding 25-30 percent premiums over conventional diesel. Cost compression in the economy tier is intensifying as Chinese engine imports displace domestic fabrication, while mining operators in Australia's Pilbara demonstrate lowest price sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Export control regimes under Wassenaar Arrangement restrictions limit gas turbine blade casting technology transfers to Indian joint ventures, constraining localization of precision components. Manufacturing concentration centers on Germany for turbine engineering, China for auxiliary electrical systems, and India for structural fabrication and site assembly. Raw material dependencies span high-temperature alloys from Japan, power electronics from South Korea, and cooling system refrigerants subject to EU F-Gas Regulation phase-down schedules. Single-source vulnerability concentrates in precision casting for hot gas path components, where two German suppliers control 70 percent of global capacity. Distribution runs through original equipment manufacturer direct sales for large projects and authorized dealer networks for sub-10 MW modular deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive power generation is accelerating through a technology inflection as solar-biomass hybrid configurations displace diesel baseload under EU carbon border adjustment pressure. India's PLI scheme for manufacturing compresses payback periods for renewable integration, reshaping competitive positioning toward carbon-accounting-compliant suppliers.
For Market Incumbents: Build switching-cost moats through predictive maintenance platform subscriptions that embed sensor-enabled service contracts. Anchor turbine technology integration positions by securing CEA-compliant grid interconnection engineering talent pools in Gujarat and Maharashtra. Defend against renewable disruptors by acquiring solar EPC capabilities and dual-fuel control system integrators. Prioritize certification investment for EU carbon border adjustment mechanism accreditation to capture export-facing steel and aluminum producer demand.
For New Entrants and Emerging Players: Interior Tamil Nadu and Karnataka textile belts present underpenetrated demand for peak shaving reciprocating engine deployments where grid volatility exceeds 15 percent annual downtime. Target mining operators in Queensland's untapped copper extraction zones with containerized hybrid renewable microgrids. Enter through power-as-a-service leasing models that eliminate capital intensity barriers for mid-scale manufacturing facilities.
For Investors and Strategic Acquirers: Digital remote monitoring platform specialists with established mining sector footprints represent priority acquisition targets as predictive maintenance contracts displace transactional equipment sales. Long-term viability favors asset-light technology licensors over capital-intensive fabricators. Monitor EPA enforcement discretion on Tier 4 Final compliance timelines as the critical inflection signal—delayed mandates would extend diesel generator cash flows, while accelerated enforcement would compress retrofit economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Combined-Cycle Capacity Buildout | Siemens AG turbine integration captures waste heat recovery premiums in Gujarat petrochemical corridors. |
| Solar-Biomass Hybrid Certification | EU carbon border adjustment mechanism compliance secures green accreditation for export-facing Indian steel mills. |
| Predictive Maintenance Platform Launch | Sensor-enabled subscriptions transform transactional equipment sales into recurring availability guarantee revenue. |
| Backward Integration into Casting | In-house production of hot gas path components mitigates German supplier concentration risk for turbine OEMs. |
| CEA Interconnection Engineering Acquisition | Grid synchronization capability scarcity commands wage premiums and delays project commissioning without captive talent. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA industrial energy consumption reports, FERC interconnection filings, and CEA technical standards documentation. The analysis draws from structured interviews with captive plant engineering directors, EPC contractor procurement leads, grid operator interconnection specialists, and aftermarket service managers. Bottom-up capacity installation tracking across India's western industrial corridor triangulates against top-down national energy demand projections.
Forecast inputs incorporate fuel source segmentation, generation capacity tier thresholds, project scale brackets, and regional regulatory framework differentials across the analysis window. Modeled outputs reflect CAGRs derived from installation run-rate trending, policy incentive elasticity estimates, and carbon accounting compliance cost trajectories. Industry-specific inputs include PLI scheme subsidy utilization rates and EU carbon border adjustment mechanism implementation phasing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese engine exporters or accelerated EPA enforcement would shift outcomes. Material shifts in India's CEA interconnection mandates or EU F-Gas Regulation refrigerant phase-down timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
South America Thermal Power Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
East Africa Power Market
Power Generation
Peaking Power Plant Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Europe Thermal Power Market
Power Generation
India Thermal Power Plant Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Hydrogenerators Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Solar Generator Market