
 Residential Boiler Market | 2026-2036
Residential Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Boiler Market Analysis
Aftermarket service revenue is tilting toward connected diagnostics and predictive maintenance contracts as manufacturers seek recurring income beyond unit sales. Bosch Thermotechnology leverages its European installed base to sustain long-term service agreements. Viessmann anchors its competitive stance through deep specialization in condensing systems and heat pump hybrids. A.O. Smith competes aggressively in North American replacement cycles through extensive contractor channel control.
A residential boiler is a closed-vessel heating appliance that generates hot water or steam for space heating and domestic hot water supply, typically operating at pressures below 160 psig and temperatures up to 250°F through combustion of fossil fuels or electrical resistance. Combi boilers lead volume in urban retrofits where space constraints eliminate separate hot water tanks, while biomass boilers occupy a premium niche in rural districts with localized fuel supply chains. Gas-fired technology dominates installed capacity across temperate climates, though electric segments accelerate in markets with aggressive grid decarbonization mandates.
The EPA regulates residential boiler emissions through New Source Performance Standards under the Clean Air Act, while the EU F-Gas Regulation and Ecodesign Directive constrain refrigerant choices and minimum efficiency thresholds. The DOE enforces federal minimum efficiency standards that phase out non-condensing designs in the United States. Stakeholders must monitor evolving carbon-border adjustments and building-performance standards that will reshape procurement criteria and product certification requirements.
Market Dynamics
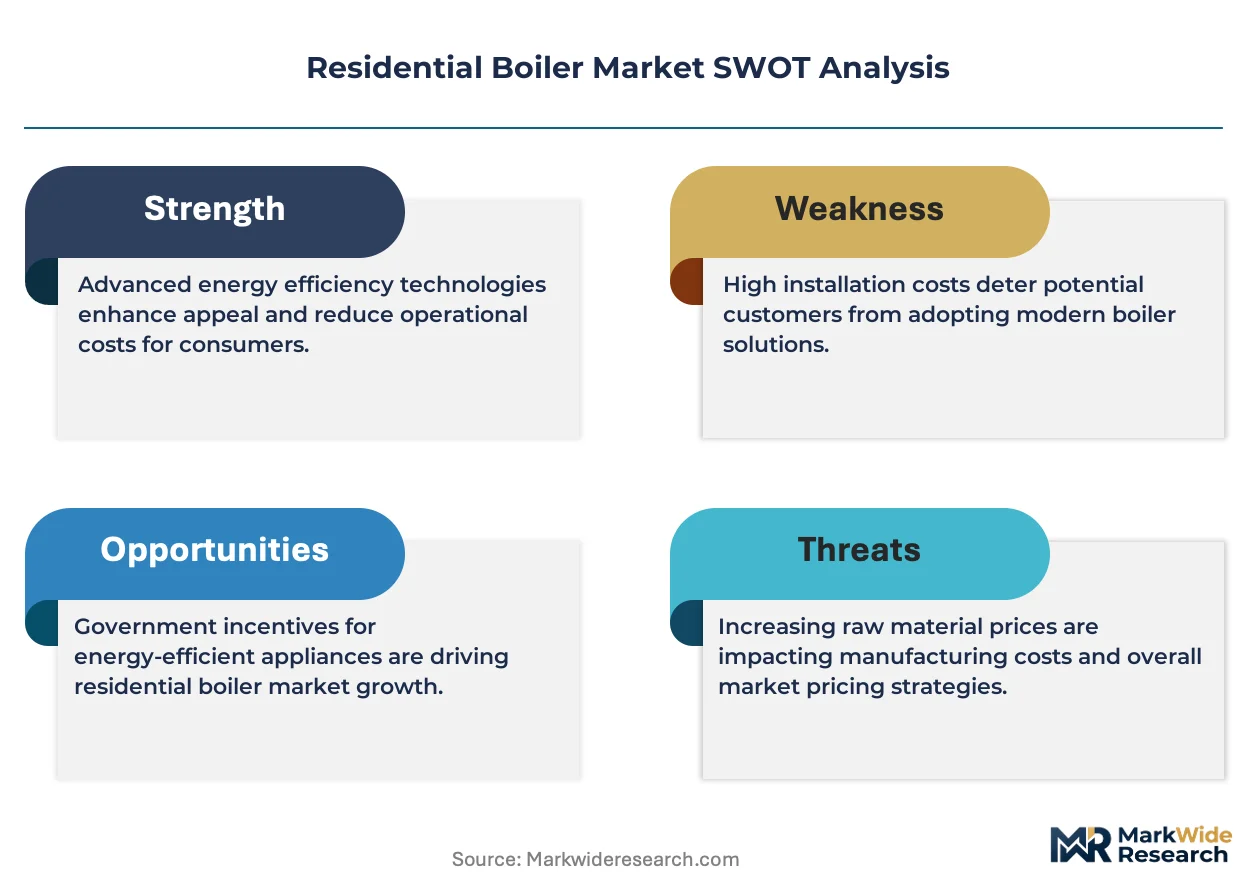
Condensing technology mandates and low-NOx combustion standards are compressing product lifecycles while forcing manufacturers to absorb R&D costs ahead of replacement demand curves. The regulatory acceleration in Germany, the United States, and China is eliminating non-compliant inventory faster than historical upgrade cycles.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds are phasing out conventional atmospheric boilers across member states, forcing replacement demand into condensing systems.
- Heat pump hybrids:Dual-source configurations are capturing renovation projects where full electrification faces grid capacity constraints or legacy radiator incompatibility.
- Urban retrofit density:Combi boiler formats are penetrating multi-unit housing stock in Germany and the United Kingdom where space constraints eliminate separate hot water storage.
Market Restraints
- Copper and stainless steel input volatility:Heat exchanger material costs swing with commodity markets, compressing margin visibility for manufacturers on fixed-price contracts.
- Installation labor scarcity:Certified condensing boiler technicians concentrate in Western European and North American metropolitan corridors, creating service backlogs in secondary markets.
- Electrical resistance substitution:Grid-decarbonized markets are accelerating electric heating adoption where gas infrastructure retrofit costs exceed full-fuel-switch economics.
Strategic Opportunities
- Predictive maintenance platforms:Connected diagnostics contracts are converting one-time equipment sales into recurring revenue streams anchored to installed base longevity.
- Rural biomass clusters:Localized pellet supply chains in Central European and North American forest regions support premium boiler positioning outside gas grid coverage.
- DOE federal efficiency standards:Upcoming phase-outs of non-condensing designs in the United States are compressing replacement windows ahead of compliance deadlines.
Industry Challenges
- Condensing system commissioning complexity:Flue gas analysis and condensate drainage requirements demand specialized training that contractor networks lack at scale.
- Legacy control integration:Smart thermostat compatibility gaps force costly bridge installations or full system replacements in older housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Boiler Market |
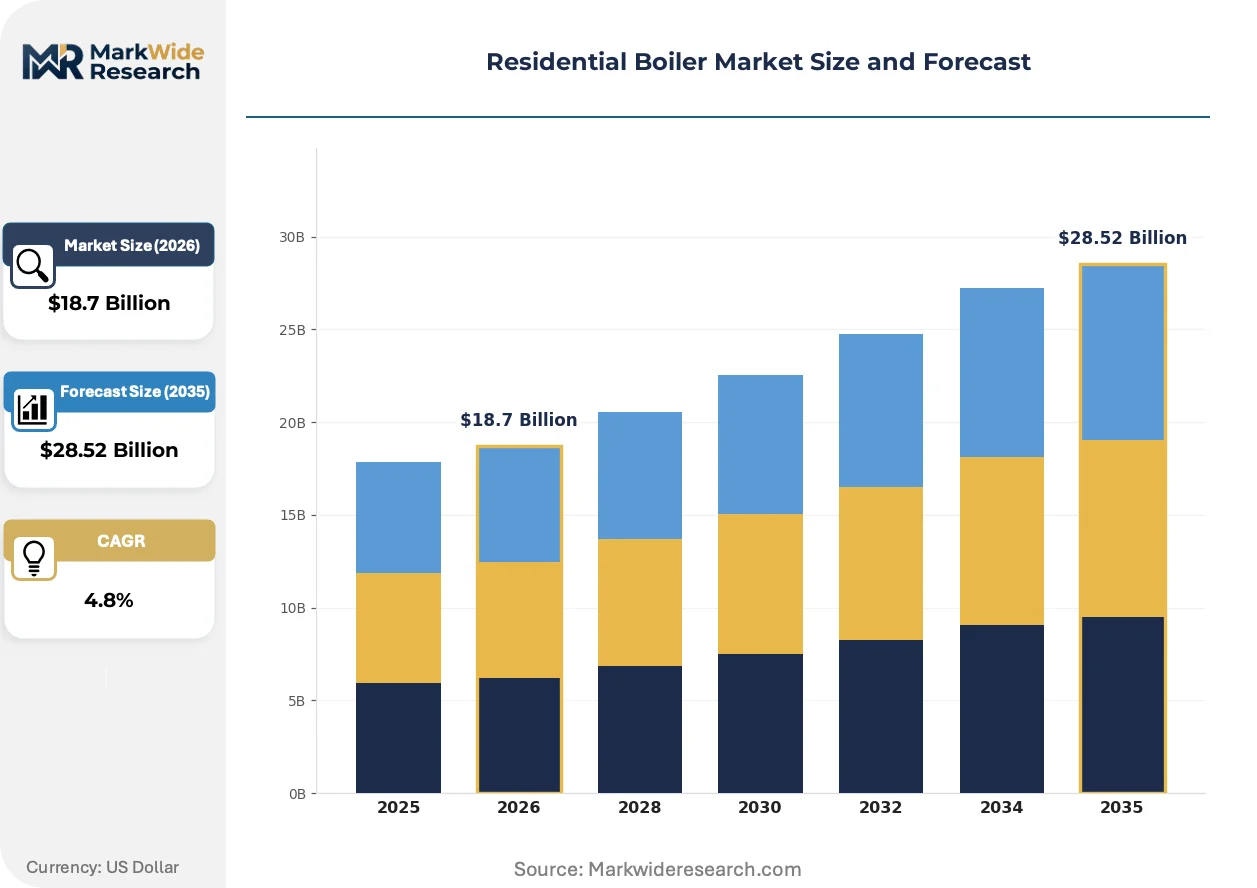
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combi Boilers, System Boilers, Conventional Boilers, Biomass Boilers Technology: Gas-Fired, Oil-Fired, Electric, Solar Thermal End User: Homeowners, Tenants, Property Managers, Contractors Installation Type: New Installations, Replacement, Upgrades, Retrofitting |
| Companies Covered | BDR Thermea Group, Navien, Bosch Thermotechnology, Weil-McLain, Lochinvar, Viessmann, Ariston Holding, A.O. Smith, Vaillant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Boiler Market Emerging Trajectories
Product architecture is compressing around hybrid heat sources and connected service models, while regulatory timing is compressing replacement windows. The intersection of hardware efficiency mandates and software-enabled longevity is redefining manufacturer-customer relationships.
Condensing combustion technology is collapsing the distinction between space heating and domestic hot water efficiency ratings. Homeowners in Germany and the United Kingdom are adopting integrated systems that eliminate separate tank losses. The technology is collapsing product category boundaries as manufacturers reposition single appliances against full-system replacements.
EPA New Source Performance Standards under the Clean Air Act are tightening NOx emission limits for residential gas-fired equipment. Manufacturers are redesigning burner geometries and combustion control algorithms to maintain output ratings within stricter bounds. The United States market is responding with pre-compliance inventory builds and accelerated certification timelines ahead of enforcement dates.
Service contract unbundling is fragmenting the traditional equipment-plus-installation bundle. Contractors in North America are separating hardware procurement from ongoing maintenance, creating transparent lifecycle cost comparisons. This pattern concentrates in replacement-driven markets where homeowner decision cycles have shortened to single heating seasons.
Residential Boiler Market Segmentation
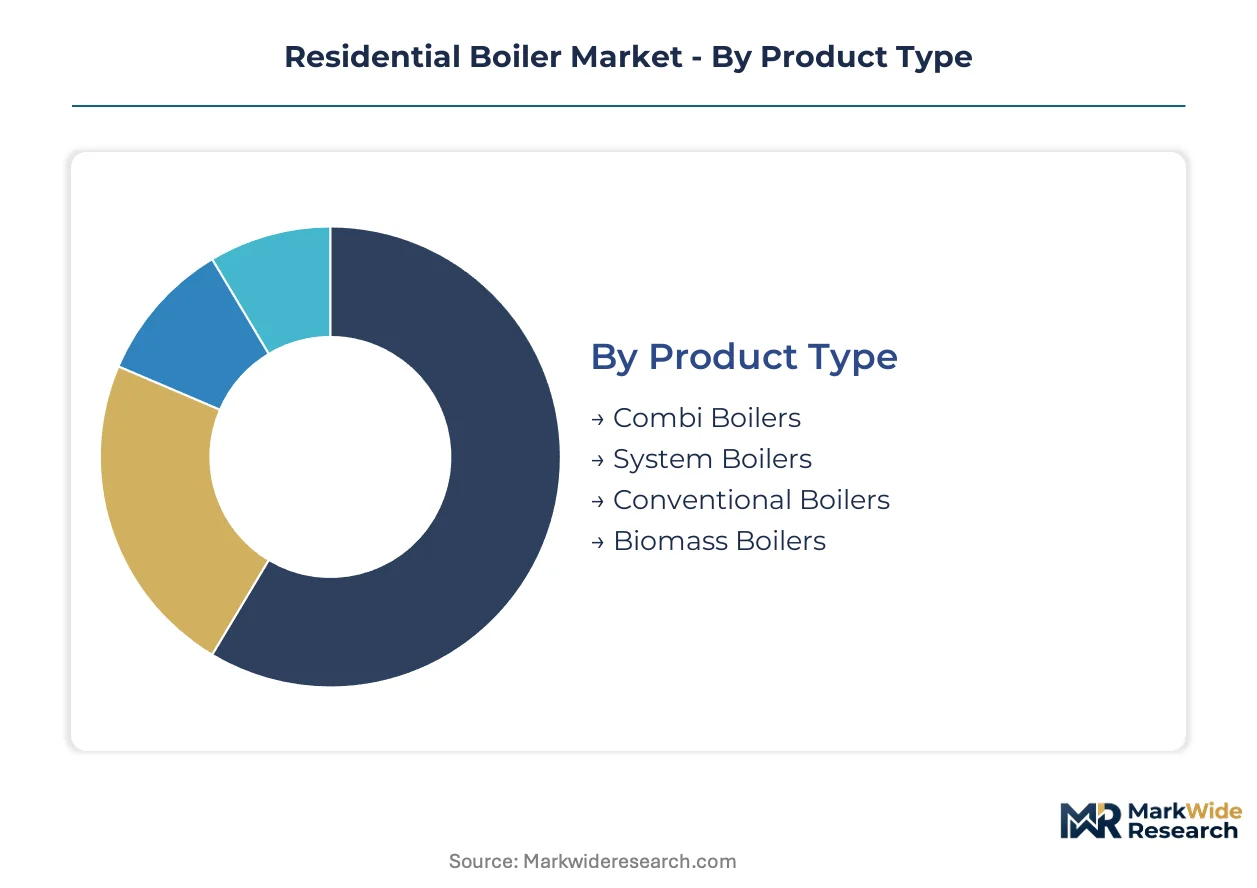
Segmentation in the residential boiler market determines service contract structures and lifetime value calculations. Manufacturers align warranty terms and predictive maintenance offerings to the distinct operational profiles of each category.
Product Type:
After-sales-service intensity varies dramatically across boiler formats, with combi and system units commanding premium diagnostic subscriptions due to integrated component complexity.
- Combi Boilers:Integrated appliances deliver both space heating and domestic hot water through a single compact unit, eliminating storage tank requirements. Demand concentrates in German and United Kingdom urban retrofits where apartment footprints restrict mechanical room sizing and homeowners prioritize space reclamation.
- System Boilers:These units heat water for central heating while storing hot water in a separate cylinder, maintaining compatibility with legacy radiator systems. Property managers in United States multi-family housing favor this format for its balanced efficiency and simplified maintenance scheduling across rental portfolios.
- Conventional Boilers:Traditional heat-only designs requiring separate cold water tanks and hot water cylinders persist in rural United Kingdom properties with existing gravity-fed plumbing infrastructure.
- Biomass Boilers:Pellet and wood-chip combustion systems serve off-grid German and Austrian forest-region homes with localized fuel supply chains.
By volume, combi boilers lead. By growth pace, biomass boilers are climbing the fastest in decarbonization-driven rural clusters.
Technology:
Cost tier stratification separates premium condensing gas systems from economy electric resistance units, with solar thermal occupying a narrow premium niche.
- Gas-Fired:Natural gas and liquefied petroleum gas combustion systems dominate temperate-climate installed capacity through mature distribution infrastructure. German homeowners under the EU Ecodesign Directive are accelerating replacement of atmospheric models with condensing alternatives ahead of compliance deadlines.
- Electric:Resistance and electrode boiler technologies are gaining share in French and Norwegian markets where grid decarbonization and nuclear or hydroelectric baseload eliminate fossil fuel combustion emissions.
- Oil-Fired:Kerosene and heating oil systems persist in rural United States Northeast and Irish properties beyond natural gas grid reach.
- Solar Thermal:Evacuated tube and flat-plate collector systems supplement conventional boilers in Mediterranean European single-family renovations with favorable insolation profiles.
Gas-fired technology retains volume leadership. Electric segments are expanding most quickly in markets with aggressive building electrification mandates.
End User:
Customer type determines procurement authority and decision-cycle length, with homeowners driving specification while contractors control installation channel access.
- Homeowners:Owner-occupiers make final equipment selections based on lifecycle cost calculations and available retrofit subsidies. This segment is accelerating fastest in Germany and the United States as energy-efficiency mandates tighten and replacement windows compress.
- Property Managers:Multi-unit residential portfolio operators standardize across assets to simplify maintenance contractor relationships and spare parts inventory.
- Tenants:Rental occupants influence landlord decisions indirectly through comfort complaints and utility cost concerns in metered-billing arrangements.
- Contractors:Installation professionals steer product selection through stocking agreements and manufacturer incentive programs in North American replacement markets.
Homeowners dominate absolute unit demand. Property managers are gaining share fastest through institutional rental housing expansion.
Installation Type:
Application context separates new construction specification from replacement urgency, with retrofitting presenting the most complex engineering challenges.
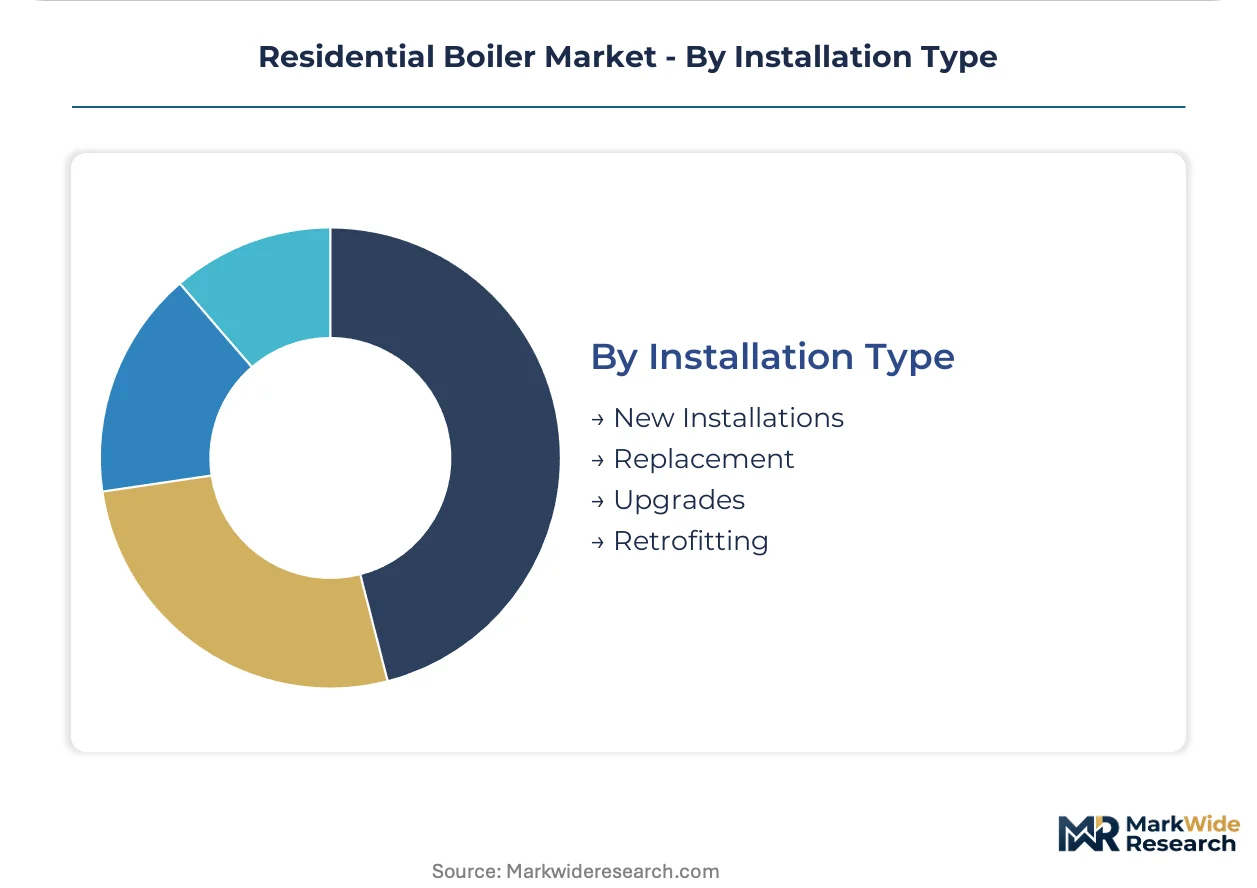
- Replacement:Like-for-like swaps of failed or end-of-life units drive the majority of transactions in mature United States and Western European housing stock with aging boiler populations.
- New Installations:First-fit equipment in residential construction concentrates in German and Chinese greenfield developments where building codes mandate condensing technology from project inception.
- Upgrades:Efficiency-improving retrofits of functional systems are accelerating in United Kingdom properties ahead of proposed fossil fuel heating phase-out dates.
- Retrofitting:Fuel-switching conversions from oil to gas or gas to electric involve flue modifications, pipe rerouting, and control system integration in older housing stock.
Replacement installations lead by volume. Retrofitting projects are expanding most quickly as decarbonization policies force fuel-switching economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across markets. German buyers accept premium condensing systems under regulatory pressure, while United States replacement cycles remain price-sensitive until failure forces action. Chinese urban retrofits prioritize compact formats over efficiency premiums.
United States
Replacement urgency dominates the Northeast and Midwest where aging oil-fired systems face natural gas conversion economics. The DOE enforces federal minimum efficiency standards that phase out non-condensing designs ahead of state-level building code adoptions. Chicago and Detroit metropolitan corridors concentrate contractor networks trained in condensing system commissioning.
Germany
Building stock renovation cycles and the EU Ecodesign Directive compress replacement windows into multi-year compliance waves. The F-Gas Regulation constrains refrigerant choices in heat pump hybrids that supplement gas-fired systems. Bavarian and Baden-Württemberg industrial clusters anchor condensing boiler manufacturing and service infrastructure.
China
Urban retrofit density in tier-one cities drives combi boiler penetration where apartment footprints eliminate hot water tank options. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate building electrification pilots in Beijing and Shanghai. Yangtze River Delta manufacturing bases supply compact heat exchanger components for domestic and export markets.
United Kingdom
Proposed fossil fuel heating phase-out dates accelerate efficiency-improving retrofits of functional systems ahead of compliance deadlines. The Building Regulations Part L mandates condensing technology in replacement installations across England and Wales. London and Southeast England concentrate property management portfolios standardizing system boiler formats across rental assets.
France
Grid decarbonization and nuclear baseload position electric resistance boilers competitively against gas alternatives in new construction. The RE2020 environmental regulation mandates low-carbon heating in residential buildings. Île-de-France and Auvergne-Rhône-Alpes regions concentrate heat pump hybrid adoption where radiator compatibility limits full electrification.
Residential Boiler Market Vendor Landscape
Capability concentration sits with European specialists commanding condensing system expertise; scale advantage sits with North American players controlling replacement channel access. The vendor base separates into three tiers: integrated heating conglomerates with full-system portfolios, regional fabricators with contractor loyalty, and emerging electric heating specialists. Consolidation pressure concentrates among mid-scale European manufacturers facing R&D cost absorption. Dominant competitive moves include technology licensing agreements for low-NOx combustion control and backward integration into heat exchanger materials.
Within the integrated conglomerate tier, Bosch Thermotechnology and Viessmann exemplify deep specialization in condensing architectures and service contract anchoring. A.O. Smith occupies a position representing North American replacement market channel control. These three entities illustrate divergent geographic anchoring strategies: European regulatory compliance leadership versus North American contractor network density.
| Leading Market Players |
|---|
| BDR Thermea Group |
| Navien |
| Bosch Thermotechnology |
| Weil-McLain |
| Lochinvar |
| Viessmann |
| Ariston Holding |
| A.O. Smith |
| Vaillant Group |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta heat exchanger manufacturing clusters anchor global component supply, translating concentrated foundry capacity into asymmetric pricing power for stainless steel and copper alloy fabricators serving condensing boiler assemblers.
Pricing Analysis
Predictive maintenance contracts and extended service agreements generate lifetime value that exceeds original equipment margins by multiples. Three-tier pricing structure across premium condensing, standard efficiency, and economy replacement tiers separates buyers by certification grade and after-sales bundling intensity. Cost compression in economy tiers is intensifying because commodity input volatility compresses margin visibility on fixed-price contracts. Homeowners in replacement-driven markets exhibit highest price sensitivity, while property managers standardizing across portfolios accept premium positioning for simplified maintenance scheduling.
Supply Chain Analysis
Contract manufacturing concentrates with specialized heat exchanger fabricators in Germany, China, and Italy holding captive capacity for condensing system OEMs. Raw material dependencies center on copper tube stock, stainless steel sheet, and precision burner assemblies sourced from metals processors in Eastern Europe and East Asia. Single-source vulnerability in low-NOx combustion control modules creates chokepoint exposure as regulatory deadlines compress certification timelines. Distribution runs through authorized contractor networks in North America and dedicated heating wholesalers in Western Europe, with direct-to-installer platforms gaining share in urban retrofit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among institutional property managers and multi-unit portfolio operators, fragmenting procurement authority away from individual homeowners and compressing manufacturer margins through standardized specification and volume aggregation.
For Market Incumbents: Pre-empt margin erosion by anchoring service contract penetration before equipment failure forces replacement decisions. Backward integration into heat exchanger materials secures supply continuity against copper and stainless steel volatility. Deepen condensing system commissioning training networks to capture installation labor scarcity as a competitive moat against emerging electric heating specialists. For New Entrants and Emerging Players: Pursue rural biomass boiler clusters in Central European forest regions where localized pellet supply chains insulate against gas grid dependency and create defensible positioning outside incumbent service infrastructure. Target United Kingdom retrofitting urgency ahead of proposed fossil fuel heating phase-out deadlines. Lead with hybrid heat pump compatibility to exploit radiator incompatibility barriers blocking full electrification in legacy housing stock. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connected diagnostics platforms converting hardware sales into recurring revenue streams. Long-term viability over the next decade hinges on regulatory compliance timing across German, United States, and Chinese enforcement waves. Acquisition targets should display installed base density enabling predictive maintenance contract anchoring. Monitor EPA New Source Performance Standards enforcement dates and EU Ecodesign Directive compliance windows as inflection indicators for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Condensing Technology Certification | EPA and EU Ecodesign mandates eliminate non-compliant inventory ahead of enforcement deadlines. |
| Heat Pump Hybrid Development | Dual-source configurations capture radiator-incompatible renovations where full electrification fails. |
| Predictive Maintenance Platform Launch | Connected diagnostics convert one-time equipment sales into recurring service revenue streams. |
| Contractor Network Expansion | Channel control in North American replacement markets steers product selection through stocking agreements. |
| Heat Exchanger Backward Integration | Captive supply of copper and stainless steel components insulates margin against commodity volatility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with heating equipment procurement managers, certified installation contractors, property management portfolio directors, and aftermarket service technicians. Secondary validation drew from DOE efficiency standard filings, EPA emission compliance databases, EU Ecodesign Directive implementation reports, and trade customs data for heat exchanger component flows. Bottom-up unit shipment estimates triangulated against top-down replacement cycle modeling across the analysis window.
Calibration against historical replacement patterns and regulatory phase-out timelines shaped the analytical framework. Segmentation dimensions modeled include product type, combustion technology, end-user category, and installation context across the projection horizon. CAGRs were derived from fitted growth curves incorporating efficiency mandate acceleration, building stock age distributions, and fuel-switching economics. Forecast inputs included commodity price sensitivity bands and certified technician availability constraints.
Sensitivities concentrate around EPA enforcement timing, EU carbon-border adjustment implementation, and grid decarbonization pace in key markets. Forecasts reflect assumptions on regulatory adherence rates and contractor training scalability that may shift with policy acceleration or delay. Quarterly review of compliance deadline announcements, heat exchanger material spot prices, and installation backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Water Tube Industrial Boiler Market
Boilers
Boiler System Market
Boilers
Boiler Combustion Chamber Market
Boilers
Field Erected Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Industrial Boiler MRO Market
Boilers
Industrial and Residential Heating Market
Boilers
Boiler Control Solutions Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Oil-Fired Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
Combi Boiler Market
Boilers
North America Residential Boiler Market
Boilers
Boiler Control Market
Boilers
GCC Electric Water Heater Market