
 Coal-Saving Combustion-Supporting Agent Market | 2026-2036
Coal-Saving Combustion-Supporting Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Coal-Saving Combustion-Supporting Agent Market Insights
A shift from single-source chemical procurement to multi-supplier qualification programs is repositioning how industrial buyers secure combustion-supporting agents. BASF SE leverages its global manufacturing footprint to supply standardized additive packages across European power plants. Koppers Inc. anchors its position through deep specialization in coal-tar-derived combustion enhancers for North American boiler operators. Tiancheng Chemical competes aggressively on cost structures, dominating bulk supply contracts with Chinese cement producers.
Coal-saving combustion-supporting agents comprise catalytic and oxidative chemical formulations—typically containing transition metal salts, rare earth compounds, or organic combustion catalysts—that accelerate carbon oxidation kinetics and lower ignition temperatures in solid-fuel systems. These additives functionally reduce excess air requirements, cut unburned carbon losses, and suppress slagging in high-ash coal environments. Powdered additives currently occupy the largest volume share due to straightforward dosing integration with existing pulverized coal infrastructure, while liquid additives represent the fastest-expanding category as fluid injection systems gain traction in retrofit boiler installations. Among applications, power generation commands the deepest margin pool because utilities negotiate multi-year supply agreements with technical service bundles, whereas cement production offers fragmented but higher-growth opportunities as kiln operators seek fuel-switching flexibility.
EPA emission guidelines and China's GB standards on coal-fired boiler efficiency jointly constrain permissible additive chemistries, forcing reformulation away from heavy metal catalysts toward rare earth and organic alternatives. India's CEA technical regulations on station heat rates create compliance-driven procurement pull, particularly among state-level generation utilities. Stakeholders must monitor how tightening particulate and SOx limits across multiple jurisdictions reshape the acceptable ingredient slate and certification burden for new product registrations.
Market Dynamics
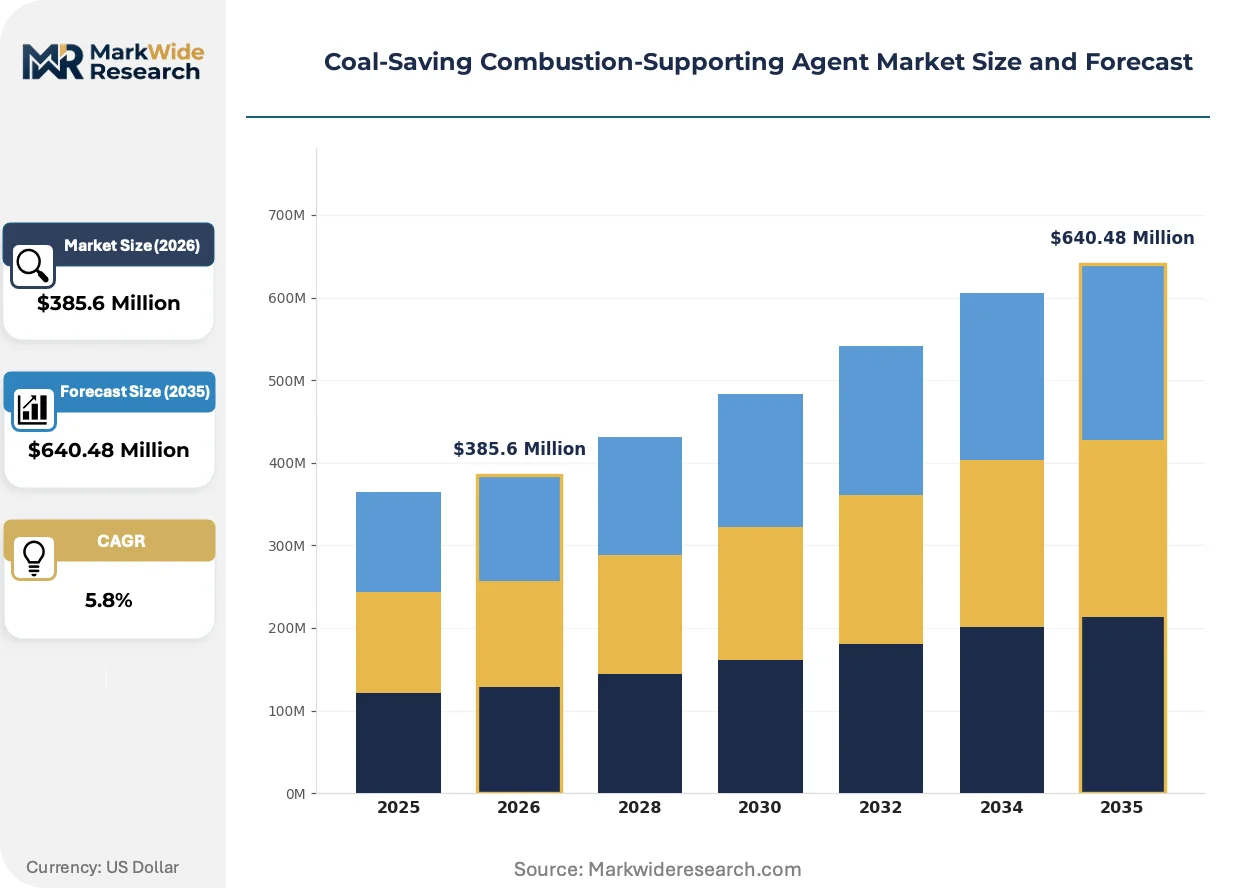
China's MEE emission standards and India's CEA heat-rate mandates are forcing simultaneous reformulation of additive chemistries and rewiring procurement relationships across coal-dependent industries. Suppliers must now validate rare-earth and organic catalyst alternatives while utilities negotiate multi-year technical service bundles.
Growth Catalysts
- MEE tightening:China's Ministry of Ecology and Environment standards on NOx and particulate emissions compel power generators to adopt low-ignition-temperature additives. Cement kilns in Shandong and Hebei provinces face accelerated compliance timelines.
- CEA technical regulations:India's Central Electricity Authority mandates on station heat rates create procurement pull among state-level generation utilities. Discoms in Maharashtra and Gujarat prioritize combustion-supporting agents to avoid efficiency penalties.
- Pulverized coal infrastructure:Powdered additive dosing systems integrate directly with existing boiler feed lines. Retrofit costs remain minimal compared to liquid injection system overhauls.
Market Restraints
- Rare earth input volatility:Cerium and lanthanum price swings destabilize formulation economics. Chinese export quota policies compound supply uncertainty for non-domestic blenders.
- Heavy metal regulatory friction:EPA guidelines and REACH restrictions on cobalt and manganese catalysts force premature product obsolescence. Reformulation R&D cycles compress margin recovery windows.
- Biomass co-firing substitution:European utilities accelerate wood-pellet and agricultural-waste blending trials. Combustion-supporting agents face displacement risk in low-carbon transition scenarios.
Strategic Opportunities
- Indonesian industrial belt:Nickel smelters and captive power plants in Sulawesi and Maluku operate high-ash subbituminous coal. Local additive qualification programs remain underdeveloped.
- Liquid additive channel innovation:Fluid injection system retrofits enable precision dosing in circulating fluidized bed boilers. Engineering-procurement-construction firms bundle chemical supply with installation services.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive cement and steel incentivize emission-reduction investments. Combustion-efficiency additives qualify as embedded-carbon reduction pathways.
Industry Challenges
- Combustion chemistry specialization gap:Formulation chemists with solid-fuel kinetics expertise remain scarce. Universities in coal-dependent regions have downsized relevant research programs.
- Multi-jurisdiction certification complexity:Separate GB standard testing in China, BIS registration in India, and EPA notification in the US extend product launch timelines. Each jurisdiction demands distinct toxicological and performance data packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal-Saving Combustion-Supporting Agent Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Additives, Powdered Additives, Granular Additives, Emulsified Products Application: Industrial Boilers, Power Generation, Cement Production, Residential Heating End User: Energy Providers, Manufacturing Plants, Residential Consumers, Construction Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, Solvay S.A., Koppers Inc., Clariant, Mitsubishi Chemical Corporation, SABIC, ExxonMobil, Nalco Water, Tiancheng Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal-Saving Combustion-Supporting Agent Market Trends and Innovations
Additive developers are converging on rare-earth-organic hybrid formulations that satisfy simultaneous efficiency and emission mandates. This chemistry pivot demands new synthesis capabilities and rewires supplier-customer technical relationships.
Fluid injection systems are integrating cerium-based nanocatalyst suspensions with real-time boiler control feedback loops. European power operators in Poland and the Czech Republic pilot these configurations to stabilize flame temperatures across variable coal quality. The technology is integrating combustion optimization with predictive maintenance platforms, compressing the traditional separation between chemical supply and digital services.
REACH restrictions on heavy metal catalysts are accelerating substitution timelines for cobalt and manganese formulations. Industrial blenders must now qualify rare-earth alternatives through extended boiler trials. German and Dutch utilities impose the most stringent pre-qualification protocols, delaying supplier onboarding by 18-24 months relative to other European markets.
Multi-supplier qualification programs are displacing single-source additive contracts among large power generators. Procurement teams in India's NTPC and China's Huaneng Group now maintain approved vendor lists across three or more formulation specialists. This pattern is most visible in procurement departments with dedicated technical evaluation cells, where risk diversification trumps volume discount negotiations.
Coal-Saving Combustion-Supporting Agent Market Segmentation
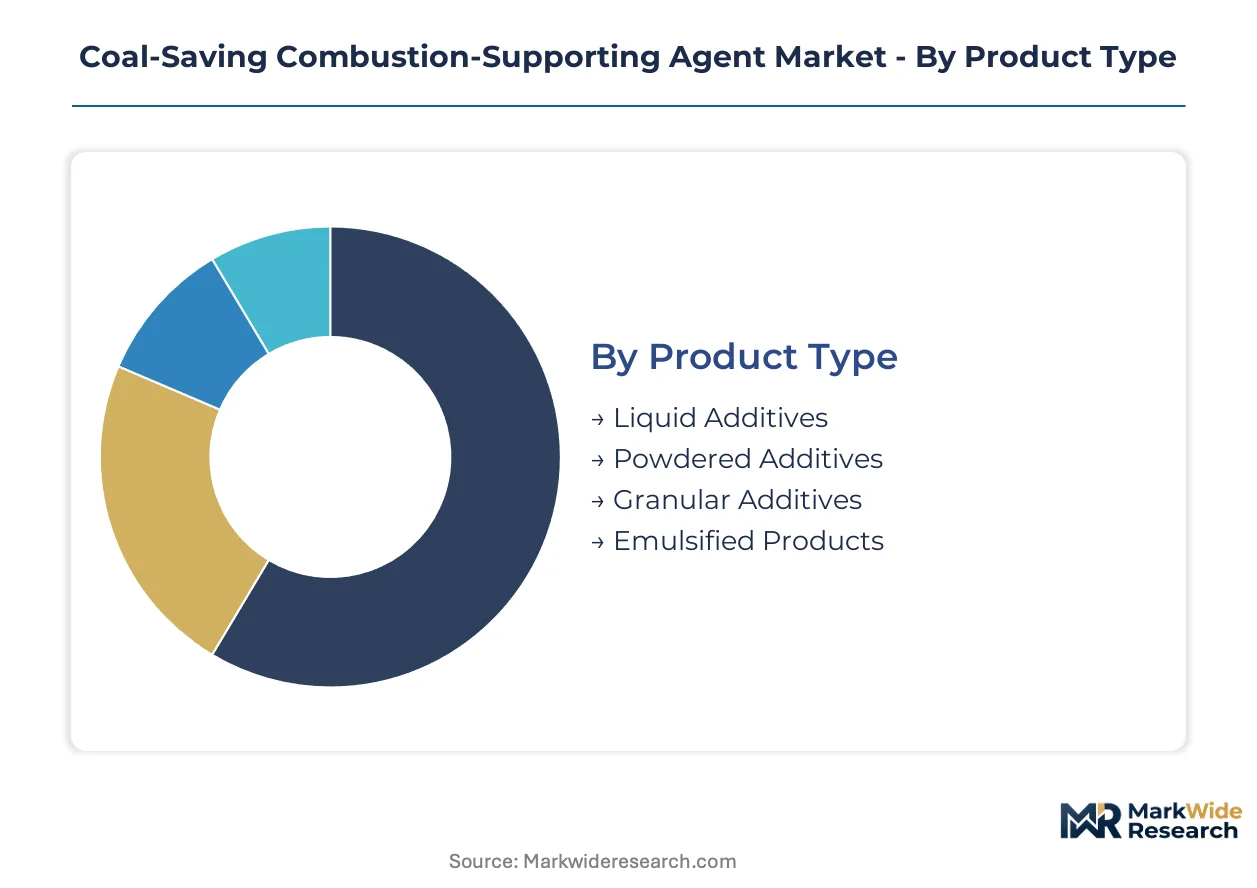
Segmentation in the coal-saving combustion-supporting agent market reveals distinct technical requirements across fuel system architectures and procurement behaviors. Each axis exposes different margin structures, reformulation pressures, and customer relationship intensities that reshape supplier strategy.
Product Type:
Formulation state dictates integration complexity, dosing precision, and retrofit economics across boiler generations.
- Powdered Additives:Dry transition metal salt and rare earth compound blends integrate directly with existing pulverized coal feed lines. Demand concentrates in China's Shandong and Hebei cement kilns where MEE emission standards compel rapid, low-capital compliance upgrades.
- Liquid Additives:Cerium-based nanocatalyst suspensions in aqueous or organic carriers enable precision injection through fluid delivery systems. European power operators in Poland and the Czech Republic pilot these configurations to stabilize flame temperatures across variable coal quality, with fluid injection retrofits gaining traction in circulating fluidized bed boiler installations.
- Granular Additives:Pelletized rare earth-organic hybrids suit stoker-fed industrial boilers with mechanical grate systems. Indian state generation utilities in Maharashtra deploy these for controlled release in aging subcritical units.
- Emulsified Products:Oil-water-catalyst dispersions target small-scale industrial boilers with inconsistent fuel handling infrastructure. Indonesian nickel smelters in Sulawesi test these for high-ash subbituminous coal combustion.
Mature deployment sits with powdered additives. Newer deployment is concentrated in liquid additive configurations.
Application:
End-use thermal intensity and regulatory exposure create divergent customer value propositions and contract structures.
- Power Generation:Utilities negotiate multi-year supply agreements bundling combustion-supporting agents with technical service packages. India's CEA heat-rate mandates drive procurement pull among state-level generation utilities in Gujarat and Maharashtra, where efficiency penalties loom for non-compliance.
- Cement Production:Kiln operators seek fuel-switching flexibility between coal and alternative fuels. China's tightening GB standards on particulate emissions force accelerated additive adoption in Shandong and Hebei provinces.
- Industrial Boilers:Manufacturing plants prioritize ignition temperature reduction for high-moisture, low-rank coal. captive power units face cost pressure.
- Residential Heating:Small-scale coal stoves in rural heating districts drive demand for low-dose catalytic additives. Distribution concentrates through regional fuel suppliers.
Power generation commands the deepest margin pool through technical service bundling. Cement production offers the steepest expansion trajectory as fuel-switching flexibility becomes critical.
End User:
Procurement sophistication and technical evaluation capacity segment customers by relationship intensity and contract duration.
- Energy Providers:Centralized procurement departments with dedicated technical evaluation cells maintain multi-supplier qualification programs. China's Huaneng Group and India's NTPC operate approved vendor lists across three or more formulation specialists.
- Manufacturing Plants:Cement and steel producers prioritize cost-per-ton-of-steam metrics over technical service bundles. Fragmented procurement patterns dominate.
- Construction Companies:Project-based additive purchasing for temporary heating and batch plant operations. Spot market transactions prevail.
- Residential Consumers:Price-sensitive demand channeled through fuel distributors and local retailers. Limited technical specification awareness.
Energy providers anchor long-term contract structures. Manufacturing plants concentrate spot-market volume.
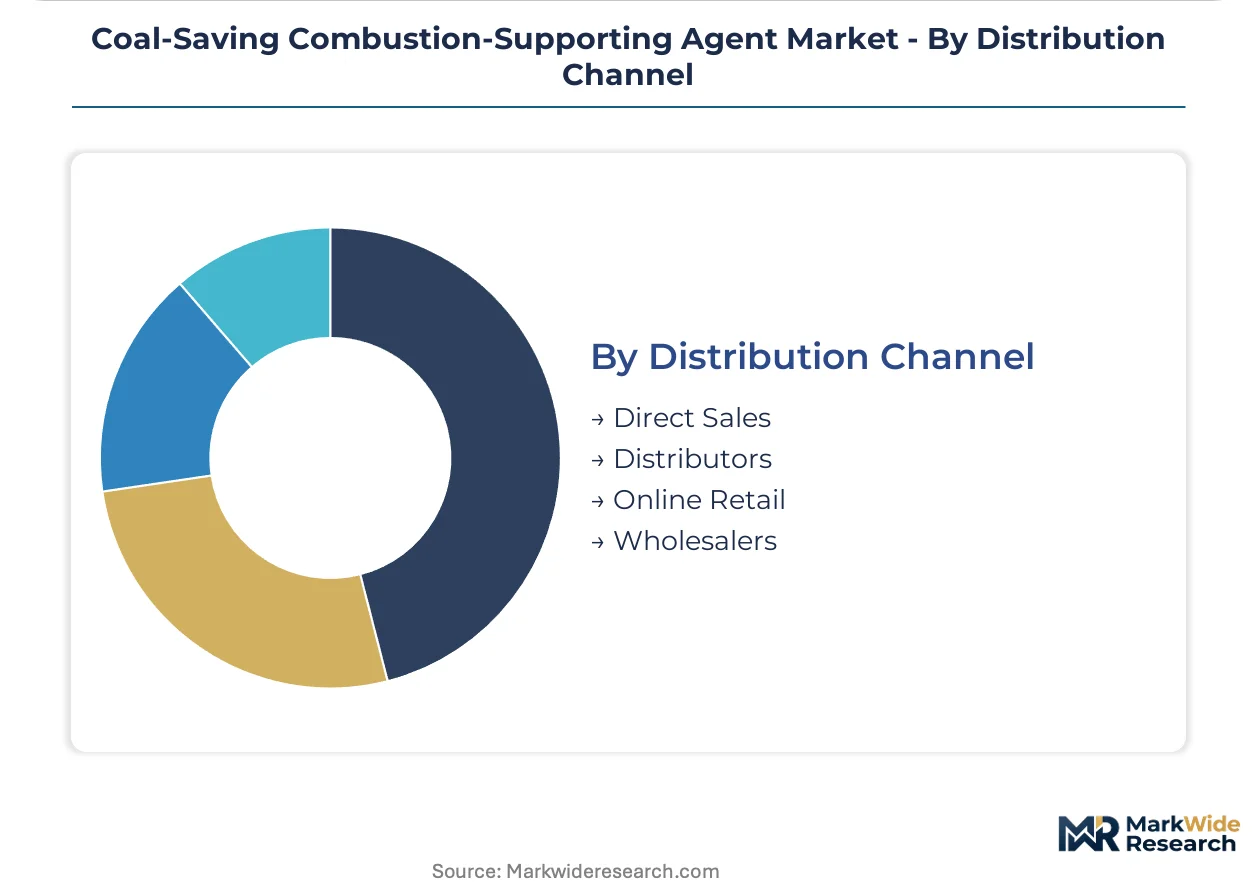
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and geographic concentration of demand.
- Direct Sales:BASF SE and Koppers Inc. deploy technical field teams for utility-scale customers requiring boiler trial supervision and performance guarantees. Engineering-procurement-construction firms bundle chemical supply with installation services for liquid additive retrofits.
- Distributors:Regional chemical distributors serve mid-sized industrial boiler operators with standardized powdered additive packages. Inventory positioning near coal-dependent manufacturing clusters reduces lead times.
- Wholesalers:Bulk volume aggregation for cement producer consortiums and state utility cooperatives. Price negotiation leverage concentrates procurement power.
- Online Retail:Emerging channel for small-dose residential and light industrial customers. Limited technical consultation capacity constrains adoption.
Direct sales capture the highest-margin technical service relationships. Distributor networks dominate volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rare earth processing dominance anchors global additive chemistry supply chains. Coal-dependent industrial belts in Asia, Europe, and North America drive differentiated formulation demand.
China
Shandong and Hebei cement kilns deploy powdered combustion-supporting agents to meet MEE emission standards. GB standards on coal-fired boiler efficiency constrain permissible additive chemistries. Qingdao and Tangshan industrial clusters host qualification trials for rare-earth-organic hybrid formulations.
India
State-level generation utilities in Maharashtra and Gujarat procure additives to comply with CEA heat-rate mandates. Discoms face efficiency penalties for non-compliance. The Mumbai-Ahmedabad industrial corridor concentrates demand from captive power units.
Germany
REACH restrictions on cobalt and manganese catalysts accelerate reformulation toward rare-earth alternatives. ECHA oversight extends pre-qualification timelines for new additive registrations. The Ruhr industrial basin hosts extended boiler trials for cerium-based nanocatalyst suspensions.
United States
EPA emission guidelines constrain heavy metal catalyst use in coal-fired utilities. Koppers Inc. anchors North American supply through coal-tar-derived combustion enhancers. Appalachian power operators negotiate multi-year technical service bundles.
Poland
Utilities pilot fluid injection systems integrating cerium-based nanocatalyst suspensions with real-time boiler controls. EU Green Deal carbon border adjustments incentivize emission-reduction investments. The Silesian coal basin drives demand for low-ignition-temperature additives.
Coal-Saving Combustion-Supporting Agent Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and technical service bundling. Market structure consolidates around diversified chemical conglomerates with rare earth sourcing advantages, while regional specialists retain share through deep boiler-operator relationships. Three archetypes dominate: integrated chemical majors with global manufacturing footprints, coal-tar derivatives specialists, and cost-optimized bulk suppliers. Competitive moves center on multi-supplier qualification program penetration and rare-earth supply chain backward integration.
Within the integrated chemical major tier, BASF SE and Solvay S.A. occupy positions defined by global additive package standardization and EMEA regulatory navigation capabilities. Among Asia-Pacific bulk suppliers, Tiancheng Chemical exemplifies cost-structure competition for cement producer procurement tenders. Mitsubishi Chemical Corporation represents the Japanese industrial conglomerate archetype with captive rare earth processing linkages.
| Leading Market Players |
|---|
| BASF SE |
| Solvay S.A. |
| Koppers Inc. |
| Clariant |
| Mitsubishi Chemical Corporation |
| SABIC |
| ExxonMobil |
| Nalco Water |
| Tiancheng Chemical |
| Others |
Pricing and Supply Chain Analysis
Captive rare earth processing in China's Inner Mongolia and Jiangxi provinces anchors both formulation cost structures and supplier pricing power. BASF SE and Solvay S.A. leverage backward integration into cerium and lanthanum supply chains to stabilize margin positions against volatile spot markets, while regional blenders without upstream control face compressed economics during export quota restrictions.
Pricing Analysis
Technical service bundling separates premium supplier contracts from commodity additive transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentials, with REACH-compliant rare-earth-organic hybrids commanding premiums over legacy heavy metal formulations. Price differentiation hinges on boiler trial supervision inclusion and multi-year performance guarantees. Cost compression in standard-tier powdered additives is intensifying because Indian cement producers aggregate procurement through state-level consortiums. Manufacturing plants with captive power units exhibit highest price sensitivity; utilities with dedicated technical evaluation cells prioritize qualification depth over unit cost.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale buyer demand through embedded technical field teams. Raw material concentration centers on China for rare earth oxides, Germany for organic combustion catalyst precursors, and the United States for coal-tar derivative feedstocks. Formulation economics rest on cerium, lanthanum, and transition metal salt inputs. Single-source vulnerability in Chinese rare earth export quotas compounds supply uncertainty for European and North American blenders. Distribution runs through engineering-procurement-construction firms bundling liquid additive retrofits with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
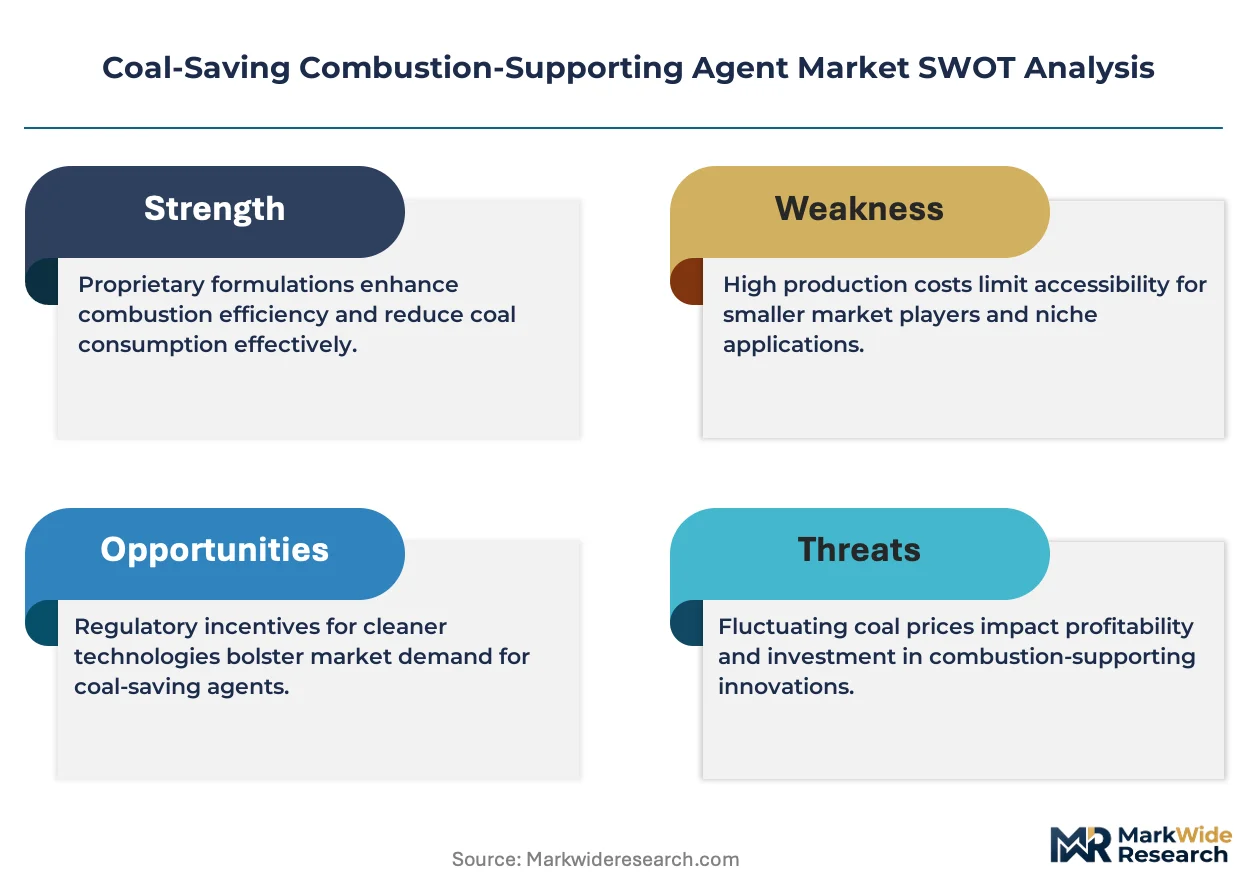
The coal-saving combustion-supporting agent market operates as a vertical-integration race. Players are pursuing captive rare earth processing capacity to secure formulation cost stability against Chinese export policy volatility.
For Market Incumbents: Acquire cerium and lanthanum mining or refining assets to decouple from Chinese quota exposure. Expand technical service bundling to deepen multi-year contract stickiness against emerging low-cost Asian suppliers. Biomass co-firing substitution in European utilities threatens displacement; defend through rare-earth-organic hybrid R&D pipelines that demonstrate carbon-intensity reduction qualifying under EU Green Deal carbon border adjustments.
For New Entrants and Emerging Players: Indonesian nickel smelter captive power units represent an underserved buyer archetype with minimal incumbent technical presence. Local additive qualification programs in Sulawesi and Maluku remain underdeveloped, creating first-mover windows. Partner with engineering-procurement-construction firms to bundle fluid injection system retrofits with supply contracts, bypassing direct utility procurement complexity.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical majors seeking rare earth backward integration. Long-term viability favors suppliers with demonstrated multi-jurisdiction certification capabilities spanning GB standards, BIS registration, and EPA notification. Watch for CEA heat-rate mandate enforcement intensity in Maharashtra and Gujarat as inflection indicator for Indian demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Cerium and lanthanum supply security insulates margin positions against Chinese export quota volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB standard, BIS, and EPA qualification compresses product launch timelines for global utilities. |
| Liquid Additive Channel Partnership | Engineering-procurement-construction bundling opens retrofit-driven revenue streams in European CFB boiler installations. |
| Rare-Earth-Organic Hybrid R&D Pipeline | REACH-compliant formulations preempt heavy metal catalyst obsolescence in German and Dutch utility procurement. |
| Indonesian Industrial Belt Market Development | Sulawesi nickel smelter captive power demand offers first-mover positioning in high-ash subbituminous coal applications. |
Research Methodology
Independent corroboration across plant manager interviews, utility procurement lead surveys, and distribution channel partner assessments underwrites the qualitative findings. Primary fieldwork engaged boiler operations directors at state-level generation utilities in India, technical R&D directors at European chemical conglomerates, and procurement leads at Chinese cement producer consortiums. Secondary validation drew from MEE emission standard filings, CEA heat-rate mandate documentation, ECHA REACH restriction updates, and customs trade data on rare earth oxide flows. Bottom-up additive volume estimates triangulate against top-down coal consumption projections across power generation and cement production end-uses.
Rate-of-change decomposition separates volume growth drivers from price evolution across the analysis window. The analytical framework models segmentation dimensions including formulation state, end-use thermal intensity, procurement sophistication tier, and regional regulatory cluster. CAGRs derive from additive penetration rate assumptions applied to coal-fired capacity expansion and retrofit cycles. Industry-specific forecast inputs incorporate MEE compliance timeline acceleration in Shandong and Hebei provinces and CEA penalty enforcement probability distributions across Indian state utilities.
Revisions become necessary when rare earth export quota policies shift, REACH restriction scopes expand, or biomass co-firing substitution rates exceed baseline assumptions. Forecasts reflect documented assumptions on regulatory enforcement intensity and additive efficacy validation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Residential Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
District Heating Market
Boilers
Biomass Boiler Market
Boilers
Boiler System Market
Boilers
Commercial Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
Power Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
North America Commercial Boiler Market
Boilers
US Boiler Market
Boilers
Europe Residential Boiler Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market