
 Oil Free Compressor Market | 2026-2036
Oil Free Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Free Compressor Market Outlook
Compressed air engineering talent is collapsing across mature manufacturing economies, constraining OEM capacity expansion and aftermarket service networks. Atlas Copco AB leverages its captive training academies and digital service infrastructure to sustain technician density in critical markets. Ingersoll Rand competes through modular platform architectures that reduce field commissioning complexity. Kaeser Kompressoren SE anchors its position with regionally distributed spare parts logistics and localized assembly footprints.
An oil free compressor delivers compressed air without hydrocarbon lubricant contact, achieving ISO 8573 Class Zero purity through dry-running screws, scroll wraps, or centrifugal impeller designs with non-metallic sealing surfaces. These systems serve pharmaceutical aseptic processing, semiconductor wafer fabrication, and food packaging lines where oil contamination risks batch rejection or regulatory non-compliance. Centrifugal designs dominate large-flow industrial installations above 200 kW, while scroll compressors capture medical and laboratory segments demanding near-silent operation below 50 kW. Stationary deployment configurations command the majority of installed base value, though modular skid packages are gaining traction in pharmaceutical greenfield projects requiring rapid qualification timelines.
ISO 8573 air quality classes, FDA Current Good Manufacturing Practice requirements, and EU F-Gas Regulation phase-down schedules collectively shape product development roadmaps and replacement demand cycles. EPA enforcement of leak detection and repair protocols in US process industries tightens operational compliance burdens, favoring sealed-for-life compressor designs over legacy lubricated alternatives. Stakeholders must monitor evolving refrigerant transition timelines and regional energy efficiency labeling schemes to align portfolio investments with emerging procurement specifications.
Market Dynamics
ISO 8573 Class Zero certification mandates are compressing replacement cycles across pharmaceutical and semiconductor installations, forcing capital equipment decisions toward sealed-for-life architectures that eliminate hydrocarbon contamination risks entirely.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant transition timelines accelerate compressor technology refreshes in cold chain and process cooling applications across European pharmaceutical manufacturing.
- Semiconductor wafer fabrication:Sub-7 nanometer process nodes demand ultra-high purity compressed air systems, concentrating procurement in Taiwan, South Korea, and Germany.
- Precision engineering clusters:Automotive supplier networks in Stuttgart and Munich drive premium oil-free compressor specification for electric vehicle battery assembly lines.
Market Restraints
- Specialized alloy supply concentration:Non-metallic sealing surfaces and precision-machined rotors depend on German and Japanese specialty materials suppliers with limited second-source availability.
- Energy efficiency labeling friction:Divergent national test protocols between US DOE and EU energy labeling schemes complicate product platform standardization and certification costs.
- Scroll compressor cost structure:Dry-running wrap geometries require tight-tolerance ceramic coatings that elevate unit economics relative to lubricated alternatives below 50 kW.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO enforcement of EU-equivalent GMP standards in active pharmaceutical ingredient plants creates first-time Class Zero compressor demand in Hyderabad and Ahmedabad clusters.
- Modular skid packaging:Pre-qualified plug-and-play compressor packages compress pharmaceutical greenfield commissioning timelines from months to weeks.
- Digital service infrastructure convergence:Remote monitoring platforms integrated with predictive maintenance algorithms enable outcome-based compressor availability contracts displacing traditional spare parts revenue models.
Industry Challenges
- Compressed air engineering talent scarcity:Technician density is collapsing across mature manufacturing economies, constraining OEM capacity expansion and aftermarket service network coverage.
- Multi-standard certification complexity:Simultaneous FDA cGMP, EU GMP Annex 1, and ISO 8573 compliance extends qualification timelines for pharmaceutical installations.
- Legacy lubricated system integration:Brownfield sites face compressed air header reconfiguration costs when retrofitting oil-free units into existing distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Free Compressor Market |
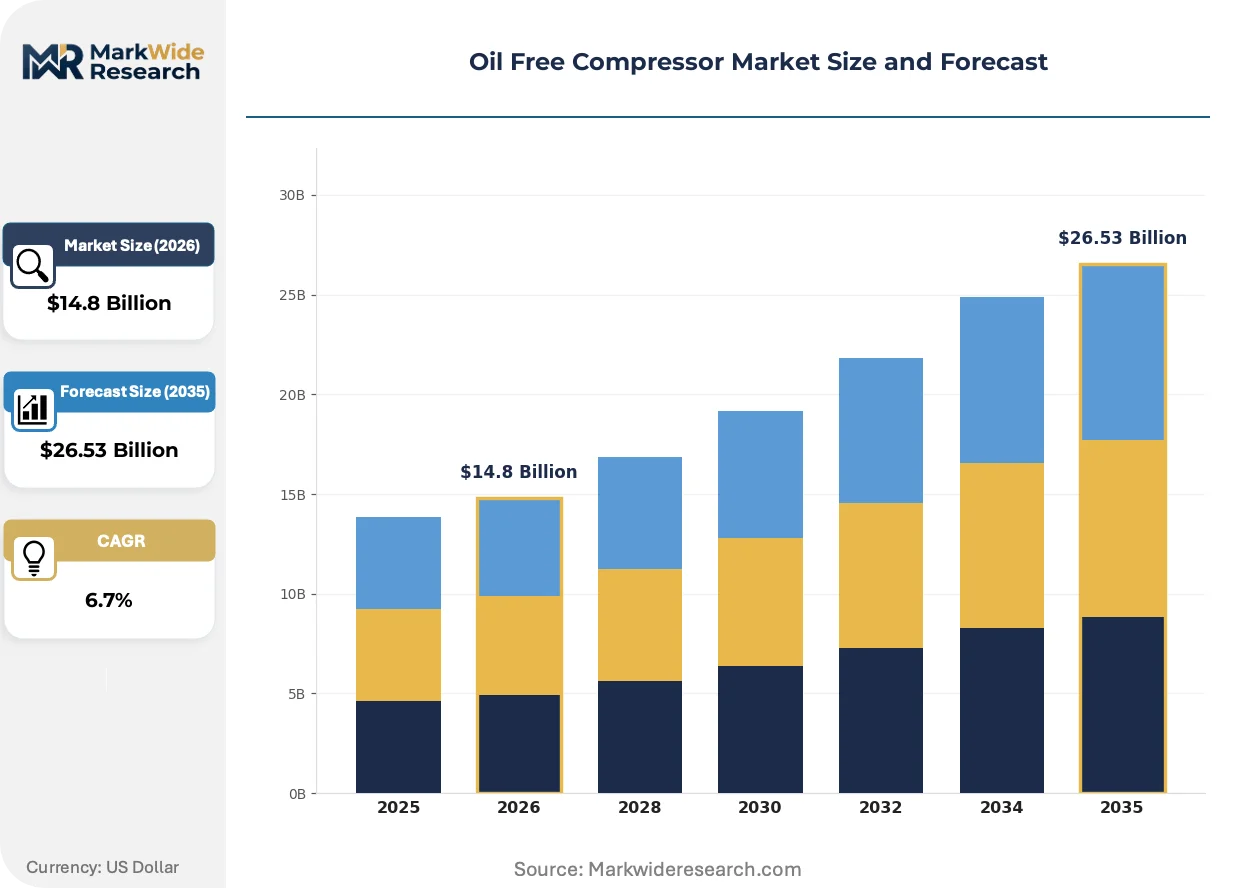
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll, Centrifugal, Reciprocating, Rotary End User: Pharmaceuticals, Food & Beverage, Electronics, Aerospace Deployment: On-Premise, Portable, Stationary, Modular Application: Breathing Air, Vacuum Packaging, Leak Testing, Industrial Processes |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Kaeser Kompressoren SE, Sullair, LLC, Aerzen, Hitachi Industrial Equipment Systems Co., Ltd., ELGi, Gardner Denver, FS Elliot Co., LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Free Compressor Market Strategic Shifts
Dry-running screw and scroll architectures are actively compressing the addressable market for legacy lubricated compressors in purity-critical applications, while digital service models reconfigure how compressor availability is contracted and monetized.
Magnetic bearing centrifugal compressors are supplanting traditional geared designs in large-flow industrial installations above 200 kW. Semiconductor fabs in Taiwan and memory manufacturers in South Korea specify these units for their elimination of mechanical wear surfaces and associated particulate generation. The technology is supplanting oil-film bearing alternatives entirely in new greenfield specifications, compressing the viable product lifecycle of conventional centrifugal architectures.
The EPA's leak detection and repair protocol enforcement in US process industries tightens operational compliance burdens on existing compressed air systems. Refinery and chemical plant operators face elevated inspection frequencies and documentation requirements that favor sealed-for-life compressor designs. Texas and Louisiana process industry clusters are responding with accelerated replacement schedules that prioritize designs eliminating lubricant reservoirs entirely.
Pharmaceutical buyers are unbundling compressor procurement from long-term service contracts, reversing decades of bundled equipment-and-maintenance purchasing. Large molecule biologics manufacturers now separate capital equipment selection from aftermarket service provider choice, compressing incumbent OEM service margins. This pattern is most visible in Massachusetts and North Carolina biotech corridors, where specialized third-party service firms capture maintenance volumes previously captive to equipment suppliers.
Oil Free Compressor Market Segmentation
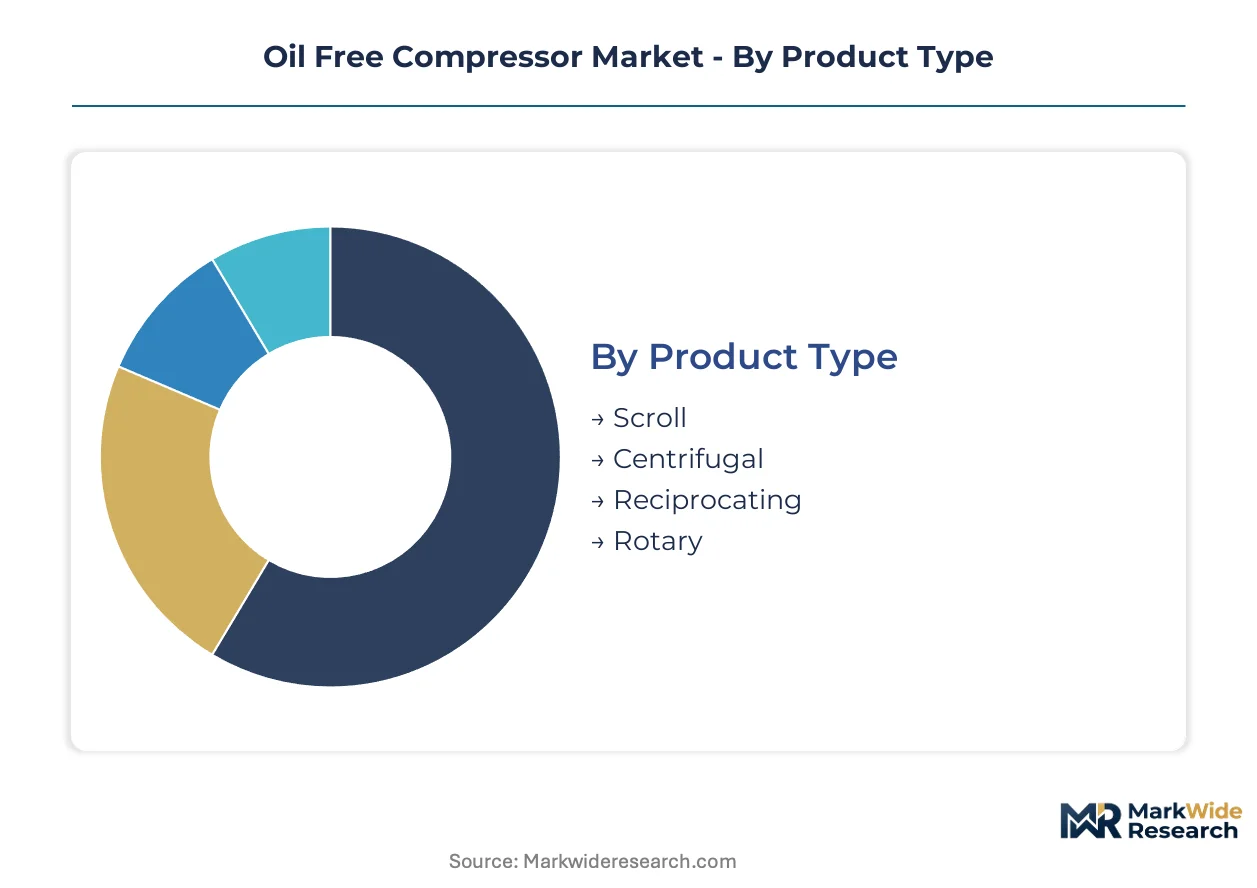
Oil free compressor procurement patterns diverge sharply across purity requirements, installation scale, and regulatory exposure. Segment boundaries reflect where ISO 8573 Class Zero mandates intersect with operational constraints like footprint limits, mobility needs, and integration complexity.
Product Type:
Centrifugal and scroll architectures anchor domestic manufacturing demand in Germany and Japan, while reciprocating and rotary units serve price-sensitive export markets in Southeast Asia and Latin America.
- Centrifugal:Magnetic bearing designs eliminate mechanical wear surfaces through non-contact rotor suspension. Taiwan semiconductor fabs and South Korean memory manufacturers specify these units for sub-7 nanometer process nodes where particulate generation risks wafer contamination.
- Scroll:Interleaved spiral wraps compress air through orbital motion without lubricant contact. Dry-running ceramic coatings enable near-silent operation below 50 kW, concentrating demand in Swiss pharmaceutical packaging lines and German medical device sterilization suites where acoustic limits apply.
- Reciprocating:Piston-driven compression serves intermittent-duty applications in Brazilian food processing and Indian textile manufacturing where capital constraints limit premium technology adoption.
- Rotary:Twin-screw dry-running geometries dominate automotive supplier networks in Stuttgart and Munich, supplying Class Zero air for electric vehicle battery assembly without hydrocarbon contamination risks.
Centrifugal designs command the established base in large-flow industrial installations. The steepest expansion runs through scroll compressors capturing medical and laboratory segments.
End User:
Customer procurement sophistication stratifies by regulatory burden — pharmaceutical and aerospace buyers enforce ISO 8573 Class Zero strictly, while food and beverage and electronics segments apply tiered purity specifications.
- Pharmaceuticals:Aseptic processing lines require sealed-for-life architectures eliminating lubricant reservoirs entirely. FDA cGMP and EU GMP Annex 1 compliance drives replacement cycles in Massachusetts and North Carolina biotech corridors.
- Food & Beverage:Packaging line operators balance contamination risk against energy efficiency. German dairy processors and French winery bottling facilities specify oil-free systems for product-contact applications while tolerating lubricated alternatives in utility air circuits.
- Electronics:Semiconductor wafer fabrication concentrates procurement in Taiwan, South Korea, and Germany where sub-7 nanometer nodes demand ultra-high purity compressed air.
- Aerospace:Aircraft ground support and component testing applications in Toulouse and Seattle manufacturing clusters require portable and stationary configurations with rapid deployment capabilities.
Pharmaceuticals anchor premium pricing tiers through qualification-intensive procurement. Food and beverage represents the volume expansion pathway as EU hygiene regulations tighten.
Deployment:
Installation mobility requirements map to application volatility — permanent production lines favor stationary and on-premise configurations, while contract manufacturing and field service drive portable and modular adoption.
- On-Premise:Dedicated compressor rooms with integrated air treatment serve continuous-process pharmaceutical and semiconductor facilities. Hyderabad and Ahmedabad API plants are installing first-time Class Zero infrastructure as CDSCO enforces EU-equivalent GMP standards.
- Portable:Wheeled skid packages support construction, mining, and emergency breathing air applications. Rental fleet operators in Australia and Canada specify these units for remote site mobilization.
- Stationary:Fixed-base installations dominate installed base value across German automotive supplier networks and Japanese precision engineering clusters.
- Modular:Pre-qualified plug-and-play packages compress pharmaceutical greenfield commissioning timelines from months to weeks. Massachusetts biotech corridors are adopting standardized skid configurations for rapid facility qualification.
Stationary deployments retain the majority of installed base value. Modular configurations are climbing the fastest as pharmaceutical greenfield projects prioritize speed-to-qualification.
Application:
Purity thresholds and flow dynamics segment demand — human safety applications enforce the strictest contamination limits, while industrial processes tolerate broader specification ranges.
- Breathing Air:Hospital surgical suites, firefighting equipment, and diving operations require pharmacopeia-grade purity with continuous monitoring. German DIN standards and US NFPA specifications drive certified system procurement.
- Vacuum Packaging:Modified atmosphere packaging for meat, cheese, and prepared foods concentrates demand in Italian and Spanish processing facilities where oil contamination accelerates rancidity.
- Leak Testing:Automotive component validation and refrigeration system integrity verification employ oil-free air to prevent false-positive contamination readings.
- Industrial Processes:Pneumatic conveying, instrument air, and general factory supply constitute volume demand in Mexican and Vietnamese manufacturing expansion zones.
Industrial processes command the broadest installed base through generic utility applications. Breathing air is gaining share fastest as healthcare infrastructure expands and safety regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys oil-free compressors predominantly for precision automotive manufacturing, whereas India and Taiwan concentrate procurement in pharmaceutical and semiconductor fabs respectively. This consumption-mix differential shapes regional technology preferences and certification requirements.
Germany
Automotive supplier networks in Stuttgart and Munich drive premium compressor specification for electric vehicle battery assembly lines. The EU F-Gas Regulation accelerates technology refreshes in cold chain applications. Precision engineering clusters across Baden-Württemberg and Bavaria anchor Class Zero procurement for contamination-sensitive manufacturing processes.
United States
Biologics manufacturers in Massachusetts and North Carolina biotech corridors enforce strict FDA cGMP compliance for aseptic processing lines. EPA leak detection and repair protocol enforcement tightens operational burdens on Texas and Louisiana process industry clusters. Pharmaceutical buyers here are unbundling equipment procurement from long-term service contracts.
India
Active pharmaceutical ingredient plants in Hyderabad and Ahmedabad are installing first-time Class Zero infrastructure. CDSCO enforcement of EU-equivalent GMP standards creates virgin demand for sealed-for-life compressor architectures. Domestic manufacturing expansion concentrates in western and southern industrial corridors.
Taiwan
Semiconductor wafer fabrication at sub-7 nanometer process nodes demands ultra-high purity compressed air systems. Magnetic bearing centrifugal compressors supplant traditional geared designs for elimination of mechanical wear surfaces. Foundry investments concentrate procurement in Hsinchu and Tainan Science Parks.
Japan
Medical device sterilization suites and precision electronics manufacturing specify scroll compressors for near-silent operation below 50 kW. METI energy efficiency labeling schemes influence product platform decisions. Industrial equipment demand clusters in Kansai and Chubu manufacturing belts.
Oil Free Compressor Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through captive training infrastructure and digital service platforms. The middle tier competes on modular platform architectures that reduce field commissioning complexity. Geographic expansion and outcome-based contracting represent the dominant competitive moves reshaping traditional equipment-and-maintenance revenue models.
Among European-originated industrial groups, Atlas Copco AB and Kaeser Kompressoren SE exemplify the integrated leader archetype through established regional footprints. Ingersoll Rand occupies a position representing North American-headquartered diversification across compressed air and industrial equipment categories. These three anchors illustrate how scale-driven service density and modular product strategies compete for technician-constrained markets.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Kaeser Kompressoren SE |
| Sullair, LLC |
| Aerzen |
| Hitachi Industrial Equipment Systems Co., Ltd. |
| ELGi |
| Gardner Denver |
| FS Elliot Co., LLC |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with pharmaceutical and semiconductor fabs lock in both supply access and price visibility for oil-free compressor OEMs, insulating tier-one suppliers from spot-market volatility while compressing margins for tier-two players competing on project-based tenders.
Pricing Analysis
Project-based contracting dominates pharmaceutical greenfield installations, while recurring service subscriptions anchor aftermarket revenue streams. Price differentiation rests on ISO 8573 Class Zero certification tier and geographic proximity to service networks. Cost compression in standard-grade scroll compressors is intensifying because ceramic coating suppliers in Japan face capacity constraints. Food and beverage buyers exhibit highest price sensitivity, whereas semiconductor fabs prioritize contamination elimination over unit economics.
Supply Chain Analysis
German and Japanese specialty alloy suppliers constitute a chokepoint for precision-machined rotors and non-metallic sealing surfaces. Raw material sourcing draws from precision ceramics foundries in Baden-Württemberg and advanced polymer compounders in Osaka Prefecture. Single-source vulnerability concentrates in magnetic bearing subassemblies where Swedish and Swiss suppliers dominate. Distribution runs through OEM-direct channels for large installations and authorized distributor networks for sub-50 kW units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 8573 Class Zero mandates are compressing replacement cycles and elevating certified architectures above commodity alternatives, creating asymmetric returns for suppliers with pre-qualified modular platforms.
For Market Incumbents: Secure captive technician training pipelines through regional academies to offset collapsing engineering talent density. Anchor service revenue through predictive maintenance platforms that displace traditional spare parts models. Defend against unbundling threats by pharmaceutical buyers through outcome-based availability contracts. For New Entrants and Emerging Players: Lead with modular skid packaging for Indian pharmaceutical greenfield projects where CDSCO enforcement creates first-time Class Zero demand. Target breathing air applications in expanding healthcare infrastructure where certification barriers remain lower than semiconductor fabs. Pursue rental fleet partnerships in Australian and Canadian remote site markets. For Investors and Strategic Acquirers: Capital is best deployed toward regional service specialists with dense technician footprints in Germany and Japan rather than pure manufacturing assets. Long-term viability favors platforms with digital infrastructure integration. Watch for magnetic bearing technology maturation as the inflection signal for centrifugal compressor margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Skid Packaging | Compresses pharmaceutical commissioning timelines from months to weeks in Massachusetts biotech corridors. |
| Backward Integration into Ceramic Coatings | Secures supply of tight-tolerance scroll wrap materials from Japanese specialty compounders. |
| Predictive Maintenance Platform Launch | Enables outcome-based contracts displacing traditional spare parts revenue at German automotive suppliers. |
| Regional Training Academy Expansion | Offsets compressed air engineering talent scarcity constraining OEM capacity in mature manufacturing economies. |
| Magnetic Bearing Technology Licensing | Accelerates displacement of oil-film bearing designs in Taiwan semiconductor fabs above 200 kW. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers, aftermarket service heads, OEM procurement teams, and pharmaceutical facility managers and refined through secondary validation against SEC filings, customs trade data, ISO certification registries, and industry association technical reports. Bottom-up unit economics were triangulated against top-down sectoral spending patterns.
Variance decomposition across product type, end-user vertical, deployment configuration, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from installed base replacement cycles and greenfield capital expenditure trajectories. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and EPA leak detection protocol enforcement intensity.
Underlying assumptions cover continued ISO 8573 Class Zero adoption curves, with deviation risk concentrated in specialty alloy supply disruptions and divergent national energy efficiency labeling schemes. Practitioners should keep alternative scenarios live as refrigerant transition timelines and pharmaceutical GMP harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
CNG Compressor Market
Compressors
Scroll Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Centrifugal Air Compressor Market
Compressors
LNG Compressor Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
North America Air Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
High Speed Blowers Market
Compressors
Stationary Air Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Compressed Air Lubricators Market
Compressors
Turbocompressor Market