
 Global Fuel Flexible Boiler Market | 2026-2036
Global Fuel Flexible Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuel Flexible Boiler Market Analysis
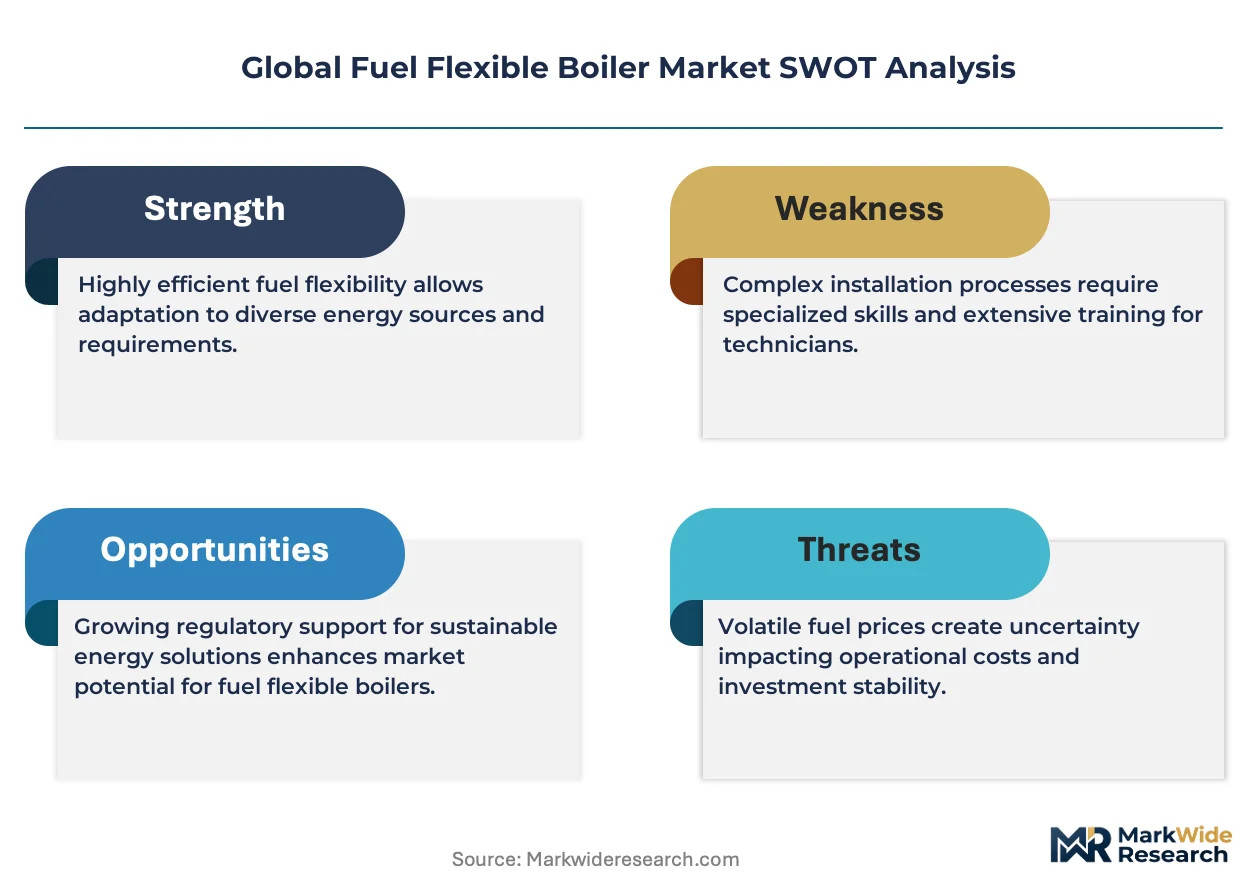
Project finance and power purchase agreement structures is narrowing the competitive field to developers with balance-sheet capacity. Doosan Heavy Industries & Construction Co. Ltd. leverages its integrated EPC capabilities across Asian markets. Babcock & Wilcox Enterprises Inc. anchors its position through specialized boiler engineering for utility-scale retrofits. Siemens AG competes via digital control integration with its combustion hardware portfolio.
A fuel flexible boiler is a combustion system engineered to burn multiple fuel types—natural gas, oil, biomass, or coal—through adjustable burner configurations, variable air-fuel ratio controls, and modified furnace geometries, designed to maintain thermal efficiency and emissions compliance across fuel switches. Its primary industrial purpose is to provide operational resilience for power plants and manufacturing facilities facing fuel price volatility or supply disruption. Natural gas configurations currently dominate installed capacity due to lower capital conversion costs, while biomass segments are expanding fastest in European markets driven by carbon accounting rules. Smart control systems command margin premiums as utilities prioritize automated fuel switching and real-time emissions optimization.
The EPA enforces emissions standards that compel boiler operators to adopt cleaner fuel blends or install costly scrubber systems, directly stimulating retrofit demand for flexible combustion units. The EU Green Deal and REACH frameworks restrict heavy fuel oil usage in industrial settings, pushing manufacturers toward certified multi-fuel systems. India's Central Electricity Authority mandates efficiency benchmarks that favor boilers capable of blending domestic coal with imported gas. Stakeholders must monitor how carbon border adjustment mechanisms reshape the fuel cost calculus for cross-border power trade.
Market Dynamics
Power utilities face a structural squeeze between carbon accounting mandates and volatile fuel input costs, forcing capital allocation toward combustion hardware that can arbitrage price spreads across natural gas, biomass, and residual fuel oils without plant downtime.
Growth Catalysts
- EU F-Gas Regulation:Industrial operators in Germany and Poland retrofit coal units for biomass co-firing to avoid carbon border taxes on exported power, accelerating certified multi-fuel boiler orders.
- India CEA efficiency mandates:Domestic power plants blend high-ash local coal with imported LNG to meet heat-rate benchmarks, requiring burner systems with real-time fuel-ratio adjustment.
- Electrostatic precipitator integration:New boiler architectures embed particulate capture at the furnace level, cutting retrofit compliance costs for US utilities facing EPA Mercury and Air Toxics Standards.
Market Restraints
- Nickel alloy supply concentration:Superalloy furnace tubing relies on Indonesian and Philippine ore processing, exposing boiler OEMs to export quota volatility and 18-month order backlogs.
- REACH chemical registration:Refractory ceramic fiber insulation faces authorization hurdles in EU member states, delaying plant recertification timelines for operators using legacy linings.
- Heat pump substitution:District heating networks in Scandinavian cities pivot to electric compression systems for sub-100°C loads, capping addressable demand for small-scale flexible boilers.
Strategic Opportunities
- Vietnam coal-to-biomass pivot:The country's national power development plan mandates 20% renewable thermal share by 2030, opening greenfield demand for palm-waste combustion systems in Mekong Delta industrial zones.
- US IRA production tax credits:Biogas and renewable natural gas qualify for $3 per MMBtu incentives, pushing dairy and landfill operators toward dual-fuel boiler investments with automated biogas injection.
- Digital twin convergence:Combustion physics modeling fused with IoT sensor arrays enables predictive slagging detection, creating premium service attach rates for control system vendors.
Industry Challenges
- Computational combustion engineering:CFD modeling expertise for multi-fuel flame stability sits concentrated at a handful of university labs and retired utility engineering departments, constraining design throughput.
- ASME Section I certification:Stamp approval for high-pressure flexible boilers requires 14-18 month third-party review cycles, freezing project finance draws and inflating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuel Flexible Boiler Market |
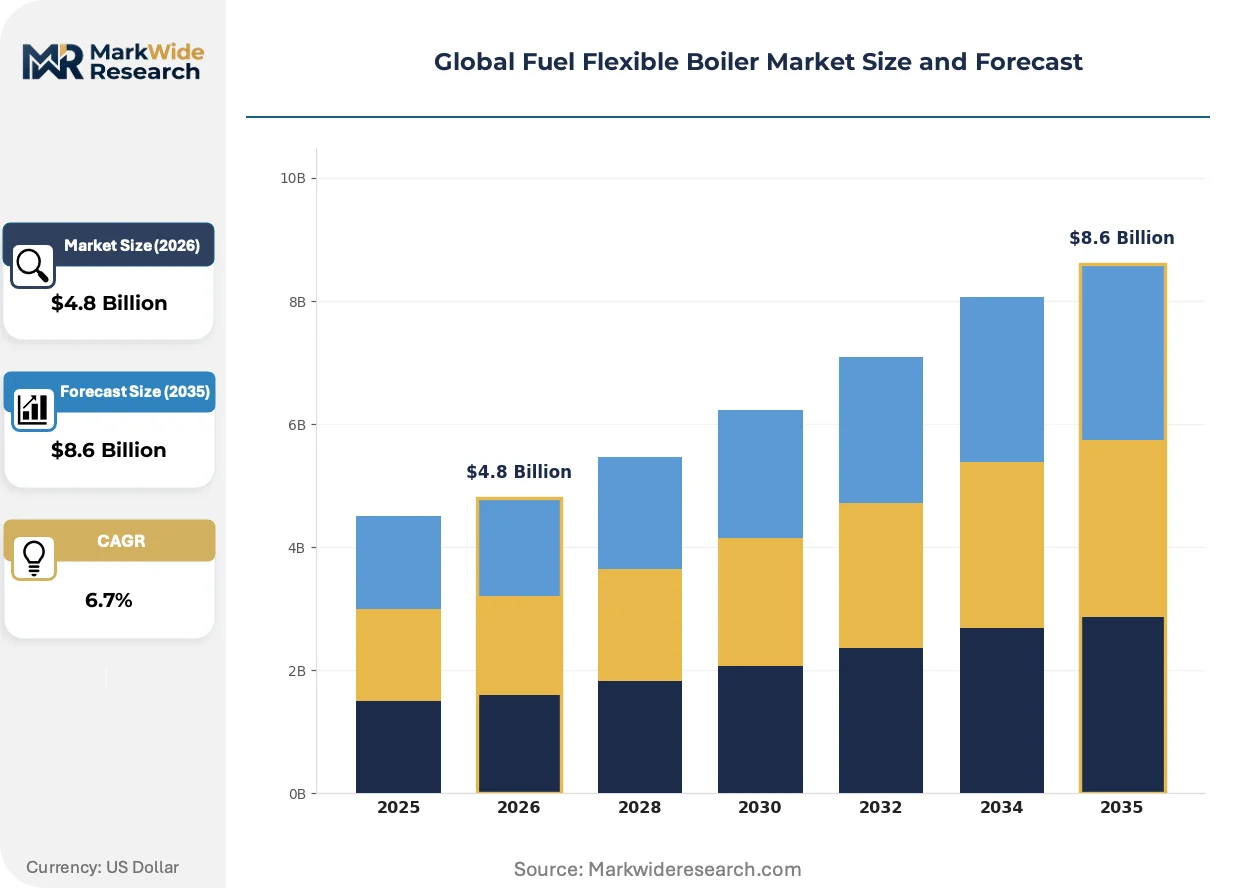
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Natural Gas, Oil, Biomass, Coal Industry Application: Power Generation, Manufacturing, Food Processing, Healthcare Installation Type: Onshore, Offshore, Modular, Fixed Control System: Manual, Automated, Smart, Hybrid |
| Companies Covered | AE&E Nanjing Boiler Co., Ltd., Bharat Heavy Electricals Limited, Doosan Heavy Industries & Construction Co. Ltd., Mitsubishi Hitachi Power Systems, Ltd., Babcock & Wilcox Enterprises Inc., Siemens AG, Alfa Laval Corporate AB, Andritz AG, General Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuel Flexible Boiler Market Emerging Trajectories
Combustion control architectures are migrating from analog PID loops to machine-learning inference at the edge, compressing fuel-switching transition times from hours to minutes while embedding emissions compliance into the real-time operating envelope.
Advanced burner management systems are digitizing flame characterization through spectral imaging and acoustic sensing arrays. US independent power producers deploy these packages at combined-cycle plants in Texas and Pennsylvania to arbitrage hourly natural gas and fuel oil price spreads. The technology is digitizing dispatch economics by enabling automated fuel selection based on marginal cost signals from regional transmission operators.
REACH authorization timelines for chromia-alumina refractories are forcing European boiler operators toward zirconia-based lining materials with shorter qualified supplier lists. German TÜV certification bodies have expanded inspection scopes to cover trace element migration from new ceramic formulations. Industrial heat users in the Ruhr and Saxony regions are responding by consolidating maintenance contracts with full-service refractory OEMs that carry inventory risk.
Asset-light service contracting is displacing traditional equipment ownership in North American pulp and paper mills. Boise Cascade and Georgia-Pacific now source steam through 15-year energy-as-a-service agreements where vendors retain boiler title and bear fuel price risk. The model concentrates procurement authority at corporate sustainability offices rather than mill engineering departments, privileging suppliers with balance-sheet capacity for long-dated power purchase hedges.
Global Fuel Flexible Boiler Market Segmentation
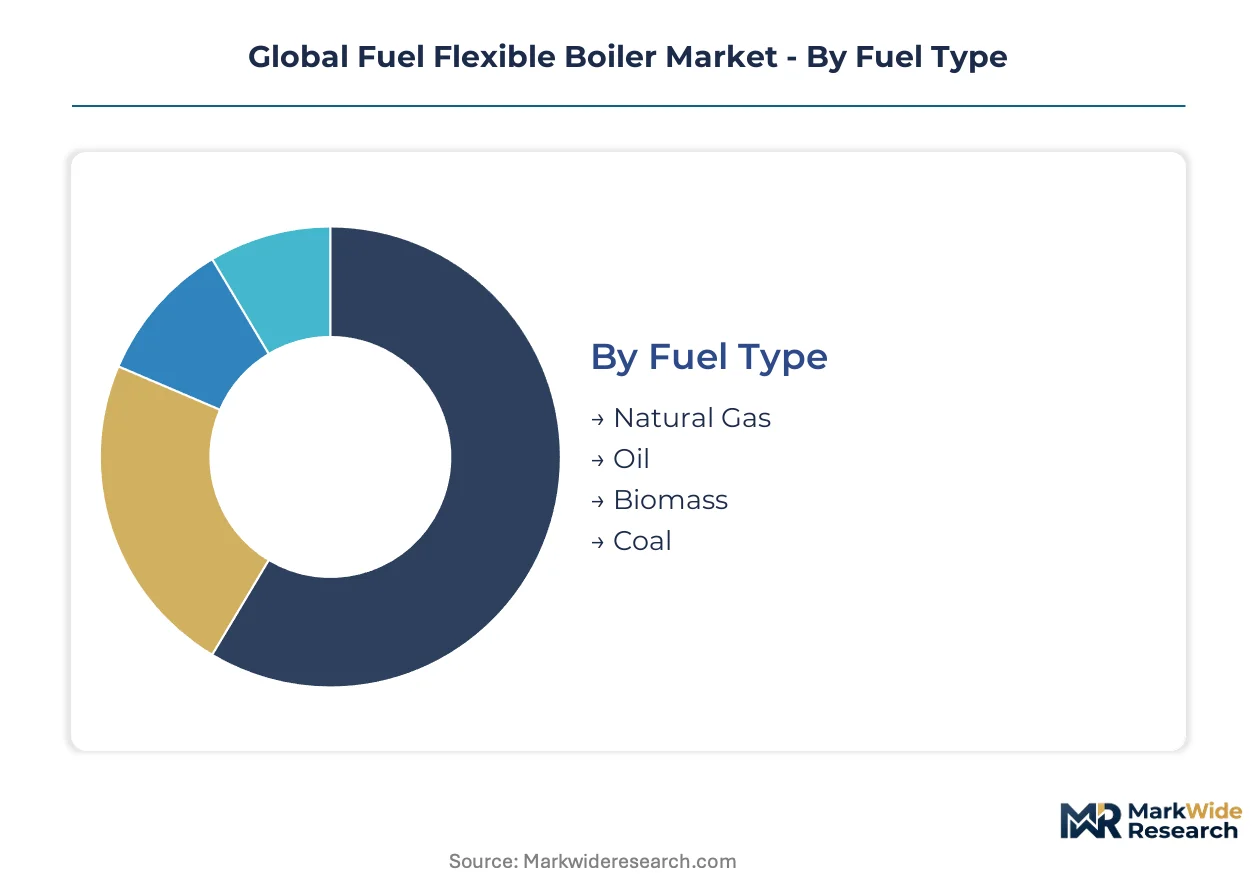
Segmentation in fuel flexible boilers reveals how capital allocation splits between conversion economics and operational resilience. Each dimension—fuel, application, installation, and control—carries distinct procurement authority and margin structures.
Fuel Type:
Mature configurations dominate installed base while emerging alternatives reshape forward demand curves.
- Natural Gas:Burner systems optimized for methane combustion with rapid flame adjustment capabilities. US and German utilities concentrate procurement here, driven by lower retrofit capital requirements and pipeline infrastructure density.
- Oil:Heavy fuel oil and distillate configurations retain niche status for backup dispatch and remote installations. Maritime and island grid operators in Greece and Japan maintain residual demand for dual-fuel oil-gas systems.
- Biomass:Agricultural residue and wood pellet combustion units with specialized grate and feeding mechanisms. Polish and Danish power producers accelerate orders to meet EU carbon accounting thresholds.
- Coal:Pulverized fuel and circulating fluidized bed architectures for high-ash domestic reserves. Indian state utilities under CEA mandates blend local coal with gas imports, sustaining retrofit demand.
Natural Gas retains volume leadership; Biomass holds the steepest expansion curve.
Industry Application:
Application segmentation tracks where thermal load flexibility commands premium pricing versus commodity procurement.
- Power Generation:Utility-scale boilers rated above 100 MW with grid-synchronized dispatch protocols. Independent power producers in Texas and Pennsylvania prioritize automated fuel switching to arbitrage hourly price spreads.
- Manufacturing:Process steam systems for chemicals, pulp, and cement with batch-variable heat demand. German Ruhr Valley industrial clusters consolidate procurement through energy-as-a-service contracts.
- Food Processing:Sanitary steam generators with rapid temperature cycling for dairy and meat operations. US dairy cooperatives leverage IRA biogas credits for dual-fuel boiler investments.
- Healthcare:Redundant steam supply for sterilization and HVAC with 99.9% uptime requirements. Hospital systems in France and Italy specify manual-automated hybrid controls for emergency protocols.
Power Generation commands the largest equipment value per installation; Food Processing shows the fastest adoption of smart control premiums.
Installation Type:
Installation architecture determines project finance structure and supplier working capital exposure.
- Onshore:Ground-mounted utility boilers with conventional civil works and direct fuel pipeline connections. Standard configuration for German and Indian retrofit markets.
- Offshore:Platform-integrated steam systems for oil and gas processing with space-constrained modular designs. North Sea operators specify these for enhanced oil recovery steam injection.
- Modular:Skid-mounted, shop-fabricated units with reduced field construction duration. Vietnamese Mekong Delta industrial zones favor these for palm-waste co-firing projects.
- Fixed:Permanent brick-and-mortar installations with 30-year asset life assumptions. Traditional procurement for US manufacturing and healthcare facilities.
Fixed installations retain volume leadership; Modular configurations gain share fastest in Southeast Asian greenfield development.
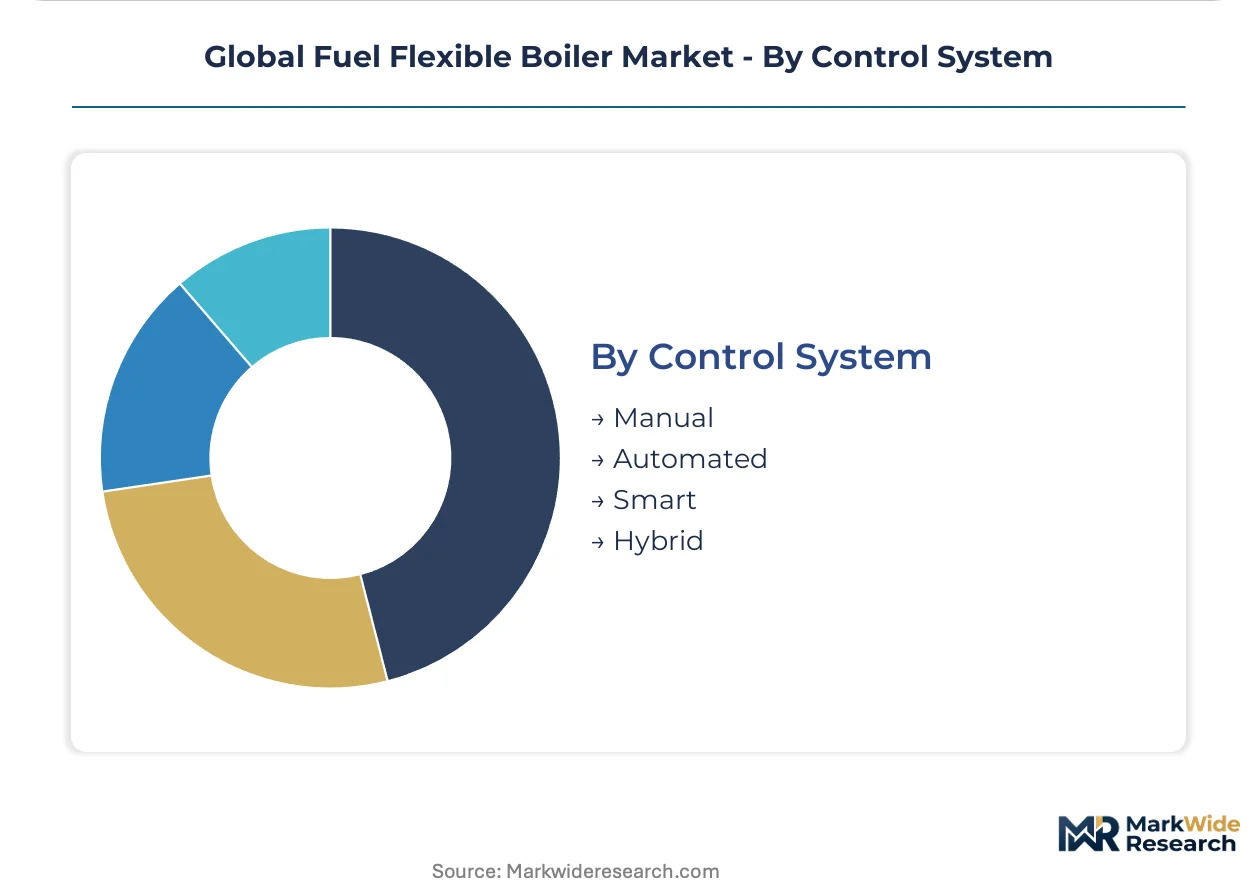
Control System:
Control sophistication separates commodity hardware from margin-accretive system sales.
- Manual:Operator-supervised fuel switching with mechanical linkage adjustments. Legacy systems in Eastern European district heating networks.
- Automated:PLC-based fuel ratio management with pre-programmed switching sequences. Standard specification for US EPA compliance retrofits.
- Smart:Machine-learning inference at the edge with real-time emissions optimization and predictive slagging detection. Siemens and Babcock & Wilcox compete here with digital twin integration.
- Hybrid:Manual override capability layered on automated base control for critical infrastructure. French and Italian healthcare regulators mandate this architecture.
Automated systems retain volume leadership; Smart controls capture the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power utilities and industrial operators in Germany, India, the United States, Poland, and Vietnam concentrate procurement authority for fuel flexible boiler systems. These buyers prioritize combustion hardware that arbitrages fuel price spreads while satisfying tightening emissions mandates.
Germany
Ruhr Valley industrial clusters and lignite-dependent utilities drive retrofit demand for biomass co-firing capabilities. The EU F-Gas Regulation and national coal phase-out legislation compel operators to certify multi-fuel systems before 2030 deadlines. Engineering procurement in North Rhine-Westphalia concentrates on TÜV-certified burner conversions for municipal district heating networks.
India
State-owned generation companies blend high-ash domestic coal with imported LNG to meet Central Electricity Authority efficiency benchmarks. The PLI scheme for clean energy components subsidizes control system upgrades at thermal stations. Procurement clusters in Maharashtra and Gujarat prioritize real-time fuel-ratio adjustment for grid-stabilizing dispatch.
United States
Independent power producers in Texas and Pennsylvania arbitrage hourly natural gas and residual fuel oil spreads through automated switching systems. EPA Mercury and Air Toxics Standards enforcement stimulates electrostatic precipitator-integrated boiler architectures. Dairy cooperatives in Wisconsin leverage IRA biogas production tax credits for dual-fuel investments.
Poland
Hard coal-dependent utilities retrofit for agricultural residue and wood pellet combustion to avoid EU carbon border adjustment taxes on exported power. National energy security directives mandate minimum fuel diversification thresholds for baseload plants. Silesian industrial zones consolidate procurement through energy-as-a-service contracts with full-service OEMs.
Vietnam
Mekong Delta industrial parks and coal-intensive manufacturing zones pivot toward palm-waste co-firing under national power development plan renewable thermal mandates. Modular skid-mounted configurations dominate greenfield procurement to compress construction timelines. Foreign EPC contractors partner with local fabricators to satisfy domestic content requirements.
Global Fuel Flexible Boiler Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base organizes around three strategic archetypes: integrated EPC contractors with balance-sheet capacity for project finance, specialized boiler engineering houses with combustion physics expertise, and digital control vendors with IoT-enabled optimization platforms. Dominant competitive moves include backward integration into superalloy furnace tubing supply and technology licensing partnerships for biomass grate systems.
Within the integrated EPC tier, Doosan Heavy Industries & Construction Co. Ltd. and Mitsubishi Hitachi Power Systems, Ltd. occupy positions that span fabrication through commissioning. Among specialized engineering houses, Babcock & Wilcox Enterprises Inc. exemplifies the utility-scale retrofit focus, while Siemens AG anchors the digital control convergence segment with machine-learning inference capabilities. These three names represent distinct competitive vectors without exhausting the vendor landscape.
| Leading Market Players |
|---|
| AE&E Nanjing Boiler Co., Ltd. |
| Bharat Heavy Electricals Limited |
| Doosan Heavy Industries & Construction Co. Ltd. |
| Mitsubishi Hitachi Power Systems, Ltd. |
| Babcock & Wilcox Enterprises Inc. |
| Siemens AG |
| Alfa Laval Corporate AB |
| Andritz AG |
| General Electric Co. |
| Others |
Supply Flow & Price Mechanics
Nickel alloy export quota volatility from Indonesian and Philippine ore processors determines both the premium commanded by TÜV-certified multi-fuel systems and the geographic distribution of boiler OEM assembly capacity. Buyers facing 18-month order backlogs for superalloy furnace tubing accept cost-plus contracts with raw material indexation, while suppliers without captive nickel sourcing concede margin in standard burner configurations.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate project finance structures for utility-scale retrofits. Three-tier pricing structure across premium, standard, and economy levels separates smart control-integrated systems from automated PLC-based units and manual legacy configurations. Price differentiation hinges on ASME Section I certification tier and bundled predictive maintenance service contracts. Cost compression in economy-tier manual systems is intensifying because Indian state utilities prioritize heat-rate compliance over control sophistication. Hospital systems in France and Italy show least price sensitivity due to 99.9% uptime mandates, while Vietnamese Mekong Delta industrial zones exhibit highest sensitivity given domestic content requirements and compressed construction timelines.
Supply Chain Analysis
Export-control restrictions on advanced combustion modeling software limit CFD simulation tool flows to Chinese boiler fabricators, constraining design throughput for multi-fuel flame stability optimization. Geographic supply concentration centers on Germany for precision burner engineering, South Korea for integrated EPC fabrication, and Indonesia for nickel superalloy feedstock. Raw material dependencies encompass chromia-alumina refractories subject to REACH authorization delays, zirconia-based ceramic linings with qualified supplier list concentration, and electrostatic precipitator components anchored in US EPA compliance engineering. Single-source vulnerability runs through Indonesian nickel ore processing quota allocations. Distribution runs through full-service OEMs carrying inventory risk for Silesian industrial zone operators and energy-as-a-service providers retaining boiler title for North American pulp and paper mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where ASME Section I certification entrenchment creates switching costs that freeze project finance draws for 14-18 month third-party review cycles. Regulatory compliance timelines function as structural barriers that privilege incumbents with established TÜV and EPA approval track records.
For Market Incumbents: Pre-empt heat pump substitution threats in Scandinavian district heating networks by embedding electrostatic precipitator integration at the furnace level, cutting retrofit compliance costs for US utilities facing EPA Mercury and Air Toxics Standards enforcement. Capture backward integration into superalloy furnace tubing supply to neutralize Indonesian export quota volatility, or consolidate maintenance contracts with full-service refractory OEMs carrying zirconia-based lining inventory risk for German Ruhr Valley industrial clusters. For New Entrants and Emerging Players: Mid-market food processing facilities in Vietnam's Mekong Delta industrial parks represent the most penetrable entry point, given national power development plan mandates for 20% renewable thermal share and foreign EPC contractor partnership requirements for domestic content compliance. Modular skid-mounted configurations for palm-waste co-firing projects offer a go-to-market angle that compresses construction timelines and sidesteps fixed installation incumbency. US dairy cooperatives leveraging IRA biogas production tax credits present a secondary white-space target for dual-fuel boiler investments with automated biogas injection capabilities. For Investors and Strategic Acquirers: EU F-Gas Regulation implementation reshapes the acquisition landscape by accelerating certified multi-fuel boiler orders for German and Polish coal unit retrofits ahead of 2030 deadlines. Long-term viability over the next decade rests on positioning for carbon border adjustment mechanism expansion across power trade corridors. Acquisition targets should display integrated EPC capabilities with balance-sheet capacity for project finance, or specialized combustion physics expertise concentrated at university lab partnerships. The signal to watch is REACH authorization timeline compression for chromia-alumina refractories, which would force European boiler operators toward zirconia-based lining materials and consolidate procurement authority with full-service refractory OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Superalloy Supply | Captive ore processing insulates Doosan and Mitsubishi Hitachi from Indonesian export quota volatility. |
| Digital Twin Convergence for Predictive Slagging | Siemens and Babcock & Wilcox attach premium service rates to machine-learning inference at the edge. |
| Energy-as-a-Service Contract Expansion | Boise Cascade and Georgia-Pacific shift procurement authority to corporate sustainability offices. |
| Biomass Grate System Technology Licensing | Polish and Danish power producers accelerate orders to meet EU carbon accounting thresholds. |
| ASME Section I Certification Fast-Track Investment | Third-party review cycle compression unlocks project finance draws for working capital-constrained developers. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads, then refined through secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up unit economics triangulated with top-down regulatory scenario modeling across fuel source, generation capacity tier, and regional grid type segmentation.
Demand-supply balance framing anchored the analytical approach across the analysis window, with CAGRs derived from installation type splits between fixed, modular, offshore, and onshore configurations. Control system sophistication tiers—manual, automated, smart, hybrid—provided cross-segment calibration points alongside fuel type transitions from natural gas dominance toward biomass co-firing acceleration.
Macroeconomic conditions sit as an overlay; deviation in nickel alloy commodity pricing, REACH authorization timelines, or IRA biogas credit durability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and EPC contractor balance-sheet capacity. Material shifts in EU carbon border adjustment mechanism scope or Indonesian nickel export regime would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
GCC Electric Water Heater Market
Boilers
Gas Fired Boilers Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Global Marine Boilers Market
Boilers
Electric Boiler Market
Boilers
Gas Condensing Boiler Market
Boilers
District Heating Market
Boilers
Biomass Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Global Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Space Heating Boilers Market
Boilers
Global Domestic Boilers Market
Boilers
Waste Heat Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Reformer Unit Market