
 Boiler Combustion Chamber Market | 2026-2036
Boiler Combustion Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler Combustion Chamber Market Analysis
Modular combustion chamber bundling with pre-assembled burner systems is consolidating buyer preference across industrial procurement channels. Viessmann Werke GmbH & Co. KG leverages its European manufacturing footprint to anchor premium indoor installations. General Electric Company competes on technology leadership in large-scale power generation configurations. Hurst Boiler & Welding Company, Inc. specializes in custom horizontal designs for North American manufacturing clients.
A boiler combustion chamber is the enclosed vessel where fuel-air mixture ignites and burns to generate thermal energy, typically fabricated from steel or cast iron alloys rated for temperatures exceeding 1,100°C and pressures up to 200 bar, serving as the core heat source for steam generation in power plants, factories, and marine propulsion systems. Stainless steel segments command margin pools where corrosion resistance extends operational lifespan in high-sulfur fuel environments. Modular product types represent the fastest-growing configuration as plant operators prioritize reduced field assembly time and faster commissioning schedules. Cast iron retains mature demand in residential boiler segments where lower thermal cycling stress permits thinner wall construction.
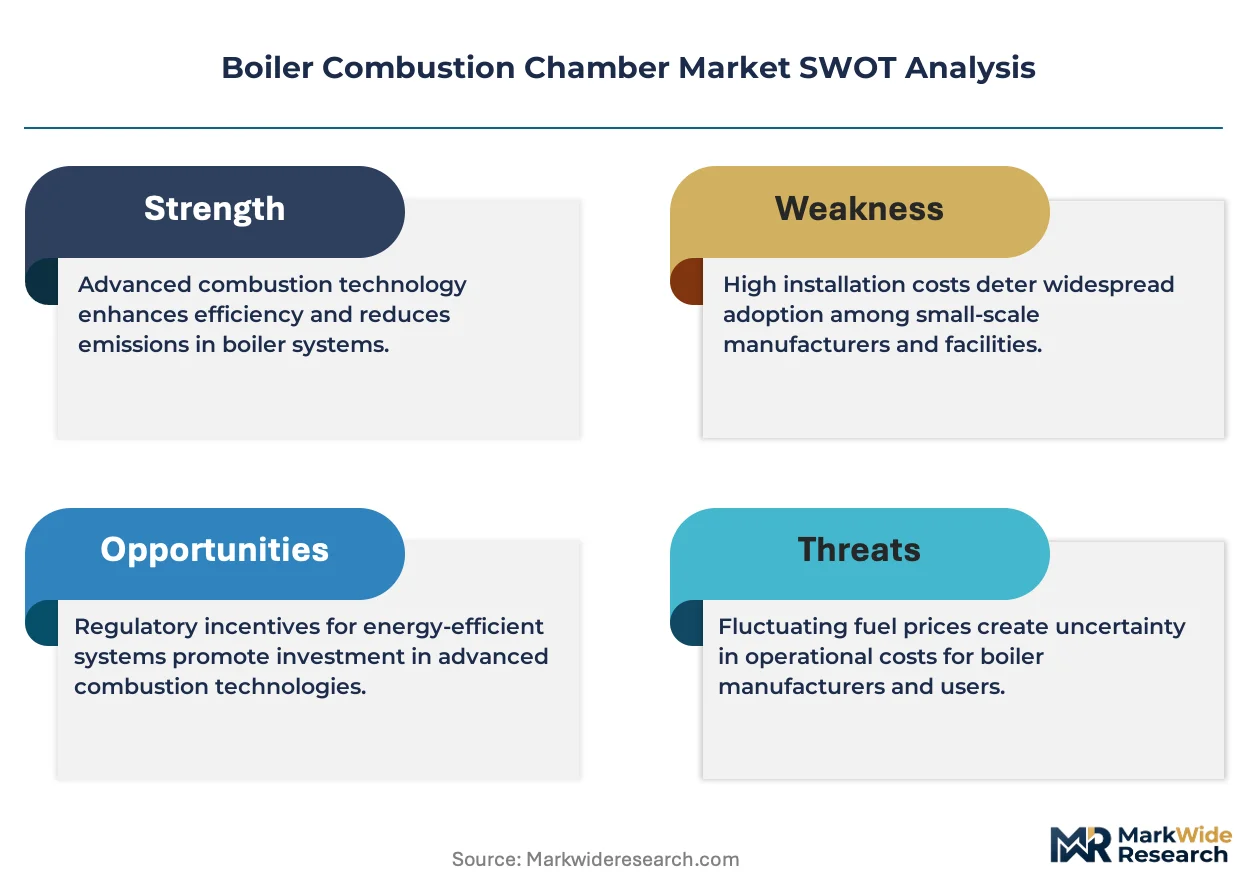
EPA emissions standards under the Clean Air Act and the EU F-Gas Regulation restrict NOx and particulate outputs from industrial combustion systems, forcing chamber redesigns toward staged combustion and flue gas recirculation architectures. India's Central Pollution Control Board enforces emission norms for boiler installations exceeding defined thermal capacities, creating compliance-driven replacement cycles across state-level manufacturing corridors. Stakeholders must monitor evolving metallurgical standards from ISO and ASME that govern creep resistance and weld integrity under cyclic thermal loading.
Market Dynamics
Modular combustion chamber architectures are compressing field assembly timelines and forcing incumbent fabricators to reconfigure production lines around pre-integrated burner-chamber bundles rather than standalone vessel sales.
Growth Catalysts
- EPA Clean Air Act amendments:Staged combustion mandates for NOx reduction are accelerating replacement cycles across US power generation fleets, particularly for coal-fired units exceeding 250 MW thermal capacity.
- Biomass co-firing retrofits:European utilities are converting existing pulverized coal boilers to biomass blends, requiring chamber redesigns for lower flame temperatures and higher particulate loads.
- India's Central Pollution Control Board norms:Emission limits for boilers above 10 TPH capacity are triggering compliance-driven procurement waves across Maharashtra and Gujarat manufacturing corridors.
Market Restraints
- Nickel alloy price volatility:Superalloy costs for creep-resistant chamber linings fluctuate with Indonesian ore export policies, squeezing margin pools on high-pressure configurations.
- Specialized welder scarcity:ASME Section IX-certified fabricators concentrate in Germany, Japan, and South Korea, creating bottlenecks for large-diameter vessel production.
- Heat pump substitution:Commercial building operators below 5 MW thermal demand are bypassing boiler investments entirely for electric heat pump systems.
Strategic Opportunities
- EU Green Deal industrial heat funding:Carbon border adjustment mechanisms and Innovation Fund grants are subsidizing hydrogen-ready combustion chamber pilots in Rotterdam and Antwerp port clusters.
- Marine dual-fuel conversions:LNG-hydrogen flexible burners are opening new vessel categories for cruise ship and container propulsion retrofits.
- Digital twin integration:CFD modeling platforms from ANSYS and Siemens are enabling remote chamber optimization services, unbundling from hardware sales.
Industry Challenges
- ASME stamp certification timelines:Third-party inspection backlogs for Section VIII pressure vessel approvals now extend 14-18 months, delaying project commissioning.
- Legacy DCS integration complexity:New burner management systems must interface with 1980s-vintage distributed control architectures common in US Midwest power plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler Combustion Chamber Market |
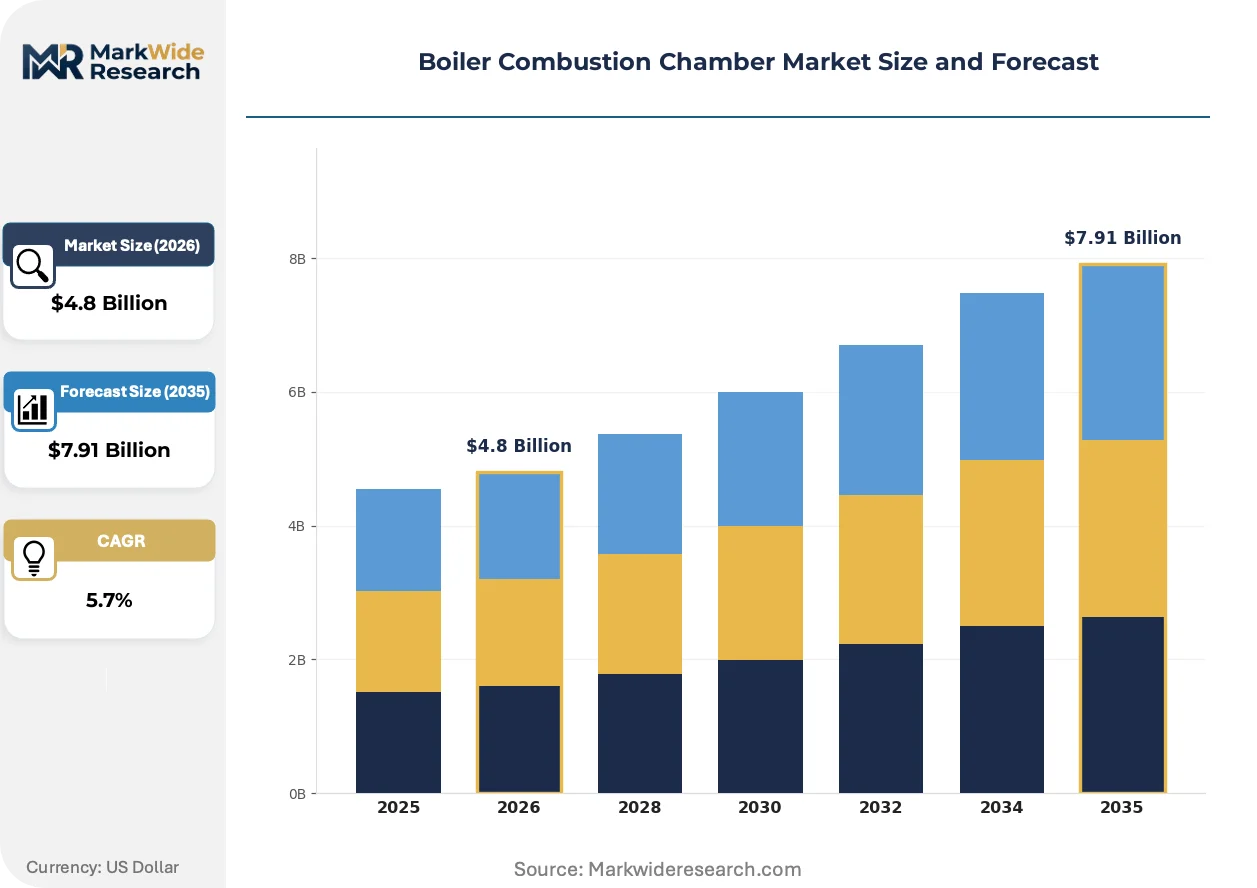
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Modular, Custom Material: Steel, Cast Iron, Stainless Steel, Composite End User: Power Generation, Manufacturing, Marine, Residential Installation Type: Indoor, Outdoor, Compact, Retrofit |
| Companies Covered | Thermax Limited, Viessmann Werke GmbH & Co. KG, General Electric Company, Hurst Boiler & Welding Company, Inc., Cleaver-Brooks, Inc., Mitsubishi Heavy Industries, Ltd., Bosch Industriekessel GmbH, IHI Corporation, Babcock & Wilcox Enterprises, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler Combustion Chamber Market Emerging Trajectories
Computational fluid dynamics and additive manufacturing are converging to reshape how combustion chambers are designed, tested, and produced, compressing development cycles while enabling geometries impossible with conventional fabrication.
Ceramic matrix composite liners are integrating into high-temperature zones previously reserved for castable refractory, enabling operating temperatures above 1,400°C without metallic creep failure. Aerospace-derived SiC-SiC composites from CoorsTek and Rolls-Royce subsidiaries are penetrating industrial gas turbine-derived boiler configurations first. This material transition is integrating thermal barrier coatings with structural load-bearing functions, eliminating separate insulation layers and reducing chamber wall thickness by 30-40 percent.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is forcing refrigerant-based flue gas heat recovery systems toward CO2 transcritical cycles, which in turn demands corrosion-resistant chamber outlet designs for acidic condensate environments. Industrial boiler operators in Germany and Poland are retrofitting stainless steel lower sections to accommodate these new heat pump couplings. The regulatory pressure is concentrating procurement specifications around 316L and duplex 2205 grades for condensing operation.
Utility procurement departments are unbundling long-term service agreements from initial equipment purchases, treating combustion chamber maintenance as a separate competitive tender. European power generators now separate 10-year parts-and-labor contracts from CAPEX decisions, enabling specialized aftermarket providers to compete with OEM service arms. This behavioral shift is most pronounced in the UK and Netherlands, where unbundled service contracts now cover 60 percent of new CCGT boiler installations.
Boiler Combustion Chamber Market Segmentation
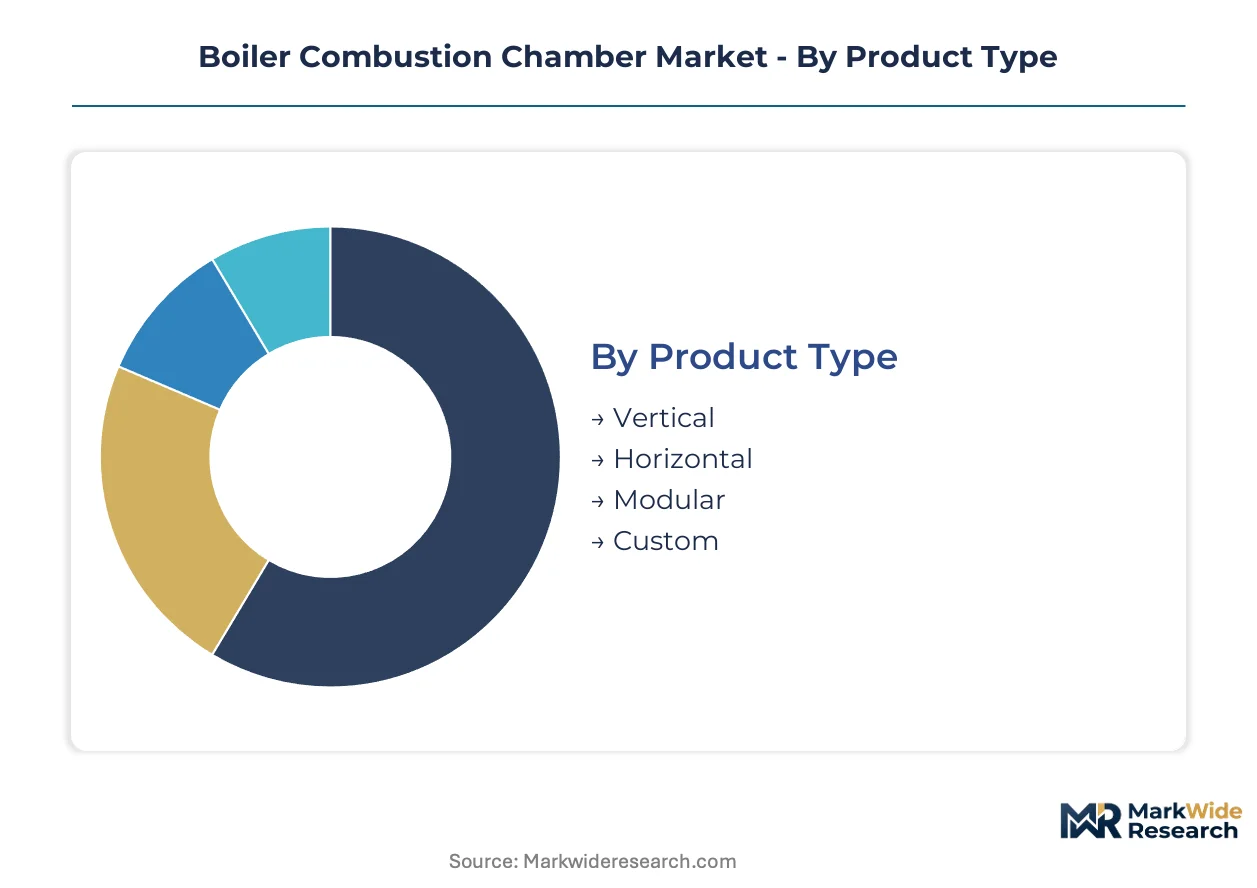
Boiler combustion chamber procurement splits sharply between commodity volume plays and engineered premium positions. Material selection and installation geometry determine margin pools more than end-use application alone.
Product Type:
Horizontal configurations dominate legacy industrial footprints, while modular architectures command premium positioning through reduced field labor.
- Vertical:Space-constrained urban installations in Japan and South Korea favor these stack-efficient designs. Pharmaceutical and food processing plants in Osaka and Busan specify vertical chambers to minimize building envelope modifications.
- Horizontal:These cylindrical vessels with longitudinal burner firing accommodate higher thermal loads in US Midwest power corridors. Coal-to-gas conversion projects across Ohio and Indiana specify horizontal retrofits to preserve existing boiler footprints and structural foundations.
- Modular:Pre-integrated burner-chamber bundles from European fabricators compress commissioning schedules by 40-60 percent. Rotterdam and Antwerp port clusters specify these for hydrogen-ready pilot installations.
- Custom:Bespoke geometries serve naval propulsion and specialized chemical processing where standard ASME stamp configurations fail.
Today's leader: Horizontal. Tomorrow's challenger: Modular.
Material:
Corrosion resistance premiums separate stainless from carbon steel, while composite adoption remains confined to demonstration projects.
- Steel:Carbon and alloy grades anchor baseline utility procurement, with SA-516 Grade 70 dominating sub-critical pressure ratings. Indian state power boards specify these for 500 MW thermal units across Maharashtra and Gujarat where sulfur content remains moderate.
- Stainless Steel:316L and duplex 2205 grades capture condensing boiler specifications under EU F-Gas Regulation pressure. German district heating operators in Berlin and Munich specify these for acidic condensate environments in flue gas heat recovery retrofits.
- Cast Iron:Residential and light commercial segments specify these for thermal cycling below 400°C where wall thickness tolerances permit thinner construction.
- Composite:Ceramic matrix SiC-SiC liners from aerospace suppliers penetrate only high-temperature gas turbine derivatives above 1,400°C.
Steel retains volume dominance. Stainless steel gains share fastest in regulated markets.
End User:
Power generation concentrates procurement scale, while marine applications sustain margin through certification complexity.
- Power Generation:Utilities above 250 MW thermal capacity drive staged combustion mandates under EPA Clean Air Act amendments. US independent power producers across Texas and Pennsylvania anchor replacement cycles for NOx-compliant chamber redesigns.
- Manufacturing:Process heat demand from cement, steel, and chemical plants concentrates in India's Central Pollution Control Board enforcement corridors. Textile processors in Surat and chemical complexes in Vadodara trigger compliance-driven procurement above 10 TPH capacity thresholds.
- Marine:LNG-hydrogen flexible burners for cruise ship and container propulsion require dual-fuel chamber architectures certified by classification societies.
- Residential:Condensing boilers below 50 kW thermal demand specify cast iron and aluminum heat exchangers rather than industrial-grade combustion chambers.
Power generation commands CAPEX scale. Manufacturing delivers replacement velocity.
Installation Type:
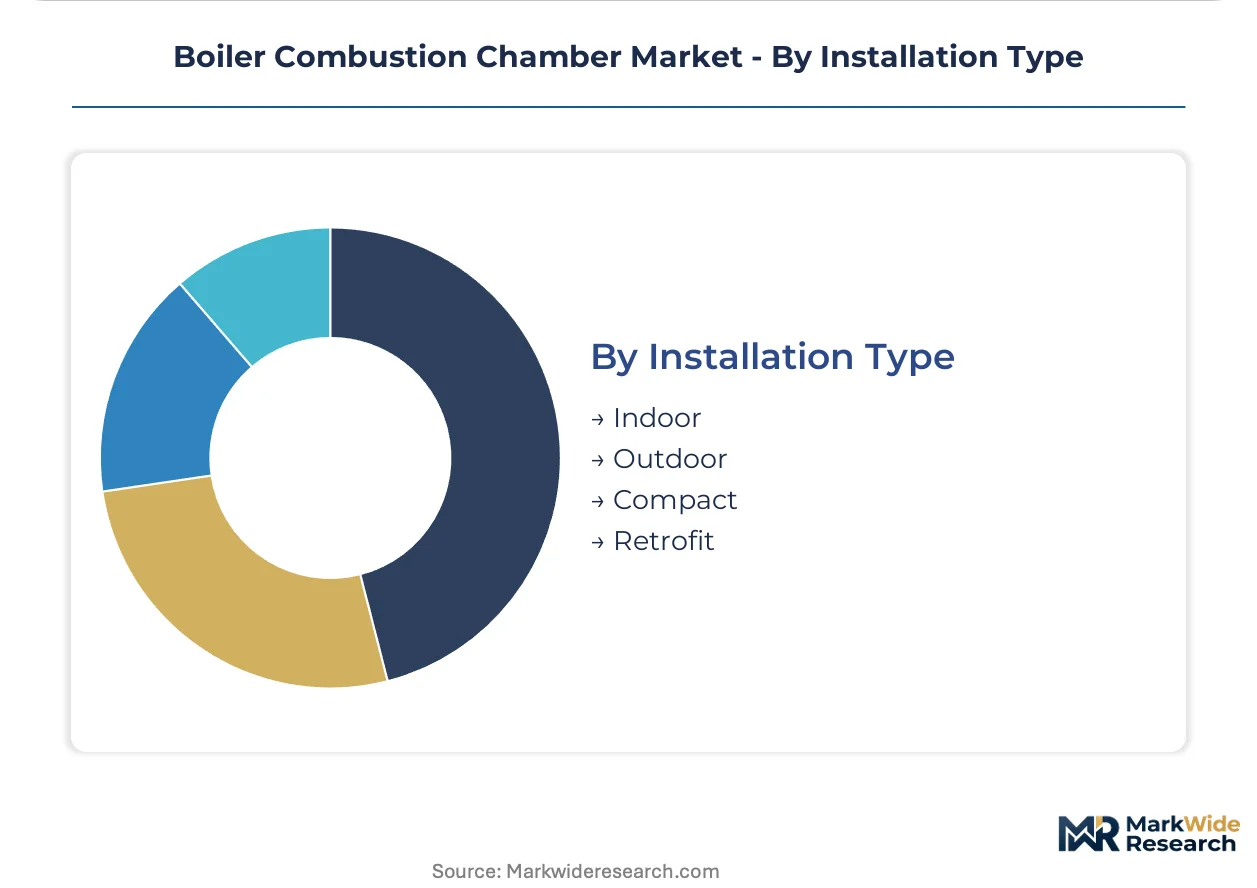
Retrofit specifications outnumber greenfield in mature industrial economies, while compact designs penetrate distributed generation.
- Indoor:European premium positioning from German and Austrian manufacturers targets controlled-environment installations. Viessmann Werke anchors this segment through weather-independent quality assurance.
- Outdoor:US utility and petrochemical sites in Gulf Coast humidity specify these with enhanced weatherization and thermal insulation packages.
- Compact:Containerized and skid-mounted configurations serve remote mining and oilfield operations where permanent structures prove uneconomical.
- Retrofit:Chamber-in-chamber inserts preserve existing pressure vessel shells while upgrading combustion performance. US Midwest plants with 1980s-vintage distributed control systems specify these to avoid full DCS replacement.
Retrofit dominates mature markets. Compact configurations expand in resource extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The boiler combustion chamber industry traces its modern scale to German and Austrian engineering traditions that standardized cast iron and steel vessel fabrication for district heating networks during the post-war reconstruction era. These manufacturing foundations established the metallurgical specifications and pressure vessel certifications that govern global procurement today. Contemporary demand patterns now concentrate in five national markets where regulatory enforcement and industrial retrofit cycles intersect.
United States
Independent power producers across Texas and Pennsylvania drive replacement cycles for coal-fired units exceeding 250 MW thermal capacity. EPA Clean Air Act amendments mandate staged combustion architectures for NOx reduction. Ohio and Indiana manufacturing corridors specify horizontal chamber retrofits to preserve existing boiler footprints during gas conversion projects.
Germany
District heating operators in Berlin and Munich prioritize condensing boiler specifications for flue gas heat recovery systems. EU F-Gas Regulation pressure accelerates stainless steel procurement for acidic condensate environments. The Eindhoven-Antwerp-Rotterdam port cluster anchors hydrogen-ready pilot installations with modular pre-integrated bundles.
India
State power boards across Maharashtra and Gujarat specify carbon steel chambers for 500 MW thermal units with moderate sulfur content. Central Pollution Control Board emission norms for boilers above 10 TPH capacity trigger compliance-driven procurement. Textile processors in Surat and chemical complexes in Vadodara anchor manufacturing corridor demand.
Japan
Pharmaceutical and food processing plants in Osaka favor vertical chamber configurations to minimize building envelope modifications. METI efficiency standards for industrial boilers concentrate procurement in space-constrained urban installations. The Kansai region's precision manufacturing base sustains demand for compact, stack-efficient designs.
South Korea
Busan-Ulsan industrial complexes specify vertical chambers for petrochemical and shipbuilding process heat applications. National emission enforcement for large combustion plants aligns with EU-equivalent efficiency mandates. Daegu-Gyeongbuk manufacturing zones drive replacement velocity for aging pulverized coal installations.
Boiler Combustion Chamber Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and fabrication complexity tiers. The vendor base stratifies between ASME-stamped fabricators serving utility procurement and regional specialists capturing residential and light commercial segments. Three archetypes dominate: integrated boiler OEMs with captive chamber production, standalone pressure vessel fabricators supplying retrofit inserts, and aerospace-derived composite suppliers penetrating ultra-high-temperature zones. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as hydrogen-ready designs reshape R&D allocation.
Among German and Austrian engineering groups, Viessmann Werke GmbH & Co. KG and Bosch Industriekessel GmbH occupy positions anchored by controlled-environment manufacturing footprints and weather-independent quality assurance protocols. Mitsubishi Heavy Industries, Ltd. and IHI Corporation represent Japanese integrated industrial conglomerates with captive boiler-chamber production serving domestic utility and export marine propulsion markets. Thermax Limited and Babcock & Wilcox Enterprises, Inc. exemplify regional scale specialists with concentrated exposure to India's compliance-driven procurement cycles and North American retrofit demand respectively.
| Leading Market Players |
|---|
| Thermax Limited |
| Viessmann Werke GmbH & Co. KG |
| General Electric Company |
| Hurst Boiler & Welding Company, Inc. |
| Cleaver-Brooks, Inc. |
| Mitsubishi Heavy Industries, Ltd. |
| Bosch Industriekessel GmbH |
| IHI Corporation |
| Babcock & Wilcox Enterprises, Inc. |
| Others |
Supply Flow & Price Mechanics
Nickel alloy superalloy costs for creep-resistant chamber linings cascade from Indonesian ore export policies through ASME-certified fabricator pricing tiers, compressing margin pools on high-pressure configurations while carbon steel segments absorb volume procurement at utility scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASME-stamped utility configurations from modular pre-integrated bundles and commodity carbon steel vessels. Price differentiation hinges on certification grade and after-sales service bundling, with stainless steel 316L and duplex 2205 commanding corrosion resistance premiums under EU F-Gas Regulation pressure. Cost compression in standard tiers is intensifying because Indonesian nickel export restrictions feed raw material volatility. Manufacturing corridors in India exhibit highest price sensitivity, while German district heating operators demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with ASME Section IX-certified welders concentrated in Germany, Japan, and South Korea, creating production bottlenecks for large-diameter vessels. Geographic supply concentration centers on Germany, India, and China for pressure vessel fabrication, with raw material dependencies drawing from Indonesian nickel, Australian iron ore, and Chinese steel semifinished products. Supply chain risk manifests as tariff exposure on specialty alloy imports into North American utility procurement. Distribution runs through EPC contractor channels for utility-scale projects and direct OEM relationships for industrial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in stainless steel premium tiers and modular pre-integrated bundles as regulatory compliance shifts procurement specifications away from commodity carbon steel.
For Market Incumbents: Deepen captive control over nickel alloy supply through long-term offtake agreements with Indonesian ore processors, insulating margin pools from export policy volatility. Expand ASME-certified welding capacity in India to capture compliance-driven procurement waves from Maharashtra and Gujarat manufacturing corridors. Heat pump substitution in sub-5 MW commercial segments threatens residential boiler adjacent markets. For New Entrants and Emerging Players: Ceramic matrix composite liner technology offers entry into ultra-high-temperature zones above 1,400°C previously reserved for aerospace-derived suppliers. Target hydrogen-ready pilot installations in Rotterdam and Antwerp port clusters where EU Green Deal funding reduces customer acquisition friction. Digital twin integration using ANSYS or Siemens CFD platforms enables unbundled service revenue without heavy manufacturing capital. For Investors and Strategic Acquirers: Consolidation pressure builds where ASME stamp certification timelines extend 14-18 months, favoring acquirers with existing third-party inspection relationships. Long-term viability favors vertically integrated fabricators with captive burner technology and aftermarket service arms. Watch for inflection when marine dual-fuel conversion contracts accelerate beyond cruise ship pilots into container propulsion retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Long-term offtake agreements with Indonesian processors stabilize input costs against export policy volatility. |
| Hydrogen-Ready Chamber Development | EU Green Deal funding in Rotterdam and Antwerp port clusters accelerates pilot installation demand. |
| Digital Twin Service Unbundling | Remote CFD optimization from ANSYS and Siemens platforms separates recurring revenue from hardware sales. |
| ASME Certification Capacity Expansion | Indian fabrication facilities capture compliance-driven procurement from Central Pollution Control Board enforcement. |
| Ceramic Matrix Composite Partnership | Aerospace-derived SiC-SiC technology from CoorsTek penetrates industrial gas turbine boiler configurations. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and EPC contractors combined trade data from customs authorities, ASME stamp registration databases, and EPA enforcement records. Secondary validation drew from SEC filings of listed boiler manufacturers, IEA industrial heat reports, and FERC power plant databases. Bottom-up vessel shipment tallies triangulated against top-down utility CAPEX disclosures.
Segment-level projections across material grade, product configuration, end-use application, and installation type fed into analytical framework outputs across the analysis window. CAGRs derived from regression against regulatory enforcement timelines, fleet age distributions, and fuel switching patterns. Forecast inputs incorporated nickel price volatility indices and ASME certification backlog durations.
The model holds under stable regulatory enforcement trajectories; deviation in EPA amendment timing or Indonesian export policy shifts would revise replacement cycle velocity. Forecasts reflect documented assumptions about hydrogen pilot conversion rates and composite material adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
GCC Electric Water Heater Market
Boilers
Global Package Boilers Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Industrial Boiler MRO Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Combi Boiler Market
Boilers
Steam Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
District Heating Market
Boilers
Utility Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Gas Fired Boilers Market
Boilers
Field Erected Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
North America Residential Boiler Market