
 Industrial Biomass Boiler Market | 2026-2036
Industrial Biomass Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Biomass Boiler Market Outlook
Multi-source fuel procurement is decoupling from traditional single-feedstock contracts across the industrial biomass boiler sector. ANDRITZ leverages its Austrian engineering base to dominate European pulp and paper retrofits. Babcock & Wilcox anchors North American utility-scale installations through its supercritical water-tube designs. Kohlbach Group specializes in decentralized combined heat and power systems for Central European sawmills.
An industrial biomass boiler is a combustion or gasification system designed to generate steam or hot water using organic feedstocks with moisture content typically below 50 percent and heating values ranging from 8 to 20 MJ per kilogram. These units serve district heating networks, process industries, and power plants seeking to displace coal or natural gas thermal output. Water-tube configurations command the premium segment due to higher pressure ratings and superheat capabilities required by power generation end users. Stoker-fired systems occupy the mature replacement cycle across food processing facilities where operational simplicity outweighs thermal efficiency targets. Fluidized bed technology is displacing grate-fired units in straw and agricultural residue applications where fuel variability demands superior combustion control.
The EPA enforces Maximum Achievable Control Technology standards for industrial boilers under the Clean Air Act, directly influencing NOx and particulate emission limits that shape burner design and flue gas treatment investments. The EU Green Deal and national carbon border adjustment mechanisms are tightening fossil fuel penalties, redirecting capital toward biomass thermal assets. Stakeholders must monitor feedstock cost volatility and evolving sustainability certification requirements for biomass sourcing.
Market Dynamics
Carbon border adjustment mechanisms are forcing industrial thermal operators to revalue fuel-switching timelines, compressing payback period calculations from seven years toward four across European heavy industry.
Growth Catalysts
- EU Green Deal carbon pricing:Industrial operators in Finland and Sweden face escalating fossil fuel penalties that accelerate biomass boiler procurement decisions.
- District heating network expansion:Municipal utilities across Germany integrate biomass thermal plants to meet renewable heat mandates under the Renewable Energy Directive.
- Fluidized bed combustion:This technology handles agricultural residue variability that stoker-fired systems cannot manage, opening feedstock supply to straw and energy crop producers.
Market Restraints
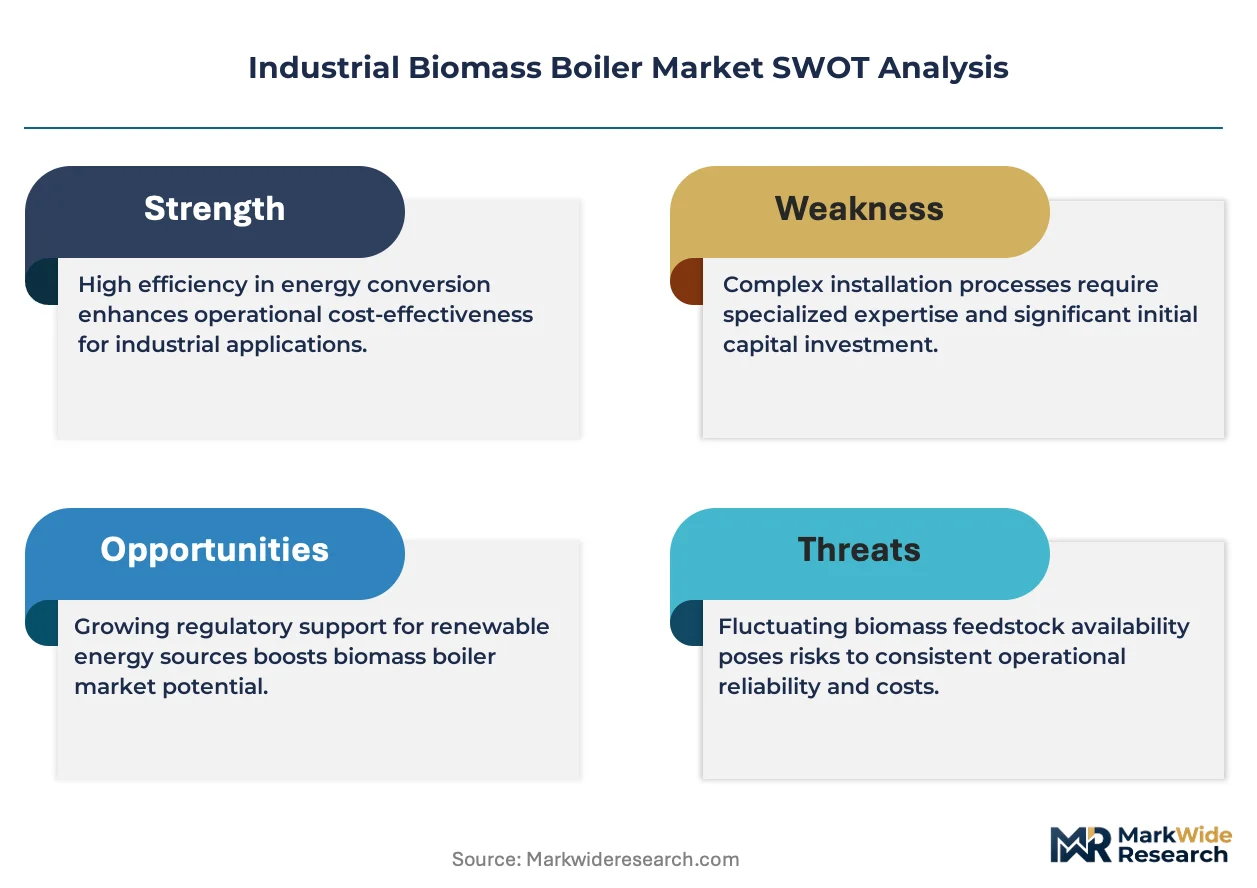
- Feedstock cost volatility:Wood pellet prices fluctuate with forestry harvest cycles and competing demand from residential heating sectors.
- High-pressure water-tube supply concentration:Specialized boiler fabrication capacity clusters in Austria and Germany, creating procurement bottlenecks for utility-scale projects.
- EPA Maximum Achievable Control Technology compliance:NOx and particulate limits under the Clean Air Act add flue gas treatment capital costs that disadvantage smaller industrial operators.
Strategic Opportunities
- US Inflation Reduction Act clean energy credits:Industrial facilities capture production tax incentives for biomass thermal systems displacing natural gas process heat.
- Pulp and paper black liquor integration:Chemical recovery boilers that co-fire biomass residues offer combined heat and power output with minimal incremental fuel cost.
- Carbon capture retrofits:Post-combustion capture systems attached to biomass boilers generate negative emission credits attractive to cement and steel producers.
Industry Challenges
- Combustion engineering talent scarcity:Fluidized bed design expertise concentrates among retiring specialists in Central European boiler houses.
- Sustainability certification complexity:Sourcing compliance with EU Timber Regulation and national biomass sustainability criteria extends procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Biomass Boiler Market |
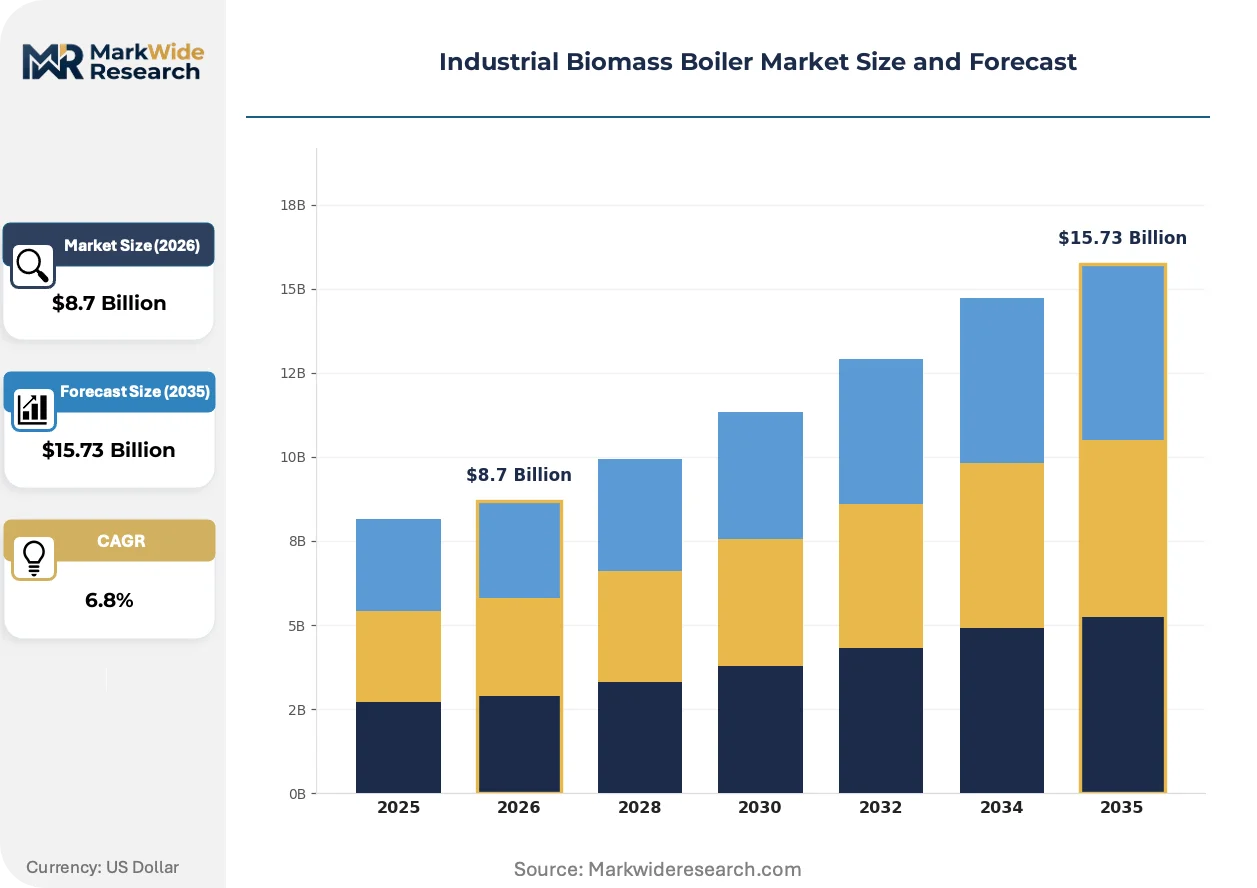
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-tube, Water-tube, Fluidized Bed, Stoker Fuel Type: Wood Chips, Agricultural Residues, Pellets, Energy Crops End User: Manufacturing, Power Generation, Pulp & Paper, Food Processing Technology: Combustion, Gasification, Pyrolysis, Anaerobic Digestion |
| Companies Covered | Dongfang Electric, ANDRITZ, Hurst Boiler, Kohlbach Group, Alstom, Babcock & Wilcox, Valmet, Harbin Electric, Thermax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Biomass Boiler Market Strategic Shifts
Automation and digital combustion control are redefining operational staffing models across industrial biomass installations, shifting value capture from hardware margins toward performance-guaranteed service contracts.
Advanced flue gas condensing technology is recovering latent heat from biomass combustion exhaust streams. District heating operators in Denmark and the Netherlands deploy these systems to push plant thermal efficiency past ninety percent. The technology is expanding into combined heat and power configurations where recovered heat displaces separate boiler capacity.
The EU F-Gas Regulation is phasing down fluorinated greenhouse gases used in biomass plant refrigeration and heat pump integration. Industrial operators face retrofit obligations for cooling systems attached to biomass-fired absorption chillers. Food processing facilities in Spain and Italy accelerate boiler upgrades to synchronize with F-Gas compliance timelines.
Multi-feedstock contracting is replacing single-species supply agreements. Paper mills in Sweden negotiate portfolios spanning forest residues, agricultural straw, and processed refuse-derived fuel. This sourcing flexibility commands premium boiler automation but insulates operators against individual feedstock price spikes.
Industrial Biomass Boiler Market Segmentation
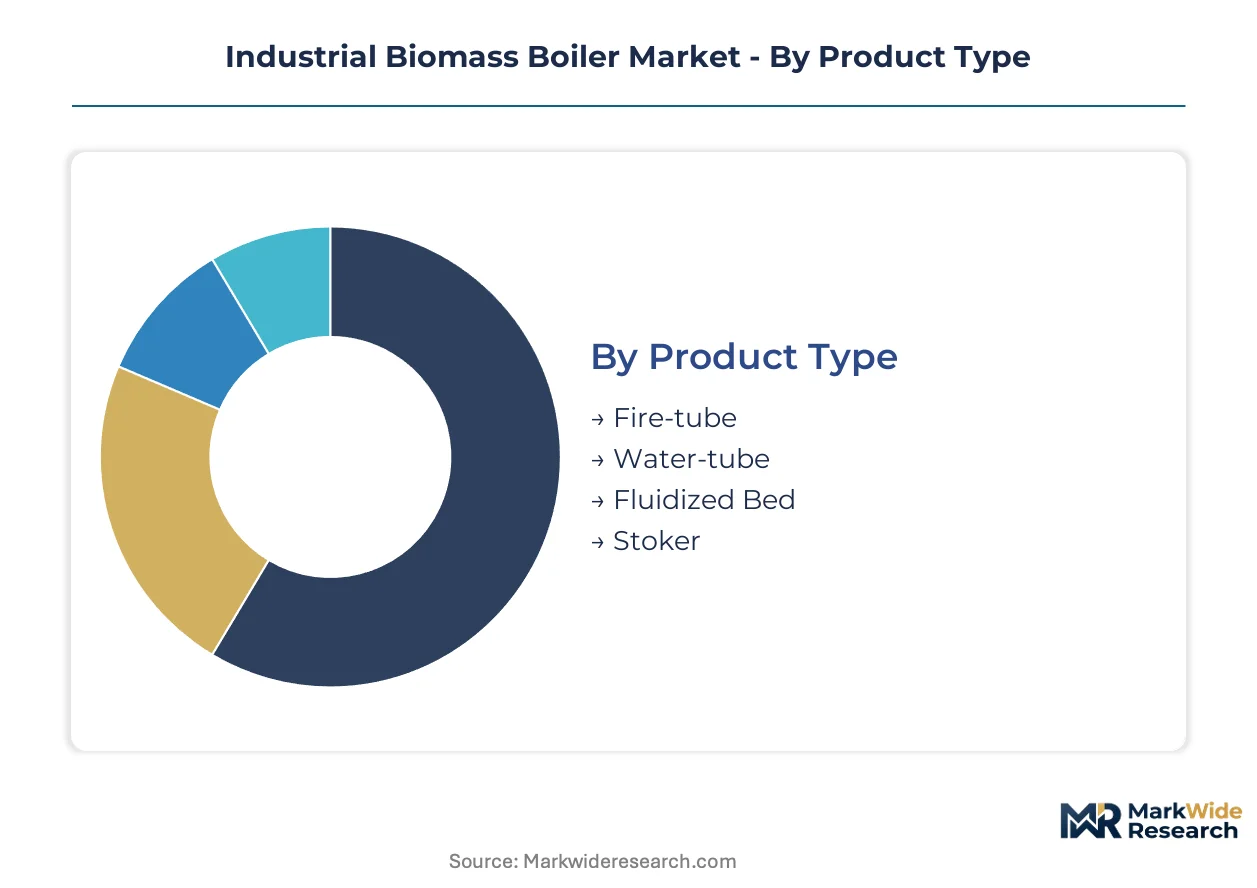
Industrial biomass boiler procurement decisions cluster around pressure ratings, fuel variability tolerance, and integration complexity with existing thermal infrastructure. Segmentation reveals where engineering margins concentrate and which configurations face commoditization pressure from standardized designs.
Product Type:
Supply concentration for high-pressure fabrication capacity in Austria and Germany shapes procurement timelines and premium pricing dynamics across boiler configurations.
- Water-tube:These systems circulate water through tubes surrounded by combustion gases, enabling supercritical steam conditions above 200 bar. Demand concentrates in Finnish and Swedish district heating networks where combined heat and power output justifies capital intensity. The EU Green Deal carbon border adjustments compress payback thresholds for these premium installations.
- Fluidized Bed:Suspended particle combustion delivers superior fuel flexibility for agricultural residues with moisture content variability. German municipal utilities and Danish district heating operators deploy these units to access straw and energy crop supply chains unavailable to grate-fired alternatives. The technology commands automation premiums but insulates operators against single-feedstock price spikes.
- Fire-tube:Shell-and-tube designs with lower pressure ratings serve small-scale food processing facilities in Italy and Spain where operational simplicity outweighs thermal efficiency targets.
- Stoker:Grate-fired mechanical feed systems occupy mature replacement cycles across Central European sawmills with consistent wood chip supply.
Today's leader: Water-tube. Tomorrow's challenger: Fluidized Bed.
Fuel Type:
Cost tier differentiation separates commoditized bulk fuels from certified premium feedstocks with traceability premiums attached.
- Pellets:Densified wood fuel with standardized moisture content below 10 percent and heating values near 17 MJ per kilogram. Scandinavian paper mills and Austrian district heating operators specify ENplus-certified pellets to satisfy EU Timber Regulation compliance. Residential heating competition creates price volatility that industrial buyers hedge through multi-year supply contracts.
- Wood Chips:Forest residue fuel with variable particle size and moisture content typically between 25 and 50 percent. Finnish and Swedish pulp mills integrate captive chip supplies from integrated forestry operations, minimizing incremental fuel procurement costs. The segment gains share where on-site chipping infrastructure exists.
- Agricultural Residues:Straw and corn stover combustion expands in Denmark and the Netherlands where district heating networks access seasonal farm supply.
- Energy Crops:Dedicated biomass cultivation including miscanthus and switchgrass remains marginal outside experimental German biogas co-combustion trials.
Pellets dominate premium applications. Wood Chips expand fastest in integrated forestry operations.
End User:
Application-driven segmentation reveals where thermal demand scale justifies boiler complexity and where standardized units suffice.
- Pulp & Paper:Chemical recovery boilers co-fire black liquor with biomass residues to deliver combined heat and power with minimal incremental fuel cost. Scandinavian mills in Finland and Sweden anchor demand for high-pressure water-tube configurations integrated with recovery furnace technology. The sector captures carbon capture retrofit potential for negative emission credits.
- Power Generation:Utility-scale installations in Germany and Austria require supercritical steam conditions and flue gas treatment systems compliant with EU Industrial Emissions Directive limits. These projects face procurement bottlenecks from concentrated fabrication capacity.
- Manufacturing:Cement and steel producers in Poland and the Czech Republic evaluate biomass thermal systems for process heat displacement under tightening EU carbon pricing.
- Food Processing:Low-pressure steam demand in Spanish and Italian facilities favors operational simplicity over thermal efficiency optimization.
Pulp & Paper leads capital deployment. Power Generation faces supply constraints.
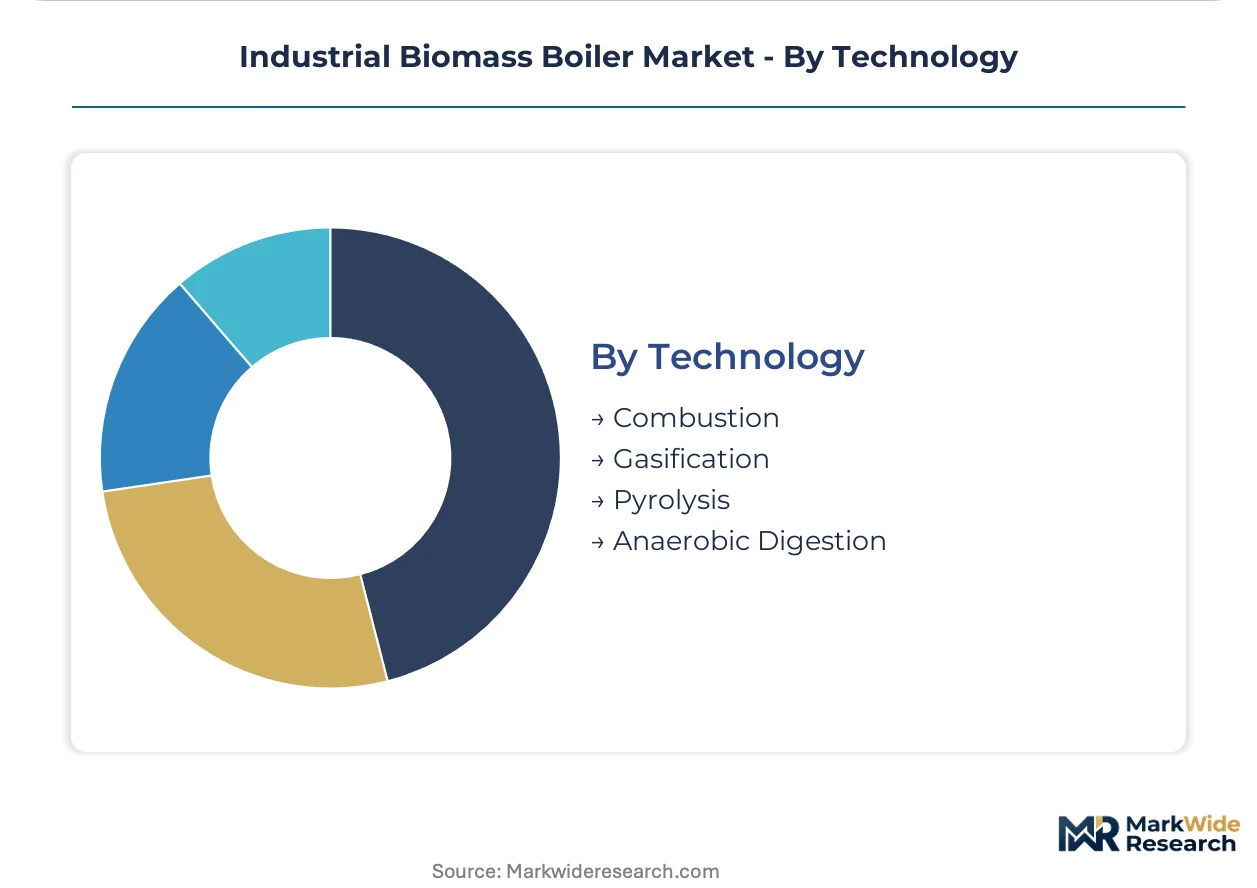
Technology:
Maturity curves separate proven combustion pathways from emerging conversion technologies with scale-up risk profiles.
- Combustion:Direct firing of solid biomass in grate, fluidized bed, or suspension configurations delivers thermal output with commercial maturity across all pressure ratings. Finnish and German engineering houses dominate combustion system design for district heating and industrial process heat applications. The technology captures IRA production tax credits in US installations displacing natural gas.
- Gasification:Partial oxidation to syngas enables higher efficiency combined cycle operation but remains concentrated in pilot demonstrations outside commercial scale.
- Pyrolysis:Thermal decomposition to bio-oil and char serves niche biofuel preprocessing with limited direct boiler integration.
- Anaerobic Digestion:Wet biomass conversion to biogas operates adjacent to boiler markets in agricultural waste processing facilities.
Combustion holds installed base dominance. Gasification carries scale-up uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting biomass boiler procurement toward jurisdictions where carbon pricing penalties and renewable heat mandates create the steepest cost-of-compliance gaps for fossil fuel thermal systems.
Germany
Municipal utilities in Bavaria and North Rhine-Westphalia integrate biomass thermal plants into district heating networks to satisfy Renewable Energy Directive mandates. The EU Green Deal carbon border adjustments compress payback calculations for industrial operators switching from natural gas. Engineering clusters around Munich and Cologne anchor fabrication capacity for high-pressure water-tube configurations.
Finland
Pulp and paper mills in the Kymenlaakso and Central Finland regions replace fossil fuel steam systems with biomass-fired generation integrated with black liquor recovery. National carbon pricing schemes escalate penalties on coal and oil thermal output. The Lahti and Jyväskylä industrial corridors concentrate demand for supercritical boiler installations.
Sweden
Scandinavian paper producers in the Västra Götaland and Norrland regions leverage integrated forestry operations to secure captive wood chip supplies for biomass steam generation. EU Timber Regulation compliance requirements shape feedstock certification protocols. The Gothenburg and Sundsvall clusters drive procurement of fluidized bed systems handling agricultural residue variability.
United States
Industrial facilities in the Pacific Northwest and Southeast evaluate biomass thermal systems to capture Inflation Reduction Act production tax credits displacing natural gas process heat. EPA Maximum Achievable Control Technology standards under the Clean Air Act influence NOx emission limits and flue gas treatment investments. The Portland and Atlanta metropolitan areas concentrate utility-scale installation demand.
Denmark
District heating operators in Copenhagen and Aarhus deploy advanced flue gas condensing technology to push plant thermal efficiency past ninety percent. National renewable heat targets accelerate biomass boiler procurement timelines for municipal utilities. The Zealand and Jutland regions integrate straw and energy crop supply chains into fluidized bed combustion configurations.
Industrial Biomass Boiler Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue carbon capture retrofits and multi-feedstock automation as differentiation vectors. The vendor base stratifies across Austrian-German engineering houses dominating high-pressure fabrication, Nordic specialists anchoring pulp and paper integration, and Asian conglomerates scaling utility-class output. Two strategic archetypes predominate: integrated technology licensors bundling combustion systems with environmental controls, and regional fabricators capturing proximity advantages in district heating procurement. Competitive moves concentrate on backward integration into feedstock logistics and technology licensing partnerships for fluidized bed designs.
Among European engineering specialists, ANDRITZ and Babcock & Wilcox exemplify contrasting archetypes within premium-tier positioning. ANDRITZ leverages its Austrian base to represent integrated technology licensing across pulp and paper retrofits. Babcock & Wilcox occupies a position anchoring North American utility-scale installations through supercritical water-tube specialization. Kohlbach Group sits within the decentralized combined heat and power segment, exemplifying regional fabrication proximity to Central European sawmill demand. These three names illustrate how geographic origin and corporate structure map onto distinct competitive vectors without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Dongfang Electric |
| ANDRITZ |
| Hurst Boiler |
| Kohlbach Group |
| Alstom |
| Babcock & Wilcox |
| Valmet |
| Harbin Electric |
| Thermax |
| Others |
Value Chain & Pricing Dynamics
Fluidized bed combustion engineering expertise concentrates among retiring specialists in Austria and Germany, compressing labor-cost differentials that widen pricing-tier spreads between premium water-tube configurations and standardized stoker-fired units. Carbon border adjustment mechanisms amplify this spread as industrial operators in Finland and Sweden accelerate procurement timelines for high-pressure systems.
Pricing Analysis
Distributor margins for high-pressure water-tube configurations absorb fabrication bottlenecks in Austrian and German engineering clusters, compressing channel economics. Three-tier pricing structure across premium, standard, and economy levels separates supercritical steam systems from fire-tube alternatives, with ENplus certification and automation bundling commanding tier premiums. Pricing pressure stems from feedstock cost volatility in wood pellet markets, squeezing margins on fixed-price service contracts. Food processing facilities in Italy and Spain exhibit highest price sensitivity, while pulp and paper operators in Scandinavia prioritize thermal efficiency over capital cost.
Supply Chain Analysis
ENplus certification and EU Timber Regulation compliance gates concentrate premium pellet sourcing through accredited forestry operations in Sweden, Finland, and Austria. Boiler fabrication draws from specialized pressure-vessel steel, high-alloy tubing, and precision combustion control systems. Single-source vulnerability sits with concentrated high-pressure fabrication capacity in Central Europe. Distribution runs through engineering-procurement-construction contractors for utility-scale installations and regional distributors for industrial retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial biomass boiler market functions as a regulatory compounder where EU Green Deal carbon pricing milestones compress fossil fuel payback thresholds and redirect capital toward biomass thermal assets.
For Market Incumbents: Extend fluidized bed automation capabilities to capture multi-feedstock contracting premiums as paper mills in Sweden diversify beyond wood chips. Black liquor recovery integration anchors defensive positioning against emerging carbon capture retrofit specialists. Backward integration into certified pellet logistics secures supply security for district heating operators in Germany facing EU Timber Regulation compliance complexity. For New Entrants and Emerging Players: Small-scale food processing facilities in Spain and Italy represent an underserved buyer archetype currently served by outdated fire-tube configurations with minimal automation. Carbon capture retrofit services for existing biomass installations offer white-space penetration with lower engineering barriers than greenfield utility-scale projects. A performance-guaranteed service contract model displaces capital-sale incumbents in this segment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with captive district heating relationships but limited technology licensing reach. The five-to-ten year viability window hinges on carbon border adjustment expansion beyond European heavy industry. Acquisition targets cluster around fluidized bed design houses with transferable agricultural residue combustion expertise. The signal to watch is US Inflation Reduction Act credit guidance clarifying biomass thermal eligibility for production tax incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Feedstock Automation Development | Captures sourcing flexibility premiums as Swedish paper mills diversify fuel portfolios. |
| Carbon Capture Retrofit Integration | Generates negative emission credits attractive to cement and steel producers under EU carbon pricing. |
| Black Liquor Recovery Co-Combustion | Delivers combined heat and power with minimal incremental fuel cost for Finnish pulp mills. |
| Advanced Flue Gas Condensing Deployment | Pushes Danish district heating plant thermal efficiency past ninety percent. |
| Certified Feedstock Logistics Backward Integration | Secures ENplus pellet supply security for Austrian district heating operators facing residential competition. |
Study Parameters
Direct dialogue with plant engineers at pulp and paper mills, district heating utility procurement officers, boiler OEM technical directors, and aftermarket service heads grounded qualitative insights in operational reality. Secondary validation incorporated EU ETS carbon price data, national renewable heat mandate filings, customs trade statistics for pressure-vessel steel imports, and SEC disclosures from publicly traded engineering conglomerates. Bottom-up installation tracking across Finnish and Swedish industrial corridors triangulated against top-down carbon pricing impact modeling.
Segmented outputs across product type, fuel category, end-use application, and regional regulatory cluster fed into the projection framework. Modeled dimensions included pressure rating tiers, feedstock moisture tolerance bands, and integration complexity with existing thermal infrastructure. CAGRs emerged from regression analysis against carbon price trajectory scenarios and district heating network expansion pipelines. Industry-specific inputs encompassed forestry harvest cycle patterns and F-Gas Regulation retrofit obligation timelines.
Underlying measurement precision varies by segment; water-tube and fluidized bed categories carry tighter precision than fire-tube alternatives due to concentrated supplier reporting. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and national biomass sustainability criteria evolution. Feedstock cost volatility, combustion engineering talent scarcity, and carbon capture technology scale-up risks could materially revise trajectory. A model refresh is warranted upon material change in EU carbon border adjustment mechanism coverage scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Field Erected Boiler Market
Boilers
US Industrial Boiler Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Gas Fired Boilers Market
Boilers
North America Industrial Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Global Boiler Market
Boilers
Superheater Tubes Market
Boilers
Steam Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Gas Condensing Boiler Market