
 Boiler Control Solutions Market | 2026-2036
Boiler Control Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler Control Solutions Market Analysis
Silicon carbide sensor elements are broadening the operating temperature envelope for boiler control transmitters beyond legacy ceramic limits. Emerson Electric Co. leverages its process automation portfolio to anchor long-term service contracts across North American refinery boiler units. Siemens AG competes through its digital twin integration for utility-scale steam generators, while Honeywell International Inc. specializes in safety instrumented systems for critical boiler applications.
Boiler control solutions encompass instrumentation, logic controllers, and actuation systems that regulate combustion air, fuel feed, water level, and steam pressure within fired pressure vessels. Modern architectures integrate SIL-rated safety loops with real-time thermal efficiency algorithms, typically maintaining drum level within plus-or-minus two percent of setpoint under variable load conditions. Temperature controllers and pressure controllers dominate the product type landscape, reflecting their foundational role in every boiler safety circuit. Smart control technology represents the fastest-expanding technology segment, as facilities replace standalone PID loops with model-predictive architectures that optimize fuel-to-air ratios across load swings.
The EPA enforces Maximum Achievable Control Technology standards that compel industrial boiler operators to upgrade legacy control systems for emissions compliance. OSHA process safety management rules mandate functional testing of boiler safety interlocks, creating recurring demand for control system validation services. Stakeholders must weigh the capital efficiency of phased retrofit programs against the operational risk of extended reliance on obsolete control hardware.
Market Dynamics
The EPA's Maximum Achievable Control Technology standards and Europe's F-Gas Regulation are forcing simultaneous control hardware replacement cycles across aging industrial boiler fleets, compressing vendor delivery timelines and reshaping procurement patterns toward bundled automation retrofits.
Growth Catalysts
- Power generation automation retrofits:Utilities across Germany, the United Kingdom, and Japan are absorbing premium distributed control system upgrades to extend boiler asset life while meeting tightening emissions ceilings.
- EU Green Deal combustion architecture mandates:The framework's 2030 climate targets accelerate demand for low-NOx burner management systems and continuous emissions monitoring integration.
- Silicon carbide sensor thermal envelope expansion:These elements enable transmitter operation beyond legacy ceramic limits, opening high-temperature boiler zones to closed-loop digital control.
Market Restraints
- Specialized control hardware supply concentration:Safety instrumented system logic solvers and SIL-rated transmitters depend on concentrated semiconductor foundry capacity in East Asia, exposing delivery timelines to geopolitical friction.
- Copper and rare-earth magnet input volatility:Actuator motor assemblies and sensor housings face raw material cost swings that compress system integrator margins on fixed-price retrofit contracts.
- Legacy communication protocol entrenchment:Proprietary fieldbus architectures from 1990s installations resist seamless integration with modern Ethernet-IP backbones, forcing costly gateway layers or full rip-and-replace decisions.
Strategic Opportunities
- India industrial boiler modernization:The country's Perform, Achieve and Trade scheme and tightening particulate matter norms under the Central Pollution Control Board create first-mover advantage for control vendors offering localized service networks.
- Digital twin convergence with model-predictive control:Real-time thermal efficiency algorithms fused with physics-based boiler simulations enable predictive maintenance contracts that lock in decade-long service revenue.
- OSHA process safety management validation services:Mandated functional testing of boiler safety interlocks generates recurring demand for control system certification expertise and spare parts logistics.
Industry Challenges
- Control systems integration talent scarcity:Facilities struggle to source engineers proficient in both legacy relay logic and modern safety PLC programming, delaying commissioning timelines.
- SIL certification timeline compression:Third-party functional safety assessments for burner management systems now extend 8-14 months, misaligning with utility outage windows.
- Obsolete hardware obsolescence management:Operators of 1980s-vintage boiler control platforms face parts scarcity forcing unplanned full-system replacements during critical heating seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler Control Solutions Market |
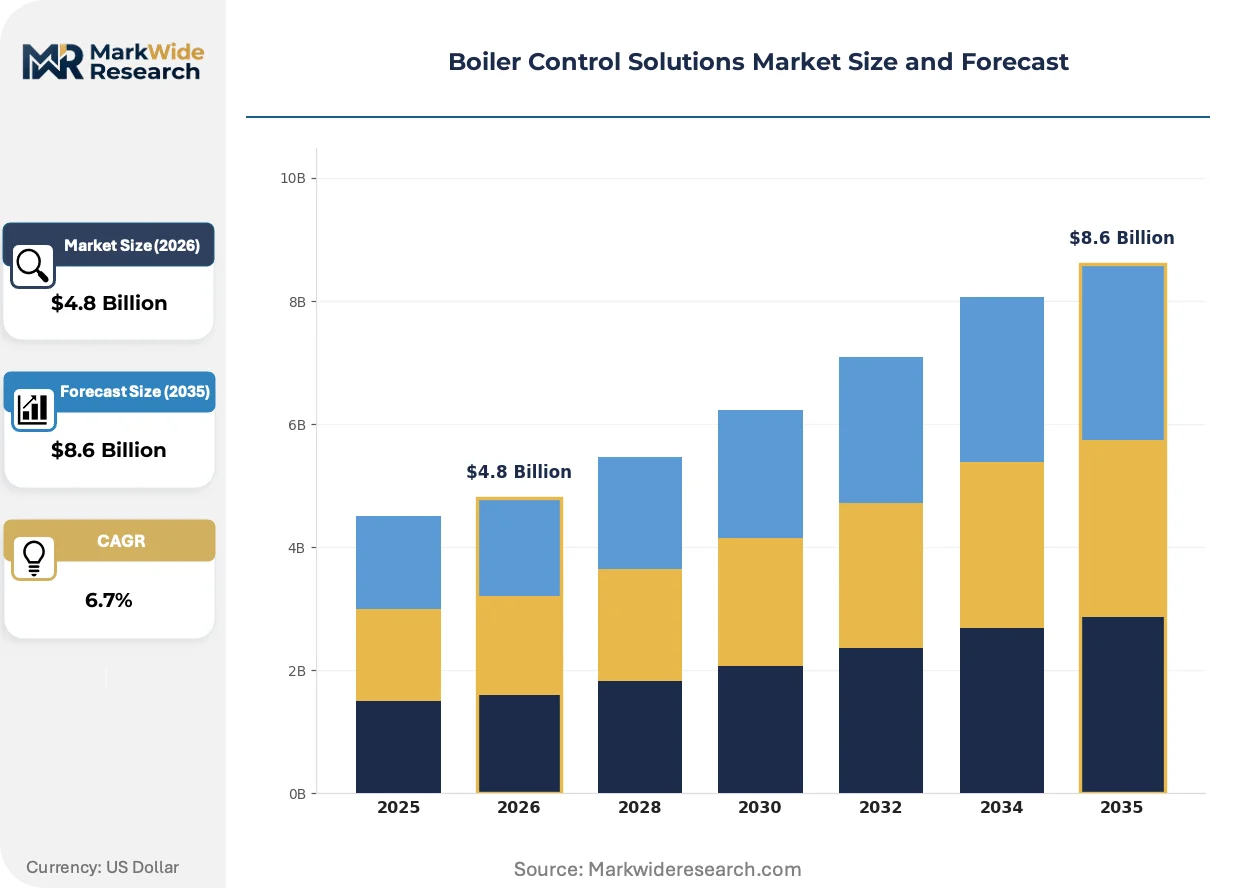
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Controllers, Pressure Controllers, Flow Controllers, Level Controllers Application: Industrial Processes, Commercial Buildings, Power Generation, Residential Heating Technology: PID Control, Smart Control, Remote Monitoring, Cascade Control End User: Manufacturing, Energy, Healthcare, Hospitality |
| Companies Covered | Schneider Electric, Emerson Electric Co., Siemens AG, BURNHAM COMMERCIAL BOILERS, Honeywell International Inc., ABB, Yokogawa Electric Corporation, HBX Control Systems, Cleaver-Brooks Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler Control Solutions Market Emerging Trajectories
Edge computing architectures and wireless sensor networks are redistributing intelligence from central control rooms to boiler field devices, while regulatory tightening in multiple jurisdictions forces simultaneous compliance technology refresh cycles.
Model-predictive combustion control is decentralizing optimization authority from centralized distributed control systems to localized edge nodes mounted directly on burner fronts. Refinery and chemical plant operators in Texas and Louisiana are piloting these architectures to manage fuel-to-air ratios across rapid load swings. The technology is compressing response latency from seconds to milliseconds, enabling tighter emissions compliance without hardware redundancy.
The F-Gas Regulation's phasedown of hydrofluorocarbon-based refrigerants and heat transfer fluids is forcing boiler operators to certify alternative working fluids in combined heat and power systems. Industrial facilities in Germany and the Netherlands face 2027 deadlines to retrofit thermal fluid control loops or replace entire heat recovery packages. The regulation is accelerating demand for multi-fluid-capable temperature transmitters and recalibrated safety relief valve specifications.
After-sales service unbundling is fragmenting traditional control system vendor relationships as facility operators separate hardware procurement from commissioning and long-term maintenance contracts. Independent system integrators in the United Kingdom and Australia now capture 30-40% of retrofit commissioning work that incumbents previously bundled. This pattern concentrates margin pressure on original equipment manufacturers while elevating specialized service firms with vertical expertise in specific boiler configurations.
Boiler Control Solutions Market Segmentation
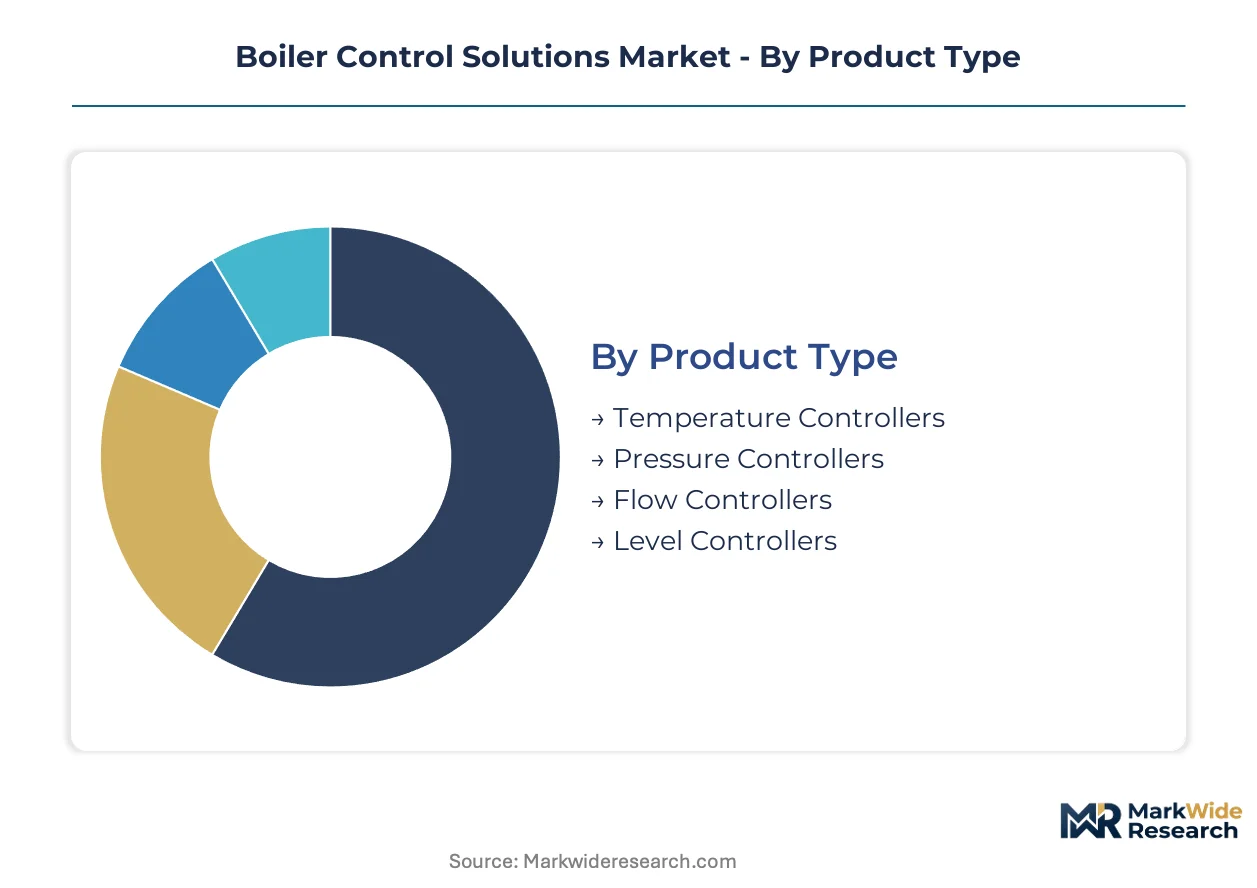
Boiler control architectures fragment across multiple technical and commercial dimensions, each carrying distinct procurement patterns and lifecycle economics. Understanding these divides clarifies where automation budgets concentrate and which specifications dominate competitive tenders.
Product Type:
Standardization dominates at the component level, yet integration complexity rises sharply when specifications must harmonize across mixed-vendor environments.
- Temperature Controllers:Thermocouple and RTD input modules regulate combustion zone and steam header temperatures within tight bands. Demand clusters in German industrial boiler modernization programs where EU Green Deal thermal efficiency mandates drive premium specification upgrades.
- Pressure Controllers:These devices maintain drum pressure and safety valve setpoints through pneumatic or electronic actuation. Refinery operators in Texas and Louisiana specify SIL-rated configurations to satisfy OSHA process safety management requirements for burner management interlocks.
- Flow Controllers:Fuel and combustion air metering valves with integrated position feedback.
- Level Controllers:Drum level transmitters using differential pressure or guided-wave radar principles.
Most installed capacity flows through Temperature Controllers. Expansion is steepest in Pressure Controllers.
Application:
Capital intensity and regulatory exposure vary dramatically across facility types, with power generation absorbing the longest procurement cycles.
- Industrial Processes:Chemical, petrochemical, and pulp mill boilers demand ruggedized control hardware with explosion-proof housings. Japanese utilities are retrofitting aging refinery boiler fleets with distributed control system upgrades that extend asset life while tightening emissions compliance.
- Power Generation:Utility-scale steam generators require redundant safety instrumented systems and continuous emissions monitoring integration. British power producers face compressed delivery timelines as F-Gas Regulation deadlines force simultaneous control hardware replacement cycles across combined heat and power installations.
- Commercial Buildings:Hospital and university district heating systems with seasonal load swings.
- Residential Heating:Condensing boiler modulating controls for multi-family housing.
Power Generation absorbs the highest per-unit control system investment. Commercial Buildings are gaining share fastest as building automation convergence accelerates.
Technology:
Intellectual property concentration and service revenue potential diverge sharply between legacy algorithmic approaches and connected architectures.
- Smart Control:Model-predictive algorithms optimize fuel-to-air ratios across variable loads using embedded edge computing nodes. Pilot deployments in Netherlands industrial facilities demonstrate millisecond response latency that compresses emissions excursions during rapid demand swings.
- Remote Monitoring:Cloud-connected sensor networks enable predictive maintenance contracts and vendor-managed spare parts logistics. Indian cement and steel producers under Perform, Achieve and Trade scheme pressure are adopting these architectures to minimize unplanned outages.
- PID Control:Proportional-integral-derivative loops remain standard for base-load applications.
- Cascade Control:Nested loop architectures for drum level and combustion air coordination.
PID Control retains the largest installed base. Smart Control is climbing the fastest as facilities replace standalone loops with integrated optimization platforms.
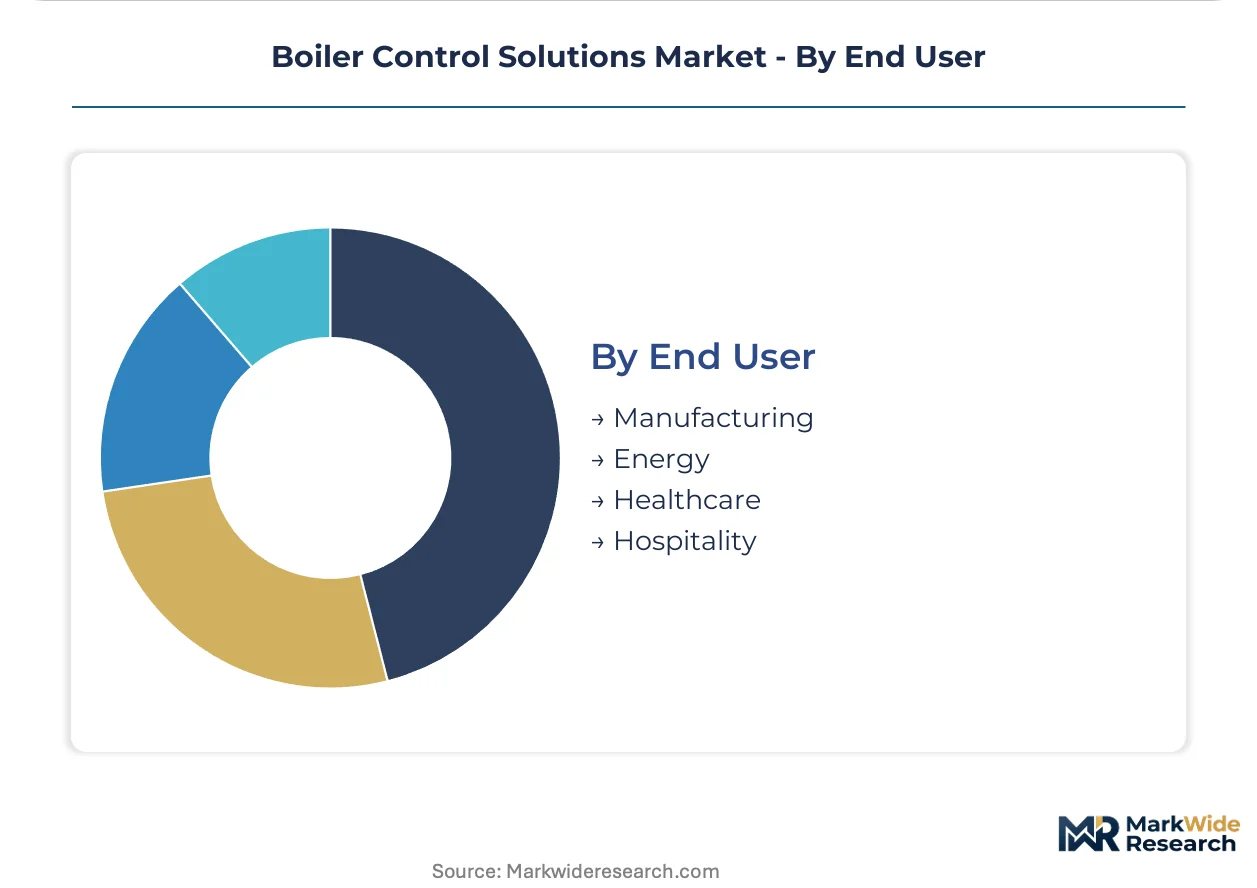
End User:
Procurement sophistication and safety culture maturity create distinct customer archetypes with diverging contract structures.
- Energy:Power utilities and independent power producers operate under strict grid codes and emissions ceilings. German operators absorb premium control system upgrades through long-term service contracts that bundle hardware, commissioning, and predictive maintenance.
- Manufacturing:Food processing and automotive plants prioritize rapid return on retrofit investments. Healthcare facilities in the United Kingdom specify hygienic-design transmitters with sanitary process connections for steam sterilization systems.
- Healthcare:Hospital central steam plants with 24/7 reliability requirements.
- Hospitality:Hotel and resort heating systems with seasonal occupancy-driven load profiles.
Energy sector procurement dominates total contract value. Manufacturing is expanding most quickly as industrial boiler fleets reach end-of-design-life control hardware obsolescence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial boiler modernization programs absorb the most concentrated premium control system upgrades worldwide. Utilities and chemical processors across specific national markets face synchronized regulatory deadlines that compress procurement timelines and reshape vendor relationships.
Germany
Rhineland chemical complexes and Bavarian automotive plants drive demand for SIL-rated burner management systems. The F-Gas Regulation forces 2027 retrofits of thermal fluid control loops in combined heat and power installations. North Rhine-Westphalia's industrial belt concentrates the heaviest upgrade activity as operators replace 1990s-vintage distributed control systems.
United States
Texas and Louisiana refineries pilot edge-computing combustion architectures to manage fuel-to-air ratios across rapid load swings. EPA Maximum Achievable Control Technology standards compel emissions compliance retrofits across aging boiler fleets. The Gulf Coast petrochemical corridor generates concentrated demand for explosion-proof control hardware with integrated safety instrumented systems.
United Kingdom
British power producers face compressed delivery timelines for combined heat and power control hardware replacements. The F-Gas Regulation deadlines force simultaneous upgrade cycles across industrial boiler installations. Independent system integrators in England now capture 30-40% of retrofit commissioning work previously bundled by incumbent vendors.
Japan
Japanese utilities retrofit aging refinery boiler fleets with distributed control system upgrades extending asset life. METI efficiency mandates tighten thermal performance requirements for industrial steam generators. The Keihin industrial zone between Tokyo and Yokohama concentrates demand for ruggedized control hardware with continuous emissions monitoring integration.
India
Indian cement and steel producers under the Perform, Achieve and Trade scheme adopt cloud-connected sensor networks to minimize unplanned outages. Central Pollution Control Board particulate matter norms create first-mover advantage for vendors with localized service networks. The Gujarat and Maharashtra industrial corridors concentrate the fastest-expanding demand for remote monitoring architectures.
Boiler Control Solutions Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors bundle hardware procurement with decade-long predictive maintenance contracts. The vendor base organizes around three tiers: integrated automation conglomerates with full-stack portfolios, specialized safety system houses with SIL certification expertise, and regional system integrators capturing unbundled commissioning work. Two archetypes define competitive positioning: full-service providers anchoring long-term service relationships, and technology specialists monetizing predictive algorithms through recurring software revenue. Geographic expansion and technology licensing represent the dominant competitive moves, with vendors leveraging localized service networks to capture first-mover advantage in tightening regulatory environments.
Among the integrated automation conglomerates, Schneider Electric, Siemens AG, and Emerson Electric Co. exemplify the full-service archetype, anchoring vendor-customer relationships through bundled hardware-software-service offerings. These players occupy positions spanning safety instrumented systems, distributed control platforms, and edge-computing combustion optimization, representing the premium tier where procurement concentrates on total lifecycle cost rather than upfront capital expenditure. Their geographic footprints align with regulatory pressure points, positioning them to capture compressed upgrade cycles across German industrial belts, US Gulf Coast refineries, and Japanese utility fleets.
| Leading Market Players |
|---|
| Schneider Electric |
| Emerson Electric Co. |
| Siemens AG |
| BURNHAM COMMERCIAL BOILERS |
| Honeywell International Inc. |
| ABB |
| Yokogawa Electric Corporation |
| HBX Control Systems |
| Cleaver-Brooks Company, Inc. |
| Others |
Supply Flow & Price Mechanics
SIL certification tier divergence separates premium burner management systems from commodity PID controllers, and this bifurcation manifests in both procurement premiums and concentrated semiconductor sourcing for safety-rated logic solvers. German chemical processors absorb tier-one pricing for integrated digital twin architectures while Indian cement producers negotiate standardized packages, with supply chain configurations tracking these performance thresholds through differentiated foundry relationships and regional service network investments.
Pricing Analysis
Input-cost pass-through from copper and rare-earth magnet volatility compresses system integrator margins on fixed-price retrofit contracts. Three-tier pricing structure across SIL-certified, industrial-grade, and commercial configurations reflects certification investment and after-sales bundling depth. Pricing pressure stems from raw material swings and unbundled commissioning competition. Manufacturing buyers exhibit highest price sensitivity; German utilities demonstrate lowest, anchoring decade-long service contracts.
Supply Chain Analysis
Dual-sourcing requirements for safety instrumented system logic solvers mandate multi-supplier qualification across concentrated East Asian semiconductor foundries and European automation assembly facilities. Raw material dependencies center on copper for actuator windings, rare-earth magnets for servo motors, and silicon carbide for high-temperature sensor elements. Single-source vulnerability in specialized SIL-rated transmitter production exposes delivery timelines to geopolitical friction. Distribution runs through OEM-direct channels for utility-scale projects and independent system integrators for mid-market retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as regulatory tightening across multiple jurisdictions forces simultaneous compliance-driven upgrades toward premium SIL-rated architectures. The shift from standalone PID loops to integrated model-predictive platforms concentrates procurement on vendors with certified safety portfolios and localized service networks.
For Market Incumbents: Deepen backward integration into silicon carbide sensor production to secure thermal envelope expansion capabilities and buffer rare-earth input volatility. Anchor long-term predictive maintenance contracts with German chemical processors and Japanese utilities before independent integrators capture commissioning margins. Invest in SIL certification pipeline acceleration to compress third-party assessment timelines misaligned with outage windows.
For New Entrants and Emerging Players: Launch via cloud-connected remote monitoring architectures targeting Indian cement and steel producers under Perform, Achieve and Trade scheme pressure. Penetrate the unbundled commissioning segment in the United Kingdom and Australia where independent integrators now capture 30-40% of retrofit work. Lead with vertical expertise in specific boiler configurations—pulp mill recovery boilers or refinery process steam generators—to differentiate from full-stack conglomerates.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional system integrators lack capital to certify SIL-rated burner management systems under compressed regulatory deadlines. Long-term viability favors vendors with decade-long service revenue locked through predictive maintenance contracts and spare parts logistics. Target acquisition candidates with concentrated expertise in F-Gas Regulation compliance and multi-fluid thermal loop certification. Watch EPA MACT enforcement intensity as inflection indicator for North American retrofit cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Production | Captive silicon carbide supply secures high-temperature transmitter differentiation against ceramic-limited competitors. |
| Digital Twin Platform Integration | Siemens and Emerson leverage physics-based boiler simulations to lock decade-long predictive maintenance contracts. |
| Localized Service Network Expansion | First-mover advantage in India and Southeast Asia depends on certified commissioning engineers near industrial corridors. |
| SIL Certification Pipeline Acceleration | Compressed third-party assessment timelines align vendor delivery schedules with utility outage windows. |
| Multi-Fluid Thermal Loop Certification | F-Gas Regulation deadlines force 2027 retrofits requiring recalibrated safety relief valve and transmitter specifications. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at power utilities and industrial facilities across Germany, the United States, Japan, and India were combined with secondary validation from EPA enforcement databases, EU F-Gas Regulation implementation reports, SEC filings of listed automation vendors, and customs trade data for control hardware imports. Triangulation between facility-level retrofit budgets and vendor shipment disclosures ensures segmentation integrity.
Historical trendline analysis of automation retrofit cycles, regulatory compliance spending patterns, and safety system replacement timelines informs the projection framework. Segmentation dimensions include product type, application intensity, technology architecture, and end-user procurement sophistication, with regional regulatory cluster effects modeled separately. CAGRs derive from fitted growth curves calibrated against disclosed vendor backlog data and utility capital expenditure plans. Industry-specific forecast inputs incorporate SIL certification timeline compression and semiconductor foundry capacity allocation for safety-rated components.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA enforcement escalation or East Asian semiconductor export restrictions. Deviation in F-Gas Regulation implementation timelines would shift European upgrade cycle phasing materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Europe Residential Boiler Market
Boilers
Space Heating Boilers Market
Boilers
Waste Heat Boiler Market
Boilers
Superheater Market
Boilers
Global Boiler Market
Boilers
Power Boiler Market
Boilers
North America Commercial Boiler Market
Boilers
US Commercial Boiler Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Biomass Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Advanced Utility Boilers Market
Boilers
Industrial and Residential Heating Market