
 Vitamin and Mineral Premixes Market | 2026-2036
Vitamin and Mineral Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin and Mineral Premixes Market Intelligence
The use of microencapsulated vitamins to replace standard powder forms is expanding shelf life and formulation stability in functional foods. This shift toward value-added, technologically advanced ingredients allows for higher-margin product development. dsm-firmenich leverages its extensive R&D in bioavailability to lead this area. Glanbia PLC competes by focusing on custom premix solutions for the sports nutrition segment, while Archer Daniels Midland Company sustains its position through vast raw material sourcing and processing scale.
Vitamin and mineral premixes are complex, homogenous mixtures of specific micronutrients blended with a carrier to ensure uniform distribution. These formulations, often containing precisely dosed vitamins and trace elements, serve to fortify foods, beverages, dietary supplements, and animal feeds. Animal feed constitutes the largest volume application, while sports nutrition and functional foods represent high-growth areas. Powder forms remain dominant due to cost-effectiveness, but liquid concentrates are gaining share in beverage fortification.
Regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate permissible nutrient levels and health claims. In China, GB standards enforced by the State Administration for Market Regulation (SAMR) govern food additive and fortification requirements, influencing market access. Suppliers must now navigate diverging regional regulations on novel nutrient sources and maximum dosage limits.
Market Dynamics
Diverging regional regulations and the technical demands of new food applications are the central forces shaping the vitamin and mineral premixes market, pushing manufacturers toward greater specialization and scientific substantiation.
Growth Catalysts
- Functional Foods:Demand for health-enhancing products propels premix use in sports nutrition and fortified beverages, requiring specialized formulations.
- Fortification Mandates:Public health initiatives in developing nations mandate staple food fortification, creating baseline volume demand aligned with WHO guidelines.
- Intensive Farming:Growth in industrial animal farming in Asia requires advanced feed premixes to ensure animal health and productivity.
Market Restraints
- Input Cost Volatility:Prices for key raw materials like synthetic vitamins exhibit significant volatility, impacting formulation costs and margin stability.
- Regulatory Divergence:Conflicting nutrient level regulations from bodies like the EFSA and FDA complicate global product development and trade.
- Technical Complexity:Ensuring micronutrient stability and bioavailability in complex food matrices without unwanted interactions remains a significant technical hurdle.
Strategic Opportunities
- Plant-Based Fortification:The expanding plant-based food market requires novel premixes to achieve nutritional parity with animal-derived products.
- Personalized Nutrition:Direct-to-consumer models are creating a new market for high-margin, custom premixes tailored to individual health data.
- Aquaculture Feeds:Growth in global aquaculture presents an opportunity for specialized premixes designed for aquatic species' unique dietary needs.
Industry Challenges
- Regulatory Burden:Navigating divergent regional rules, such as China's GB standards and EFSA health claims, demands constant monitoring and investment.
- Talent Scarcity:A shortage of formulators skilled in managing complex micronutrient interactions and ensuring stability slows innovation and product development.
- Traceability Demands:Implementing full source traceability for every component to meet clean-label standards adds significant operational cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin and Mineral Premixes Market |
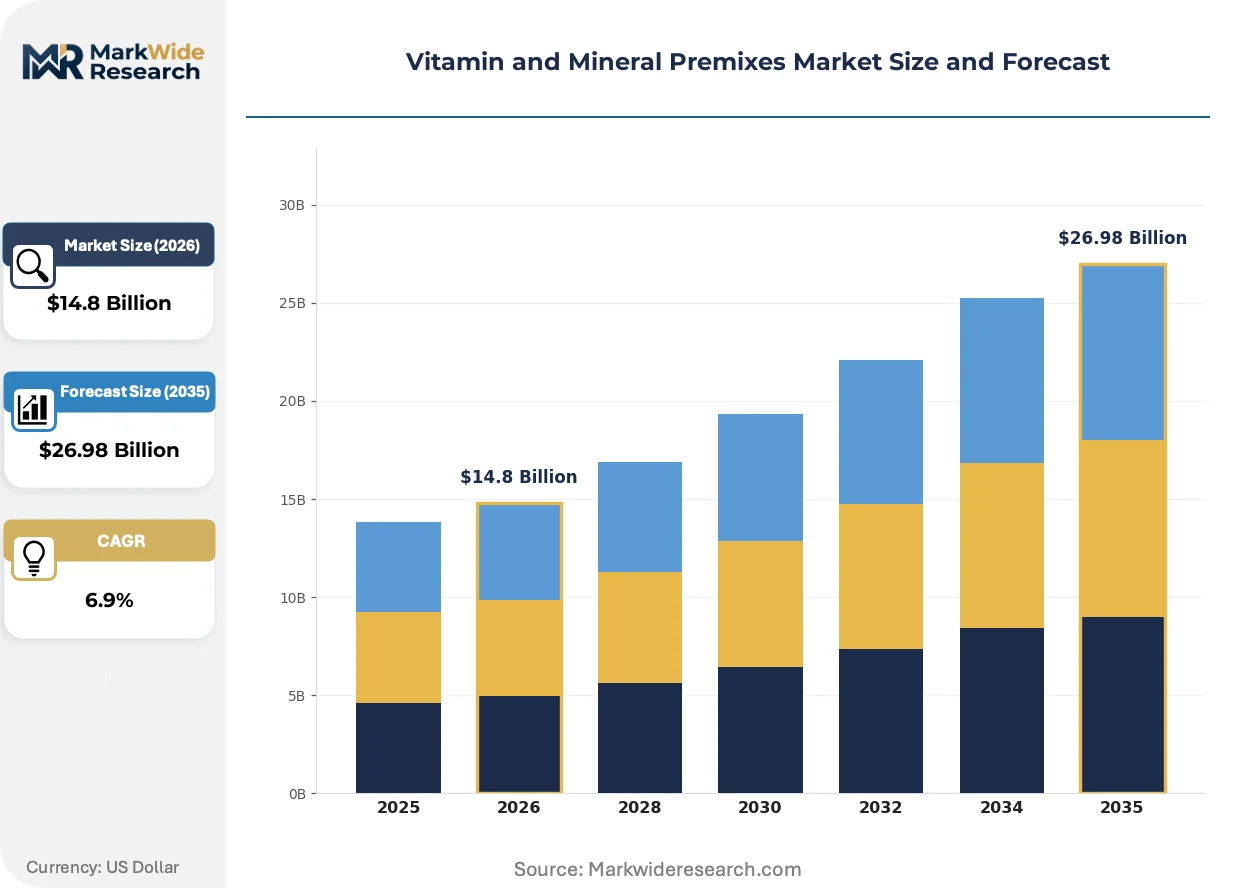
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Premixes, Mineral Premixes, Multivitamin Blends, Trace Element Specials Application: Infant Nutrition, Sports Nutrition, Functional Food, Animal Feed, Dietary Supplements End User: Food Manufacturers, Pharmaceutical Firms, Animal Nutrition Companies, Nutraceutical Producers, Custom Premix Makers Form: Powder, Granules, Liquid Concentrates, Tablets, Capsules |
| Companies Covered | Archer Daniels Midland Company, dsm-firmenich, Glanbia PLC, Corbion, SternVitamin GmbH & Co. KG, NAGASE & CO., LTD., Nutreco, Barentz, FENCHEM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin and Mineral Premixes Market Strategic Shifts & Innovations
The market is shifting from commoditized ingredients toward value-added, application-specific solutions. This evolution is driven by advances in formulation technology and heightened consumer expectations for product efficacy and transparency, particularly in functional foods and supplements.
Microencapsulation technology protects sensitive micronutrients like iron or Vitamin C from degradation during processing and storage. Functional food and infant formula manufacturers are rapidly adopting this method for premium products. This innovation is rewriting formulation rules, enabling the inclusion of previously incompatible ingredients and extending product shelf life.
Stricter regulations on nutrient content claims, exemplified by the European Food Safety Authority (EFSA), are becoming a global benchmark. This forces manufacturers to provide rigorous scientific substantiation for any health benefit associated with their premixes. The dietary supplement and functional beverage segments are most affected, investing in clinical studies and transparent sourcing.
A demand shift towards personalized nutrition is moving premix procurement away from standardized, high-volume orders. Direct-to-consumer supplement brands seek small-batch, custom-formulated premixes tailored to specific demographic or lifestyle needs. This trend is most prominent in North America and Europe, driven by digital health platforms and consumer-facing diagnostic tools.
Vitamin and Mineral Premixes Market Segmentation
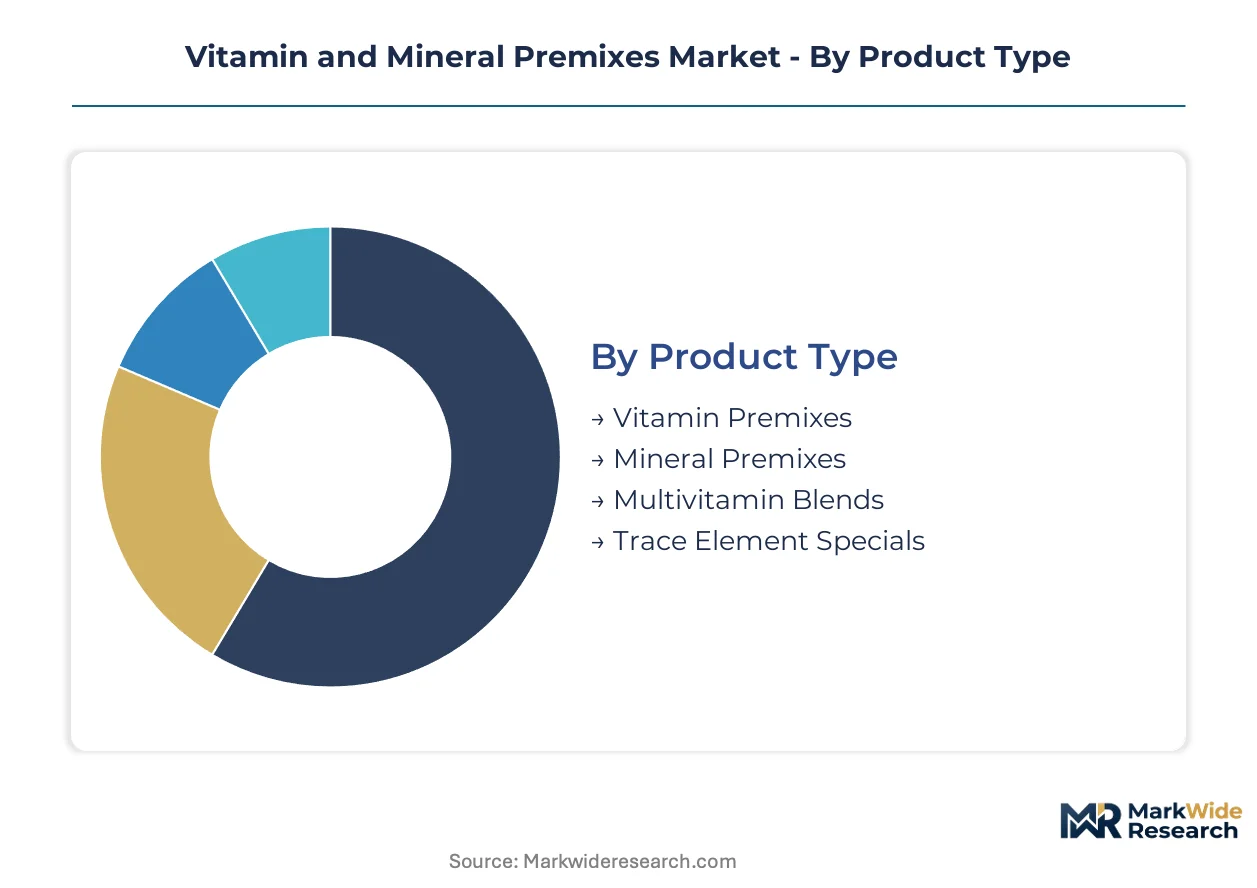
The Vitamin and Mineral Premixes Market segments distinctively, reflecting the diverse nutritional requirements across various industries. Understanding these segmentations allows suppliers to tailor product development and market strategies to specific customer needs and regulatory environments. Each segment presents unique technical challenges and commercial opportunities for manufacturers.
Product Type:
Buyers often select premixes based on the specific micronutrient profile required for their final product formulation. This ensures precise nutritional content and functionality.
- Vitamin Premixes:These formulations concentrate specific vitamins, such as Vitamin D for bone health or B vitamins for energy metabolism, often blended with a carrier. Demand is strong in animal feed applications, particularly for poultry and swine, to support growth and immunity.
- Multivitamin Blends:These complex mixtures combine multiple vitamins, sometimes alongside minerals, to offer comprehensive nutritional support in a single ingredient. Dietary supplement manufacturers and fortified beverage producers in North America and Europe utilize these blends for broad consumer wellness products.
- Mineral Premixes:These premixes deliver essential macro and trace minerals, crucial for metabolic functions and structural integrity. They are frequently incorporated into livestock feed to prevent deficiencies and improve animal productivity in regions with intensive farming.
- Trace Element Specials:These highly specific premixes focus on delivering precise quantities of individual trace elements like selenium, iodine, or zinc. Such specialized products find application in targeted human health supplements or veterinary therapeutic diets.
Vitamin Premixes leads on scale; Multivitamin Blends leads on momentum.
Application:
The volume of premix consumed varies significantly across distinct application areas, reflecting diverse fortification needs.
- Animal Feed:This application constitutes the largest volume segment, providing essential vitamins and minerals to livestock, poultry, and aquaculture species for optimal growth, health, and feed conversion efficiency. Intensive farming operations in China and Brazil rely heavily on these premixes to enhance productivity.
- Functional Food:Premixes in functional foods fortify everyday food items like cereals, dairy products, and snacks with added health benefits beyond basic nutrition. Consumer demand for wellness products in Germany and the UK drives innovation in this segment, requiring stable and bioavailable formulations.
- Infant Nutrition:This segment requires highly specialized and strictly regulated premixes to support the healthy development of infants. Formulations adhere to stringent global standards set by bodies like WHO guidelines and national regulators.
- Sports Nutrition:Premixes for sports nutrition products focus on enhancing athletic performance, aiding muscle recovery, and boosting energy levels. These are commonly found in protein powders, energy bars, and hydration drinks targeted at active consumers.
- Dietary Supplements:This broad category includes a wide array of products, from daily multivitamins to targeted nutrient formulations, designed to complement dietary intake. Personalized nutrition trends in the US and Canada are expanding demand for custom supplement premixes.
Animal Feed applications drive the largest market share, while Sports Nutrition represents the fastest-growing trajectory.
End User:
Different end-user types require distinct product specifications and service levels from premix suppliers.
- Food Manufacturers:These companies incorporate premixes into a wide range of consumer food products, from staple foods to processed goods, to enhance nutritional value and meet fortification mandates. Large-scale food producers in India and Mexico utilize premixes for public health initiatives.
- Animal Nutrition Companies:These firms formulate and produce animal feed, integrating premixes to create balanced diets for various livestock and aquaculture species. Global players like Archer Daniels Midland Company maintain vast sourcing networks for these components.
- Pharmaceutical Firms:Pharmaceutical companies use high-purity premixes in specific medical foods, therapeutic nutritional products, or over-the-counter vitamin preparations. Their requirements include strict GMP compliance and detailed documentation.
- Nutraceutical Producers:This segment focuses on creating health-promoting products, including functional beverages, health shots, and specialized supplements. Glanbia PLC caters to this segment with custom premix solutions.
- Custom Premix Makers:These specialized businesses create bespoke premix formulations tailored to unique client specifications, often for niche markets or experimental product development. They serve smaller brands and personalized nutrition platforms.
Food Manufacturers and Animal Nutrition Companies collectively account for the majority of premix procurement.
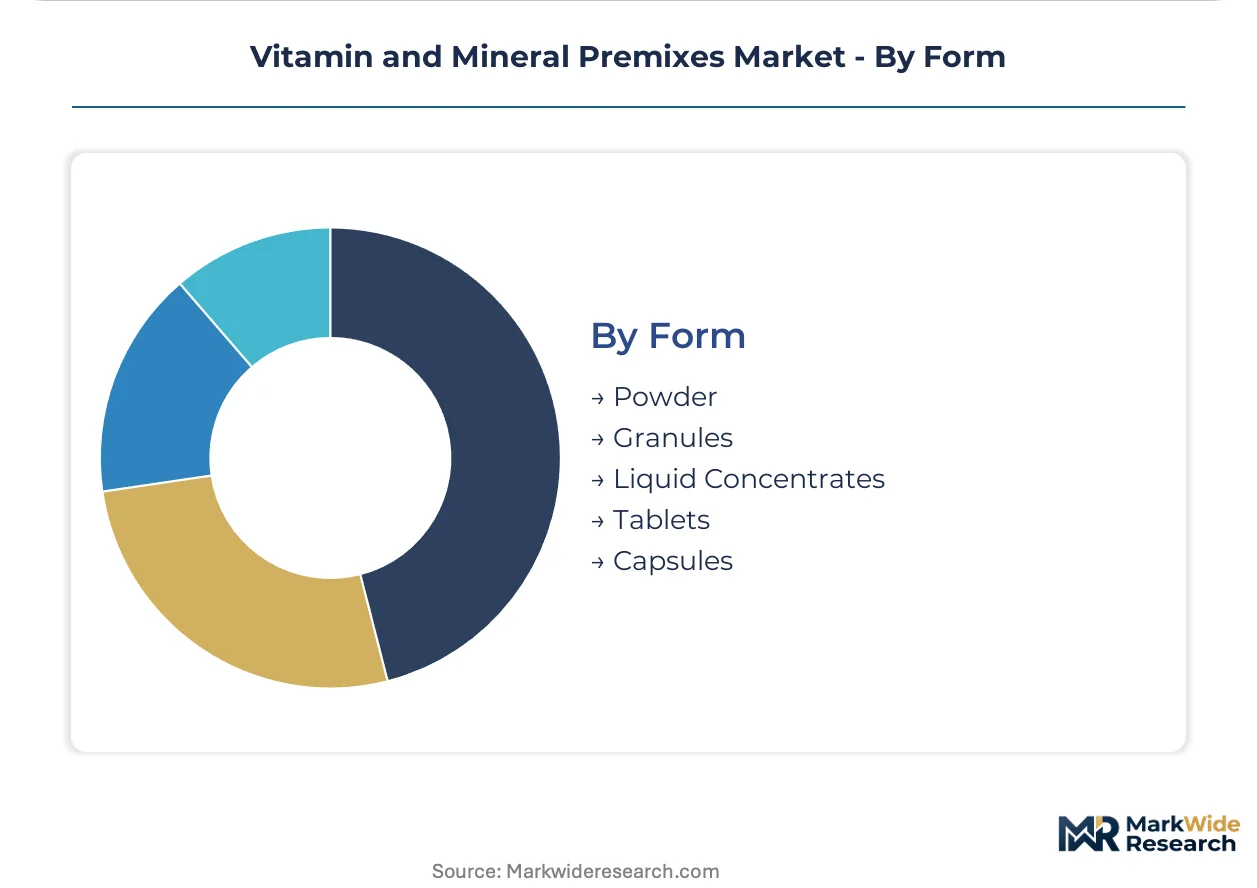
Form:
The physical form of premixes is critical for stability, ease of incorporation, and final product application.
- Powder:Powder forms are the most prevalent due to their cost-effectiveness, ease of handling, and versatility in blending with other dry ingredients. Animal feed and dry food mixes globally utilize powder premixes extensively.
- Liquid Concentrates:These highly soluble forms are ideal for fortification of beverages, allowing for uniform dispersion and often offering enhanced bioavailability for certain nutrients. Fortified drinks in Germany and Japan are increasingly adopting liquid concentrates.
- Granules:Granular premixes offer benefits such as reduced dust, improved flowability, and minimized segregation during mixing, making them suitable for specific manufacturing processes. They are often preferred in certain animal feed and food applications.
- Tablets:Premixes in tablet form are primarily used in the dietary supplement market, providing precise dosing and convenience for consumers. Many daily multivitamin products are manufactured as tablets.
- Capsules:Capsules provide a protective barrier for sensitive ingredients and allow for targeted release or combination of incompatible nutrients within a single dose. High-value dietary supplements frequently employ encapsulated premixes.
Powder forms maintain market dominance, while Liquid Concentrates are gaining share due to specific functional benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's intensive farming operations drive significant demand for vitamin and mineral premixes. This market is influenced by diverse regional regulations and specific application needs. Fortification mandates and health trends further shape consumption patterns across various geographies.
China
China's vast animal feed sector necessitates substantial vitamin and mineral premix volumes for livestock and aquaculture. GB standards enforced by the State Administration for Market Regulation (SAMR) strictly govern food additive and fortification requirements. The Yangtze River Delta region concentrates numerous food and feed manufacturers, driving innovation in premix formulations.
United States
The United States market sees strong demand from dietary supplements and personalized nutrition trends. FDA regulations dictate permissible nutrient levels and health claims for fortified products. California's robust health and wellness industry fosters innovation in custom premixes for consumer-facing diagnostic tools.
Germany
Germany's advanced functional food and beverage sectors require high-quality premixes for consumer health products. EFSA guidelines significantly influence nutrient content claims and product development for European markets. Bavaria hosts a cluster of specialized food ingredient companies, focusing on bioavailable and stable premix solutions.
India
Public health initiatives in India drive significant demand for staple food fortification, aligning with WHO guidelines. The Food Safety and Standards Authority of India (FSSAI) sets mandatory fortification standards for various food products across the country. Maharashtra's extensive food manufacturing base, including dairy and cereal processors, integrates premixes for nutritional enhancement.
Brazil
Brazil's large-scale animal agriculture, particularly poultry and swine, creates substantial demand for specialized feed premixes. ANVISA regulates the use of vitamins and minerals in food and dietary supplements within the country. São Paulo state's agribusiness hub supports numerous feed mills and food processors requiring consistent premix supply.
Vitamin and Mineral Premixes Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution networks within the vitamin and mineral premixes market. The market exhibits a tiered structure, with large ingredient suppliers coexisting with specialized custom formulators. Archetypes include diversified chemical conglomerates, dedicated nutrition solution providers, and niche segment specialists. Strategic partnerships and portfolio diversification are common competitive moves among market participants.
At the scale-driven end, Archer Daniels Midland Company exemplifies a player leveraging vast raw material sourcing and processing capabilities. dsm-firmenich, a global nutrition science leader, represents a company focused on extensive R&D in bioavailability and microencapsulation technologies. Glanbia PLC occupies a position as a custom premix solution provider, particularly for the sports nutrition segment. These companies anchor different facets of the market, from commodity supply to high-value ingredient innovation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| dsm-firmenich |
| Glanbia PLC |
| Corbion |
| SternVitamin GmbH & Co. KG |
| NAGASE & CO., LTD. |
| Nutreco |
| Barentz |
| FENCHEM |
| Others |
Cost & Logistics Intelligence
Formulators skilled in complex micronutrient interactions, particularly in Europe and North America, command higher labor costs. These differentials contribute to the tiered pricing spreads observed for custom-formulated versus standard premixes.
Pricing Analysis
Input cost volatility for key raw materials like synthetic vitamins directly impacts premix pricing, often passed through via contract adjustments. The market primarily operates on a hybrid contract-based and value-based pricing model. Price differentiation stems from quality grade, customization level, and brand premium associated with scientific substantiation. Animal feed manufacturers exhibit high price sensitivity, while personalized nutrition platforms are less sensitive due to custom formulation value.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns facilitate efficient delivery of premixes, with raw material supply for synthetic vitamins concentrated in China. Specialized premix production clusters in Europe and the United States. The supply chain relies on a consistent flow of trace elements and carrier agents. Regulatory restriction divergence between regions, particularly for novel nutrient sources, poses a significant structural risk, while direct sales to large food and animal nutrition companies dominate the distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitamin and mineral premixes market acts as a regulatory compounder, where compliance with evolving standards drives product innovation. WHO guidelines for staple food fortification represent a key regulatory milestone fueling baseline demand.
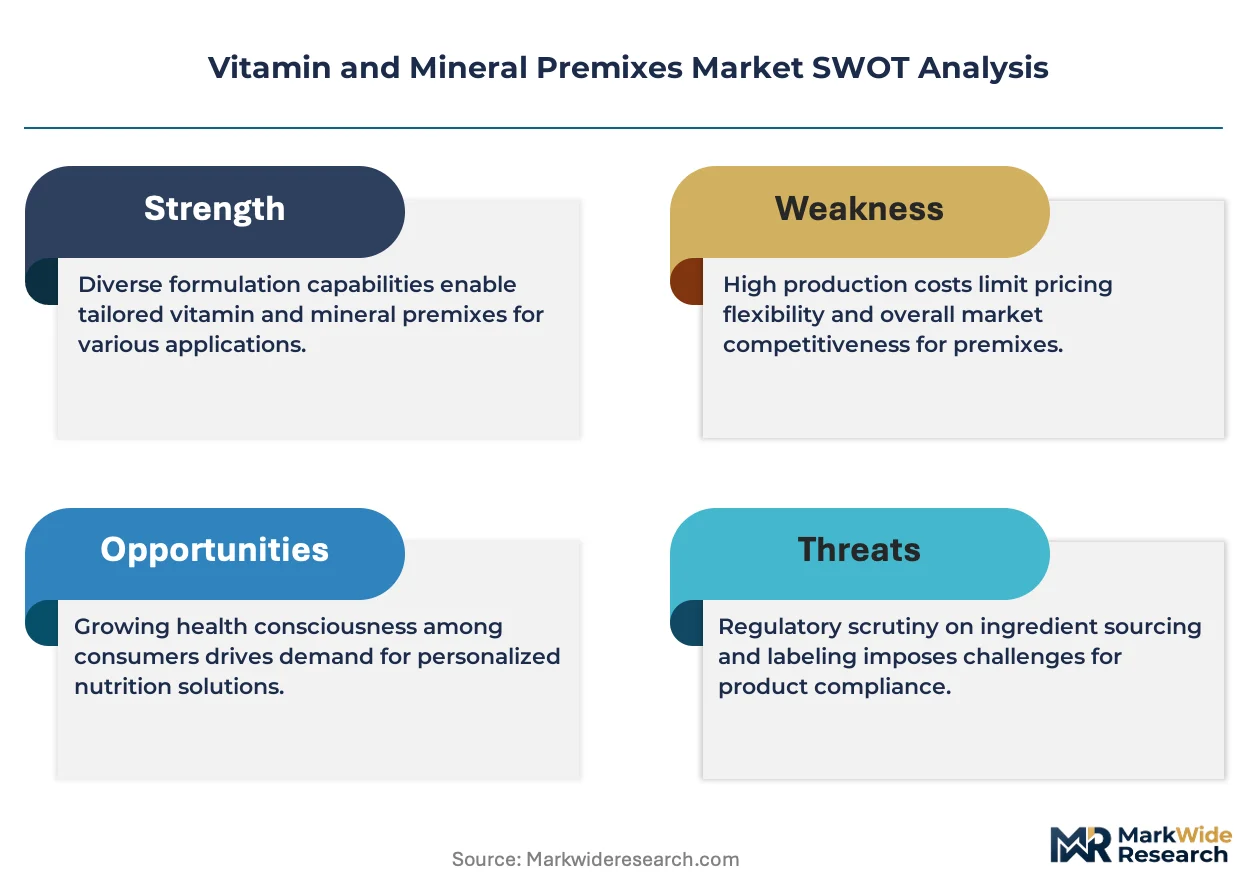
For Market Incumbents: Deploy extensive R&D in bioavailability and microencapsulation to differentiate premium offerings against commoditization. Incumbents must diversify their portfolio into high-growth areas like personalized nutrition and plant-based fortification. Strategic partnerships with functional food manufacturers can expand market reach and secure long-term contracts. Investing in advanced analytical capabilities counters the threat from specialized niche players.
For New Entrants and Emerging Players: Digital health platforms and direct-to-consumer models offer a viable route for new entrants to access niche markets. The personalized nutrition segment in North America presents a highly penetrable white space due to demand for custom premixes. Focus on specialized premixes for aquaculture, backed by rigorous scientific substantiation, creates a strong value proposition. Leveraging agile R&D to quickly develop bespoke formulations for emerging dietary trends serves as a key go-to-market angle.
For Investors and Strategic Acquirers: Large food and animal nutrition conglomerates are the most active acquirers in this space, seeking to deepen their ingredient portfolios. The market demonstrates long-term viability driven by essential micronutrient demand and health-conscious consumer trends. Acquisition targets include specialized formulators with strong R&D in bioavailability and custom premix solutions for high-growth segments. Consolidation of microencapsulation technology expertise acts as a key signal to watch for future market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach into plant-based and personalized nutrition categories, reducing reliance on mature segments. |
| R&D Investment | Enhances bioavailability and stability of sensitive micronutrients, meeting evolving functional food requirements. |
| Strategic Partnerships | Secures access to distribution channels and co-develops specialized solutions with key industry players. |
| Custom Formulation Development | Addresses demand for tailored micronutrient blends in sports nutrition and dietary supplements. |
| Geographic Expansion | Captures growth in intensive farming operations across China and fortification mandates in India. |
Research Approach
Bottom-up animal feed application modeling reconciled against top-down vitamin and mineral premix supply-side tracking forms the analytical core. This approach combines primary interviews with R&D directors, procurement leads, and regulatory affairs specialists across key regions. Secondary validation draws from EFSA reports, FDA filings, GB standards, and relevant trade association publications. Triangulation across these diverse data points ensures robust market sizing and segmentation.
An input-output matrix frames the forecast framework, projecting market trajectories across the analysis window. This model segments by product type, application, end-user, form, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) derive from historical trends and projected demand drivers for each segment. Micronutrient stability data and anticipated fortification mandate schedules serve as critical forecast inputs.
Raw material price volatility, diverging regulatory shifts, and unforeseen technological breakthroughs are the dominant revision risks. Forecasts reflect assumptions documented within the study. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pet Food Ingredients Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Calendula Oil Market
Ingredients
Clean Label Flour Market
Ingredients
Psyllium Products Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Beverage Ingredients Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Chickpea Fiber Market
Ingredients
Seaweed Derivatives Market
Ingredients
Sunflower Lecithin Market
Ingredients
Bean Flour Market
Ingredients
Global Edible Oil Market
Ingredients
Soy Hydrolysates Market
Ingredients
Banana Essence Market