
 Global Edible Oil Market | 2026-2036
Global Edible Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Edible Oil Market Analysis
The EU Deforestation Regulation is shifting compliance burdens onto upstream suppliers across tropical origin countries. Cargill, Incorporated leverages its integrated crush and refining footprint to pre-certify supply chains ahead of enforcement deadlines. Wilmar International Limited dominates Southeast Asian palm oil origination, while Bunge Limited anchors South American soybean oil exports through its riverine logistics network.
Edible oil comprises triglycerides extracted from oilseeds, fruits, or nuts through mechanical pressing or solvent extraction, refined to achieve specific free fatty acid levels, color indices, and smoke points for human consumption. Palm oil leads global trade volumes due to its superior yield per hectare and versatile fractionation profile, while olive oil occupies the premium tier with its monounsaturated fat composition and protected designation of origin frameworks. Organic grade oils are expanding fastest within retail channels as certification premiums attract health-conscious buyers.
The FDA governs allowable trans-fat declarations and processing aid residues in US-bound shipments, while EFSA sets maximum contaminant thresholds for 3-MCPD esters and glycidyl esters in refined oils. Indonesia's national palm oil sustainability certification program operates alongside Malaysia's MSPO standard, creating a dual-track compliance environment for exporters. Stakeholders must monitor divergence between EU deforestation traceability mandates and emerging Asian domestic sustainability schemes to avoid stranded inventory positions.
Market Dynamics
The EU Deforestation Regulation is forcing a wholesale reconfiguration of sourcing architectures across tropical supply basins, with traceability mandates now filtering backward through crushing and refining networks.
Growth Catalysts
- Palm oil fractionation advances:Dual-fractionation technologies enable tailored olein and stearin outputs for confectionery and bakery applications without trans-fat formation.
- Indonesia's B35 biodiesel mandate:Domestic absorption of crude palm oil is accelerating, tightening exportable surplus and supporting refined product premiums.
- REACH compliance automation:Digital chain-of-custody platforms are reducing certification latency for EU-bound shipments from Malaysian MSPO-certified estates.
Market Restraints
- Input cost volatility:Natural gas and methanol price swings directly compress margins on hydrogenation and interesterification processes.
- Supply concentration risk:Indonesian and Malaysian palm oil output dominates tradeable volumes, exposing buyers to El Niño-driven yield shocks.
- Regulatory friction:Divergence between EU deforestation traceability deadlines and Indonesia's ISPO timeline creates dual-certification burdens for exporters.
Strategic Opportunities
- Underpenetrated geography:West African palm oil processing remains below capacity, offering first-mover advantages in Côte d'Ivoire and Ghana for integrated crush-refine operations.
- Regulatory tailwind:The EU Green Deal's farm-to-fork strategy is mandating saturated fat reduction, accelerating demand for high-oleic sunflower and algae oil formulations.
- Channel innovation:Direct-to-foodservice bulk dispensing systems are bypassing traditional packaged goods distribution in Southeast Asian institutional catering.
Industry Challenges
- Certification timeline compression:MSPO and RSPO audit backlogs are extending lead times for sustainability claims by four to six months.
- Capex intensity:Refinery upgrades to meet EFSA's tightened 3-MCPD ester thresholds require solvent extraction system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Edible Oil Market |
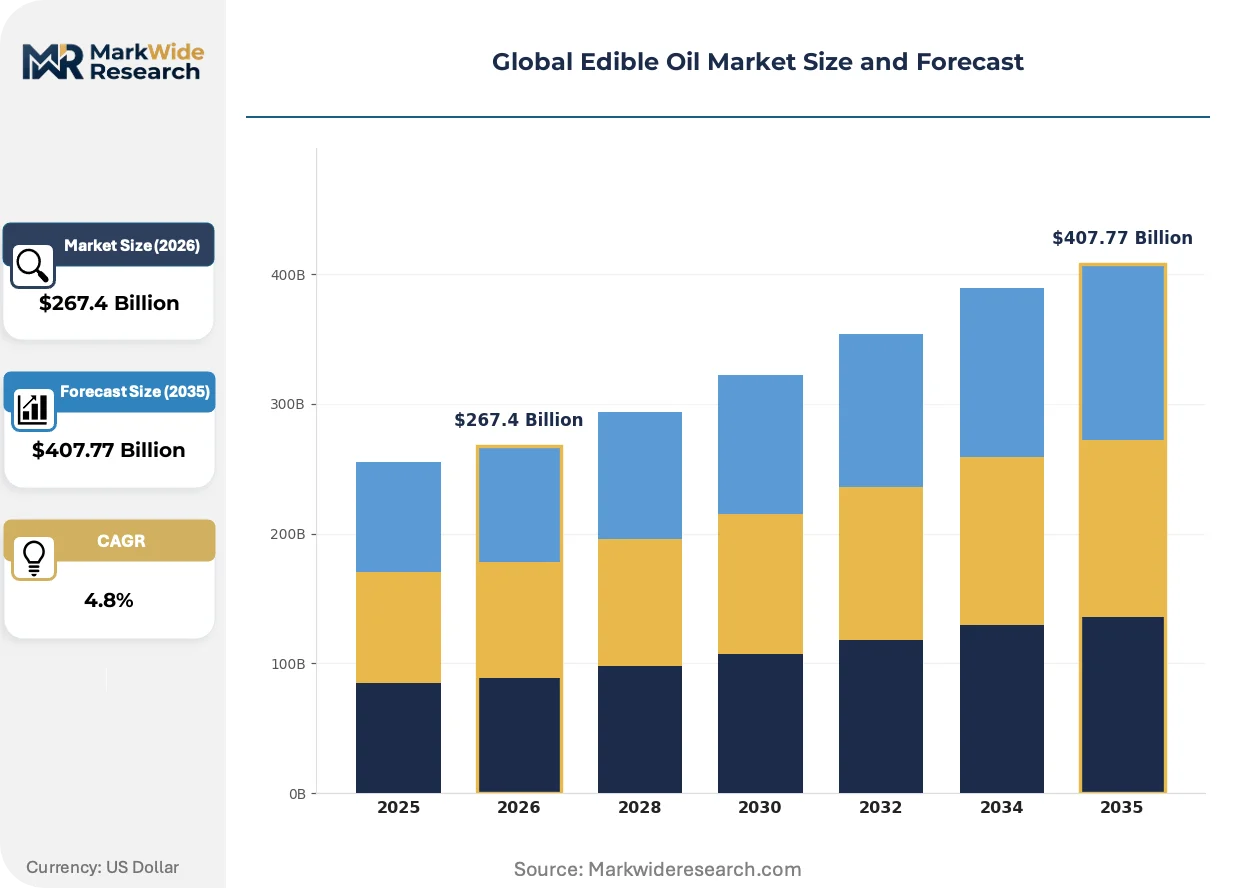
| Market Size in 2026 | $267.4 Billion |
| Market Size in 2035 | $407.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Sunflower Oil, Palm Oil, Soybean Oil End User: Households, Food Service, Food Processing, Retail Packaging Type: Bottles, Cans, Tetra Packs, Bulk Containers Grade: Refined, Crude, Organic, Pomace |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Bunge Limited, Wilmar International Limited, ADM, Olam International, Louis Dreyfus Company, Associated British Foods plc, COFCO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Edible Oil Market Emerging Trajectories
Digital traceability infrastructure and novel oilseed development are compressing traditional supply hierarchies while regulatory chemistry mandates reshape refining economics.
Precision fermentation-derived oils are expanding into cocoa butter equivalent and palm oil substitute applications. Specialty fats manufacturers in Europe and North America are scaling bioreactor capacity to secure supply for chocolate and personal care formulations. This platform is expanding into mid-market bakery shortenings as cost curves intersect with hydrogenated oil price floors.
EFSA's 2023 revision of glycidyl ester maximum levels is forcing refiners to adopt dual-deodorization or enzymatic degumming retrofits. The regulation tightens allowable limits in infant formula and follow-on products, redirecting premium crude palm oil volumes toward pharmaceutical-grade processing lines. Malaysian refiners are responding with accelerated acid-catalyzed conversion technology deployment.
Food manufacturers are consolidating supplier panels around vertically integrated crush-to-refine operators capable of delivering ISCC-certified mass balance documentation. This procurement consolidation is displacing spot-market traders from premium tender processes. The shift is most visible in Northern European confectionery and margarine production, where sustainability scorecard weightings now exceed price in vendor selection algorithms.
Global Edible Oil Market Segmentation
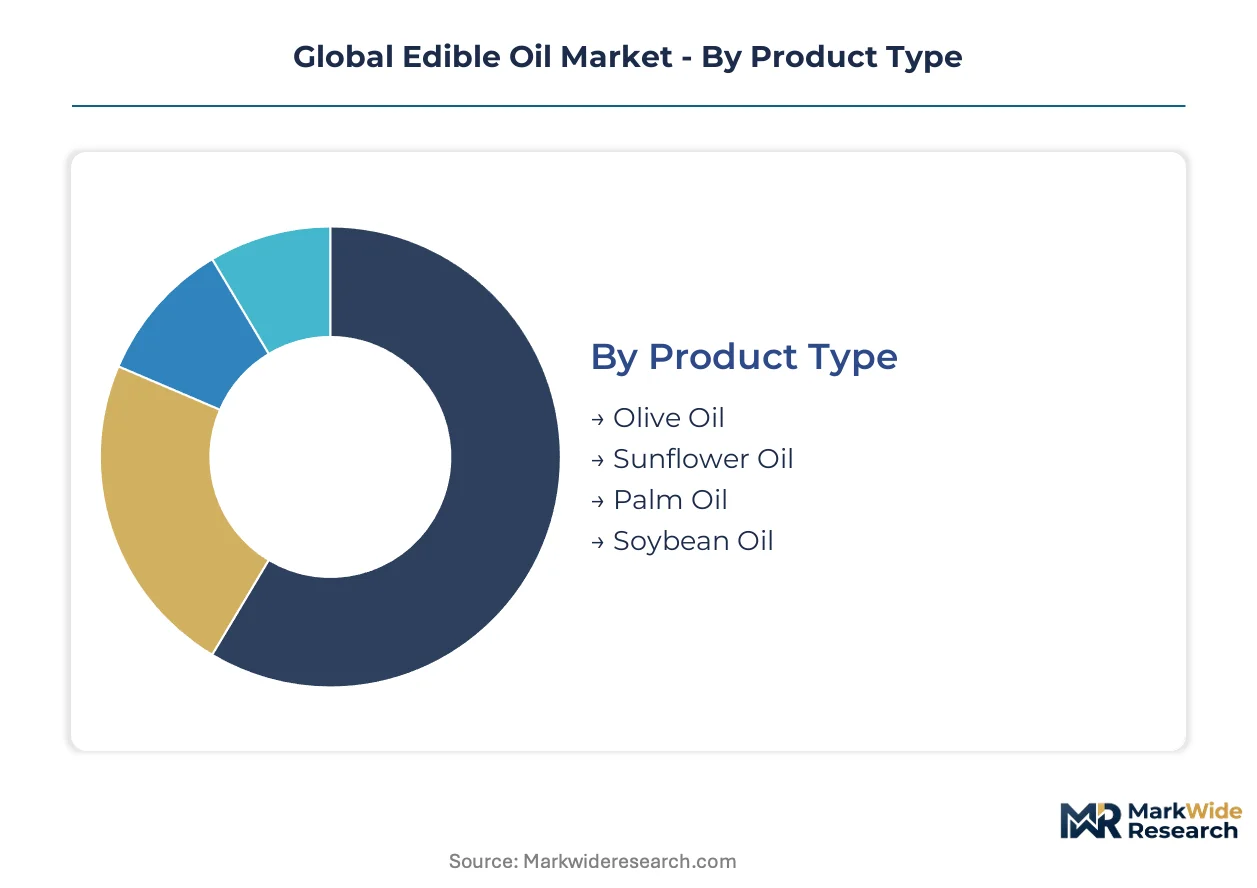
Edible oil purchasing patterns diverge sharply across consumer, institutional, and industrial channels, with packaging formats and certification grades commanding distinct price premiums. Buyers select grades and delivery mechanisms based on smoke point requirements, shelf stability needs, and traceability mandates rather than commodity pricing alone.
Product Type:
Yield per hectare and fractionation flexibility separate commercial buyers from those prioritizing fatty acid profiles for health claims.
- Palm Oil:Superior oil yield per hectare enables cost leadership in frying and confectionery applications. Indonesian and Malaysian refineries now absorb larger domestic volumes under biodiesel mandates, tightening exportable surplus. Fractionation into olein and stearin streams serves bakery and chocolate manufacturing without hydrogenation.
- Soybean Oil:High-oleic variants are displacing partially hydrogenated oils in North American food processing as trans-fat regulations tighten. Crushing capacity concentrates in Argentina, Brazil, and the US Midwest, with riverine logistics determining export competitiveness.
- Olive Oil:Protected designation of origin frameworks in Spain, Italy, and Greece sustain premium pricing for extra-virgin grades. Monounsaturated fat content drives Mediterranean diet positioning in retail channels.
- Sunflower Oil:Neutral flavor profile and high smoke point serve Central and Eastern European frying traditions. Ukrainian supply disruptions have redirected sourcing toward Russian and Argentine origins.
Palm oil leads volumes today; high-oleic soybean oil is gaining share fastest.
End User:
Volume concentration and specification stringency create four distinct procurement behaviors with diverging sustainability documentation requirements.
- Food Processing:Bulk purchasing with ISCC mass balance certification dominates confectionery, margarine, and snack manufacturing in Northern Europe. EFSA contaminant thresholds for 3-MCPD esters force refinery selection based on processing technology rather than price alone.
- Food Service:Institutional catering in Southeast Asia is adopting direct-to-kitchen bulk dispensing systems, bypassing traditional packaged goods distribution. Fry life and oxidative stability determine purchasing decisions for high-turnover frying operations.
- Households:Retail bottle sizing and organic certification premiums shape purchasing in North American and European supermarkets. Private label penetration is highest in standard-grade olive and canola oils.
- Retail:Branded positioning around origin stories and cold-press extraction commands shelf space in premium urban markets. Malaysian MSPO and Indonesian ISPO certifications are appearing on labels for palm-containing products.
Food processing absorbs the largest tonnage; food service is expanding most quickly.
Packaging Type:
Logistics economics and shelf-life extension technologies determine format selection across ambient and temperature-controlled supply chains.
- Bulk Containers:Flexitanks and ISO tank containers serve intercontinental refined oil movements from Malaysian Port Klang and Indonesian Belawan to European and Indian destinations. Direct discharge into food manufacturing lines eliminates intermediate handling costs.
- Bottles:PET and glass formats dominate retail olive oil and premium vegetable oil segments in Italy, Spain, and California. Light protection and pour control features differentiate premium offerings.
- Cans:Tinplate and aluminum formats preserve oxidative stability for high-oleic sunflower and peanut oils in Middle Eastern and North African markets. Pilferage resistance favors institutional catering procurement.
- Tetra Packs:Aseptic filling extends shelf life for specialty oils in Japanese and South Korean convenience retail. Carton packaging supports sustainability marketing claims in Scandinavian markets.
Bulk containers move the greatest volume; Tetra Packs are climbing the fastest.
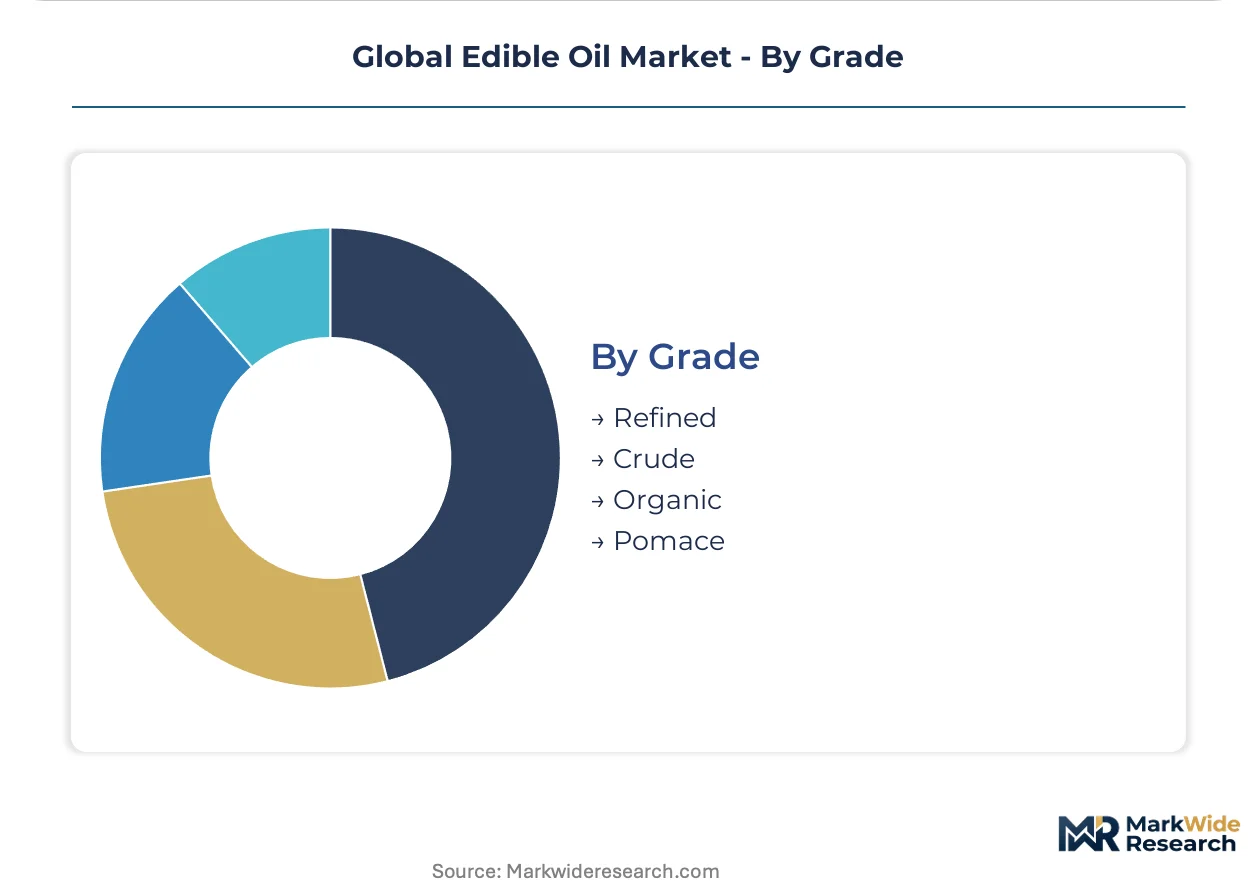
Grade:
Processing intensity and certification status stratify pricing across pharmaceutical, food, and feed applications.
- Refined:Bleaching and deodorization achieve specific free fatty acid levels and color indices for frying stability. EFSA glycidyl ester maximums are forcing dual-deodorization retrofits in European and Malaysian refineries.
- Organic:Third-party certification premiums attract health-conscious buyers in German, French, and US coastal markets. Supply constraints in organic soybean and sunflower origins limit volume expansion.
- Crude:Unprocessed oils enter biodiesel feedstock channels or refining operations with captive degumming capacity. Indonesian B35 mandate absorption is redirecting crude palm oil away from export markets.
- Pomace:Solvent-extracted olive residue oils serve soap manufacturing and lower-tier food applications in Mediterranean markets. Regulatory restrictions on pomace oil labeling vary across EU member states.
Refined grade dominates current volumes; organic certification is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edible oil processing originated in the Mediterranean basin, where olive pressing established the first commercial oilseed value chains. Industrial-scale palm oil extraction later emerged in colonial Southeast Asia, while soybean crushing scaled across the American Midwest during the twentieth century.
Indonesia
Domestic biodiesel absorption under the B35 mandate is tightening exportable crude palm oil volumes. The national ISPO certification program operates alongside private sustainability schemes, creating dual-track compliance for exporters. Refining clusters in North Sumatra and Riau provinces are expanding fractionation capacity to serve Indian and Chinese food manufacturing demand.
Malaysia
MSPO-certified estates are deploying digital chain-of-custody platforms to reduce EU-bound certification latency. The Port Klang refining corridor dominates intercontinental bulk shipments through flexitank and ISO tank container movements. EFSA's tightened glycidyl ester thresholds are accelerating acid-catalyzed conversion technology adoption across Selangor processing facilities.
United States
High-oleic soybean oil variants are displacing partially hydrogenated oils as FDA trans-fat regulations tighten across food processing. Crushing capacity concentrates in the Midwest riverine network, with barge logistics determining export competitiveness to Mexican and Canadian destinations. Iowa and Illinois refineries are retrofitting interesterification systems to meet bakery and confectionery formulation requirements.
Brazil
Riverine logistics through the Paraná-Paraguay waterway anchor South American soybean oil exports to Asian and European destinations. The Matopiba frontier region is expanding planted area for oilseed production. Crushing and refining investments in Mato Grosso and Goiás are integrating with port terminals at Santos and Paranaguá to reduce inland freight differentials.
India
Palm oil imports from Southeast Asian origins dominate food service and household consumption channels. FSSAI labeling mandates and maximum contaminant thresholds are reshaping refinery procurement criteria. Processing clusters in Gujarat and Maharashtra are expanding solvent extraction capacity to handle rising soybean and sunflower oil demand from domestic oilseed production.
Global Edible Oil Market Vendor Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive crush-to-refine footprints. Consolidation around multinational traders with riverine and port logistics control has displaced spot-market intermediaries from premium tender processes. Three archetypes dominate: vertically integrated plantation-refiners, merchant traders with origination networks, and regional processors serving domestic biodiesel and food manufacturing. Capacity expansion and sustainability certification pre-positioning represent the dominant competitive moves as EU deforestation traceability deadlines approach.
Among integrated plantation-refiners, Wilmar International Limited and Bunge Limited exemplify the archetype of traders with crushing and refining assets anchored in origin markets. Cargill, Incorporated occupies a position representing the merchant trader model with pre-certification supply chain capabilities. These entities sit within a tier where ISCC mass balance documentation and digital traceability infrastructure determine vendor selection outcomes in Northern European procurement.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Wilmar International Limited |
| ADM |
| Olam International |
| Louis Dreyfus Company |
| Associated British Foods plc |
| COFCO Group |
| Others |
Supply Flow & Price Mechanics
Natural gas and methanol input costs cascade through hydrogenation and interesterification processes into refined product premiums, compressing margins at Indonesian and Malaysian refineries while supporting price elevation in EU-bound certified grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies edible oil markets by certification grade and volume commitment. Organic and ISCC-certified mass balance documentation commands substantial premiums over conventional refined grades, while spot-market crude palm oil trades at compressed levels due to Indonesian B35 biodiesel absorption. Cost compression in standard refined tiers is intensifying because of El Niño-driven yield volatility and energy input inflation. Food processing buyers in Northern Europe demonstrate lowest price sensitivity, prioritizing EFSA contaminant compliance over unit economics, whereas Southeast Asian food service operators optimize strictly on fry life per dollar.
Supply Chain Analysis
Regional distribution centers at Port Klang and Belawan anchor hub-and-spoke patterns for intercontinental bulk movements. Supply concentrates in Indonesia, Malaysia, and Brazil, with Indonesian and Malaysian palm oil output dominating tradeable volumes. Raw material dependencies rest on crude palm oil fruit bunches, soybean seeds, and high-oleic sunflower seeds. Single-source vulnerability from El Niño-driven yield shocks in Southeast Asian estates poses structural risk. Distribution runs through flexitank and ISO tank container networks direct to food manufacturing lines, bypassing intermediate handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium certification tiers and integrated crush-refine operations as sustainability premiums widen and energy-efficient processing technologies reduce unit costs.
For Market Incumbents: Hedge against regulatory divergence by dual-certifying supply chains under both EU Deforestation Regulation traceability mandates and Indonesian ISPO timelines. Prioritize backward integration into West African palm oil processing in Côte d'Ivoire and Ghana to diversify origin exposure. Accelerate acid-catalyzed conversion technology deployment to meet EFSA glycidyl ester thresholds ahead of competitor retrofits. For New Entrants and Emerging Players: Launch via direct-to-foodservice bulk dispensing systems in Southeast Asian institutional catering, bypassing entrenched packaged goods distribution networks. Target underpenetrated West African crush-refine operations where integrated capacity remains below demand. Exploit certification audit backlogs by offering digital chain-of-custody platforms as a service to MSPO and RSPO estates facing four-to-six-month lead time extensions. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional refiners with captive degumming capacity because sustainability certification pre-positioning creates scarcity value ahead of EU enforcement deadlines. Long-term viability hinges on positioning within ISCC-certified mass balance documentation networks serving Northern European confectionery and margarine procurement. Watch for inflection when EFSA contaminant threshold tightening redirects premium crude palm oil volumes toward pharmaceutical-grade processing lines.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Supply Chain Investment | Pre-positions inventory for EU Deforestation Regulation enforcement without stranding ISPO-compliant volumes. |
| West African Crush-Refine Capacity Buildout | Captures first-mover advantages in Côte d'Ivoire and Ghana as Southeast Asian exportable surplus tightens. |
| Digital Traceability Platform Deployment | Reduces MSPO and RSPO certification latency for EU-bound shipments from Malaysian estates. |
| Acid-Catalyzed Conversion Technology Retrofit | Enables EFSA glycidyl ester compliance in infant formula and pharmaceutical-grade processing lines. |
| Direct-to-Foodservice Distribution Expansion | Bypasses traditional packaged goods channels in Southeast Asian institutional catering markets. |
Methodological Framework
Multiple input streams — structured interviews with refinery operations managers and sustainability certification officers, trade flow analysis from customs and port authority records, and regulatory filing review across FDA, EFSA, and FSSAI jurisdictions — were reconciled through bottom-up volume modeling and top-down market sizing validation. Primary fieldwork engaged crushing facility technical directors, procurement leads at Northern European confectionery manufacturers, and bulk logistics coordinators at Port Klang and Santos terminals. Secondary sources incorporated FAO oilseed production statistics, EFSA contaminant threshold documentation, and SEC filings from listed agribusiness conglomerates.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end user channel, packaging format, certification grade, and regional production hub. CAGRs were derived from fitted growth curves applied to baseline consumption patterns, with specific adjustments for Indonesian B35 mandate absorption rates and EU Green Deal farm-to-fork saturated fat reduction targets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained El Niño conditions or accelerated EU deforestation enforcement timelines. Outputs reflect documented assumptions regarding biodiesel policy continuity and refinery technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Horehound Extract Market
Ingredients
Europe Pea Starch Market
Ingredients
North America Feed Yeast Market
Ingredients
Lupine Peptides Market
Ingredients
Global Pulse Flours Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Edible Oils and Fats Market
Ingredients
Fruit Concentrate Market
Ingredients
Bouillon Market
Ingredients
Durian Powder Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Halal Ingredients Market
Ingredients
Almond Flour Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Grape Skin Extract Market